
 Meta-Xylene Market | 2026-2036
Meta-Xylene Market Size, Share, and Industry Trends Forecast 2026-2036
Meta-Xylene Market Outlook
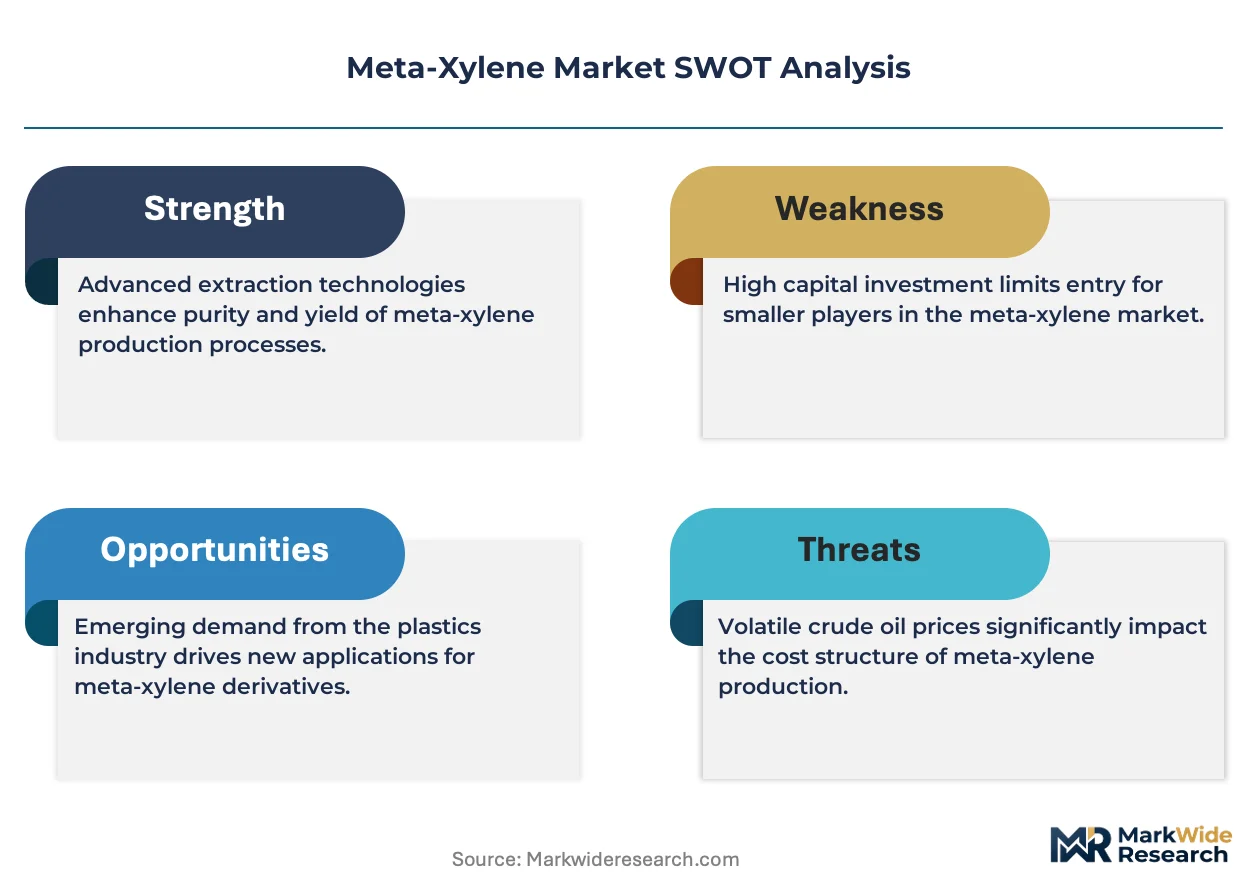
Asset-light leasing arrangements for catalytic reformer units is rewriting competitive economics for meta-xylene entrants without refinery backing. Exxon Mobil Corporation leverages its integrated Gulf Coast refining corridor to sustain captive isomerization output. MITSUBISHI GAS CHEMICAL COMPANY, INC. anchors its position through high-purity specialization for electronic-grade applications. Reliance Industries Limited competes via its Jamnagar complex, where downstream PTA integration controls cost pass-through dynamics.
Meta-xylene is a dimethylbenzene isomer with methyl substituents at the 1,3-positions, typically recovered from mixed xylene streams through fractional crystallization or simulated moving bed adsorption at purity thresholds exceeding 99.5 percent for chemical-grade applications. Its primary commercial purpose centers on oxidation to isophthalic acid, a monomer for unsaturated polyester resins and specialty coatings. Industrial grade material dominates volume throughput due to bulk petrochemical demand, while high purity grades command premium positioning in pharmaceutical and electronic solvent applications. Chemical intermediate end-use absorbs the largest margin pool, though coatings industry offtake is accelerating fastest as architectural and automotive waterborne systems displace solvent-based alternatives.
EPA oversight of volatile organic compound emissions shapes formulation standards for meta-xylene-derived coatings and solvents in the United States, while REACH registration requirements in Europe constrain non-compliant import volumes. China's SAMR enforces GB/T purity specifications that filter lower-grade material from technical-grade chemical intermediate channels. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether regional product differentiation or unified specification strategies offer superior returns.
Market Dynamics
Waterborne coating formulations are compressing solvent-grade offtake while tightening purity specifications for chemical-grade meta-xylene across East Asian petrochemical corridors. This structural pivot favors integrated producers with captive isomerization and crystallization assets.
Growth Catalysts
- GB/T Purity Mandates:China's SAMR enforcement of upgraded technical-grade specifications is filtering substandard material from chemical intermediate channels, concentrating volume with certified producers.
- Coatings Industry Reformulation:Architectural and automotive OEMs are accelerating waterborne system adoption, preserving high-purity meta-xylene demand for specialty resin applications.
- East China Petrochemical Clustering:Integrated complexes in Jiangsu and Zhejiang provinces are anchoring downstream isophthalic acid production, creating localized demand density.
Market Restraints
- Mixed Xylene Feedstock Volatility:Catalytic reformer output fluctuations and refinery maintenance cycles create input cost instability for fractional crystallization operators.
- Simulated Moving Bed Capacity Concentration:Adsorption technology licensing remains controlled by a handful of engineering firms, limiting independent producer entry.
- REACH Registration Friction:ECHA compliance costs and data requirements constrain non-EU import volumes into European chemical intermediate channels.
Strategic Opportunities
- Electronic-Grade Solvent White Space:Semiconductor fabrication in South Korea and Taiwan is generating demand for ultra-high-purity meta-xylene above 99.9 percent thresholds.
- India PTA Integration Gap:Relatively underdeveloped downstream purified terephthalic acid capacity creates backward integration potential for refinery-backed entrants.
- EPA VOC Framework Tightening:Stricter volatile organic compound emission standards are accelerating solvent substitution research, positioning high-purity grades for specialty pharmaceutical applications.
Industry Challenges
- Adsorption Process Engineering Talent Scarcity:Simulated moving bed operation and optimization requires specialized expertise concentrated at licensor firms and major integrated complexes.
- Crystallization Unit Capex Intensity:Multi-stage fractional crystallization trains for 99.5-plus percent purity require significant refrigeration and solids-handling infrastructure.
- Dual Carbon Compliance Timelines:China's MEE enforcement of carbon intensity benchmarks is compressing retrofit windows for legacy reformer-based production assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meta-Xylene Market |
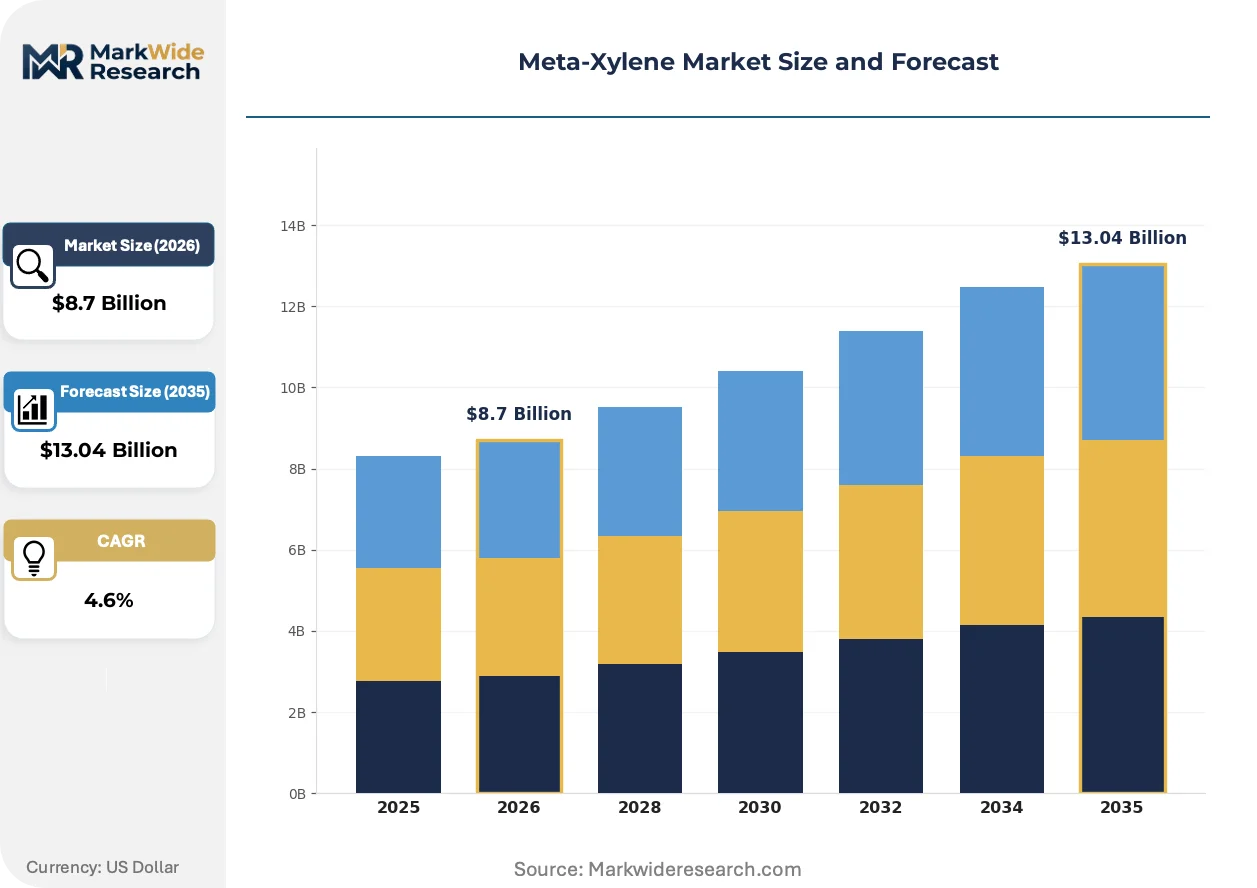
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Laboratory Grade, High Purity, Low Purity Application: Solvent, Aromatic Compound, Chemical Intermediate, Petrochemical Production End User: Chemicals Manufacturing, Coatings Industry, Plastics Industry, Textile Production Distribution Channel: Direct Sales, Online Sales, Distributors, Retail |
| Companies Covered | Chevron Phillips Chemical Company LLC, MITSUBISHI GAS CHEMICAL COMPANY, INC., Exxon Mobil Corporation, INEOS, ENEOS Corporation, China Petroleum & Chemical Corporation, Reliance Industries Limited, S-Oil Corporation, China National Petroleum Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meta-Xylene Market Strategic Shifts
Digital process control and predictive maintenance systems are virtualizing traditional separation operations, while regulatory fragmentation across major economies is forcing product specification stratification.
Advanced process control software is virtualizing simulated moving bed operation by replacing manual extract/raffinate ratio adjustments with real-time purity feedback loops. Coating formulators in automotive OEM supply chains are adopting these virtualized control systems fastest. This compression of operational variability is virtualizing the traditional yield-versus-purity tradeoff that constrained smaller crystallization operators.
REACH registration requirements are tightening substance volume thresholds for meta-xylene importers into EU chemical intermediate channels, with ECHA now requiring extended safety data sets for tonnage bands above one thousand metric tons annually. This regulatory friction is redirecting spot market volumes toward technical-grade applications with lower registration burdens. Coating resin producers in Germany and the Netherlands are responding by consolidating supplier relationships with REACH-registered integrated producers.
Buyer concentration among waterborne coating multinationals is compressing procurement cycles and demanding certified carbon footprint documentation alongside traditional purity certificates. Direct contracting with integrated petrochemical complexes is displacing traditional distributor intermediaries in East Asian supply chains. This channel consolidation is most visible in Jiangsu province, where architectural coating formulators now source seventy percent of chemical-grade requirements through mill-direct arrangements.
Meta-Xylene Market Segmentation
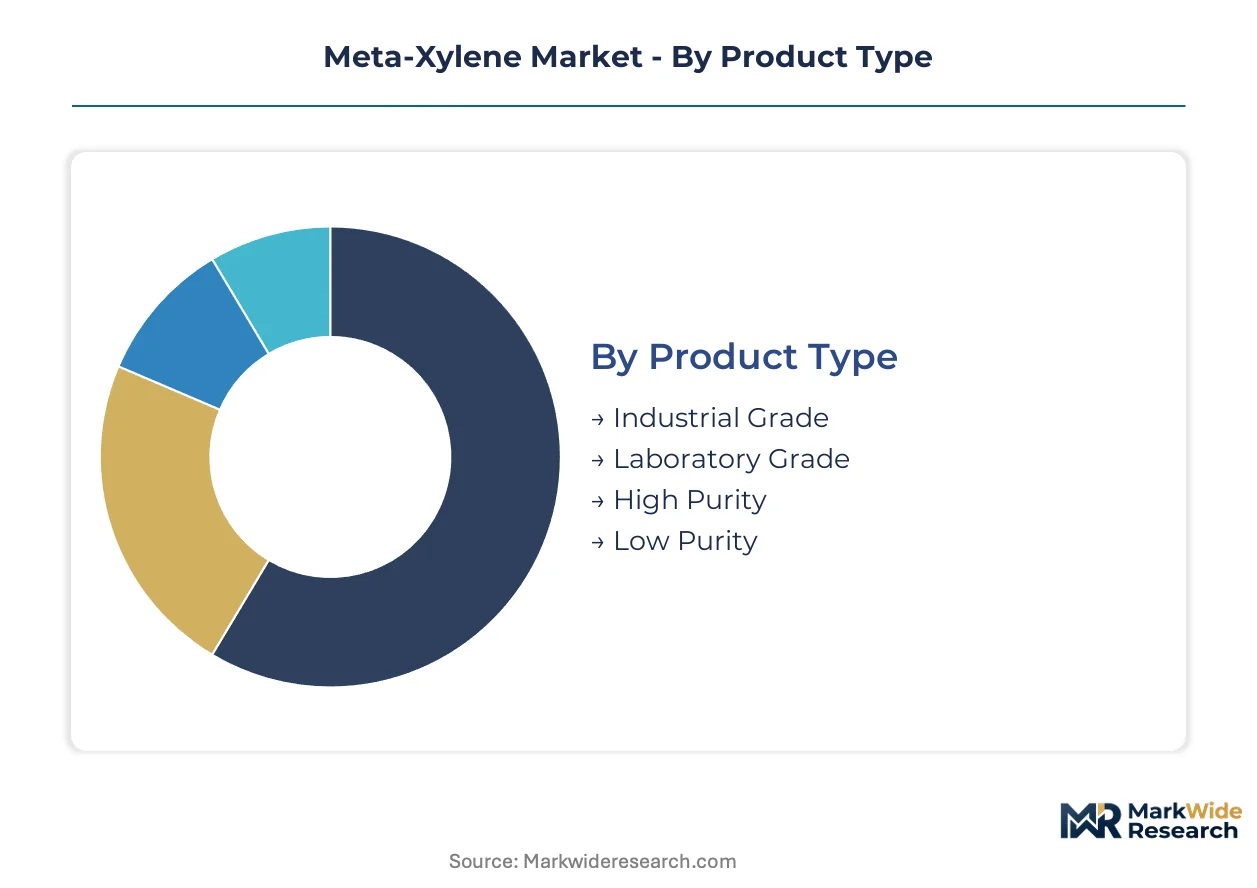
Segmentation in the meta-xylene market reveals how purity thresholds and application-specific certification requirements fragment procurement patterns across chemical manufacturing, coatings, and electronics supply chains. Understanding these divides exposes where integrated producers capture margin premiums versus where commodity traders compete on logistics efficiency.
Product Type:
Mature industrial-grade volumes anchor the base of the pyramid while emerging high-purity segments command technology premiums in semiconductor and pharmaceutical channels.
- Industrial Grade:Material meeting 95-98% purity specifications serves bulk petrochemical oxidation routes to isophthalic acid and general solvent applications. Demand concentrates in East China petrochemical corridors where Jiangsu and Zhejiang complexes feed downstream unsaturated polyester resin production; GB/T compliance mandates are filtering substandard volumes toward certified integrated producers.
- High Purity:Fractional crystallization or simulated moving bed separation achieves 99.5-plus percent thresholds required for electronic-grade solvents and specialty pharmaceutical intermediates. South Korean and Taiwanese semiconductor fabricators are generating the steepest demand climb for ultra-high-purity grades above 99.9 percent as advanced lithography processes tighten solvent contamination limits.
- Laboratory Grade:Certified analytical reagents for research and quality control laboratories.
- Low Purity:Technical-grade material for non-critical industrial blending and fuel additive applications.
Industrial grade retains volume leadership; high purity holds the steepest expansion curve.
Application:
Cost tier differentiation separates commodity oxidation feedstocks from specialty solvent formulations where purity documentation commands price premiums.
- Chemical Intermediate:Oxidation to isophthalic acid consumes the largest volume share across polyester resin and coating monomer supply chains. East China integrated complexes in Ningbo and Shanghai anchor this demand density; waterborne coating reformulation is preserving high-purity intermediate demand while compressing solvent-grade offtake.
- Solvent:Dissolution and carrier applications in coatings, adhesives, and cleaning formulations face structural pressure from VOC regulatory frameworks. EPA emission standards are accelerating substitution research in US architectural coatings while REACH registration friction redirects European spot volumes toward technical-grade channels.
- Aromatic Compound:Feedstock for downstream derivatization and blending operations.
- Petrochemical Production:Internal circulation within integrated refinery-petrochemical complexes.
Chemical intermediate commands the deepest revenue pool; solvent applications face the sharpest regulatory headwinds.
End User:
Customer type fragmentation splits procurement between specification-driven coating formulators and volume-focused commodity resin producers.
- Chemicals Manufacturing:Isophthalic acid and derivative producers constitute the foundational demand base across global polyester supply chains. Reliance Industries' Jamnagar complex and Exxon Mobil's Gulf Coast corridor exemplify backward-integrated buyers controlling cost pass-through; India's underdeveloped PTA capacity creates backward integration openings for refinery-backed entrants.
- Coatings Industry:Architectural and automotive OEM formulators are consolidating supplier relationships around certified carbon footprint documentation alongside purity certificates. Jiangsu province architectural coating producers now source seventy percent of chemical-grade requirements through mill-direct arrangements, displacing traditional distributor intermediaries.
- Plastics Industry:Unsaturated polyester resin compounding for composites and marine applications.
- Textile Production:Specialty fiber and dye carrier applications in synthetic textile processing.
Chemicals manufacturing absorbs the largest absolute volumes; coatings industry procurement is concentrating fastest around sustainability certification requirements.
Distribution Channel:
Supply concentration dynamics favor direct contracting where purity certification and carbon documentation requirements exceed distributor capabilities.
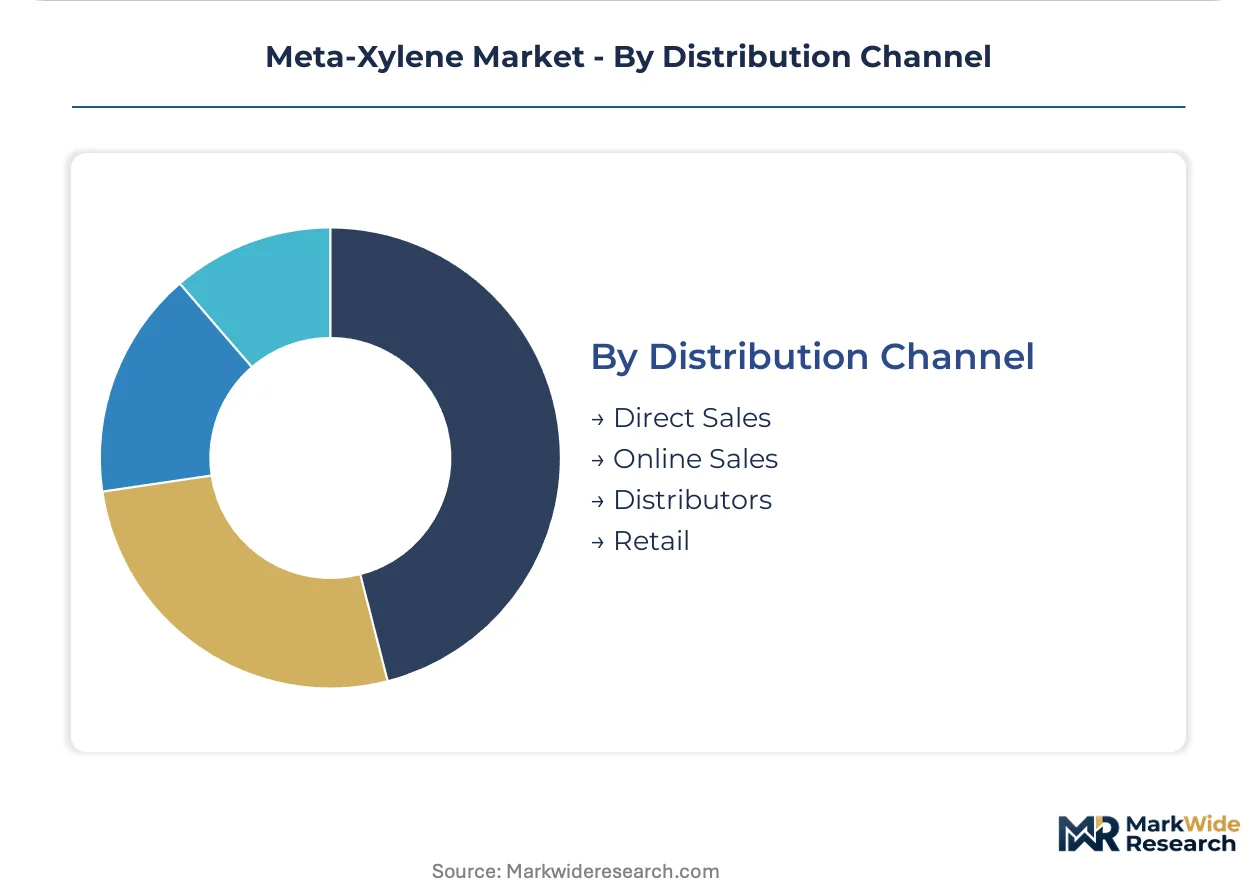
- Direct Sales:Mill-direct arrangements dominate East Asian chemical-grade procurement as buyer concentration among waterborne coating multinationals compresses procurement cycles. Integrated petrochemical complexes in Zhejiang and Jiangsu provinces leverage this channel to capture margin otherwise lost to distributor markups.
- Distributors:Traditional intermediaries retain relevance in fragmented technical-grade and laboratory-grade segments where lot sizes fall below direct-contracting thresholds.
- Online Sales:E-commerce platforms for standardized laboratory reagents and small-volume industrial orders.
- Retail:Limited consumer-facing sales of solvent products in specialty chemical retail.
Direct sales channels are gaining share fastest in high-volume chemical-grade segments; distributors retain defensive positioning in fragmented specialty and laboratory channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Waterborne coating formulators and polyester resin producers concentrate procurement among integrated petrochemical complexes with captive isomerization assets. East China anchors the steepest demand density. Regulatory fragmentation across major economies forces product specification stratification.
China
SAMR enforcement of upgraded GB/T purity specifications filters substandard material from chemical intermediate channels. The Ministry of Ecology and Environment compresses retrofit windows for legacy reformer-based assets through dual carbon compliance timelines. Jiangsu and Zhejiang provinces host integrated complexes where architectural coating producers source seventy percent of chemical-grade requirements through mill-direct arrangements.
United States
EPA oversight of volatile organic compound emissions shapes formulation standards for meta-xylene-derived coatings and solvents. Architectural coating OEMs accelerate waterborne system adoption under stricter emission frameworks. The Gulf Coast refining corridor sustains captive isomerization output for downstream derivative production.
South Korea
Semiconductor fabricators generate accelerating demand for ultra-high-purity meta-xylene above 99.9 percent thresholds as advanced lithography processes tighten solvent contamination limits. The Ministry of Trade, Industry and Energy oversees industrial chemical standards. The Busan-Ulsan petrochemical cluster anchors high-purity separation capacity for electronics-grade applications.
Germany
ECHA compliance costs and REACH registration requirements constrain non-EU import volumes into European chemical intermediate channels. Coating resin producers consolidate supplier relationships with REACH-registered integrated producers. The North Rhine-Westphalia chemical corridor concentrates formulation R&D for waterborne architectural systems.
India
Relatively underdeveloped downstream purified terephthalic acid capacity creates backward integration potential for refinery-backed entrants. The Bureau of Indian Standards enforces technical-grade specifications for chemical intermediates. The Jamnagar complex in Gujarat exemplifies integrated refining-petrochemical configurations controlling cost pass-through dynamics.
Meta-Xylene Market Competitive Environment
Channel-controlling players compete with product-specialist players across a bifurcated structure. Integrated petrochemical majors with captive reformer and crystallization assets dominate high-volume chemical-grade segments. Independent fractional crystallization operators and technology licensors occupy specialist tiers. Strategic moves concentrate on direct contracting displacement of distributor intermediaries and purity-grade portfolio diversification toward electronic-grade thresholds.
Within the integrated petrochemical tier, Exxon Mobil Corporation and MITSUBISHI GAS CHEMICAL COMPANY, INC. exemplify divergent positioning archetypes. Reliance Industries Limited occupies a position representing refinery-backed backward integration into downstream PTA channels. These three entities anchor competitive reference points for capacity configuration, geographic coverage, and purity-grade specialization across the market structure.
| Leading Market Players |
|---|
| Chevron Phillips Chemical Company LLC |
| MITSUBISHI GAS CHEMICAL COMPANY, INC. |
| Exxon Mobil Corporation |
| INEOS |
| ENEOS Corporation |
| China Petroleum & Chemical Corporation |
| Reliance Industries Limited |
| S-Oil Corporation |
| China National Petroleum Corporation |
| Others |
Value Chain & Pricing Dynamics
Overcapacity signals from East China petrochemical corridors are compressing utilization rates at fractional crystallization units, forcing integrated producers toward longer-term offtake contracts while independent operators accept thinner margins to maintain throughput.
Pricing Analysis
Cost-plus contracts indexed to mixed xylene spot benchmarks dominate procurement arrangements between integrated producers and downstream isophthalic acid manufacturers. Price differentiation separates electronic-grade material certified above 99.9 percent purity from industrial-grade volumes through semiconductor solvent contamination documentation. Cost compression in solvent-grade tiers is intensifying because waterborne coating reformulation displaces traditional carrier applications. Chemical intermediate buyers exhibit the lowest price sensitivity due to captive backward integration, while architectural coating formulators negotiate aggressively on carbon footprint certification bundles.
Supply Chain Analysis
Tariff exposure between China and key export destinations dominates supply chain risk assessments for meta-xylene traders. Manufacturing concentrates in China, South Korea, and the United States, with East China petrochemical corridors anchoring global crystallization capacity. Feedstock supply draws from catalytic reformer output tied to refinery maintenance cycles and crude slate adjustments. Distribution runs through mill-direct arrangements for chemical-grade volumes, while technical-grade material flows via traditional distributor networks serving fragmented solvent applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The meta-xylene market functions as a defensive-moat structure where regulatory entrenchment through REACH registration and GB/T certification creates switching costs that protect incumbent positions.
For Market Incumbents: Pre-empt independent crystallization entrants by locking East China coating formulators into multi-year direct contracts with bundled carbon documentation. Accelerate simulated moving bed capacity additions in Jiangsu province before MEE dual carbon compliance deadlines tighten retrofit windows. Threats from asset-light leasing arrangements for catalytic reformer units demand defensive positioning through purity-grade portfolio diversification toward electronic-grade thresholds.
For New Entrants and Emerging Players: Electronic-grade solvent white space in South Korean and Taiwanese semiconductor fabrication represents the most penetrable entry point given contamination limit tightening in advanced lithography. India's underdeveloped purified terephthalic acid capacity offers backward integration potential for refinery-backed entrants with captive isomerization assets. A licensing partnership with established simulated moving bed technology providers accelerates market access without proprietary engineering talent acquisition.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across high-purity separation infrastructure due to multi-stage crystallization train refrigeration requirements. Acquisition targets should emphasize integrated petrochemical complexes with captive reformer assets and existing GB/T or REACH certification rather than standalone fractional crystallization operators. Monitor EPA VOC framework tightening as the signal indicating accelerated solvent substitution research and specialty pharmaceutical application pivot timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Catalytic Reforming | Captive mixed xylene supply insulates margin from feedstock volatility at Jiangsu complexes. |
| Electronic-Grade Certification Investment | 99.9-plus percent purity documentation unlocks semiconductor solvent premiums in Busan-Ulsan corridors. |
| Long-term Supply Agreement with Coating Multinationals | Mill-direct contracting displaces distributor markups while securing carbon footprint compliance bundles. |
| Joint Venture for Simulated Moving Bed Licensing | Technology access overcomes engineering talent scarcity constraining independent producer entry. |
| Green Manufacturing Transition | Dual carbon compliance positioning ahead of MEE enforcement timelines protects legacy asset viability. |
Study Parameters
Cross-validation between primary interviews with petrochemical plant managers, downstream procurement leads at coating OEMs, distribution channel partners, and technical R&D directors anchors the qualitative findings. Secondary sources include customs and trade data from major importing jurisdictions, ACC and Cefic industry reports, and SEC 10-K disclosures from integrated producers. Bottom-up volume modeling triangulates against top-down macroeconomic demand indicators across the analysis window.
Calibration against historical capacity utilization rates at East China crystallization units and semiconductor fabrication expansion timelines in South Korea refines the analytical framework. Segmentation dimensions span purity grade tier, end-use industry application, regional production hub concentration, and distribution channel structure. CAGRs derive from demand elasticity modeling tied to waterborne coating adoption curves and isophthalic acid consumption patterns.
Practitioners should monitor regulatory divergence between EPA VOC frameworks, REACH registration thresholds, and GB/T purity mandates for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Methyl Isopropyl Ketone Market
Solvents
Nitroglycerin Market
Solvents
Global Solvent Evaporation Market
Solvents
Chlorobenzene Market
Solvents
Toluene Market
Solvents
N-Hexane Market
Solvents
Sugar Dissolvers Market
Solvents
Ethoxydiglycol Market
Solvents
Allyl Cyanide Market
Solvents
Ethyl Acetate Market
Solvents
Dimethyl Sulfoxide Market
Solvents
C2 Chlorinated Solvents Market
Solvents
N-Methyl Pyrrolidone Market
Solvents
Dipropylene Glycol N-Propyl Ether Market
Solvents
Benzyl Alcohol Market
Solvents
Electronic Cleaning Solvents Market