
 Digital Publishing Platforms Market | 2026-2036
Digital Publishing Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Publishing Platforms Market Analysis
ISO 27001 certification is bifurcating the competitive landscape as enterprise buyers demand audited data security before procurement. Amazon.com, Inc. dominates self-service distribution through its captive marketplace and print-on-demand infrastructure. Alphabet Inc. leverages its advertising technology stack to sustain margin advantages in programmatic content monetization. IngramSpark anchors professional publishing through its global print and digital fulfillment network.
Digital publishing platforms are software systems that enable the creation, distribution, monetization, and analytics of content across electronic formats, typically operating through cloud-native architectures with API-driven content management and DRM-protected file delivery. Their primary commercial purpose is to disintermediate traditional print supply chains while capturing reader engagement data for targeted monetization. The subscription service type captures the most predictable revenue pools as publishers seek recurring income insulated from advertising volatility. Cloud-based technology leads deployment preferences among mid-market publishers replacing on-premise legacy systems. The freemium service type represents the fastest expansion vector as platform vendors use limited free tiers to convert independent authors into paid professional accounts.
The EU Digital Services Act and GDPR impose content accountability and data processing standards that gate platform operations across European markets, while the FDA regulates health-related digital publications in the United States through its oversight of medical device software and promotional materials. The FCC's net neutrality framework shapes bandwidth economics for streaming-rich publishing formats. Stakeholders must monitor emerging AI-generated content disclosure mandates from multiple regulators as synthetic text detection becomes a procurement criterion for institutional buyers.
Market Dynamics
ISO 27001 certification is bifurcating vendor viability as enterprise procurement teams mandate audited security frameworks before contract execution, forcing mid-tier platforms to absorb compliance costs or exit contested accounts.
Growth Catalysts
- Educational Platform Adoption:Universities and K-12 districts are consolidating learning management systems with integrated publishing tools, creating institutional demand for cloud-native content distribution.
- GDPR Enforcement:The EU's data processing standards are compelling publishers to adopt compliant platforms, expanding addressable market for vendors with European data residency capabilities.
- Print-to-Digital Migration:Magazine and newspaper publishers are retiring legacy composition systems, triggering replacement cycles for API-driven content management infrastructure.
Market Restraints
- Cloud Infrastructure Concentration:AWS, Microsoft Azure, and Google Cloud dominate hosting costs, exposing platform operators to bandwidth pricing volatility and egress fee compression.
- DRM Licensing Friction:Adobe Content Server and proprietary encryption schemes impose per-title fees that erode margins for low-volume independent publishers.
- AI-Generated Content Detection:Emerging disclosure mandates from multiple regulators are forcing platforms to invest in synthetic text identification tools before standards crystallize.
Strategic Opportunities
- Indian Language Publishing:India's vernacular content creators remain underserved by English-centric platforms, creating whitespace for localized interfaces and payment integration.
- Healthcare Content Monetization:FDA-regulated medical device companies require compliant publication channels for promotional materials, opening specialized verticals.
- Programmatic Advertising Convergence:Integration of real-time bidding protocols with content management systems enables publishers to capture advertising revenue without third-party intermediaries.
Industry Challenges
- Technical Debt Integration:Publishers maintaining decades-old XML workflows face costly data migration when adopting modern headless content architectures.
- Cross-Border Tax Compliance:Platform operators must navigate VAT obligations across EU member states, US state sales tax nexus rules, and India's GST regime simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Publishing Platforms Market |
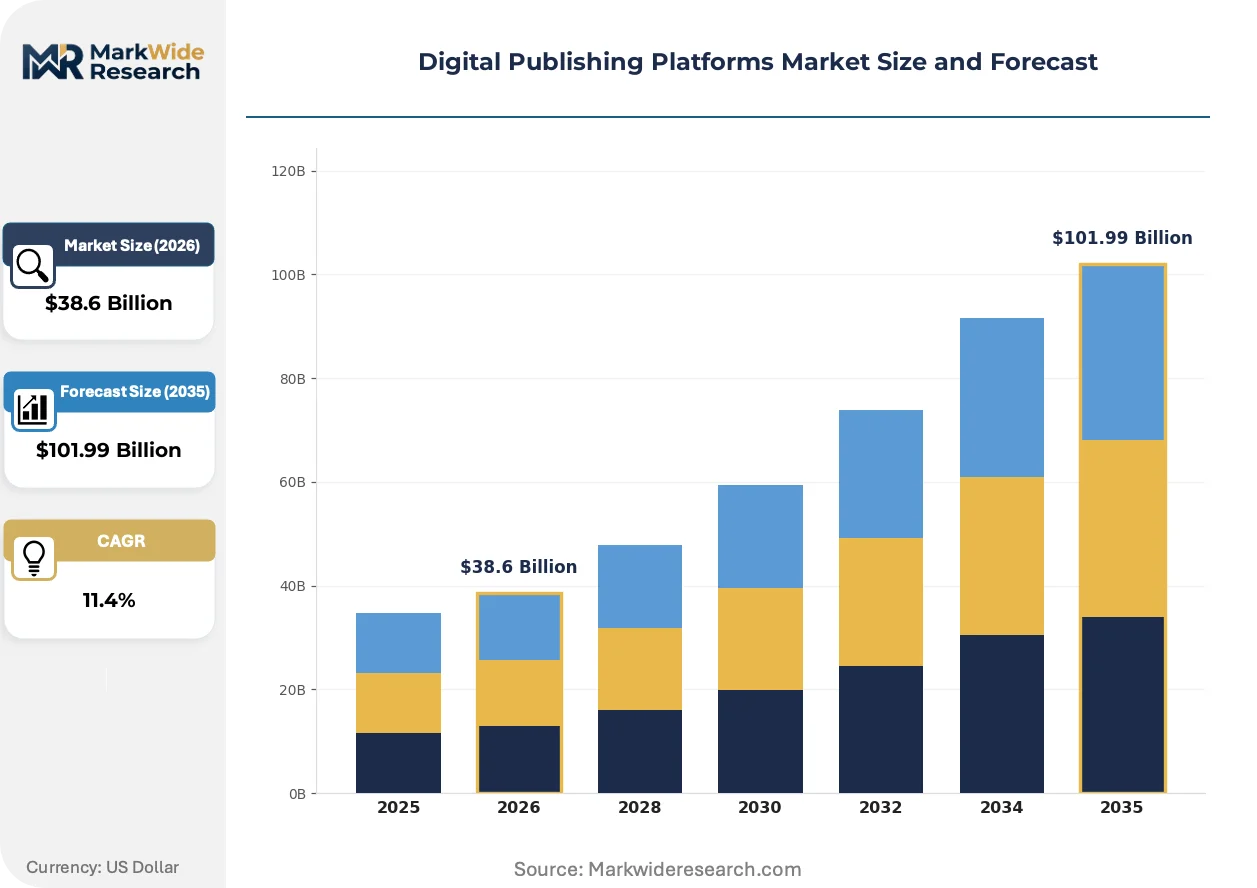
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $101.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Subscription, Advertising, Hybrid, Freemium Content Type: Books, Magazines, Articles, Comics User Type: Authors, Publishers, Readers, Educators Technology: Cloud-Based, Mobile Apps, Web Platforms, E-Publishing Tools |
| Companies Covered | Draft2Digital, Barnes & Noble Press, Amazon.com, Inc., PublishDrive, Ghost, Alphabet Inc., Kobo Writing Life, IngramSpark, Issuu, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Publishing Platforms Market Emerging Trajectories
Generative AI tools are compressing content production timelines while forcing platforms to develop attribution frameworks and synthetic media detection capabilities.
Headless content management architectures are supplanting monolithic publishing suites by decoupling content storage from presentation layers. Enterprise publishers migrating from print-centric workflows are adopting these systems to enable simultaneous multi-channel distribution. This shift is compressing vendor margins as customers demand API-first pricing rather than per-seat licensing models.
The EU Digital Services Act is imposing content accountability obligations on platform operators with user bases exceeding specific thresholds. Publishers must now maintain audit trails for algorithmic content recommendations and provide transparency reports on moderation decisions. Mid-market platforms without dedicated compliance teams are most affected, driving consolidation toward vendors with established European legal infrastructure.
Subscription fatigue among readers is forcing publishers to unbundle content access from platform membership. Individual article micropayments and tokenized access models are replacing all-you-can-read subscriptions in North American and European markets. This behavioral shift pressures platforms to develop flexible metering systems and alternative payment rail integrations.
Digital Publishing Platforms Market Segmentation
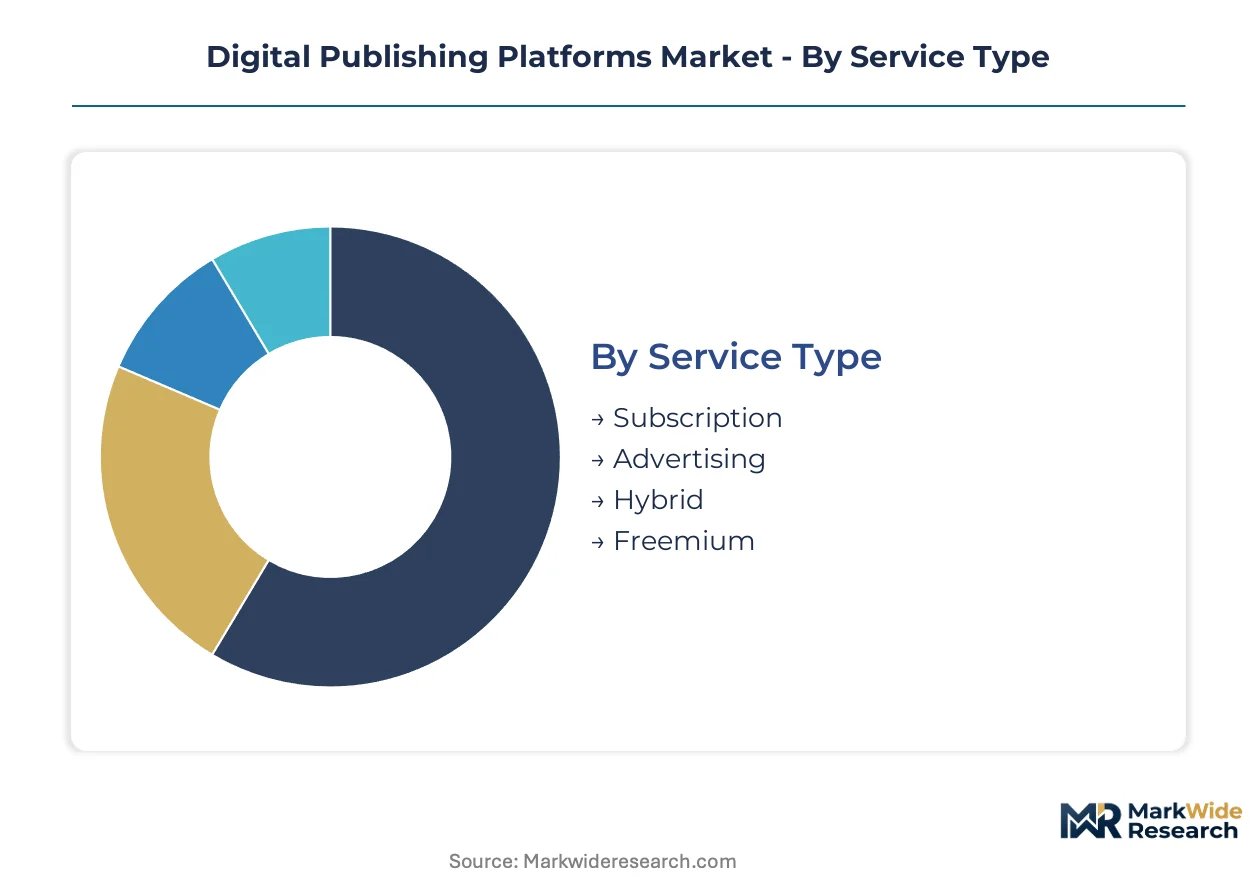
Segmentation in digital publishing platforms reveals how regulatory frameworks, deployment architectures, and monetization models reshape procurement patterns across institutional and consumer markets. Platform vendors configure feature sets and compliance capabilities to match distinct buyer risk profiles and workflow requirements.
Service Type:
GDPR and the EU Digital Services Act impose divergent compliance burdens across revenue models, with subscription platforms facing stricter data retention audits while advertising-dependent services navigate content moderation transparency mandates.
- Subscription:Recurring revenue platforms integrate ISO 27001 certification and European data residency as standard procurement requirements. Enterprise publishers in the United States favor these services for predictable budgeting insulated from advertising volatility.
- Freemium:Tiered conversion architectures allow independent authors to access basic composition tools before upgrading to professional distribution tiers. This model expands most quickly in India and Southeast Asia where price-sensitive creators dominate platform onboarding.
- Advertising:Programmatic monetization platforms must maintain audit trails for algorithmic content recommendations under EU transparency rules. Revenue concentration depends on audience scale and first-party data quality.
- Hybrid:Combined subscription and advertising models require dual compliance frameworks, increasing operational complexity for mid-market platform operators.
Established volume favors Subscription; emerging adoption favors Freemium.
Content Type:
Cost tier differentiation separates premium multimedia production suites from lightweight text-first tools, with FDA-regulated medical publishers and educational institutions driving investment in specialized compliance features.
- Books:Long-form publishing platforms support EPUB3 formatting, DRM encryption, and print-on-demand integration. Demand concentrates among independent authors and small presses replacing legacy InDesign workflows.
- Magazines:Periodical distribution tools emphasize responsive layout engines and issue-based archiving. These platforms face margin pressure from declining print-to-digital migration timelines.
- Articles:Short-form content systems prioritize SEO optimization and micropayment metering. Publishers in North America and Europe are unbundling access from platform membership through tokenized models.
- Comics:Visual narrative platforms require panel-by-panel reflow engines and high-resolution asset management. Japan and South Korea anchor specialized demand for webtoon-optimized distribution.
Revenue stability favors Books; format innovation favors Comics.
User Type:
Customer type determines API complexity and support tier allocation, with educational institutions and enterprise publishers commanding dedicated implementation teams while individual authors self-serve through documentation portals.
- Authors:Individual content creators require streamlined composition interfaces and direct-to-retailer distribution channels. This segment climbs the fastest as generative AI tools compress production timelines for independent writers.
- Publishers:Enterprise houses demand headless CMS architectures, multi-channel syndication, and granular analytics dashboards. Procurement teams mandate audited security frameworks before contract execution.
- Readers:End-user facing features include personalization algorithms and cross-device synchronization. Platform operators monetize through subscription aggregation and affiliate commerce.
- Educators:Learning management integration and accessibility compliance (WCAG 2.1) define procurement criteria for K-12 districts and universities consolidating digital textbook distribution.
Contract value favors Publishers; user growth favors Authors.
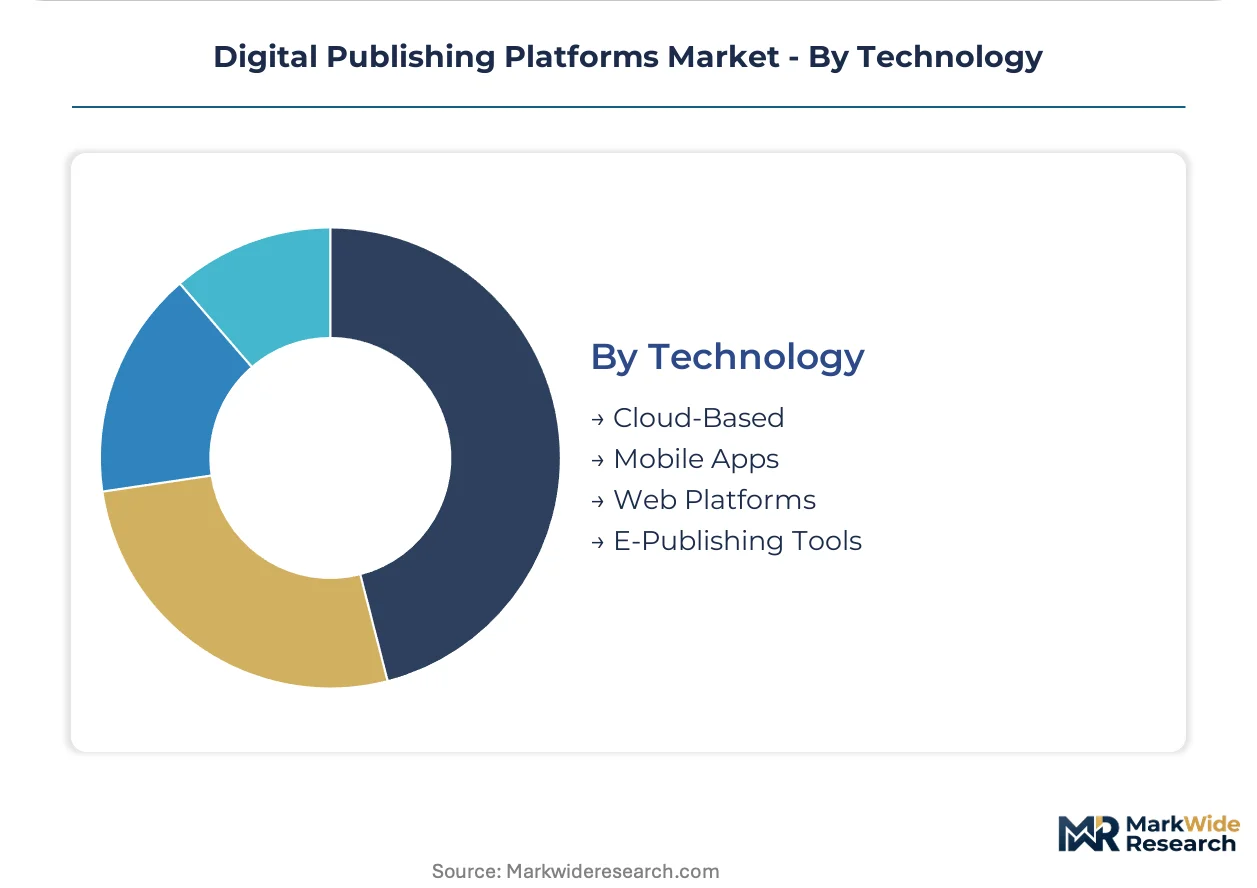
Technology:
Supply concentration in cloud infrastructure shapes deployment economics, with AWS, Microsoft Azure, and Google Cloud dominating hosting costs and exposing platform operators to bandwidth pricing volatility.
- Cloud-Based:SaaS architectures with API-driven content management and elastic scaling dominate mid-market publisher procurement. GDPR data residency requirements favor vendors with European availability zones.
- Mobile Apps:Native iOS and Android distribution requires App Store compliance and in-app purchase revenue sharing. These platforms capture reader engagement through push notification and offline reading features.
- Web Platforms:Browser-based access minimizes download friction and supports instant article preview. Publishers retiring legacy composition systems favor these for rapid deployment without IT infrastructure investment.
- E-Publishing Tools:Desktop software for EPUB formatting and fixed-layout design retains niche demand among production teams requiring offline capability and custom typography control.
Deployment velocity favors Web Platforms; feature depth favors Cloud-Based.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government digitization mandates and data localization requirements are accelerating platform procurement across major publishing economies. National regulators are imposing divergent compliance frameworks that reshape vendor viability by geography. Educational institutions and enterprise publishers drive concentrated demand in markets with mature cloud infrastructure.
United States
Enterprise publishers migrating from print-centric workflows dominate platform procurement, with Fortune 500 media houses replacing legacy composition systems. The FDA regulates health-related digital publications through oversight of medical device software and promotional materials. New York and Los Angeles anchor specialized demand for multimedia production suites serving magazine and entertainment verticals.
Germany
GDPR enforcement has elevated European data residency capabilities to a standard procurement criterion among Mittelstand publishers. The EU Digital Services Act imposes content accountability obligations on platform operators exceeding user thresholds. Berlin and Munich concentrate demand for ISO 27001-certified cloud architectures among mid-market houses.
India
Vernacular content creators remain underserved by English-centric platforms, creating whitespace for localized interfaces and payment integration. The country's national information technology regulator shapes data processing standards for educational content distribution. Bangalore and Hyderabad anchor startup activity in AI-assisted composition tools targeting regional language markets.
United Kingdom
Independent authors and small presses drive fastest user growth through freemium tier conversion architectures. The Information Commissioner's Office enforces GDPR-aligned data protection standards for subscriber management systems. London concentrates demand for headless CMS implementations among financial and professional services publishers.
Japan
Webtoon-optimized distribution platforms capture specialized demand for visual narrative formats and panel-by-panel reflow engines. The Ministry of Economy, Trade and Industry oversees digital content export promotion programs. Tokyo and Osaka anchor concentrated investment in high-resolution asset management systems for comics and illustrated publications.
Digital Publishing Platforms Market Vendor Landscape
Player mix skews toward diversified technology conglomerates with captive distribution infrastructure and advertising technology stacks. Mid-tier independent platforms compete on specialized workflow features for author segments. Strategic archetypes include: vertically integrated marketplace operators, advertising technology consolidators, and print-digital fulfillment specialists. Dominant competitive moves encompass strategic partnerships with educational institutions and portfolio diversification into AI-assisted composition tools.
Within the diversified technology tier, Amazon.com, Inc. and Alphabet Inc. exemplify platform operators leveraging captive infrastructure to sustain margin advantages. IngramSpark anchors the professional publishing archetype through global fulfillment network positioning. Ghost represents the independent developer segment with open-source architecture adoption.
| Leading Market Players |
|---|
| Draft2Digital |
| Barnes & Noble Press |
| Amazon.com, Inc. |
| PublishDrive |
| Ghost |
| Alphabet Inc. |
| Kobo Writing Life |
| IngramSpark |
| Issuu |
| Others |
Supply Flow & Price Mechanics
Thirty-to-ninety-day implementation cycles for cloud-native platform deployment compress procurement timelines while amplifying vendor pricing power among ISO 27001-certified providers. This lead-time band concentrates buyer leverage with AWS, Microsoft Azure, and Google Cloud, whose bandwidth pricing volatility feeds directly into platform operator margin structures and end-customer subscription rates.
Pricing Analysis
Certification level creates the primary spread between vendor tiers, with ISO 27001-audited platforms commanding premium positioning against uncertified competitors. SaaS-tiered subscription models dominate, separating enterprise publishers with dedicated implementation teams from individual authors on self-serve tiers. Price differentiation hinges on data residency capabilities and API call volume allowances, with GDPR-compliant European zones extracting higher rates. Pricing pressure stems from cloud infrastructure concentration, as hyperscaler egress fees compress margins for mid-market platform operators. Independent authors exhibit highest price sensitivity, while Fortune 500 media houses prioritize security audit trails over cost optimization.
Supply Chain Analysis
Just-in-time scaling preferences dominate platform procurement, with elastic cloud architectures replacing strategic capital investment in owned server infrastructure. Supply concentration rests on United States, Ireland, and Singapore as primary hosting jurisdictions, with Frankfurt and Mumbai emerging as GDPR-compliant alternatives. Raw material dependencies include proprietary DRM encryption licenses from Adobe Content Server, API gateway services, and synthetic text detection algorithms. Single-source vulnerability concentrates around AWS dominance in enterprise hosting contracts. Distribution runs through direct SaaS provisioning, with channel partners and educational institution consortia as secondary routes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in digital publishing are approaching an interoperability inflection as headless CMS architectures decouple content storage from presentation layers, forcing vendors to compete on API ecosystem breadth rather than monolithic feature depth.
For Market Incumbents: Consolidate around ISO 27001 certification investments and European legal infrastructure to defend enterprise procurement relationships against emerging cloud-native competitors. Acquire specialized workflow providers serving healthcare and educational verticals before FDA and accessibility compliance requirements harden into non-negotiable procurement criteria. Deepen backward integration into proprietary AI-assisted composition tools to reduce dependency on third-party generative APIs.
For New Entrants and Emerging Players: Differentiate on vernacular language support and localized payment rails to capture India's underserved regional creator base. Target independent author segments in the United Kingdom and Southeast Asia where freemium conversion architectures face softer competitive pressure from established platforms. Pursue hospital system and K-12 district partnerships as channel entry points, leveraging WCAG 2.1 accessibility compliance as a wedge against legacy incumbents.
For Investors and Strategic Acquirers: Long-term, this sits as a vertical SaaS consolidation play because mid-market platforms without dedicated compliance teams are exiting contested accounts under EU Digital Services Act enforcement pressure. Acquisition candidates include ISO 27001-certified regional specialists with established educational institution relationships and AI detection tool development capabilities. Monitor synthetic text disclosure mandate crystallization across multiple regulators as the signal for compliance-driven vendor replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Headless CMS adoption by Fortune 500 media houses displaces monolithic publishing suites. |
| Strategic Partnership | Educational institution LMS consolidation creates institutional demand for cloud-native distribution. |
| Acquisition of Specialist Firm | Healthcare compliance capabilities open FDA-regulated medical device promotional channels. |
| Product Launch | AI-assisted composition tools compress production timelines for independent author segments. |
| Geographic Expansion | Indian language interfaces capture whitespace among vernacular content creators. |
Methodological Framework
Cross-validation between primary interviews with platform engineering directors, educational technology procurement officers, and independent author community leads anchors the qualitative findings in operational reality. Secondary validation draws from SEC filings of diversified technology conglomerates, hyperscaler capex disclosures, EU regulatory transparency reports, and educational institution RFP documentation. Bottom-up triangulation across service type adoption rates and top-down macroeconomic modeling ensures segmentation integrity.
Sensitivity analysis across deployment model, organization size, vertical specialization, and regional regulatory cluster dimensions shapes the analytical framework over the projection horizon. CAGRs derive from modeled subscription revenue pools, freemium conversion velocity, and programmatic advertising convergence timelines. Forecast inputs incorporate cloud infrastructure pricing volatility assumptions and AI-generated content detection investment cycles across platform operators.
Material uncertainties — regulatory mandate crystallization, bandwidth pricing shocks, and educational institution budget cycles — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding GDPR enforcement consistency and hyperscaler market concentration. Revision becomes warranted when EU Digital Services Act compliance cost thresholds cross enterprise procurement abandonment levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Publishing
Magazine Subscription Service Market
Digital Publishing
Newspaper Market
Digital Publishing
Europe E-Book Market
Digital Publishing
Mexico Commercial Printing Market
Digital Publishing
Digital Music Publishing Market
Digital Publishing
Adaptive Content Publishing Market
Digital Publishing
Global E-Book Market
Digital Publishing
Online Comic Market
Digital Publishing
US Newspaper Market
Digital Publishing
Comic Book Market
Digital Publishing
France Catalog Market
Digital Publishing
Books Market
Digital Publishing
Ebook Publishing Platform Market
Digital Publishing
Africa Catalog Market
Digital Publishing
Digital Comics Platform Market
Digital Publishing
Digital Comics Market