
 Books Market | 2026-2036
Books Market Size, Share, and Industry Trends Forecast 2026-2036
Books Market Intelligence
Subscription bundling of audiobooks with e-book access is shifting buyer choice toward all-you-can-consume models rather than single-title purchases. Penguin Random House leverages its backlist depth to anchor bundled offerings across multiple platforms. Scholastic competes through vertical control of the school book fair channel. Hachette Livre differentiates via selective author exclusives that resist commoditization.
Books are bound collections of printed or digitally rendered pages, typically manufactured through offset or digital printing processes on paper stocks ranging from uncoated mechanical to coated freesheet, designed for information transfer, narrative immersion, or educational instruction. The format segment shows hardcover and paperback sustaining unit economics in gift and collector markets while audiobook and e-book formats capture commuter and mobile consumption occasions. Academic titles within product type specialization command premium pricing through revision cycles and course adoption dependencies.
Copyright office frameworks in the United States, the EU Digital Services Act content moderation provisions, and China's SAMR publishing licensing requirements collectively shape content availability, platform liability, and market access across major production geographies. Compliance with divergent national content standards fragments distribution architecture and elevates localization costs for cross-border publishers. Stakeholders must monitor regulatory divergence between open-access mandates and strengthened intellectual property enforcement as the decisive tension shaping content monetization models.
Market Dynamics
Format migration is compressing print-to-digital revenue cycles as national library regulators impose lending mandates that accelerate platform turnover and reshape publisher-platform bargaining power.
Growth Catalysts
- Curriculum refresh cycles:Educational institutions sustain bulk procurement of academic titles through predictable revision schedules that anchor publisher revenue visibility.
- EU Digital Services Act:Content moderation provisions clarify platform liability frameworks, reducing legal uncertainty for cross-border digital distribution.
- Commuter consumption patterns:Mobile listening occasions expand audiobook addressable hours beyond traditional reading windows.
Market Restraints
- Pulp input volatility:Uncoated mechanical and coated freesheet paper stocks face price pressure from energy-intensive manufacturing constraints in Nordic supplier regions.
- China SAMR licensing:Publishing approval requirements fragment distribution architecture and elevate localization costs for foreign content entrants.
- Audiobook substitution:Voice-synthesis narration tools threaten premium human-narrated production tiers.
Strategic Opportunities
- Direct-to-reader platforms:Disintermediation of wholesale channels captures margin previously allocated to distributor intermediaries.
- India educational expansion:Vernacular curriculum adoption creates localized content gaps that regional publishers can fill before multinational entry.
- Subscription bundling convergence:All-you-can-consume models combining audiobook and e-book access lock in recurring revenue streams.
Industry Challenges
- Narrator talent scarcity:Professional voice artist pipelines cannot match audiobook production scaling requirements.
- Cross-border copyright harmonization:Divergent national IP enforcement standards complicate multi-territory licensing negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Books Market |
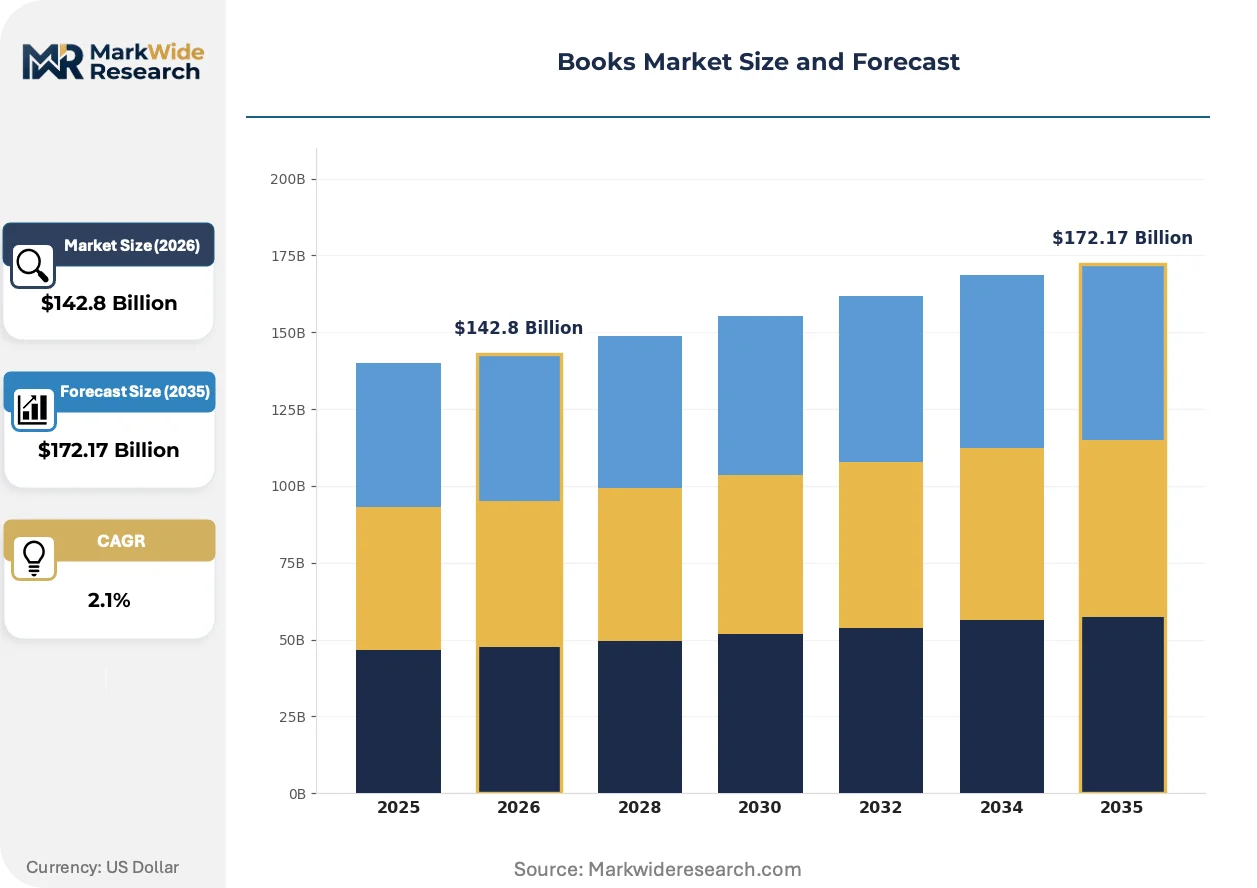
| Market Size in 2026 | $142.8 Billion |
| Market Size in 2035 | $172.17 Billion |
| CAGR (2026 – 2036) | 2.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiction, Non-Fiction, Academic, Reference Genre: Fantasy, Mystery, Romance, Science Fiction Distribution Channel: Online Retail, Bookstores, Libraries, E-Book Platforms Format: Hardcover, Paperback, E-Book, Audiobook |
| Companies Covered | Simon & Schuster, Pearson, Penguin Random House, Springer Nature, Scholastic, HarperCollins, Macmillan Publishers, Wiley, Hachette Livre, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Books Market Strategic Shifts & Innovations
Artificial intelligence tools are compressing production timelines while regulatory fragmentation forces architecture investments that favor scaled operators over mid-tier competitors.
Print-on-demand technology is decentralizing inventory risk from centralized warehousing to distributed fulfillment nodes. Academic publishers adopting this model reduce working capital tied to course adoption uncertainty. The structural consequence is compressing print-run minimums and enabling backlist monetization without remaindering losses.
REACH chemical compliance requirements in Europe are extending to printing inks and binding adhesives used in physical book manufacturing. Industrial consequence includes reformulation costs that disproportionately burden smaller print houses. Gift and collector market hardcover segments face the steepest certification timeline extensions.
Library procurement patterns are consolidating around consortium-level digital licensing that displaces individual branch acquisition autonomy. State and municipal library systems negotiate platform-wide access agreements that aggregate bargaining power. This concentration is most visible in United States metropolitan networks where taxpayer funding scrutiny intensifies cost-per-circulation metrics.
Books Market Segmentation
Format and channel configurations determine margin capture in the Books Market, with digital migration compressing legacy print economics while educational and institutional procurement anchors volume stability across product categories.
Product Type:
REACH chemical compliance requirements in Europe extend to binding adhesives and printing inks, elevating certification burdens for physical Academic and Reference titles while Fiction and Non-Fiction face lighter documentation thresholds.
- Fiction:Narrative content spanning novels, short story collections, and literary works designed for entertainment consumption. Demand concentrates in United States trade publishing clusters where subscription bundling with audiobook access reshapes single-title purchase behavior.
- Non-Fiction:Informational and narrative prose covering biography, history, self-improvement, and current affairs. Commuter consumption patterns in metropolitan United States networks expand addressable hours through mobile listening integration with print editions.
- Academic:Curriculum-aligned textbooks and scholarly monographs subject to revision cycles. China's SAMR publishing licensing requirements fragment distribution architecture for foreign content entrants in this high-value segment.
- Reference:Encyclopedias, dictionaries, atlases, and professional handbooks designed for consultation rather than sequential reading. Digital lending mandates from national library regulators accelerate format migration away from physical stock maintenance.
Leading the category by volume: Academic. Growing fastest: Non-Fiction.
Genre:
Reader preference fragmentation across Fantasy, Mystery, Romance, and Science Fiction creates tiered pricing opportunities where collector hardcover editions command premium positioning against mass-market paperback releases.
- Fantasy:World-building narratives incorporating magical systems and secondary-world settings. Backlist depth from established series sustains revenue visibility through subscription bundling across multiple platforms.
- Mystery:Plot-driven narratives centered on crime investigation and puzzle resolution. Direct-to-reader platforms disintermediate wholesale channels for established authors in this high-velocity category.
- Romance:Relationship-focused narratives with guaranteed emotional resolution. Audiobook production scaling requirements outpace professional voice artist pipeline capacity in this volume-intensive segment.
- Science Fiction:Speculative narratives exploring technological and social futures. Selective author exclusives resist commoditization through platform-specific distribution arrangements.
Volume concentration: Romance. Steepest expansion trajectory: Science Fiction.
Distribution Channel:
Channel selection determines working capital intensity, with E-Book Platforms and Online Retail minimizing inventory risk while Bookstores and Libraries carry physical stock exposure to pulp input volatility from Nordic supplier regions.
- Online Retail:Digital storefronts and e-commerce platforms enabling direct publisher-to-reader fulfillment. Margin capture improves through disintermediation of distributor intermediaries in United States metropolitan markets.
- Bookstores:Physical retail locations providing browse-and-discover environments. Gift and collector market hardcover segments face steepest REACH certification timeline extensions in European operations.
- Libraries:Institutional lending systems operating through individual branch or consortium-level procurement. State and municipal networks in United States metropolitan areas negotiate platform-wide access agreements that aggregate bargaining power.
- E-Book Platforms:Digital distribution infrastructure enabling DRM-protected content delivery. EU Digital Services Act content moderation provisions clarify platform liability frameworks for cross-border distribution.
Dominant by transaction volume: Online Retail. Gaining share fastest: E-Book Platforms.
Format:
Manufacturing process selection—offset versus digital printing—varies by format, with Hardcover and Paperback sustaining unit economics in gift markets while E-Book and Audiobook capture mobile consumption occasions without physical production constraints.
- Hardcover:Rigid case-bound construction using cardboard boards and cloth or paper covering. Collector markets in United States trade publishing clusters sustain premium positioning despite higher per-unit production costs.
- Paperback:Flexible perfect-bound or saddle-stitched construction for mass-market distribution. Print-on-demand technology decentralizes inventory risk to distributed fulfillment nodes for backlist titles.
- E-Book:Digital file formats readable on dedicated devices or multi-purpose screens. National library regulator lending mandates accelerate platform turnover and reshape publisher-platform bargaining power.
- Audiobook:Narrated audio files delivered through streaming or download. Voice-synthesis narration tools threaten premium human-narrated production tiers in high-volume categories.
Volume leadership: Paperback. Climbing the fastest: Audiobook.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters in Germany and the United States generate the bulk of physical book manufacturing capacity, while consumption concentrates in English-language markets and emerging educational systems across Asia.
United States
Trade publishing clusters in New York City and Boston sustain high-volume fiction and non-fiction output through subscription bundling platforms. The Copyright Office frameworks govern content protection and licensing negotiations. Metropolitan library systems in California and Texas negotiate consortium-level digital access agreements that aggregate taxpayer-funded procurement power.
China
Educational title demand anchors volume growth as vernacular curriculum adoption expands in provincial markets. SAMR publishing licensing requirements fragment distribution architecture for foreign content entrants. Print manufacturing concentrates in the Yangtze River Delta region where offset and digital production facilities serve both domestic and export markets.
Germany
Academic and reference title production sustains premium positioning through revision-cycle dependencies in higher education. REACH chemical compliance requirements extend to printing inks and binding adhesives, elevating certification burdens for physical manufacturing. Industrial clusters in Bavaria and Baden-Württemberg host specialized print houses serving collector and gift market segments.
India
Vernacular curriculum gaps in secondary and higher education create localized content opportunities before multinational publisher entry. The country's national education policy frameworks drive bulk procurement cycles for academic titles. Regional publishing hubs in Maharashtra and Karnataka develop indigenous language backlists that compete with translated international editions.
United Kingdom
Educational and professional title exports sustain revenue visibility across Commonwealth markets. The EU Digital Services Act content moderation provisions clarify platform liability for cross-border digital distribution. London-based trade publishers leverage backlist depth to anchor audiobook and e-book bundled offerings across multiple streaming platforms.
Books Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across format and channel dimensions. The market structure tiers into three concentration levels: integrated media holdings with cross-format portfolios, education-centric publishers with vertical channel control, and regional independents with local language specialization. Strategic moves cluster around direct-to-reader platform development and subscription bundling convergence that locks in recurring revenue streams.
Within the integrated media tier, Penguin Random House and Hachette Livre exemplify archetypes of backlist leverage and selective author exclusivity. Pearson and Springer Nature occupy positions in the education and academic specialization vector. Scholastic represents vertical channel control through captive distribution infrastructure. These entities anchor competitive dynamics without dominating absolute share.
| Leading Market Players |
|---|
| Simon & Schuster |
| Pearson |
| Penguin Random House |
| Springer Nature |
| Scholastic |
| HarperCollins |
| Macmillan Publishers |
| Wiley |
| Hachette Livre |
| Others |
Cost & Logistics Intelligence
Metropolitan library consortiums in the United States anchor procurement volume and compress publisher pricing power through aggregated platform-wide access agreements. This buyer concentration forces trade publishers toward subscription bundling models that trade unit margins for recurring revenue predictability.
Pricing Analysis
Margin tightening in academic titles reflects revision-cycle dependencies that lock in course adoptions at premium price points. Three-tier pricing structure across premium hardcover, standard paperback, and economy e-book levels segments buyer willingness-to-pay by format durability and collectibility. Cost compression in mass-market paperback traces to print-on-demand technology decentralization. Educational institutions exhibit lowest price sensitivity due to curriculum-mandated procurement, while commuter audiobook consumers show highest elasticity to subscription bundling alternatives.
Supply Chain Analysis
Single-source vulnerability sits with Nordic mechanical paper suppliers facing energy-intensive manufacturing constraints. Physical book production draws from Germany, the United States, and China for offset and digital printing capacity. Uncoated mechanical paper, coated freesheet stock, and soy-based inks constitute core input dependencies. Tariff exposure on Chinese print manufacturing elevates landed costs for North American distribution. Distribution runs through wholesale intermediaries for bookstore channels, while direct-to-reader platforms bypass inventory risk entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Narrator talent scarcity in audiobook production props premium pricing for human-voiced content, creating supply-constrained margin pools for publishers with established voice artist pipelines.
For Market Incumbents: Extend backlist monetization through subscription bundling convergence that locks readers into recurring revenue streams. Anchor platform negotiations with exclusive author relationships that resist commoditization. Counter voice-synthesis substitution threats by investing in differentiated human narration for high-velocity romance and mystery categories. For New Entrants and Emerging Players: Enter via vernacular curriculum gaps in Indian secondary education before multinational publishers establish localized content dominance. Target regional language backlist development in Maharashtra and Karnataka publishing hubs. Pursue direct-to-reader platform routes that disintermediate wholesale margin extraction. For Investors and Strategic Acquirers: The window for entry favors education-centric publishers with vertical channel control through captive distribution infrastructure. Long-term viability hinges on format migration capabilities across print-to-digital transitions. Monitor EU Digital Services Act enforcement patterns as the signal for platform liability cost inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Bundling Convergence | Combines audiobook and e-book access into recurring revenue models that displace single-title purchases. |
| Direct-to-Reader Platform Development | Captures margin previously allocated to wholesale distributors in United States metropolitan markets. |
| Vernacular Curriculum Localization | Addresses content gaps in Indian secondary education before multinational publisher market entry. |
| Print-on-Demand Infrastructure | Decentralizes inventory risk from centralized warehousing to distributed fulfillment nodes for backlist titles. |
| Voice Artist Pipeline Investment | Secures professional narration capacity ahead of audiobook production scaling requirements in high-volume categories. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with publishing executives, library procurement directors, academic curriculum coordinators, and print manufacturing plant managers validated demand assumptions. Copyright Office registrations, SAMR licensing disclosures, and EU Digital Services Act implementation guidance provided regulatory boundary conditions. Bottom-up title-level revenue modeling triangulated against top-down market sizing from trade association aggregates.
Segmentation granularity operated at product type, format, distribution channel, and regional regulatory cluster levels across the projection horizon. Fiction, non-fiction, academic, and reference categories were modeled separately with distinct revision-cycle and adoption-pattern assumptions. Format migration curves for e-book and audiobook were calibrated against national library lending mandate implementation timelines. CAGRs derived from logistic diffusion modeling of digital substitution rates intersecting with physical format residual demand.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated voice-synthesis narration adoption or abrupt pulp input price spikes. Forecasts reflect documented assumptions about curriculum refresh cycle regularity and platform bargaining power evolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Publishing
Editor App Market
Digital Publishing
Ebook Publishing Platform Market
Digital Publishing
Digital Music Publishing Market
Digital Publishing
Digital Comics Platform Market
Digital Publishing
Online Comic Market
Digital Publishing
Mexico Commercial Printing Market
Digital Publishing
Africa Catalog Market
Digital Publishing
France Catalog Market
Digital Publishing
US Newspaper Market
Digital Publishing
Digital Newspapers and Magazines Market
Digital Publishing
GCC Commercial Printing Market
Digital Publishing
Digital Comics Market
Digital Publishing
Comic Book Market
Digital Publishing
Egypt Book Services Market
Digital Publishing
Japan Catalog Market
Digital Publishing
Middle East Catalog Market