
 Digital Comics Platform Market | 2026-2036
Digital Comics Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Comics Platform Market Insights
Young adult readers migrating from print libraries to mobile-first streaming is bifurcating demand between casual scroll-based consumers and committed archive collectors. WEBTOON Entertainment dominates the vertical-scroll format through proprietary creator tools and serialized release cadences that sustain weekly reader retention. Comixology anchors the Western graphic novel segment through deep catalog partnerships with legacy publishers. Tapas competes in the indie creator economy by lowering revenue-share thresholds and extending direct tipping mechanisms.
A digital comics platform delivers serialized illustrated content through cloud-hosted distribution, optimized for panel-by-panel mobile rendering at 72-300 DPI resolution with adaptive bitrate streaming for high-fidelity artwork. Its primary commercial purpose centers on replacing physical print logistics with instantaneous global access, reducing publisher inventory risk while capturing granular reader engagement data. Webcomics and manga lead platform revenue pools due to weekly release rhythms and established translation pipelines, while freemium subscription models concentrate the fastest-growing user base through tiered content gating. Mobile apps capture disproportionate session duration compared to website portals, reflecting commuter-centric consumption patterns in dense urban markets.
The EU Digital Services Act and GDPR impose content transparency and data portability obligations on platforms serving European readers, forcing investment in automated age-gating and creator attribution systems. The US FTC monitors influencer marketing disclosures within platform-promoted titles, affecting how sponsored webcomics integrate branded narratives. Stakeholders must monitor evolving copyright frameworks for AI-assisted artwork generation, as creator guild negotiations in South Korea and Japan signal precedent-setting royalty structures that will reshape platform economics.
Market Dynamics
Mobile-first serialization is compressing release cycles from monthly print schedules to weekly digital drops, forcing publishers to rebuild production pipelines around real-time reader analytics rather than retail pre-orders.
Growth Catalysts
- GDPR-mandated data portability:European platforms now offer seamless library transfers between services, reducing reader lock-in friction and accelerating subscription switching that rewards superior curation algorithms.
- Creator economy infrastructure:South Korea's webtoon studios provide end-to-end production tools covering scripting, thumbnailing, and coloring that slash entry barriers for independent artists.
- Commuter consumption patterns:Dense urban transit systems in Japan and South Korea generate predictable daily session windows that platforms monetize through timed chapter releases and push notification strategies.
Market Restraints
- Translation pipeline bottlenecks:Human localization teams cannot match the velocity of weekly Korean and Japanese releases, creating content gaps that delay international catalog parity by 12-18 months.
- Creator compensation disputes:Guild negotiations in Seoul and Tokyo are hardening revenue-share floors that compress platform margins already strained by free-to-read ad-supported tiers.
- Device fragmentation:Panel-by-panel mobile rendering requires bespoke asset pipelines for iOS, Android, and emerging foldable form factors that multiply engineering overhead without proportional subscriber gains.
Strategic Opportunities
- AI-assisted localization:Neural translation paired with human refinement is collapsing turnaround times for niche genres that previously lacked commercial justification for manual adaptation.
- Interactive motion comics:Parallax scrolling and limited animation layers are creating premium tier differentiation that commands higher subscription pricing from engaged reader segments.
- Educational licensing verticals:Language learning platforms are licensing manga and webtoon catalogs for contextual immersion, opening B2B revenue streams outside traditional entertainment consumption.
Industry Challenges
- Content moderation at scale:Automated age-gating systems struggle with culturally variable depictions of violence and romance, requiring costly human review layers that slow publication approvals.
- IP provenance verification:AI-generated artwork submission floods are overwhelming creator authentication protocols, forcing platforms to deploy forensic detection tools that raise operational costs and creator friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Comics Platform Market |
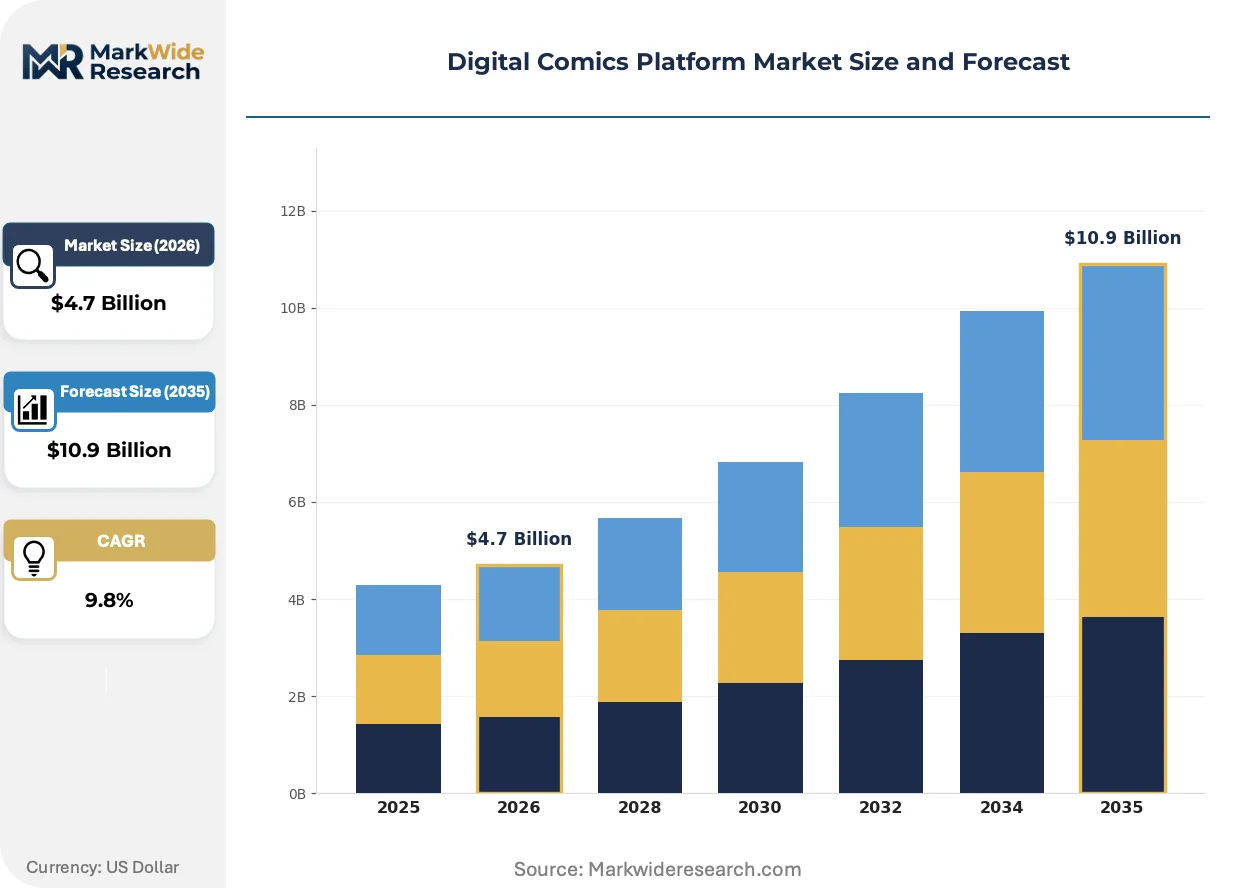
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $10.9 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Content Type: Webcomics, Manga, Graphic Novels, Indie Comics Subscription Model: Monthly Subscription, Annual Subscription, Freemium, Pay-Per-View User Engagement: Reader Comments, Social Sharing, In-App Purchases, Character Voting Platform Type: Mobile Apps, Website, Social Media Integration, E-Readers |
| Companies Covered | WEBTOON Entertainment, Comixology, Tapas, Lezhin Entertainment, GlobalComix, Zestworld, Kindle Comic Creator, Image Comics, DC Comics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Comics Platform Market Trends and Innovations
Adaptive streaming architectures are replacing static image delivery, enabling bandwidth-responsive artwork quality that preserves creator intent across variable network conditions.
Panel-by-panel infinite scroll rendering is supplanting traditional page-turn interfaces on mobile devices. Young adult readers in Seoul and Tokyo have abandoned pagination entirely, demanding vertical formats that eliminate zoom gestures. This compression of reading mechanics is enabling micro-session monetization through chapter-by-chapter tipping rather than volume-based purchases.
The EU Digital Services Act's transparency mandates now require platforms to disclose recommendation algorithms and content removal rationales to European users. Publishers serving German and French markets must rebuild backend systems for auditable ranking logic and appeal workflows. Indie creator platforms lacking compliance infrastructure are withdrawing from EU distribution rather than absorbing compliance costs.
Subscription bundling with music and video services is altering discovery patterns for serialized comics. Readers in São Paulo and Mexico City now encounter manga through telecom-aggregated entertainment packages rather than dedicated platform searches. This channel shift is privileging catalog breadth over curation depth, pressuring niche platforms to consolidate or exit.
Digital Comics Platform Market Segmentation
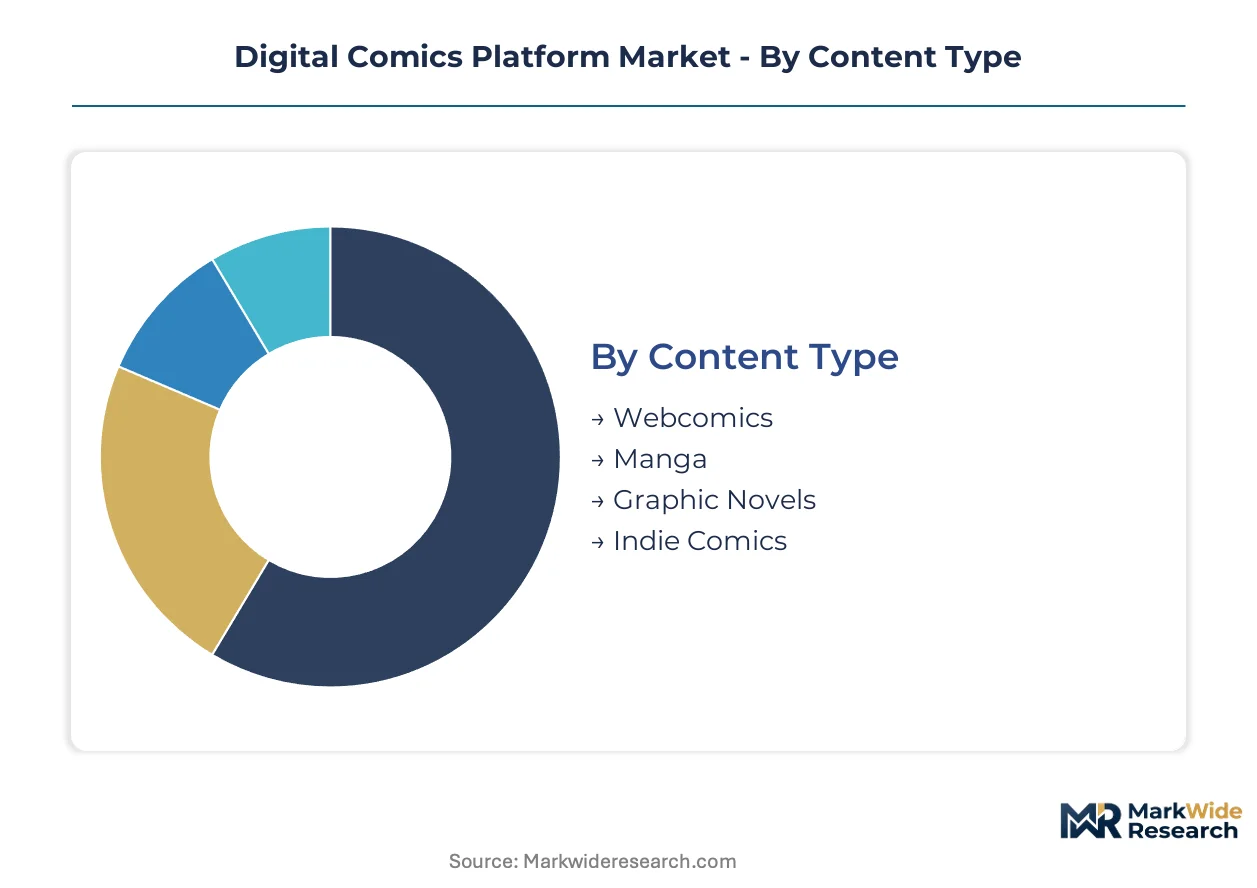
Segmentation in digital comics platforms reveals how consumption mechanics, payment psychology, and device preferences fragment addressable audiences. Platform operators must align content acquisition and feature development with the specific monetization pathways and engagement rituals each segment demands.
Content Type:
Webcomics face the most acute substitution pressure as social media-native creators bypass platforms entirely through direct Patreon or Ko-fi distribution, while manga and graphic novels retain platform dependency due to translation infrastructure and publisher licensing control.
- Webcomics:Vertical-scroll serialized chapters optimized for smartphone consumption, typically released weekly with comment-thread community integration. Demand concentrates in South Korea's creator-studio ecosystem where Naver and Kakao fund production pipelines, though direct-to-fan monetization threatens platform intermediation.
- Manga:Japanese-origin black-and-white panel sequences distributed through licensed digital simulpub releases synchronized with Japanese print schedules. Reader retention in Tokyo and Osaka commuter corridors depends on same-day translation velocity that platforms compete to compress.
- Graphic Novels:Long-form Western comics with complete narrative arcs, demanding higher resolution assets and page-based navigation. Collector-oriented readers in North American markets maintain dual physical-digital libraries, slowing pure-digital adoption.
- Indie Comics:Self-published creator-owned works spanning experimental formats and niche genres. Discovery friction limits scale despite lower revenue-share thresholds attracting artist migration from traditional publishing.
Manga anchors the volume base while webcomics gain share at the steepest rate.
Subscription Model:
Cost tier stratification determines platform margin structure, with annual commitments and freemium gateways representing opposing strategies for customer lifetime value optimization.
- Monthly Subscription:Recurring billing with unlimited catalog access, favored by binge-readers completing series in concentrated windows. Churn spikes correlate with catalog gaps between major releases.
- Annual Subscription:Prepaid yearly access at discounted effective monthly rates, locking in committed readers and improving cash flow predictability for content acquisition budgeting.
- Freemium:Ad-supported free tiers with chapter-delayed or quality-compressed content, converting scroll-based casual users through timed exclusivity gates. South Korean platforms perfected this mechanic before Western adoption.
- Pay-Per-View:Single-chapter or volume purchases without recurring commitment, preferred by archive collectors seeking permanent ownership rather than rental access.
Freemium models capture the largest addressable user base while annual subscriptions deliver the highest revenue per active reader.
User Engagement:
Application-layer features differentiate platforms when content catalogs overlap, with social mechanics and direct creator support building retention moats.
- Reader Comments:Chapter-end discussion threads that serialize community formation alongside content release, generating session extension and return triggers.
- Social Sharing:Panel extraction and format-optimized posting to external platforms, functioning as organic acquisition channels with variable attribution tracking.
- In-App Purchases:Virtual currency systems for early access, bonus episodes, or cosmetic enhancements, particularly effective in webtoon economies with established tipping cultures.
- Character Voting:Reader-influenced narrative branching or popularity-based spinoff greenlighting, deepening emotional investment through participatory storytelling.
Comments and in-app purchases dominate platform investment while character voting expands most quickly as interactive differentiation.
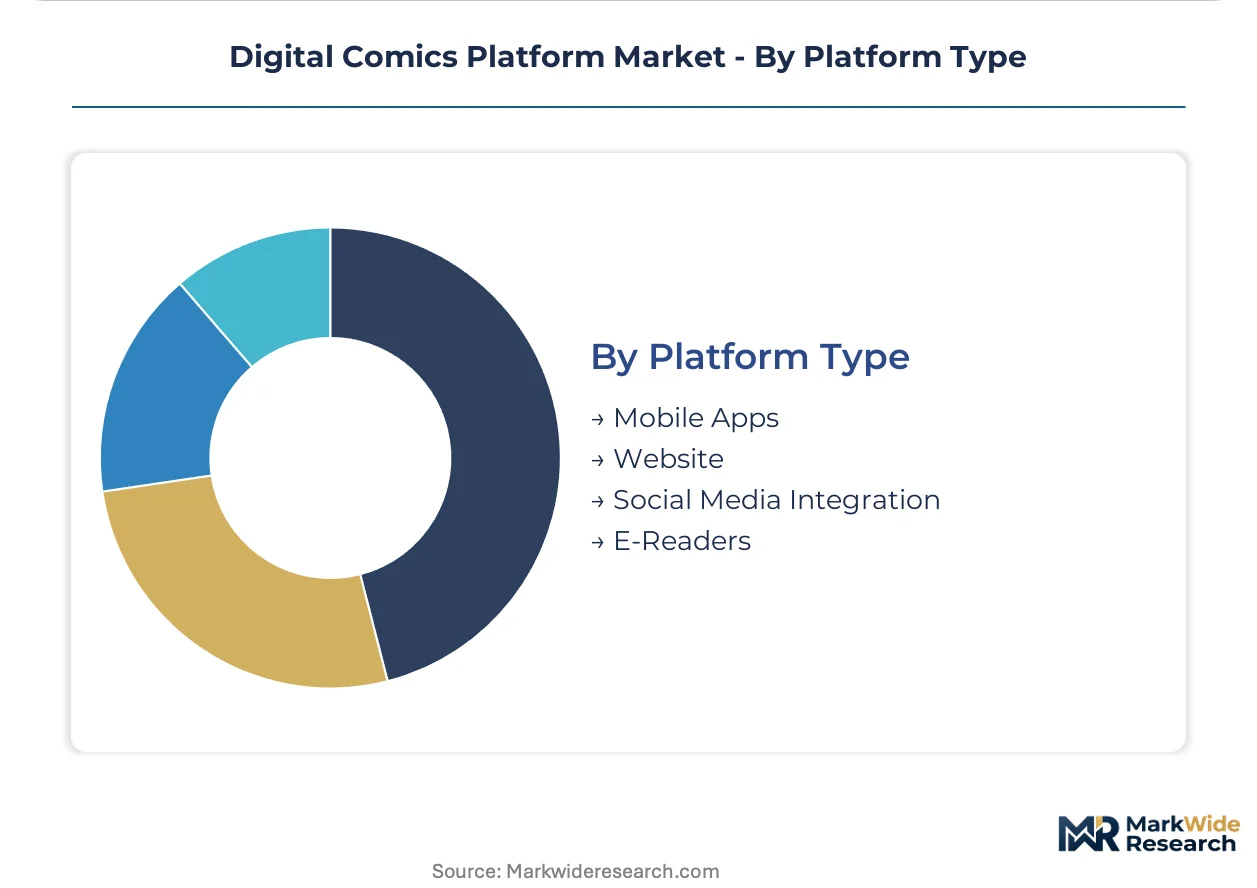
Platform Type:
Device and distribution channel selection constrains content format possibilities and monetization architecture, with mobile supremacy reshaping production standards.
- Mobile Apps:Native iOS and Android clients with offline caching, push notification release alerts, and optimized vertical-scroll rendering. Session duration in Tokyo and Seoul transit systems validates mobile-first development priority.
- Website:Browser-based access with broader format flexibility but inferior offline functionality and notification reach, retaining relevance for desktop workplace consumption.
- Social Media Integration:Distribution through embedded players in Instagram, TikTok, or X, trading platform control for audience scale and reduced acquisition cost.
- E-Readers:Dedicated hardware distribution through Kindle, Kobo, or specialized manga devices, appealing to eye-strain-sensitive readers and physical-book nostalgists.
Mobile apps command the dominant share of session time while social media integration is climbing fastest as discovery shifts to algorithmic feeds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform infrastructure and creator-studio ecosystems concentrate in East Asian metropolitan corridors, with compliance architectures diverging sharply between GDPR-governed European markets and lightly regulated Western jurisdictions.
South Korea
Naver and Kakao fund vertically integrated webtoon production pipelines spanning scripting through coloring. The Korea Communications Commission enforces content rating systems that platforms must integrate into mobile apps. Seoul's Hongdae district hosts the densest concentration of creator studios, where real-time reader analytics reshape weekly release schedules.
Japan
Tokyo and Osaka commuter rail networks generate predictable daily session windows that platforms monetize through timed chapter drops. METI guidelines on platform transparency affect how publishers disclose recommendation algorithms to domestic users. Shibuya's digital content cluster anchors translation pipelines that compress same-day release velocity for international markets.
United States
Graphic novel archive collectors in New York and Los Angeles sustain dual physical-digital library habits that slow pure-digital adoption. The FTC monitors influencer marketing disclosures within platform-promoted titles, affecting sponsored webcomic integration. Seattle's tech corridor hosts engineering teams optimizing panel-by-panel rendering for iOS and Android fragmentation.
Germany
GDPR-mandated data portability reduces reader lock-in friction between competing services in Berlin and Munich. The EU Digital Services Act forces investment in auditable recommendation logic and appeal workflows that smaller platforms cannot absorb. Hamburg's media cluster sees indie creator platforms withdrawing from EU distribution rather than rebuilding compliance infrastructure.
France
CNIL enforcement of algorithmic transparency creates operational overhead for platforms serving Paris and Lyon reader bases. The EU AI Act's content moderation provisions require automated age-gating systems with costly human review layers. Angoulême's comics heritage cluster influences platform curation priorities for European graphic novel catalogs.
Digital Comics Platform Market Competitive Landscape
Concentration sits with vertically integrated East Asian platform operators and Western catalog aggregators. The vendor base splits between creator-economy intermediaries lowering revenue-share thresholds and legacy publishers defending intellectual property control. Two strategic archetypes dominate: mobile-first serialization engines optimized for commuter consumption, and archive-heavy distributors serving collector psychology. Competitive moves center on M&A for translation pipeline capacity and strategic partnerships with telecom bundling channels.
Within the East Asian platform tier, WEBTOON Entertainment and Lezhin Entertainment exemplify vertically integrated creator-studio models. WEBTOON Entertainment anchors the vertical-scroll format through proprietary production tools and serialized release cadences. Lezhin Entertainment occupies a position in premium webtoon distribution with established tipping economies. Among Western catalog aggregators, Comixology represents the legacy graphic novel segment through deep publisher partnerships, while Tapas sits within the indie creator economy by extending direct monetization mechanisms. GlobalComix and Zestworld occupy positions in emerging platform niches focused on independent creator discovery.
| Leading Market Players |
|---|
| WEBTOON Entertainment |
| Comixology |
| Tapas |
| Lezhin Entertainment |
| GlobalComix |
| Zestworld |
| Kindle Comic Creator |
| Image Comics |
| DC Comics |
| Others |
Pricing and Supply Chain Analysis
Ninety-day content localization cycles compress platform pricing power by delaying international catalog parity and forcing aggressive freemium conversion tactics to retain subscriber momentum. This lead-time constraint concentrates supply-side leverage in Seoul and Tokyo creator-studio ecosystems while pressuring margins on translation-heavy tiered subscriptions.
Pricing Analysis
The EU Digital Services Act dictates the pricing tier structure through compliance cost allocation across ad-supported, subscription, and premium interactive tiers. Pricing stratifies across premium motion-comic experiences, standard unlimited subscriptions, and economy freemium delays based on translation velocity and creator attribution depth. Cost compression in the freemium base is intensifying because guild-mandated revenue-share floors in South Korea and Japan squeeze platform margins without proportional subscriber gains. Casual scroll-based readers in dense urban transit corridors exhibit highest price sensitivity, while archive collectors in North American markets accept premium pricing for permanent ownership access.
Supply Chain Analysis
Fourteen-to-eighteen-month translation pipelines inventory content gaps that fragment global release synchronization and amplify regional pricing arbitrage. Supply concentrates in South Korea, Japan, and the United States, where Naver and Kakao fund end-to-end creator pipelines, Shueisha and Kodansha control manga licensing, and Seattle engineering clusters optimize mobile rendering assets. Raw material dependencies include proprietary thumbnailing software, neural translation engines, and cloud bandwidth for adaptive bitrate streaming. Single-source vulnerability runs through Seoul's Hongdae creator-studio cluster, where real-time analytics infrastructure is tethered to platform-specific toolchains. Distribution runs through telecom-aggregated entertainment bundles in São Paulo and Mexico City alongside direct mobile app stores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where creator tipping economies and educational licensing verticals expand faster than base subscription hardware, rewarding platforms that embed recurring revenue layers beyond content access.
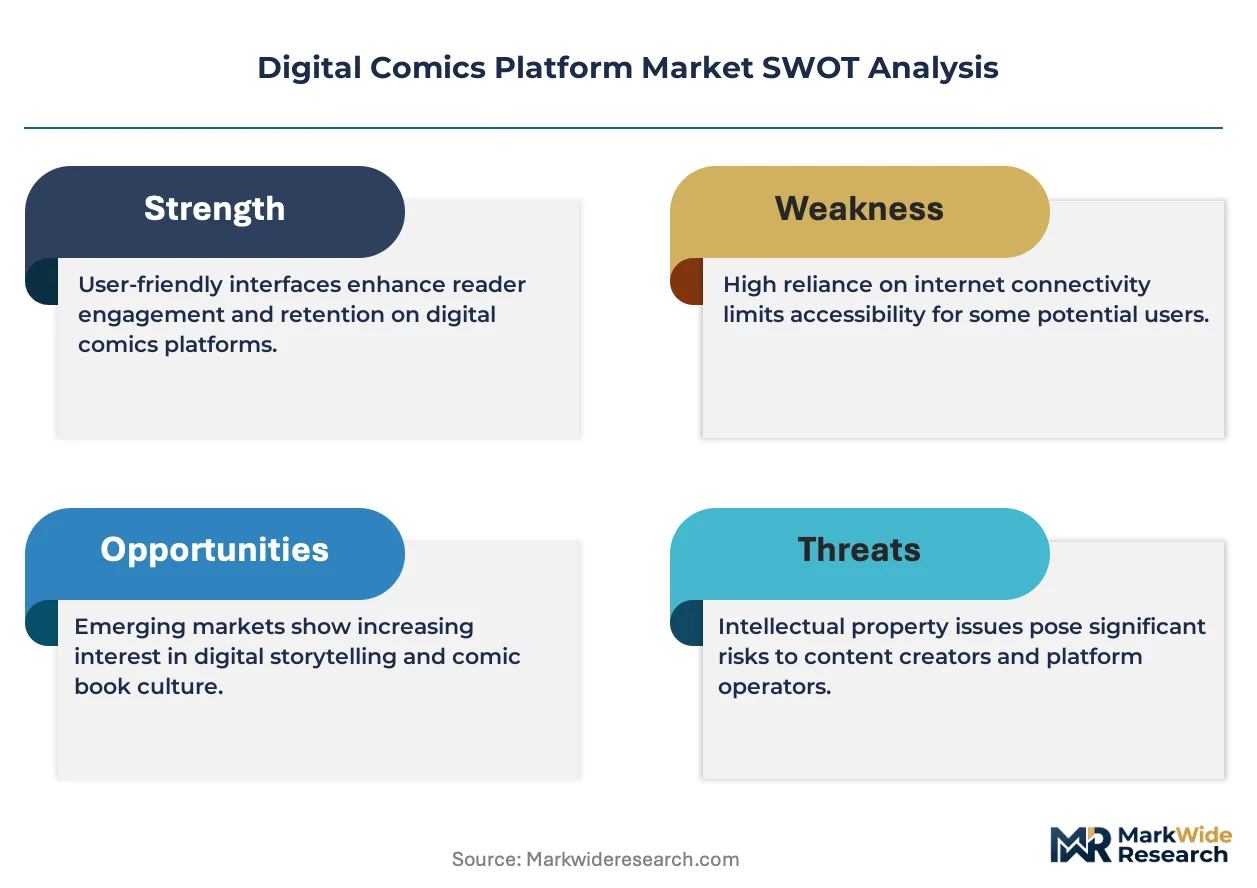
For Market Incumbents: Shield catalog exclusivity by deepening translation pipeline ownership in Shibuya and Hongdae clusters before guild negotiations harden revenue-share floors further. Prioritize backward integration into neural localization engines to collapse turnaround times that currently delay international parity. Fortify against direct-to-fan creator migration by tightening proprietary production tool ecosystems that raise switching costs for webtoon studios. For New Entrants and Emerging Players: Creator authentication and IP provenance verification services represent a service-layer gap where incumbents under-serve indie platforms overwhelmed by AI-generated submission floods. White-space targets include B2B educational licensing for language learning platforms and forensic detection tooling for creator verification. The most penetrable segment sits in indie comics discovery, where lower revenue-share thresholds attract artist migration from traditional publishing. A go-to-market angle anchored in transparent algorithmic curation appeals to European readers disillusioned with opaque recommendation systems. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-utility play because creator-economy tooling and translation pipelines consolidate regardless of which content formats dominate reader attention. Acquisition targets should emphasize vertically integrated studio networks with established weekly release cadences and proprietary analytics dashboards. The signal to watch is guild negotiation outcomes in Seoul and Tokyo, where hardened revenue-share floors would accelerate platform margin compression and trigger consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Neural Localization Engine Deployment | Collapses translation turnaround times for niche genres that previously lacked manual adaptation economics. |
| Creator Studio Vertical Integration | Captures upstream scripting and thumbnailing capacity in Seoul's Hongdae cluster before competitor lock-in. |
| Educational Licensing Partnership | Opens B2B revenue streams through language learning platform integrations outside entertainment consumption. |
| Interactive Motion Comic Tier Launch | Commands premium subscription pricing from engaged reader segments through parallax scrolling differentiation. |
| Telecom Bundling Channel Expansion | Captures discovery-shifted audiences in São Paulo and Mexico City through aggregated entertainment packages. |
Research Methodology
A spread of perspectives from platform product managers, creator-studio executives, localization pipeline directors, and telecom partnership leads converged on the working assumptions shaping this analysis. Primary interviews with these stakeholders combined with secondary validation against SEC filings from publicly traded platform operators, Korea Communications Commission content rating disclosures, and EU Digital Services Act implementation guidance. Customs data on digital content licensing flows and App Annie mobile engagement metrics provided quantitative anchors. Bottom-up subscriber and revenue modeling triangulated against top-down market sizing from trade association releases.
Segmentation dimensions modeled include content type, subscription model, user engagement mechanism, and platform distribution channel across the analysis window. The analytical framework projected value and volume through cohort-based retention curves and content release cadence assumptions. CAGRs derived from historical platform subscriber growth rates, creator compensation trend lines, and regional mobile penetration saturation points. Industry-specific forecast inputs incorporated weekly release rhythm elasticity and translation pipeline compression trajectories.
Underlying assumptions cover sustained mobile-first consumption migration, stable guild negotiation timelines, and continued GDPR enforcement stringency, with deviation risk concentrated in AI-assisted artwork copyright frameworks and sudden platform withdrawal from EU distribution. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Publishing
US Newspaper Market
Digital Publishing
Mexico Commercial Printing Market
Digital Publishing
Japan Catalog Market
Digital Publishing
Digital Comics Market
Digital Publishing
Newspaper Market
Digital Publishing
News and Magazines App Market
Digital Publishing
Africa Catalog Market
Digital Publishing
Digital Comics Distribution and Consumption Platforms Market
Digital Publishing
Global E-Book Market
Digital Publishing
Digital Music Publishing Market
Digital Publishing
Ebook Publishing Platform Market
Digital Publishing
Books Market
Digital Publishing
Digital Publishing Platforms Market
Digital Publishing
China Catalog Market
Digital Publishing
Book Publishers Market
Digital Publishing
Europe E-Book Market