
 Global E-Book Market | 2026-2036
Global E-Book Market Size, Share, and Industry Trends Forecast 2026-2036
Global E-Book Market Analysis
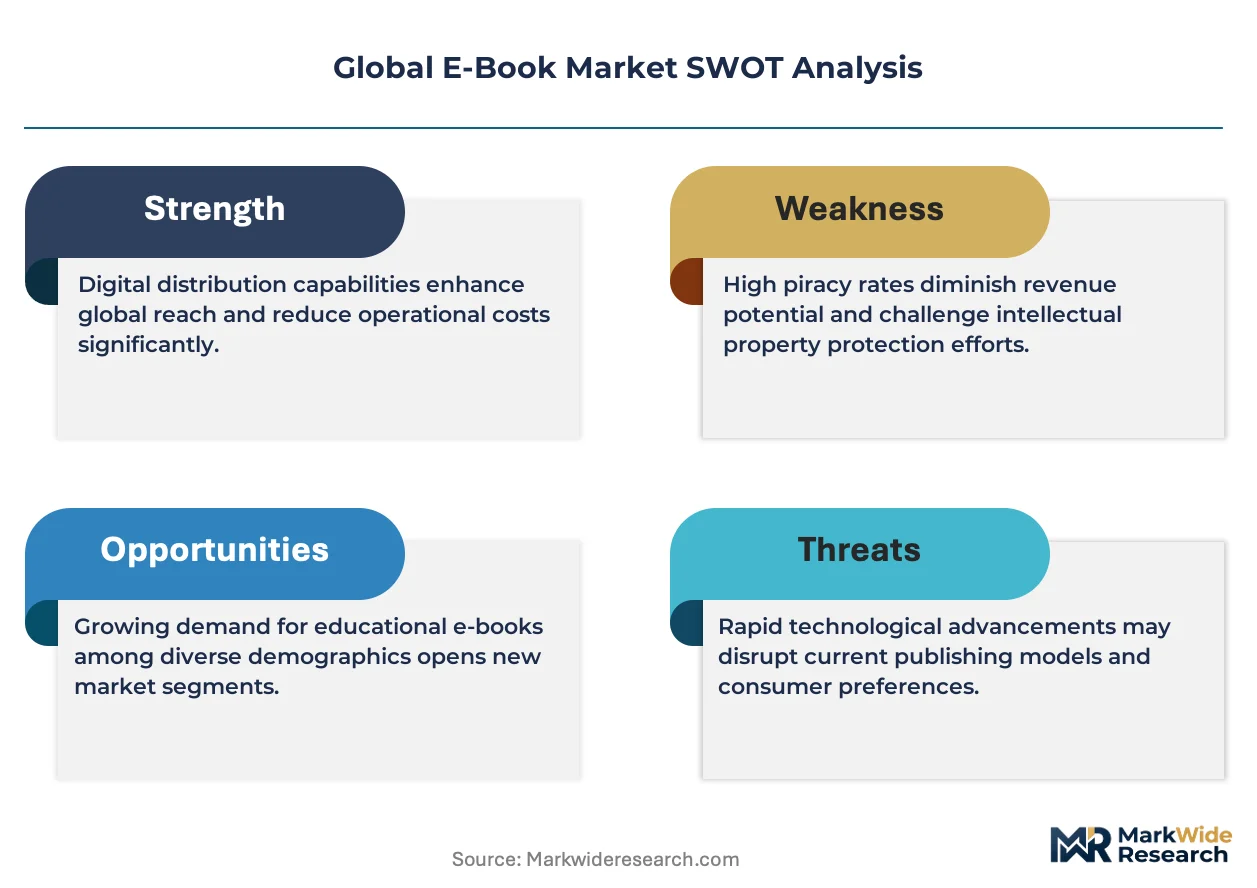
The EU Green Deal is realigning publisher sustainability commitments toward carbon-neutral digital distribution infrastructure. Amazon.com Inc. leverages its Kindle ecosystem to control hardware-software integration across major markets. Apple Inc. competes through tight vertical integration between its Books app and device ecosystem. Rakuten Kobo Inc. specializes in localized content partnerships across European and Asian markets.
E-books are digital publications encoded in reflowable or fixed-layout formats, typically distributed through DRM-protected files optimized for backlit or e-ink display technologies, serving consumer reading, education, and professional reference needs. The EPUB format dominates open-standard distribution due to accessibility compliance and reflow adaptability, while subscription services capture recurring revenue pools as reader preference shifts from unit sales to access models. E-reader hardware anchors premium engagement segments where dedicated devices reduce eye strain versus multi-purpose tablets.
FDA oversight intersects with e-book markets where health and medical content requires accuracy validation, while the EU AI Act governs automated recommendation algorithms deployed by European platforms. ECHA REACH compliance affects device manufacturing materials for e-readers sold in European markets. Stakeholders must monitor evolving accessibility mandates from national disability regulators as litigation risk around WCAG non-compliance intensifies across digital publishing.
Market Dynamics
The shift from unit sales to subscription access models is restructuring revenue capture across the e-book value chain, forcing publishers to rebuild distribution economics around recurring reader relationships rather than discrete transactions.
Growth Catalysts
- EPUB Accessibility Mandates:WCAG compliance requirements from national disability regulators in the United States, Germany, and Japan are accelerating format standardization investments that expand addressable readership.
- Academic Digital Procurement:University systems across Canada, the United Kingdom, and Australia are consolidating textbook budgets into platform licenses that bundle e-book access with learning management integration.
- Reflowable Format Superiority:EPUB's adaptability across screen sizes and assistive technologies is displacing fixed-layout alternatives in education and professional segments where device diversity prevails.
Market Restraints
- DRM Infrastructure Concentration:Encryption and rights management capabilities cluster among three US-based technology providers, creating vendor lock-in risk for mid-size publishers.
- E-Ink Display Supply Bottlenecks:Production of electrophoretic display panels concentrates in Taiwan and mainland China facilities, exposing hardware manufacturers to geographic concentration vulnerability.
- Print-to-Digital Substitution Drag:Used physical book marketplaces and library lending systems in France, Italy, and Spain continue capturing price-sensitive reader segments.
Strategic Opportunities
- India Regional Language Scale:Hindi, Tamil, and Marathi e-book platforms are penetrating tier-two cities where English-language content historically dominated, creating first-mover advantages for localized catalogs.
- EU AI Act Compliance Services:Automated content recommendation audit tools represent emerging revenue streams as European platforms face algorithmic transparency mandates.
- Healthcare Reference Convergence:Integration of e-book platforms with clinical decision support systems is opening institutional licensing channels in hospital networks across Germany and the Netherlands.
Industry Challenges
- Accessibility Litigation Exposure:WCAG non-compliance lawsuits against publishers and platforms are intensifying in United States federal courts, requiring proactive remediation of backlist catalogs.
- Cross-Platform Format Fragmentation:Proprietary enhancement layers added by major retailers are fragmenting the reading experience and increasing publisher production costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global E-Book Market |
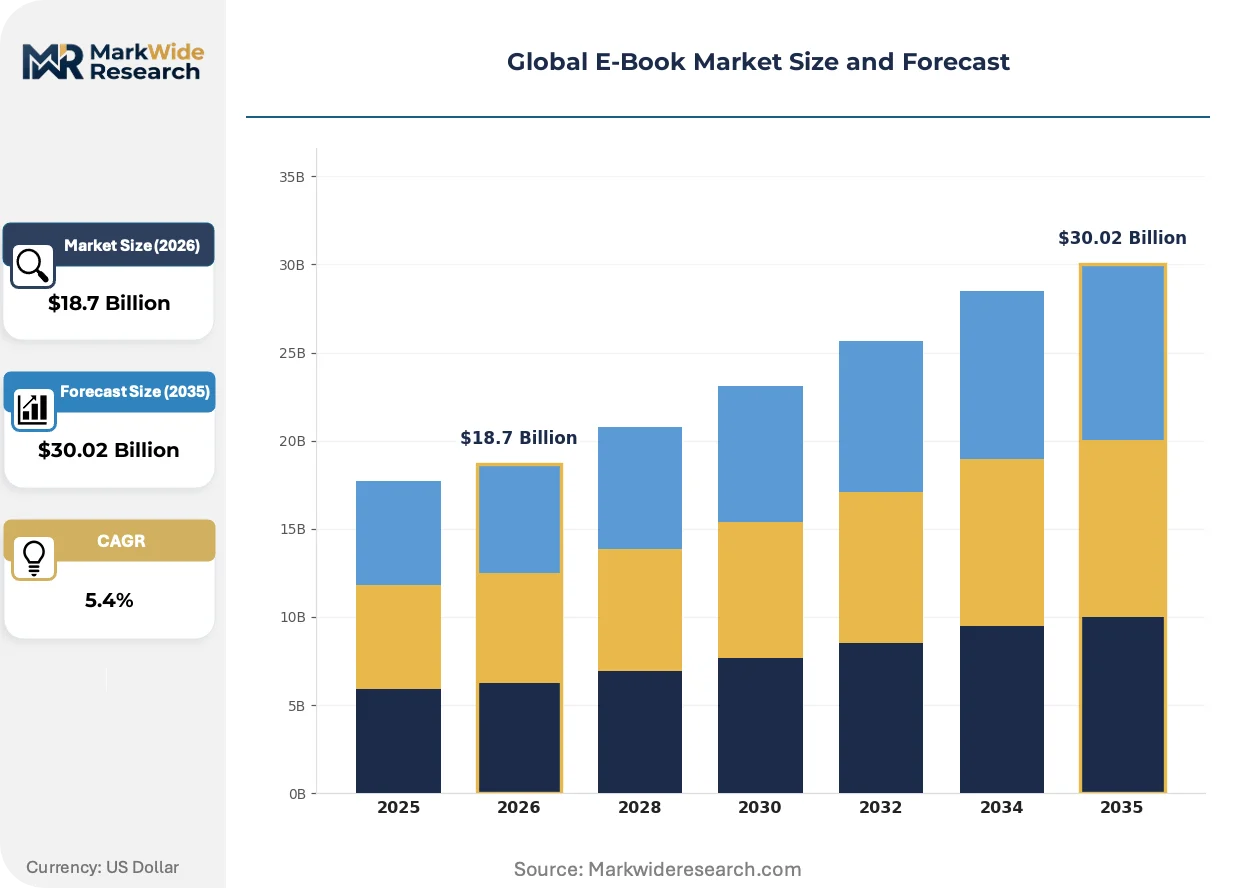
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Format: PDF, EPUB, MOBI, AZW Distribution Channel: Online Retailers, Subscription Services, Direct Sales, Libraries Device Type: E-Readers, Tablets, Smartphones, Computers Genre: Fiction, Non-Fiction, Academic, Self-Help |
| Companies Covered | Amazon.com Inc., Apple Inc., Rakuten Kobo Inc., Barnes and Noble LLC, Alphabet Inc., Scribd Inc., Smashwords Inc., BookBaby, Lulu Press Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global E-Book Market Emerging Trajectories
Technology convergence between e-reading hardware and health-monitoring sensors is creating new product categories, while regulatory pressure on algorithmic systems is forcing platform architecture redesigns.
EPUB 3 multimedia extensions are consolidating interactive educational content into single-file distribution packages that embed assessments, video, and annotation layers. K-12 districts in Ontario and Victoria are piloting these enriched formats for STEM curriculum delivery. The technology is consolidating previously separate learning tool vendors into integrated platform ecosystems.
The EU AI Act's algorithmic transparency requirements are mandating explainability documentation for content recommendation engines deployed by European e-book platforms. Publishers operating in France and Germany must now maintain audit trails linking user behavior signals to automated suggestions. Academic platforms serving these markets are responding by shifting toward librarian-curated discovery interfaces that reduce black-box algorithm exposure.
Corporate learning departments are unbundling traditional training library subscriptions in favor of role-specific micro-licenses that align content access with individual competency frameworks. This procurement model change is disrupting multi-year enterprise agreements that previously bundled generic business titles. The shift is most visible in financial services and consulting firms across London, Singapore, and New York, where talent development budgets now flow through skills-mapping software rather than centralized library services.
Global E-Book Market Segmentation
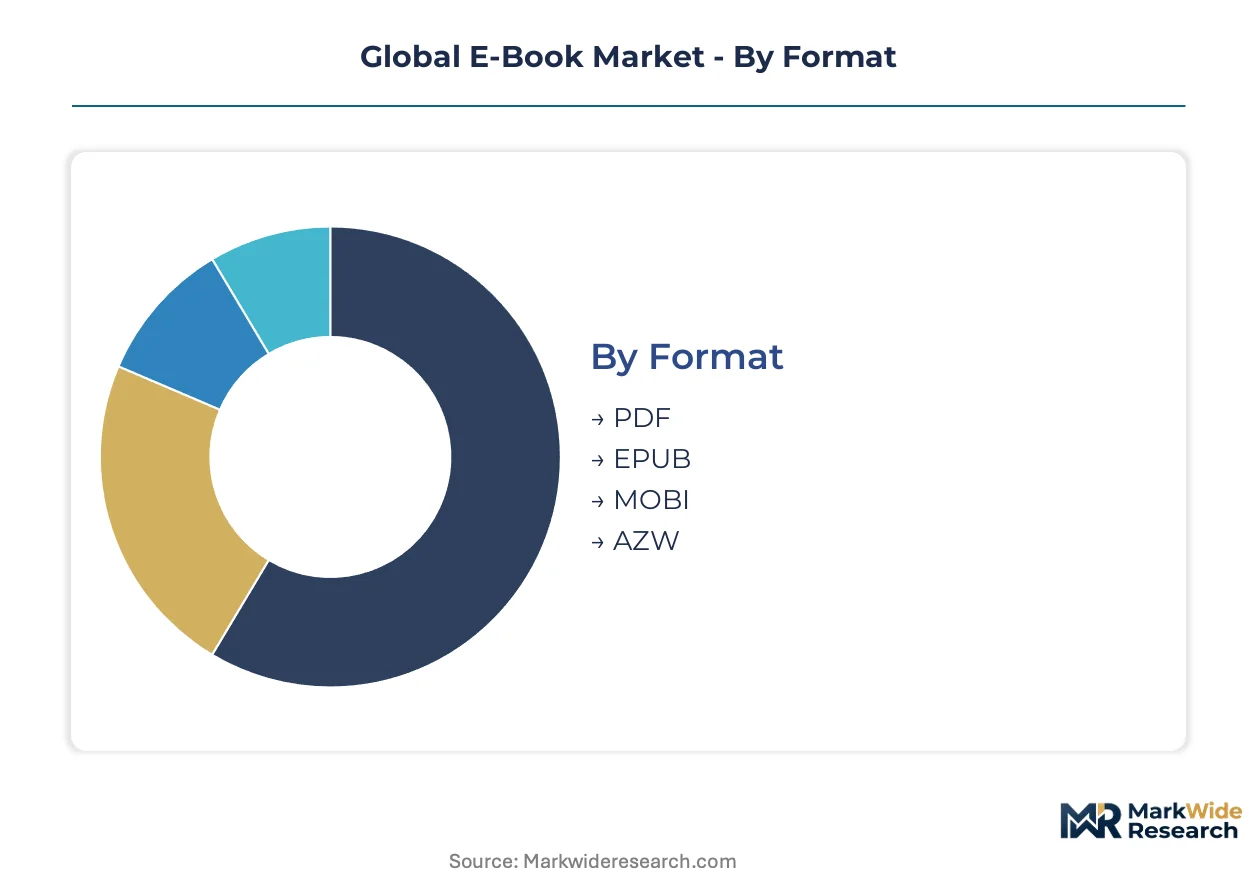
Format diversity in the e-book market creates distinct production economics and reader experience profiles. Distribution channel fragmentation determines revenue capture models and publisher-platform power dynamics. Device type and genre segmentation further stratify addressable audiences and content monetization strategies.
Format:
Supply concentration in format technologies clusters around open-standard versus proprietary ecosystems, with production workflows and DRM infrastructure determining publisher switching costs.
- EPUB:The open-standard reflowable format dominates educational and accessibility-compliant distribution due to WCAG support and screen adaptability. Academic procurement mandates in Canada and Australia are accelerating publisher migration from fixed-layout alternatives.
- PDF:Fixed-layout preservation of print pagination retains dominance in professional reference and legal documentation where exact reproduction matters. Corporate learning departments in Germany and the Netherlands favor PDF for technical manual distribution despite limited mobile reflow.
- MOBI:Legacy Amazon format facing gradual phase-out as Kindle devices adopt EPUB compatibility; residual demand concentrates in older hardware installed base.
- AZW:Proprietary Amazon format enabling enhanced typography and WhisperSync integration; captive to Kindle ecosystem with limited cross-platform portability.
EPUB absorbs the bulk of installed capacity; EPUB is expanding most quickly as accessibility mandates proliferate.
Distribution Channel:
Channel economics vary sharply between unit-sale capture and recurring revenue models, with customer acquisition costs and lifetime value calculations driving publisher resource allocation.
- Online Retailers:Unit-sale marketplaces dominated by Amazon.com Inc. and Apple Inc. capture consumer impulse purchases through device-integrated storefronts. These platforms extract 30-70% revenue shares while controlling discovery algorithms.
- Subscription Services:Access models from Scribd and Kobo Plus are restructuring reader relationships toward recurring payments. These services concentrate demand among high-volume readers in the United States and United Kingdom.
- Direct Sales:Publisher-controlled storefronts bypass platform fees but require independent marketing investment; niche academic and professional publishers favor this channel for institutional licensing.
- Libraries:OverDrive and hoopla facilitate licensed lending with per-checkout or flat-fee models; budget constraints in French and Italian public systems limit expansion versus used physical book alternatives.
Online retailers absorb the bulk of installed capacity; subscription services are climbing the fastest as reader preferences shift from ownership to access.
Device Type:
Hardware differentiation creates distinct engagement profiles, with dedicated reading devices commanding premium positioning against multi-purpose screens.
- E-Readers:E-ink electrophoretic displays from Taiwan and mainland China supply chains reduce eye strain and extend battery life. These devices anchor premium consumer segments in Japan and Germany where dedicated reading hardware persists.
- Tablets:Multi-purpose LCD and OLED screens from Apple Inc. and Samsung Electronics capture casual readers prioritizing multimedia consumption over text immersion.
- Smartphones:Ubiquitous access drives micro-reading sessions and serialized fiction consumption; India regional language platforms exploit this form factor for tier-two city penetration.
- Computers:Desktop and laptop access dominates academic research and professional reference use cases requiring multi-window workflows and annotation tools.
Smartphones absorb the bulk of installed capacity; e-readers are gaining share fastest as hardware-software integration deepens.
Genre:
Genre segmentation reflects divergent production costs, pricing power, and institutional procurement patterns across consumer and professional markets.
- Fiction:Trade narratives dominate unit sales volume with romance, thriller, and science fiction subgenres driving subscription platform engagement; self-publishing has fragmented supply across Amazon Kindle Direct Publishing.
- Non-Fiction:Biography, history, and journalism titles command higher unit pricing with stronger backlist longevity; airport retail and gift markets in the United Kingdom sustain this segment.
- Academic:Textbook and monograph licensing integrates with learning management systems; university consolidations in Ontario and Victoria are bundling e-book access into platform licenses.
- Self-Help:Personal development and wellness content exploits impulse purchase behavior with lower price points and higher volume velocity; corporate wellness programs in Singapore are emerging as institutional buyers.
Fiction absorbs the bulk of installed capacity; academic is expanding most quickly as digital procurement consolidates across university systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seattle anchors hardware-software integration for the global e-book market through Amazon's Kindle ecosystem development. The metropolitan cluster concentrates cloud infrastructure, DRM engineering, and content recommendation algorithm design. This technology concentration shapes procurement patterns across North American university systems and consumer markets.
United States
Academic digital procurement consolidates across state university systems in California, Texas, and New York. The Department of Education's accessibility enforcement under Section 508 pressures publishers toward EPUB3 compliance. The Boston-Cambridge corridor hosts learning management system vendors integrating e-book platforms with institutional licensing workflows.
Germany
Thuringia and Saxony house specialized e-ink display engineering facilities serving European hardware manufacturers. The EU AI Act mandates algorithmic transparency documentation for content recommendation engines deployed by Frankfurt-based publishing platforms. Munich anchors corporate learning departments unbundling traditional training subscriptions for role-specific micro-licenses.
India
Hindi, Tamil, and Marathi e-book platforms penetrate tier-two cities across Maharashtra and Karnataka where English-language content historically dominated. The Ministry of Electronics and Information Technology's digital literacy programs accelerate smartphone-based reading adoption. Hyderabad and Bangalore host regional language content aggregation startups capturing first-mover advantages in localized catalogs.
United Kingdom
University consolidations in Ontario and Victoria influence procurement templates adopted by British academic institutions. The Competition and Markets Authority scrutinizes platform fee structures in digital textbook distribution. London's financial services and consulting firms drive corporate learning unbundling toward skills-mapped micro-licenses.
Japan
Dedicated e-reader hardware persists in premium consumer segments across Tokyo and Osaka metropolitan areas. The Ministry of Economy, Trade and Industry promotes EPUB accessibility standards alignment with JIS specifications. Kyoto hosts specialized publishers integrating e-book platforms with clinical decision support systems for hospital networks.
Global E-Book Market Vendor Landscape
Premium-margin players sit above commodity-margin players across hardware-software integration depth and content ecosystem lock-in. The market structure concentrates around three US-based technology providers controlling DRM infrastructure, creating vendor lock-in risk for mid-size publishers. Two strategic archetypes dominate: vertically integrated hardware-software platforms and specialized regional content aggregators. Competitive moves center on localized content partnerships and accessibility compliance service expansion.
Within the vertically integrated tier, Amazon.com Inc. and Apple Inc. exemplify hardware-software ecosystem control across major consumer markets. Rakuten Kobo Inc. occupies a position emphasizing localized content partnerships across European and Asian markets. These three entities represent distinct geographic and strategic positioning archetypes rather than direct product competition.
| Leading Market Players |
|---|
| Amazon.com Inc. |
| Apple Inc. |
| Rakuten Kobo Inc. |
| Barnes and Noble LLC |
| Alphabet Inc. |
| Scribd Inc. |
| Smashwords Inc. |
| BookBaby |
| Lulu Press Inc. |
| Others |
Supply Flow & Price Mechanics
E-ink display panel costs from Taiwan and mainland China facilities flow through hardware manufacturer procurement tiers into consumer-facing device pricing, with electrophoretic display supply concentration enabling premium capture for dedicated e-reader vendors while compressing margins for mid-tier tablet competitors.
Pricing Analysis
Per-title licensing fees tied to institutional learning outcomes anchor academic segment pricing, with university systems in Canada and Australia negotiating platform bundles that embed e-book access into semester fees. Subscription services extract recurring revenue through Scribd and Kobo Plus models that trade unit-sale margins for customer lifetime value. Price compression runs through self-published fiction tiers where Kindle Direct Publishing authors compete on volume velocity. Corporate learning departments show lowest price sensitivity for clinical decision support integration, while individual consumers in France and Italy remain most sensitive due to used physical book marketplace alternatives.
Supply Chain Analysis
Dual-sourcing requirements from hardware manufacturers mandate qualified suppliers for e-ink electrophoretic displays across both Taiwan and mainland China production facilities, though actual supply concentrates in a single dominant vendor. Raw material dependencies include indium tin oxide for transparent electrodes, microencapsulated pigment particles for display layers, and lithium polymer cells for power management. Single-source vulnerability in electrophoretic display engineering exposes hardware vendors to geographic concentration risk from cross-strait logistics disruption. Distribution runs through Amazon's captive Kindle ecosystem, Apple's device-integrated storefront, and Rakuten Kobo's regional retail partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's algorithmic transparency mandates create a compliance moat where audit-ready platforms capture institutional procurement from laggard competitors, transforming regulatory burden into sustainable competitive advantage.
For Market Incumbents: Acquire specialized accessibility compliance service providers to preempt WCAG litigation exposure in United States federal courts. Consolidate DRM infrastructure capabilities through backward integration into encryption engineering, defending against vendor lock-in risk from the three dominant US-based technology providers. Channel control through librarian-curated discovery interfaces reduces black-box algorithm liability under European transparency requirements. For New Entrants and Emerging Players: Capture Hindi, Tamil, and Marathi content aggregation opportunities in Maharashtra and Karnataka tier-two cities where English-language platforms historically neglected demand. Target regional language smartphone reading segments through micro-transaction models that exploit India's digital literacy program infrastructure. Go-to-market through Ministry of Electronics and Information Technology partnerships accelerates user acquisition cost efficiency versus direct consumer marketing. For Investors and Strategic Acquirers: EU AI Act enforcement actions against non-compliant recommendation engines are the leading indicator that algorithmic transparency service providers will command acquisition premiums. Long-term viability over the next decade favors platforms with documented audit trails linking user behavior to automated suggestions. Target acquisition archetype: European academic platforms with pre-built explainability documentation and librarian-curated discovery layers.| Strategic Initiative | Industry Significance |
|---|---|
| EPUB3 Accessibility Compliance Investment | WCAG remediation services capture procurement mandates from California and New York state university systems. |
| Regional Language Content Partnership | Marathi and Tamil catalog depth secures first-mover positioning in Hyderabad and Bangalore aggregation markets. |
| Algorithmic Transparency Audit Tool Development | EU AI Act documentation platforms serve Frankfurt-based publishers facing French and German enforcement. |
| Clinical Decision Support Integration | Kyoto hospital network licensing opens institutional recurring revenue channels in Japanese healthcare. |
| Corporate Learning Micro-License Unbundling | Skills-mapped procurement aligns with London financial services talent development software workflows. |
Methodological Framework
Trade association filings from the Association of American Publishers, customs records for e-reader device imports, and SEC disclosures from Amazon.com Inc. and Apple Inc. formed the secondary backbone, cross-referenced with primary interviews involving platform engineering directors at Rakuten Kobo, accessibility compliance officers at Canadian university systems, and DRM infrastructure specialists at mid-size publishing houses. Bottom-up and top-down triangulation validated installed base estimates for e-ink versus LCD display hardware across Japan and Germany.
Bottom-up modeling segmented volume and value across format type, distribution channel, device category, and genre, with additional stratification by regional language platform penetration in India. CAGRs derived from regression analysis against digital literacy program enrollment curves and academic procurement consolidation timelines. Forecast inputs incorporated electrophoretic display production capacity expansion from Taiwan facilities and EU AI Act implementation phase-in schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to cross-strait logistics disruption and United States federal court accessibility litigation volume. Projections reflect assumptions around continued EPUB3 migration rates and smartphone display technology substitution patterns. A model refresh is warranted upon material change in EU AI Act enforcement precedent or Thuringia e-ink engineering facility capacity allocation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Publishing
Books Market
Digital Publishing
Digital Comics Distribution and Consumption Platforms Market
Digital Publishing
Online Comic Market
Digital Publishing
Digital Reading Market
Digital Publishing
Japan Catalog Market
Digital Publishing
Digital Publishing Platforms Market
Digital Publishing
Adaptive Content Publishing Market
Digital Publishing
Europe E-Book Market
Digital Publishing
Children Illustration Book Market
Digital Publishing
Digital Comics Market
Digital Publishing
US Newspaper Market
Digital Publishing
China Catalog Market
Digital Publishing
France Catalog Market
Digital Publishing
Middle East Catalog Market
Digital Publishing
Mexico Commercial Printing Market
Digital Publishing
Africa Catalog Market