
 US Newspaper Market | 2026-2036
US Newspaper Market Size, Share, and Industry Trends Forecast 2026-2036
US Newspaper Market Intelligence
USPS Periodicals class certification is bifurcating the competitive field between publishers who qualify for subsidized postal rates and those pushed toward digital-only distribution. Gannett Co., Inc. leverages its national scale to sustain favorable bulk-mailing contracts across hundreds of local markets. The New York Times Company differentiates through premium digital subscriptions that reduce its dependence on print postal economics. Lee Enterprises anchors its strategy in mid-size Midwestern dailies where it controls the dominant local news franchise.
US newspapers are periodical publications printed on newsprint or distributed digitally, typically issued daily or weekly, with editorial content ranging from investigative reporting to classified advertising and commercial messaging. Modern production employs offset web printing for dailies above fifty thousand circulation and digital-first workflows for online editions, serving democratic information dissemination and local commerce facilitation. The delivery method dimension shows hybrid print-digital models retaining the largest revenue pool as advertisers value cross-platform audience reach, while pure digital segments capture the fastest expansion among subscriber revenue streams. Content focus tilts toward local news in community publications where limited competition preserves pricing power, whereas national news competes in a saturated attention economy against broadcast and streaming alternatives.
Federal Communications Commission cross-ownership rules constrain consolidation between newspapers and broadcast stations in the same designated market area, while the Postal Regulatory Commission governs rate increases that directly affect print distribution costs. State-level public notice statutes in jurisdictions such as California and New York mandate newspaper publication for legal proceedings, preserving a residual revenue stream for print circulation. Publishers must monitor Postal Service reform legislation and evolving state public-notice digitization proposals to calibrate capital allocation between physical and digital infrastructure.
Market Dynamics
The US Newspaper Market confronts a structural compression between legacy print economics and digital subscription models, with the Postal Accountability and Enhancement Act fundamentally altering distribution cost structures for physical circulation.
Growth Catalysts
- State public-notice mandates:California and New York statutes require newspaper publication for legal proceedings, preserving residual revenue streams for print circulation.
- Texas and Florida population inflows:Metro subscriber bases in these states expand as domestic migration concentrates demand in Sun Belt markets.
- Hybrid advertising models:Local advertisers sustain cross-platform spending that values combined print-digital audience reach over single-channel alternatives.
Market Restraints
- Newsprint input cost volatility:Pulp price fluctuations and mill closures in North American supply chains compress margin structures for dailies above fifty thousand circulation.
- USPS Periodicals rate pressure:The Postal Regulatory Commission governs rate increases that directly escalate physical distribution costs for non-qualifying publishers.
- Digital-native substitutes:Social platforms and streaming services capture attention hours formerly allocated to investigative reporting and editorial content.
Strategic Opportunities
- Midwestern market consolidation:Dominant local news franchises in mid-size dailies retain pricing power where competition remains limited.
- Digital-first workflow convergence:Integration of AI-assisted content management with subscriber analytics platforms enables personalized paywall optimization.
- Podcast and newsletter channel innovation:Audio and email distribution formats attract younger demographics without legacy print infrastructure burdens.
Industry Challenges
- Investigative journalist talent scarcity:Specialized reporting skills command premium compensation that strained newsroom budgets struggle to absorb.
- Legacy CMS integration complexity:Migration from decades-old content management systems to modern digital stacks demands sustained capital deployment.
- FCC cross-ownership compliance timeline:Consolidation between newspapers and broadcast stations in the same designated market area faces regulatory friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Newspaper Market |
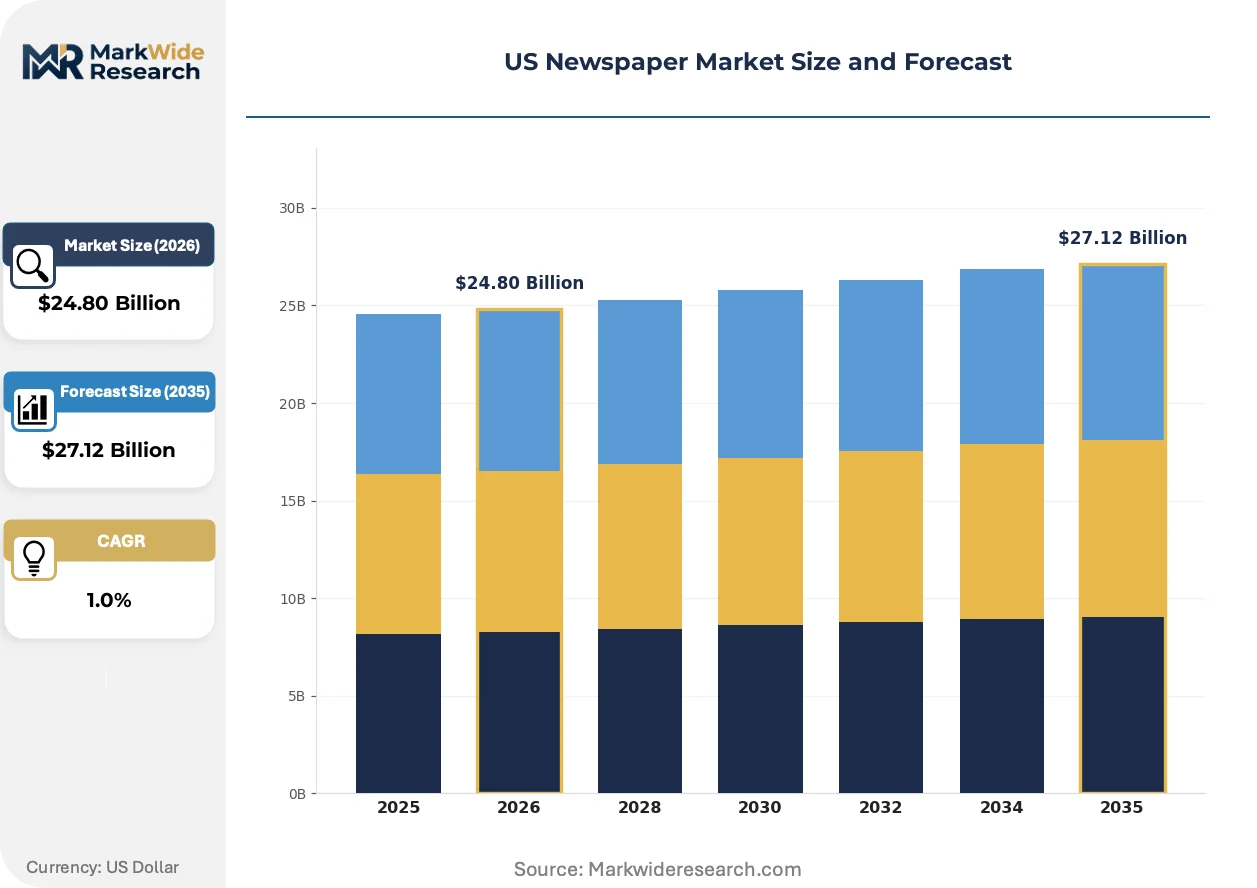
| Market Size in 2026 | $24.80 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Publication Type: Daily, Weekly, Sunday, Community Delivery Method: Print, Digital, Hybrid, Online Content Focus: Local News, National News, Sports, Lifestyle Customer Type: Subscribers, Advertisers, Researchers, Educators |
| Companies Covered | Chatham Asset Management, Advance Local Publications, Gannett Co., Inc., The New York Times Company, Tribune Publishing Company, Lee Enterprises, Hearst, News Corp, Alden Global Capital, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Newspaper Market Strategic Shifts & Innovations
Artificial intelligence tools and audience analytics platforms are actively restructuring how US publishers produce, distribute, and monetize editorial content across hybrid print-digital operations.
Generative AI content augmentation is fragmenting traditional newsroom workflows. Mid-size dailies deploy automated transcription and draft-generation tools to expand coverage volume without proportional headcount expansion. Publishers adopting these systems compress production timelines for breaking coverage while reallocating human journalists toward enterprise reporting.
The Postal Accountability and Enhancement Act continues reshaping distribution economics for physical circulation. Publishers who qualify for subsidized Periodicals rates sustain cost advantages over competitors pushed toward digital-only distribution. Texas and Florida metros see accelerated carrier-route optimization as publishers calibrate print frequency against postal cost structures.
Subscriber acquisition patterns are rotating toward platform-agnostic consumption habits. Younger demographics access local news through podcasts, newsletters, and social feeds rather than dedicated publisher apps or print delivery. Midwestern community publications respond by unbundling digital subscriptions into topic-specific vertical products.
US Newspaper Market Segmentation
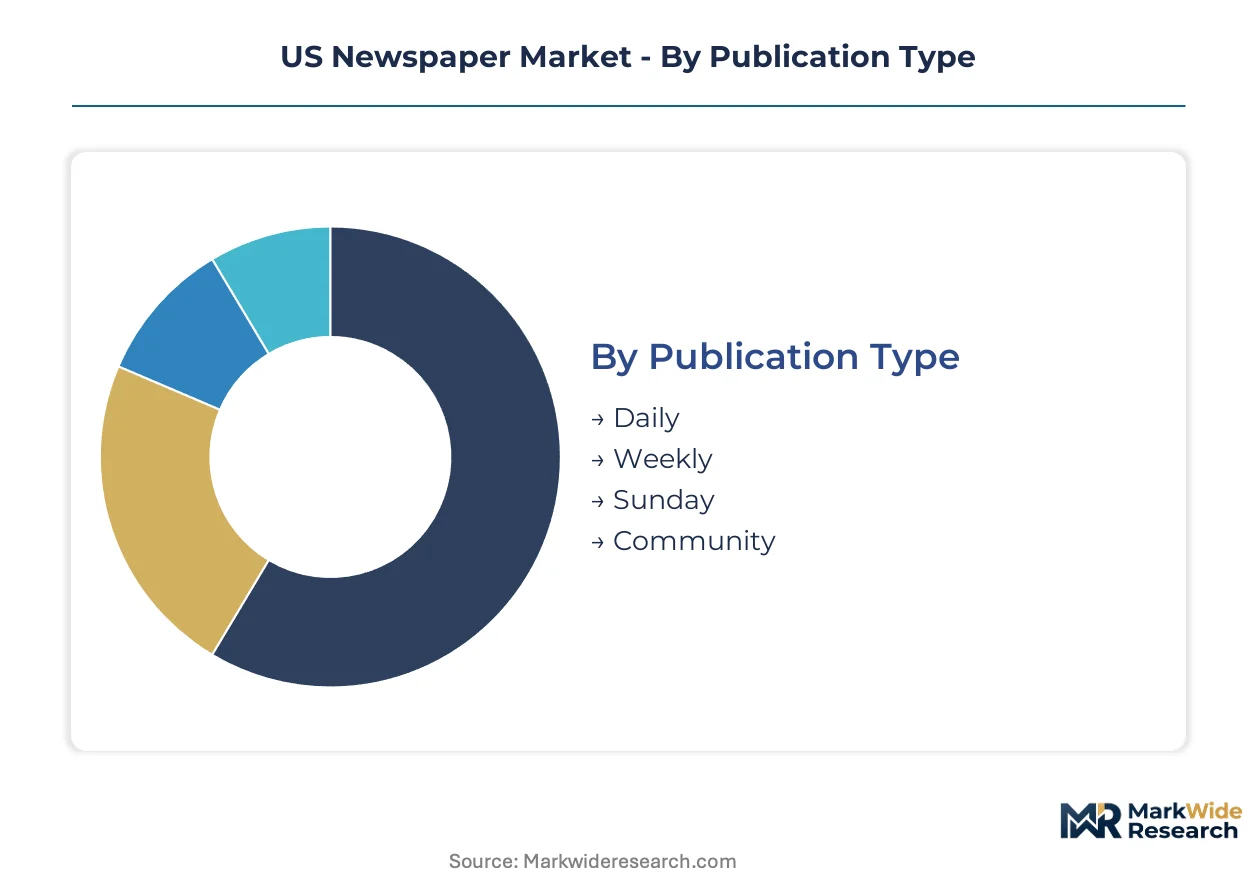
Segmentation in the US Newspaper Market reveals how revenue pools fragment across legacy and emerging formats. Publishers calibrate resource allocation differently across each dimension, with hybrid models capturing disproportionate advertiser investment.
Publication Type:
Daily publications command the highest absolute margins through premium advertising rates and established subscriber bases, while weekly formats optimize production economics through reduced frequency.
- Daily:Issued every weekday with investigative reporting and breaking news coverage. Demand concentrates in Texas and Florida metros where population inflows sustain circulation volumes against national headwinds.
- Weekly:Published once per week with community-focused coverage and event calendars. Mid-size Midwestern markets favor this format where dominant local franchises preserve pricing power through limited competition.
- Sunday:Weekend editions featuring expanded lifestyle sections and retail advertising inserts. The format retains value for national retailers targeting leisure-reading audiences.
- Community:Hyperlocal publications serving towns below fifty thousand residents. State public-notice mandates in California and New York preserve residual revenue streams for this segment.
The dominant share belongs to Daily, while Community is closing the gap fastest.
Delivery Method:
Cost structures diverge sharply between physical distribution networks and digital infrastructure, with hybrid models spreading fixed costs across both channels.
- Print:Physical newspapers distributed through carrier routes and postal delivery. USPS Periodicals rate pressure escalates distribution costs for non-qualifying publishers under Postal Regulatory Commission governance.
- Digital:Online editions accessed through publisher websites and mobile applications. Younger demographics drive expansion here through platform-agnostic consumption habits.
- Hybrid:Combined print-digital subscriptions offering cross-platform access. Local advertisers sustain spending here that values combined audience reach over single-channel alternatives.
- Online:Web-native content without corresponding print product. AI-assisted content management enables personalized paywall optimization for this segment.
Hybrid holds the revenue concentration, with Digital expanding most quickly.
Content Focus:
Application intensity varies by geographic market density, with local coverage commanding premium rates in underserved regions.
- Local News:Municipal government, school board, and community event coverage. Demand concentrates in Sun Belt metros where domestic migration creates subscriber base expansion.
- National News:Federal politics, international affairs, and economic policy reporting. This competes in a saturated attention economy against broadcast and streaming alternatives.
- Sports:Professional and collegiate athletics coverage with seasonal readership spikes. Regional loyalty drives subscription retention in markets with strong team affiliations.
- Lifestyle:Food, entertainment, and consumer culture content. Podcast and newsletter channel innovation attracts younger demographics here without legacy print infrastructure burdens.
Local News maintains the largest share, though Lifestyle is gaining share fastest.
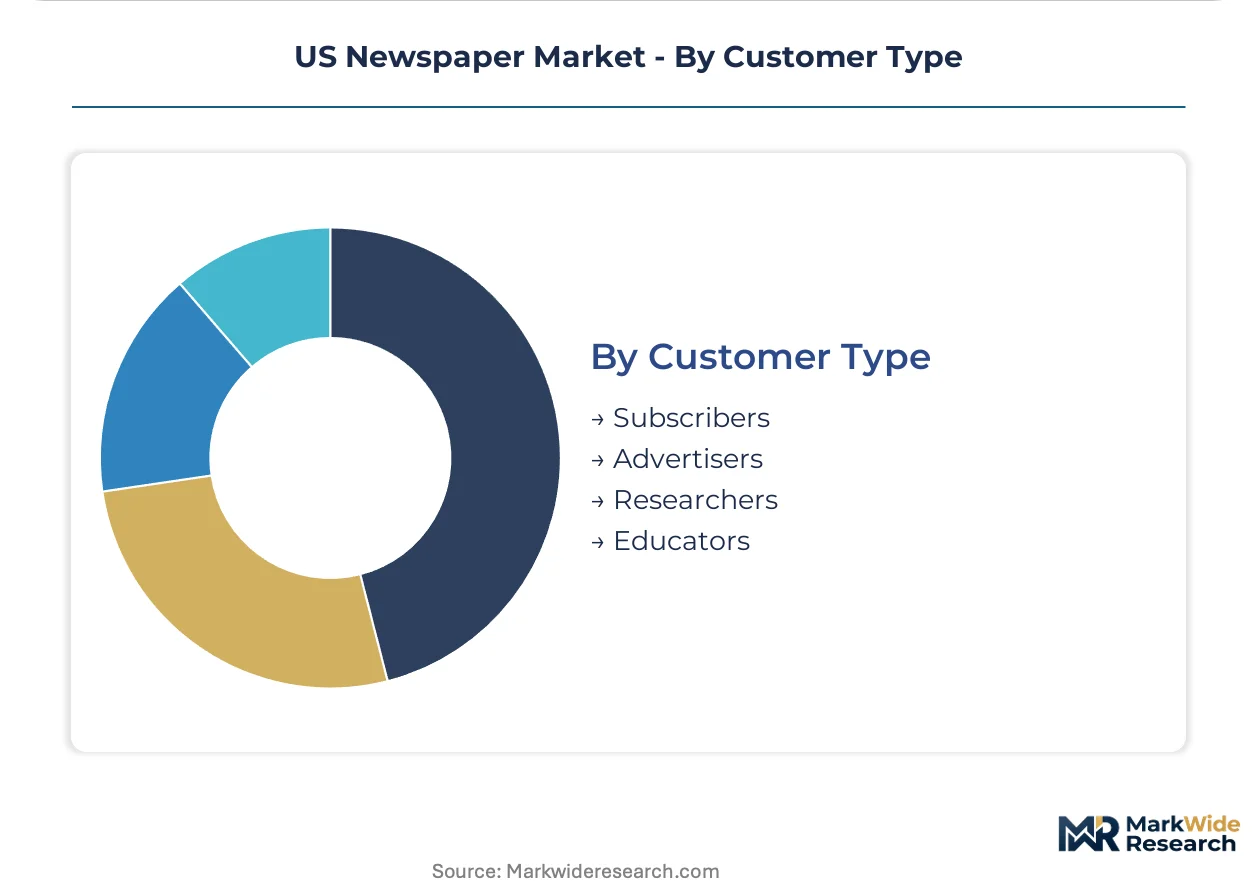
Customer Type:
Volume concentration sits with recurring revenue relationships, while marginal growth emerges from institutional contracts.
- Subscribers:Individual readers paying for recurring access to editorial content. Texas and Florida population inflows bolster these bases through domestic migration patterns.
- Advertisers:Commercial entities purchasing display and classified placement. Local advertisers sustain cross-platform spending that values combined print-digital audience reach.
- Researchers:Academic and institutional users accessing archival content. This segment supports premium pricing for historical database access.
- Educators:Schools and universities licensing content for classroom use. Curriculum integration requirements create sticky renewal patterns.
Subscribers represent the core revenue base, while Researchers show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Subscriber concentration tilts toward Sun Belt metros where domestic migration sustains circulation bases, while Midwestern markets retain dominant local franchises with limited competition. State-level public-notice mandates preserve residual revenue streams in select jurisdictions.
Texas
Houston and Dallas-Fort Worth metros absorb domestic migration inflows that expand subscriber bases for daily publications. The Texas Legislature maintains public-notice statutes requiring newspaper publication for legal proceedings, preserving print circulation revenue. Austin and San Antonio clusters see carrier-route optimization as publishers calibrate print frequency against postal cost structures.
Florida
Tampa and Orlando markets experience population-driven demand concentration from retiree and remote-worker migration patterns. State procurement rules sustain public-notice requirements for newspaper placement in government contracting. Miami-Dade and Broward counties anchor Spanish-language publication growth serving demographic shifts.
California
Los Angeles and San Francisco metros confront subscriber erosion amid high operational costs and digital-native competition. The California Government Code mandates newspaper publication for legal notices, creating protected revenue pools for surviving print operations. Sacramento and Central Valley publications leverage state capital proximity for government advertising contracts.
New York
New York City sustains national newsroom concentration despite metro circulation compression from digital substitution. New York State General Municipal Law preserves public-notice requirements for newspaper publication in legal proceedings. Albany and Hudson Valley dailies capture residual institutional advertising from state government operations.
Midwest
Chicago and Detroit metros retain dominant local news franchises where limited competition preserves pricing power for community publications. Illinois and Michigan public-notice statutes sustain residual print revenue streams for legal advertising. Minneapolis and Cleveland clusters see weekly format optimization as publishers reduce production frequency to manage newsprint input costs.
US Newspaper Market Key Industry Players
Player mix skews toward diversified media conglomerates with national scale advantages in postal negotiation and cross-platform advertising sales. The field segments into three strategic archetypes: national-scale publishers leveraging bulk-mailing contracts, premium digital-first operators reducing print dependence, and regional consolidators controlling mid-market franchises. Competitive moves concentrate on portfolio diversification through targeted asset acquisitions and technology licensing for subscriber analytics platforms.
Within the national-scale tier, Gannett Co., Inc. and The New York Times Company occupy distinct positioning vectors that exemplify divergent responses to postal economics restructuring. Lee Enterprises anchors the regional consolidator archetype with concentration in mid-size Midwestern markets. These three entities represent the primary competitive anchors shaping resource allocation patterns across print-digital hybrid operations.
| Leading Market Players |
|---|
| Chatham Asset Management |
| Advance Local Publications |
| Gannett Co., Inc. |
| The New York Times Company |
| Tribune Publishing Company |
| Lee Enterprises |
| Hearst |
| News Corp |
| Alden Global Capital |
| Others |
Cost & Logistics Intelligence
Long-term postal rate contracts with indexation to the Consumer Price Index lock in distribution cost visibility for qualifying publishers under USPS Periodicals class certification. These agreements tether print economics to federal pricing benchmarks while insulating volume-heavy operators from spot-rate volatility that squeezes non-qualifying competitors toward digital-only distribution.
Pricing Analysis
Cost-plus contracts with CPI indexation dominate subscription pricing for print circulation, anchoring annual rate adjustments to federal inflation metrics rather than demand elasticity. Price differentiation rests on geographic delivery density and volume scale, with metro dailies in Texas and Florida commanding premiums against rural weeklies. Pricing pressure intensifies downward as newsprint input costs spike and digital-native substitutes erode willingness-to-pay among younger demographics. Small-market community publications exhibit highest price sensitivity, while national-scale publishers with bulk-mailing contracts maintain lowest sensitivity due to postal cost absorption.
Supply Chain Analysis
Strategic newsprint stockpiling prevails among dailies above fifty thousand circulation, buffering against pulp mill closures and Canadian import disruptions that have compressed North American supply chains. Raw material sourcing concentrates in Canada, Finland, and the southeastern United States for mechanical pulp and recycled fiber inputs. Supply chain risk centers on single-source vulnerability for specialty-grade newsprint used in high-insert Sunday editions. Distribution runs through USPS Periodicals class for national reach, supplemented by contracted carrier routes for same-day metro delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Newspaper Market functions as a defensive-moat industry where state public-notice mandates create regulatory entrenchment that digital-native competitors cannot easily replicate. Switching costs for institutional advertisers and legal compliance departments preserve residual revenue pools for incumbent print operators.
For Market Incumbents: Fortify dominant local news franchises through targeted acquisitions of distressed mid-market dailies in Midwestern states where limited competition preserves pricing power. Deepen vertical integration into digital subscriber analytics platforms to offset postal rate pressure from the Postal Regulatory Commission. Prioritize certification for USPS Periodicals class rates to sustain cost advantages over digital-only rivals. For New Entrants and Emerging Players: FCC broadcast license fast-track programs offer regulatory pathways for cross-ownership consolidation in designated market areas where newspaper-broadcast combinations remain restricted. Target lifestyle and podcast verticals in Sun Belt metros where platform-agnostic consumption habits among younger demographics create white-space opportunities. Deploy newsletter-first go-to-market strategies that bypass legacy print infrastructure burdens entirely. For Investors and Strategic Acquirers: Capital is best deployed toward regional consolidators with concentrated mid-market franchises and established public-notice revenue streams across multiple state jurisdictions. Long-term viability hinges on successful digital subscription conversion rates and hybrid advertising model sustainability. Monitor Postal Service reform legislation as the primary inflection signal for capital reallocation between physical and digital infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Carrier-Route Optimization | Calibrating print frequency against USPS Periodicals rate structures preserves margin in Texas and Florida metros. |
| Digital-First Workflow Convergence | AI-assisted content management integration enables personalized paywall optimization for subscriber retention. |
| Podcast and Newsletter Channel Launch | Audio and email formats attract younger demographics without legacy newsprint and postal infrastructure burdens. |
| Midwestern Market Consolidation | Dominant local franchise acquisitions in limited-competition markets protect pricing power for community publications. |
| Public-Notice Revenue Defense | Lobbying against state digitization proposals in California and New York preserves protected legal advertising pools. |
Research Approach
Findings reconcile primary fieldwork against secondary review of USPS regulatory filings, Postal Regulatory Commission rate decisions, and state public-notice statute databases. Interviews with newspaper publishers, postal operations managers, and local advertising agency executives informed demand-side validation. SEC 10-K disclosures from publicly traded publishers and industry association circulation reports provided supply-side triangulation. Bottom-up subscriber volume estimates and top-down advertising revenue benchmarks were cross-referenced for convergence.
Segmentation dimensions modeled include publication frequency, delivery method hybridization, content focus verticals, and customer type across the projection horizon. Analytical frameworks incorporated postal economics restructuring, newsprint input cost trajectories, and domestic migration patterns into Sun Belt metros. CAGRs were derived from trend extrapolation of subscriber base evolution and advertising mix shifts, with sensitivity testing against digital substitution rates and regulatory change scenarios.
Underlying assumptions cover sustained USPS Periodicals class certification eligibility and stable state public-notice mandates, with deviation risk concentrated in postal reform legislation and newsprint mill closure cascades. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Publishing
Japan Catalog Market
Digital Publishing
Children Illustration Book Market
Digital Publishing
Book Publishers Market
Digital Publishing
Middle East Catalog Market
Digital Publishing
News and Magazines App Market
Digital Publishing
Digital Comics Platform Market
Digital Publishing
Books Market
Digital Publishing
Mexico Commercial Printing Market
Digital Publishing
China Catalog Market
Digital Publishing
Digital Music Publishing Market
Digital Publishing
Editor App Market
Digital Publishing
France Catalog Market
Digital Publishing
Digital Newspapers and Magazines Market
Digital Publishing
Global E-Book Market
Digital Publishing
Adaptive Content Publishing Market
Digital Publishing
Digital Reading Market