
 Digital Music Publishing Market | 2026-2036
Digital Music Publishing Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Music Publishing Market Insights
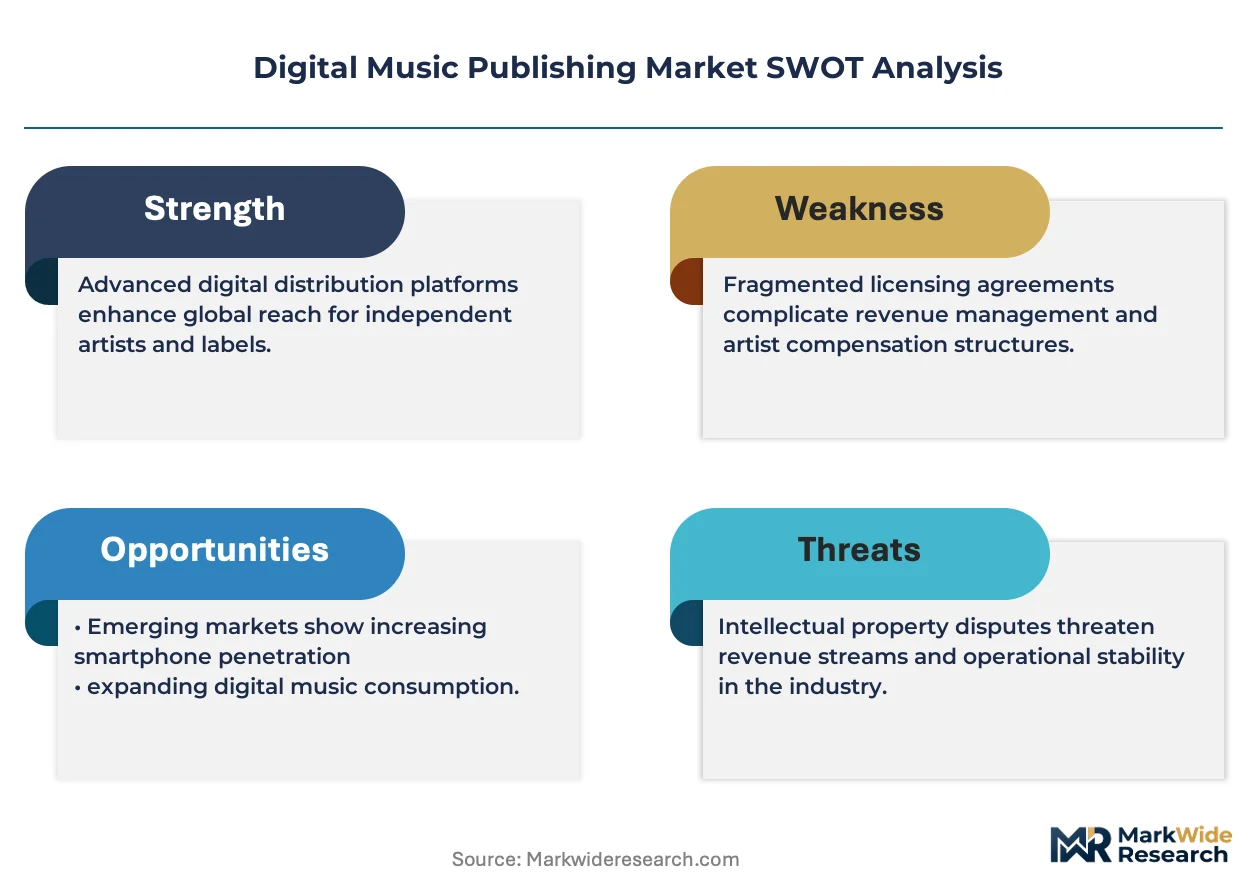
Subscription bundling with video and gaming services is consolidating buyer choice around all-access entertainment packages. Sony Music Publishing leverages its extensive catalog to anchor premium bundle negotiations with streaming platforms. Universal Music Publishing Group sustains global reach through direct licensing deals across multiple territories. Warner Chappell Music differentiates via specialized film and television synchronization services.
Digital music publishing encompasses the administration, licensing, and royalty collection for musical compositions distributed through electronic channels, operating on metadata-driven rights management systems that track usage across billions of streams. The practice generates revenue for songwriters and publishers through performance, mechanical, and synchronization rights administered via automated platforms. Streaming platforms dominate distribution channel revenue, while synchronization fees from advertising and film represent the fastest-expanding royalty category. Performance royalties retain the largest volume share, though mechanical royalties are accelerating with the shift from download-to-streaming models.
The U.S. Copyright Office oversees statutory licensing rates that directly determine publisher revenue from digital radio and interactive streaming. The EU Copyright Directive and its national implementations across France, Germany, and Italy mandate platform liability, forcing renegotiation of value transfer mechanisms. The U.S. Music Modernization Act established the Mechanical Licensing Collective, centralizing digital mechanical royalty administration. Stakeholders must monitor evolving safe-harbor interpretations and direct licensing trends that will determine whether statutory frameworks or bilateral negotiations shape future publisher economics.
Market Dynamics
Platform licensing mandates under the EU Copyright Directive's Article 17 are forcing renegotiation of value transfer mechanisms between streaming services and rights holders, compressing legacy safe-harbor protections while elevating direct licensing economics.
Growth Catalysts
- Subscription bundling:Video and gaming service consolidation is anchoring all-access entertainment packages that bundle music publishing rights into multi-product consumer contracts.
- EU Copyright Directive Article 17:Platform liability mandates across France, Germany, and Italy are compelling renegotiation of licensing terms and redirecting revenue flows toward publishers.
- Synchronization rights:Advertising and film licensing fees are expanding as streaming content production volumes accelerate demand for composition clearance.
Market Restraints
- Statutory rate compression:U.S. Copyright Office determinations on mechanical and performance rates cap upside for publishers in terrestrial and digital radio segments.
- Metadata fragmentation:Inconsistent composition identification standards across DSPs generate unclaimed royalties and audit disputes that erode net collections.
- Platform concentration:Dominance of three major streaming services in the United States creates asymmetric bargaining power in direct licensing negotiations.
Strategic Opportunities
- India market penetration:Low streaming ARPU is offset by volume scale and emerging platform competition creating first-mover advantage for localized repertoire investment.
- Blockchain royalty tracking:Distributed ledger technologies are converging with smart contracts to enable real-time, transparent rights administration and micro-payment distribution.
- Federal tax incentives:The U.S. Inflation Reduction Act's cultural production credits are expanding film and television synchronization demand in domestic content hubs.
Industry Challenges
- Black box royalty recovery:Unmatched composition claims across billions of streams require specialized data science capabilities that publishers must build or acquire.
- Legacy system integration:Migration from PRO-administered performance royalties to the Mechanical Licensing Collective's centralized platform demands costly IT infrastructure overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Music Publishing Market |
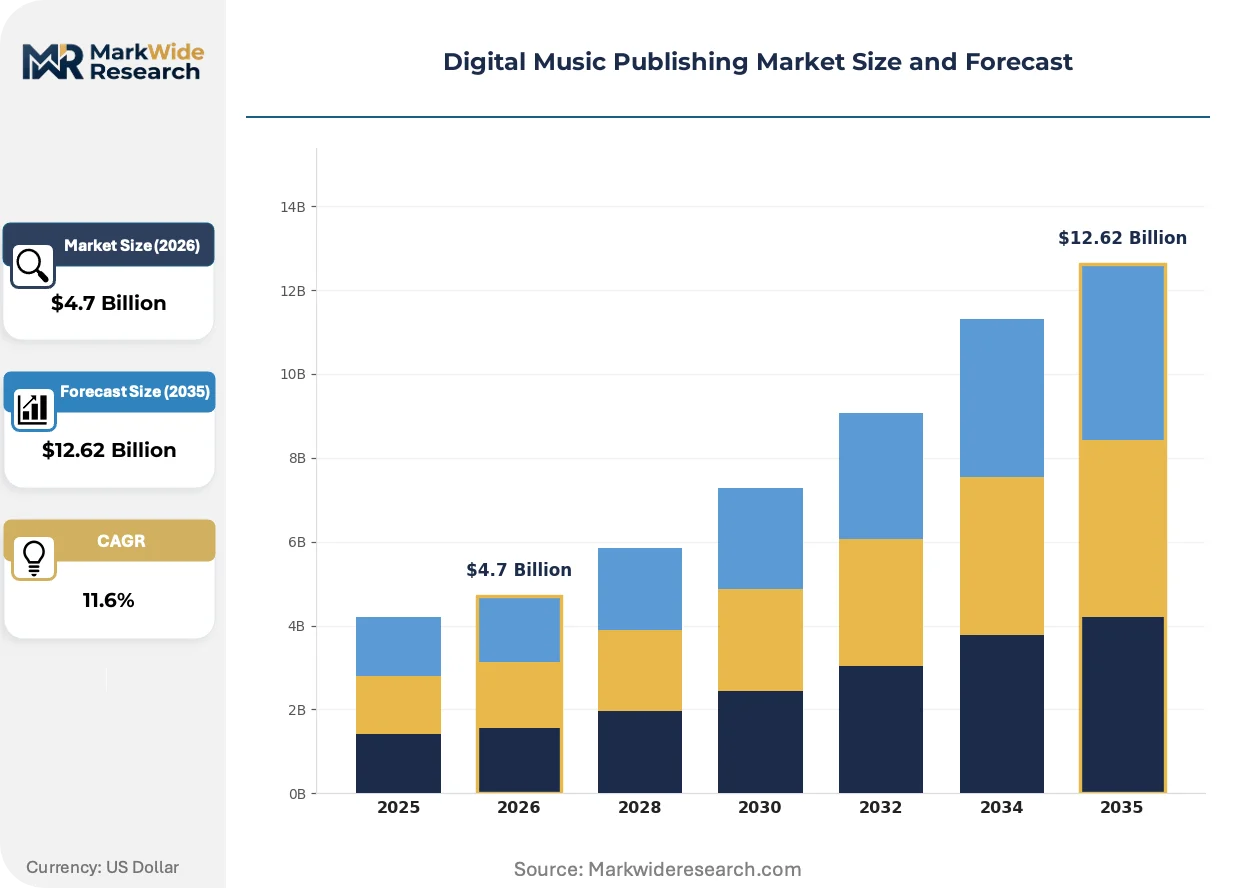
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $12.62 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Content Type: Original Songs, Cover Songs, Remixes, Instrumentals Distribution Channel: Streaming Platforms, Digital Downloads, Licensing Agreements, Broadcast Media Royalties Type: Performance Royalties, Mechanical Royalties, Synchronization Fees, Print Rights Target Audience: Independent Artists, Record Labels, Music Publishers, Advertising Agencies |
| Companies Covered | Sony Music Publishing, Universal Music Publishing Group, Warner Chappell Music, Kobalt Music Group, BMG Rights Management, Concord Music Publishing, Reservoir Media, Round Hill Music, Peermusic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Music Publishing Market Trends and Innovations
Metadata-driven rights administration systems are displacing manual clearance processes across the publishing value chain, enabling real-time tracking of composition usage while compressing the latency between consumption and royalty distribution.
Artificial intelligence-powered content identification is automating the matching of unclaimed streams to rights holders across DSP catalogs. Major publishers are deploying these systems to reduce black box exposure. The technology is automating previously manual audit processes that required human review of millions of monthly usage reports.
The U.S. Music Modernization Act established the Mechanical Licensing Collective as a statutory administrator, centralizing digital mechanical royalty distribution and displacing the prior patchwork of vendor-administered licenses. Publishers are adapting operational workflows to interface with this federal entity. Independent songwriters face the steepest adjustment curve in registering works with the new centralized database.
Buyer procurement is compressing toward direct licensing negotiations that bypass traditional performing rights organizations for digital performance royalties. Streaming platforms prefer bilateral deals that offer rate certainty and global repertoire access. This pattern is most pronounced in the United States, where major publishers have withdrawn certain digital rights from PRO administration.
Digital Music Publishing Market Segmentation
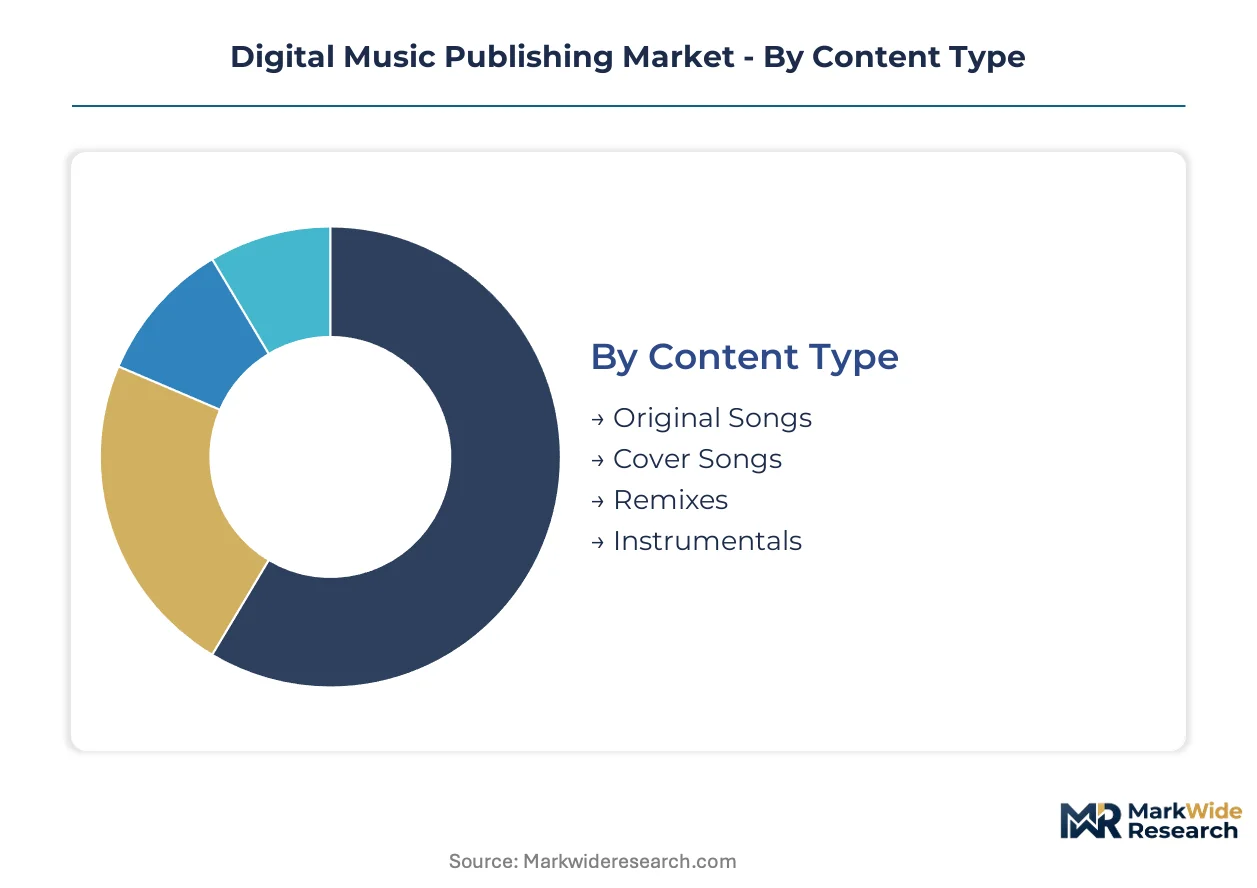
Rights administration complexity varies sharply across composition types and distribution channels. Publishers allocate catalog acquisition budgets based on royalty yield differentials between streaming and synchronization revenue streams.
Content Type:
Supply concentration in hit-driven catalogs tilts investment toward original repertoire with proven streaming velocity.
- Original Songs:Unpublished compositions generate the highest per-stream mechanical rates and anchor premium synchronization negotiations. Demand concentrates in the United States where major publishers withdraw digital performance rights from PRO administration to secure direct licensing premiums.
- Cover Songs:Compulsory licensing frameworks under U.S. Copyright Act Section 115 cap mechanical rates at statutory levels, compressing publisher margins. Demand clusters in user-generated content platforms where clearance volume offsets rate limitations.
- Remixes:Derivative works require dual clearance from both original and new composition rights holders, multiplying administrative overhead.
- Instrumentals:Stripped compositions command lower synchronization fees but accelerate clearance timelines for advertising placements.
Original songs absorb the bulk of installed capacity; cover songs are expanding most quickly via UGC platform proliferation.
Distribution Channel:
Cost tier differentiation separates high-touch licensing operations from automated streaming administration.
- Streaming Platforms:Interactive audio services generate mechanical and performance royalties through billions of monthly transactions. Demand concentrates with three dominant U.S. services that negotiate direct publisher deals, bypassing statutory rate structures where possible.
- Digital Downloads:Declining transaction volumes persist in niche classical and specialty catalog segments. Demand fragments across legacy iTunes holdouts and Bandcamp direct-to-fan operations.
- Licensing Agreements:Bespoke synchronization and performance contracts yield the highest per-use revenue. Demand clusters in film production hubs where clearance speed determines competitive positioning.
- Broadcast Media:Terrestrial radio and television maintain PRO-administered blanket licenses with rate court oversight constraining upside.
Streaming platforms absorb the bulk of installed capacity; licensing agreements represent the steepest expansion trajectory.
Royalties Type:
Application-driven revenue allocation shifts publisher resources toward synchronization as streaming mechanical rates face statutory compression.
- Performance Royalties:Public performance of compositions generates blanket license revenue through ASCAP, BMI, and SESAC in the United States. Demand concentrates in live music recovery and fitness streaming verticals post-pandemic.
- Mechanical Royalties:Reproduction and distribution rights now flow through the Mechanical Licensing Collective under U.S. Music Modernization Act mandates. Demand accelerates with streaming volume even as per-stream rates face regulatory caps.
- Synchronization Fees:Composition licensing for film, television, advertising, and gaming delivers the highest margin revenue. Demand surges with streaming content production volumes from Netflix, Disney+, and Amazon Prime Video.
- Print Rights:Sheet music and folio licensing retains niche revenue from educational and worship segments.
Performance royalties absorb the bulk of installed capacity; synchronization fees are gaining share fastest.
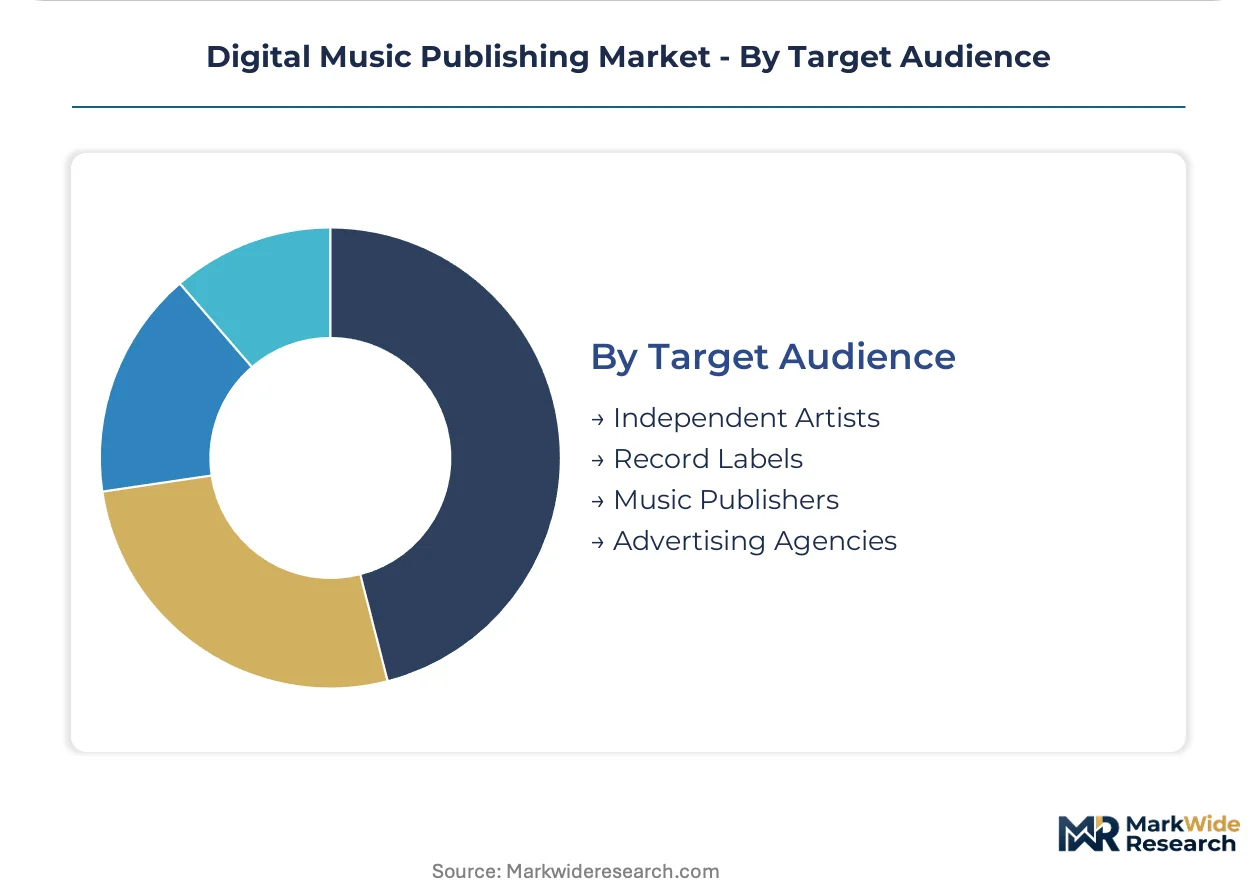
Target Audience:
Customer type determines service intensity and technology investment levels across the publisher value chain.
- Independent Artists:Unaffiliated songwriters require administrative services for global royalty collection. Demand concentrates in Nashville, Los Angeles, and New York where creator tools and DIY distribution platforms reduce barrier to entry.
- Record Labels:Sound recording owners seek bundled composition clearance to streamline release logistics. Demand clusters in major label systems with dedicated publishing affiliates.
- Music Publishers:Catalog administrators and acquiring entities require data science capabilities for black box royalty recovery.
- Advertising Agencies:Creative shops demand rapid clearance turnaround for campaign production timelines.
Record labels absorb the bulk of installed capacity; independent artists are expanding most quickly via creator economy platform growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-level production tax credits in Georgia and California are concentrating film and television synchronization work, drawing music publishers to establish dedicated clearance operations in these incentive zones.
United States
The Mechanical Licensing Collective administers digital mechanical royalties under Music Modernization Act mandates, streamlining collections across streaming platforms. Nashville, Los Angeles, and New York anchor publisher operations where major players negotiate direct licensing deals with Spotify, Apple Music, and Amazon Music, bypassing traditional PRO structures for digital performance rights.
United Kingdom
London's concentration of advertising agencies and post-production houses drives synchronization demand for commercial placements. The UK Intellectual Property Office oversees copyright frameworks while the city hosts satellite offices for all three major publishers, positioning the capital as Europe's primary hub for bespoke licensing negotiations outside EU regulatory jurisdiction post-Brexit.
Germany
Article 17 implementation through the German Copyright Service Providers Act imposes direct licensing obligations on platforms, reshaping revenue flows toward publishers. Berlin and Hamburg cluster independent publisher operations and collection society GEMA's administrative infrastructure, with the former city emerging as a center for electronic music catalog administration.
France
The French implementation of Article 17 via the Law on the Protection of Copyright on the Internet mandates platform liability, compelling renegotiation of value transfer mechanisms. Paris concentrates SACEM's operations alongside major publisher affiliates, with the city serving as the primary gateway for Francophone repertoire licensing across European and African markets.
India
Low streaming ARPU is offset by volume scale across JioSaavn, Gaana, and Spotify India, creating first-mover advantage for localized repertoire investment. Mumbai anchors Bollywood-focused publishing operations while the Indian Performing Right Society administers performance royalties, with the city emerging as the regional hub for film synchronization clearances.
Digital Music Publishing Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the digital music publishing value chain. The market structure tilts toward consolidation at the top tier, with three major publishers commanding disproportionate catalog scale and direct licensing leverage. Strategic archetypes include vertically integrated entertainment conglomerates, technology-enabled independent administrators, and specialized synchronization boutiques. Competitive dynamics center on catalog acquisition velocity and proprietary data science capabilities for black box royalty recovery.
Within the major conglomerate tier, Sony Music Publishing, Universal Music Publishing Group, and Warner Chappell Music exemplify scale-driven positioning through extensive historical catalogs and direct platform negotiations. These entities represent the archetype of diversified entertainment holdings leveraging cross-media synergies. Among technology-focused independents, Kobalt Music Group occupies a position emphasizing transparent royalty administration and creator-facing platforms. BMG Rights Management anchors the European-centered independent model, exemplifying private-equity-backed catalog consolidation strategies.
| Leading Market Players |
|---|
| Sony Music Publishing |
| Universal Music Publishing Group |
| Warner Chappell Music |
| Kobalt Music Group |
| BMG Rights Management |
| Concord Music Publishing |
| Reservoir Media |
| Round Hill Music |
| Peermusic |
| Others |
Pricing and Supply Chain Analysis
Catalog-tier divergence between hit-driven premium repertoires and long-tail commodity compositions manifests in both pricing power and supply chain configurations, with major publishers commanding direct licensing premiums while independent administrators compete on clearance velocity and metadata accuracy. The bifurcation reshapes where investment concentrates and which operational capabilities determine margin capture.
Pricing Analysis
Short lead-time premiums for rapid synchronization clearances command three-to-five-fold markups over standard licensing timelines in film and television production hubs. Three-tier pricing structure across premium, standard, and economy levels reflects clearance speed, exclusivity terms, and territorial scope. Pricing pressure stems from statutory rate caps on mechanical royalties administered by the Mechanical Licensing Collective. Independent songwriters exhibit highest price sensitivity, while streaming platforms demonstrate lowest sensitivity given bundled repertoire access requirements.
Supply Chain Analysis
Dual-sourcing requirements for composition rights mandate that streaming platforms maintain licensing relationships with multiple publishers to ensure global repertoire coverage and negotiation leverage. Supply concentrates in the United States, United Kingdom, and Germany where major publishers anchor direct licensing operations. Raw material dependencies include proprietary metadata systems, black box recovery algorithms, and PRO database integrations. Single-source vulnerability exists where platforms rely on exclusive catalog holdings for differentiated consumer offerings. Distribution runs through centralized rights administration platforms interfacing with DSP ingestion pipelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital music publishing market sits in a technology-transition phase where artificial intelligence-powered content identification systems displace manual audit processes and reshape competitive economics.
For Market Incumbents: Extend proprietary data science capabilities for black box royalty recovery to defend against technology-enabled independent administrators. Deepen direct licensing relationships with streaming platforms to secure rate certainty and global repertoire access. The threat of AI-powered matching systems commoditizing traditional clearance services demands accelerated investment in real-time rights tracking infrastructure. For New Entrants and Emerging Players: The EU Copyright Directive Article 17 implementation across France, Germany, and Italy opens a window for specialized synchronization boutiques to capture value transfer renegotiations. White-space targets include India market penetration with localized repertoire investment and blockchain-enabled micro-payment distribution for independent artist segments. The most penetrable geography is India, where low streaming ARPU and volume scale create first-mover advantage for platforms offering transparent royalty administration. For Investors and Strategic Acquirers: Exit pathways concentrate in private-equity-backed catalog consolidation and strategic acquisition by diversified entertainment conglomerates seeking cross-media synergies. Long-term viability hinges on proprietary data science capabilities and direct licensing leverage rather than PRO-administered revenue streams. The signal to watch is withdrawal rates of digital performance rights from PRO administration by major publishers, indicating accelerating bilateral negotiation trends. Deviation in safe-harbor interpretations by courts or regulators would shift acquisition valuations materially.| Strategic Initiative | Industry Significance |
|---|---|
| Catalog Acquisition Velocity | Major publishers like Sony Music Publishing anchor premium bundle negotiations through extensive historical holdings. |
| AI-Powered Content Identification | Automated matching systems reduce black box exposure and compress latency between consumption and royalty distribution. |
| Direct Licensing Expansion | Bilateral deals with Spotify, Apple Music, and Amazon Music bypass statutory rate structures and secure rate certainty. |
| Blockchain Royalty Tracking | Distributed ledger technologies enable real-time, transparent rights administration and micro-payment distribution for independent creators. |
| Synchronization Specialization | Warner Chappell Music differentiates via dedicated film and television clearance operations in production tax credit zones. |
Research Methodology
Independent corroboration across publisher financial disclosures, streaming platform regulatory filings, and collection society distribution reports underwrites the qualitative findings in this study. Primary interviews with rights administration executives, synchronization licensing directors, and independent songwriter advocates combined with secondary validation from U.S. Copyright Office rate determinations, EU national implementation texts of Article 17, and Mechanical Licensing Collective public data releases. Bottom-up and top-down triangulation cross-checks segment-level revenue allocations against aggregate market sizing.
Rate-of-change decomposition across the projection horizon separates volume growth in streaming consumption from yield compression in per-stream mechanical rates and expansion in synchronization fee premiums. Segmentation dimensions modeled include content type, distribution channel, royalty category, and target audience archetype. CAGRs derive from regression analysis of historical streaming volume trajectories, statutory rate adjustment schedules, and content production spending patterns from major streaming video platforms.
The model assumes a particular technology adoption path; alternative pathways for blockchain-based royalty distribution would alter the outlook for intermediary disintermediation and black box recovery economics. Forecasts reflect assumptions regarding Article 17 enforcement consistency across EU member states and Mechanical Licensing Collective operational maturation. Deviation in platform licensing mandate interpretations by national courts would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Publishing
Europe E-Book Market
Digital Publishing
China Catalog Market
Digital Publishing
Africa Catalog Market
Digital Publishing
Mexico Commercial Printing Market
Digital Publishing
Ebook Publishing Platform Market
Digital Publishing
Digital Comics Market
Digital Publishing
Digital Reading Market
Digital Publishing
Global E-Book Market
Digital Publishing
Digital Comics Platform Market
Digital Publishing
Children Illustration Book Market
Digital Publishing
Editor App Market
Digital Publishing
Books Market
Digital Publishing
Comic Book Market
Digital Publishing
GCC Commercial Printing Market
Digital Publishing
France Catalog Market
Digital Publishing
Newspaper Market