
 Comic Book Market | 2026-2036
Comic Book Market Size, Share, and Industry Trends Forecast 2026-2036
Comic Book Market Analysis
North American independent publishers is recalibrating output schedules as paper costs and print logistics strain fulfillment networks. Image Comics leverages creator-owned rights models to sustain talent attraction against corporate-owned competitors. Dark Horse Comics anchors its position through licensed property adaptations that extend into gaming and streaming. BOOM! Studios differentiates via younger-skewing original content that competes with established superhero franchises.
A comic book is a sequential art publication combining illustrated panels with narrative text, typically printed on coated stock between 20 and 64 pages or bound as longer-form graphic novels exceeding 120 pages, designed for entertainment consumption and collectible preservation. Its commercial purpose spans direct reader engagement, speculative investment, and intellectual property seeding for cross-media exploitation. Graphic novels command the highest margin pools as bookstore and library buyers consolidate purchases around bound volumes, while digital comics represent the fastest-expanding access channel as subscription platforms reduce per-title friction. Manga dominates volume throughput through translated weekly serialization, though independent titles capture disproportionate critical prestige that drives award recognition and film optioning.
The US Federal Trade Commission monitors collectible marketing claims to prevent misrepresentation of print runs and investment value, while the EU's Digital Services Act imposes transparency obligations on online platforms distributing comics to minors. Japan's Ministry of Economy, Trade and Industry promotes manga as cultural export through trade fair participation and copyright enforcement support. Stakeholders must weigh creator royalty structures against platform exclusivity terms as digital distribution reconfigures who controls reader relationships and derivative revenue streams.
Market Dynamics
Digital-first distribution is fragmenting reader relationships away from traditional direct-market comic shops, forcing publishers to rebuild audience access through platform intermediaries and subscription infrastructure.
Growth Catalysts
- Mobile serialization platforms:Smartphone-native distribution reaches casual readers who bypass physical retail entirely, converting non-traditional demographics into recurring subscribers.
- EU Digital Services Act transparency mandates:Platform accountability rules reduce algorithmic opacity, enabling smaller publishers to compete for discovery visibility against catalog-dominant incumbents.
- Manga export infrastructure:Japan's METI-backed copyright enforcement and trade fair participation accelerates licensed translation pipelines, opening bookstore and library channels in target markets.
Market Restraints
- Coated paper cost volatility:Print fulfillment networks face margin compression as pulp and freight inputs fluctuate, squeezing independent publishers with limited volume leverage.
- Platform dependency concentration:Digital distribution gatekeepers control reader data and recommendation algorithms, extracting revenue share terms that erode creator royalty pools.
- Weekly serialization labor intensity:Manga production schedules demand sustained artist output with limited automation, creating burnout-driven talent attrition that disrupts title continuity.
Strategic Opportunities
- Library and educational procurement:Graphic novel consolidation in institutional buyers creates stable volume contracts for bound editions with extended payment cycles.
- Gaming and streaming adaptation pipelines:Cross-media IP exploitation extends revenue lifecycles through licensed derivative production, capturing audiences outside core comic readership.
- Webtoon vertical-scroll format:Smartphone-optimized panel design reduces production costs while expanding addressable markets in Southeast Asia and Latin America.
Industry Challenges
- Creator rights negotiation complexity:Work-for-hire contracts versus creator-owned models create legal friction in talent acquisition, particularly for established franchises with derivative revenue potential.
- Print-to-digital inventory reconciliation:Direct market distributors struggle to align physical pre-order systems with real-time digital release schedules, generating channel conflict and return liability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Comic Book Market |
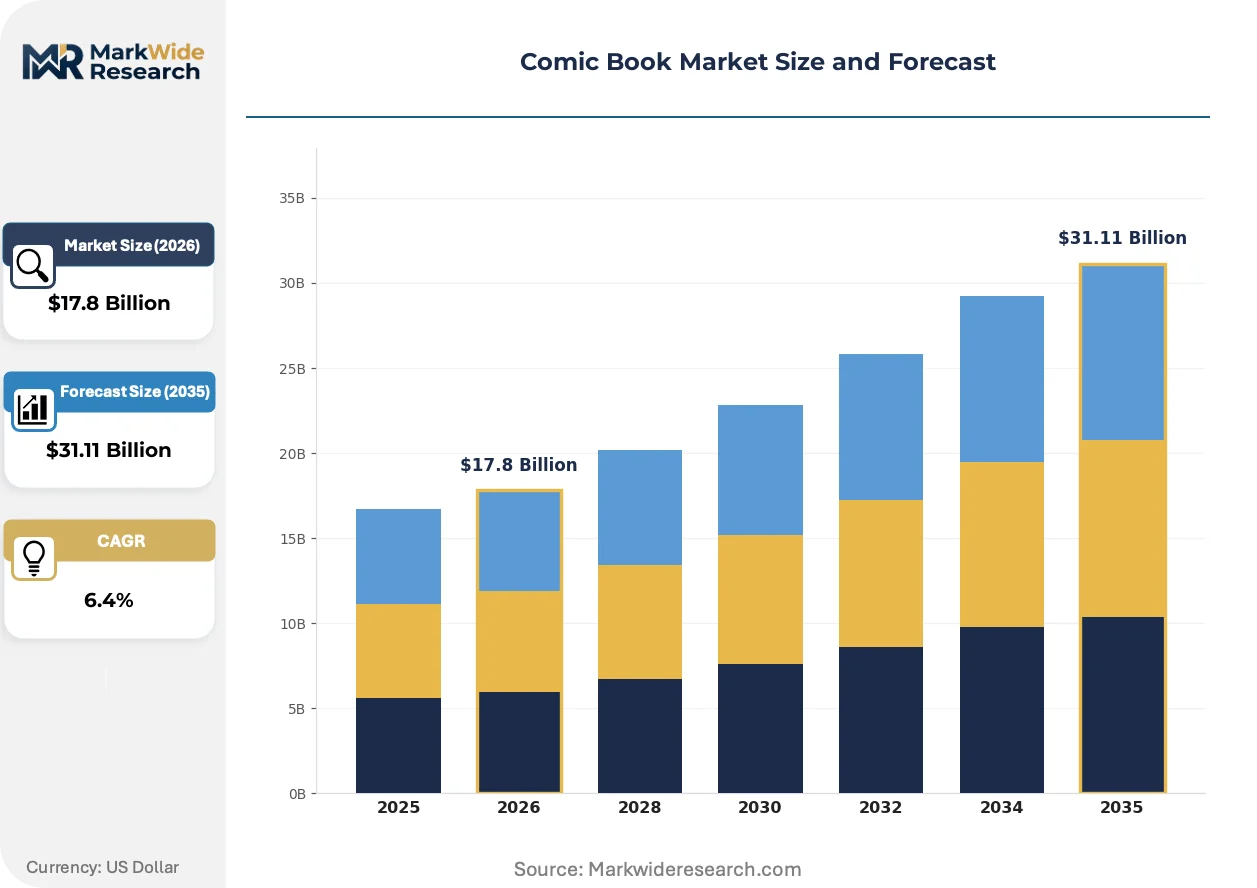
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $31.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Graphic Novels, Manga, Superhero, Independent Distribution Channel: Retail Stores, Online Platforms, Comic Shops, Direct Sales Customer Type: Collectors, Casual Readers, Retailers, Libraries Market Segment: Digital Comics, Print Comics, Merchandise, Cross-media Adaptations |
| Companies Covered | BOOM! Studios, Fantagraphics Books, Image Comics, Antarctic Press, Vault Comics, Dark Horse Comics, Oni Press, Iron Circus Comics, IDW Publishing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Comic Book Market Emerging Trajectories
Format experimentation and platform-native production methods are redefining how sequential art reaches audiences, compressing traditional publishing timelines while expanding access points.
AI-assisted coloring and lettering tools are expanding into mid-tier publisher workflows, reducing per-page production costs for titles with tight serialization deadlines. Freelance artists adopt these tools to maintain output volume without expanding studio headcount. The structural consequence is a compression of entry barriers for new publishers, flooding digital platforms with competing content that strains discovery algorithms.
Japan's METI promotes manga as cultural export through coordinated copyright enforcement and trade fair participation, reshaping how international licensing negotiations proceed. Publishers in target markets must now navigate bilateral agreements that standardize royalty structures and limit gray-market scanlation competition. European and North American distributors respond by building dedicated manga editorial teams to accelerate translation turnaround.
Collector behavior is shifting from speculative investment toward consumption-oriented access, with subscription platforms displacing single-issue accumulation as the dominant engagement mode. Younger demographics prioritize completion and community discussion over physical preservation, redirecting spending toward digital libraries and event-based merchandise. This pattern concentrates in urban markets where storage constraints and housing costs discourage accumulation.
Comic Book Market Segmentation
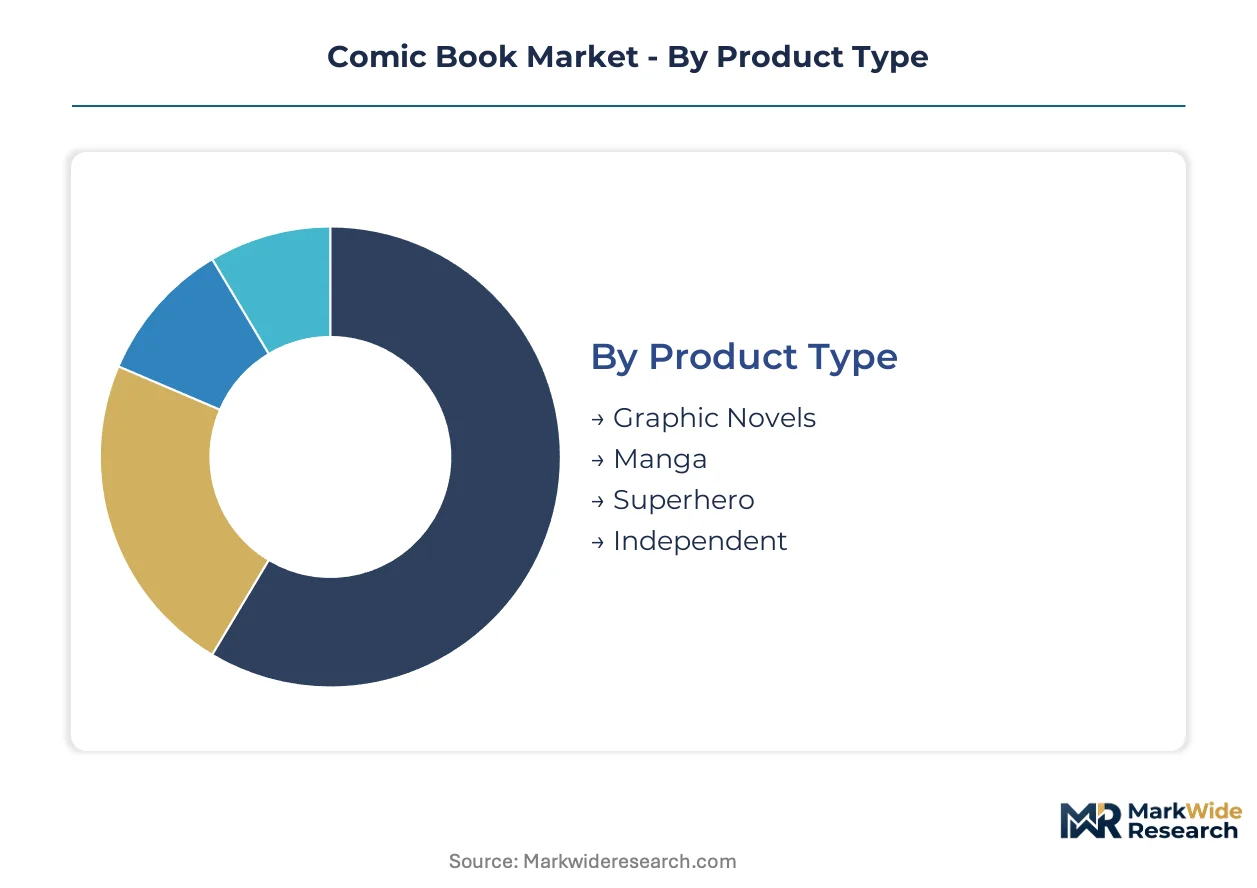
Segmentation in the comic book market reveals how format preferences, access channels, and buyer motivations split revenue pools across divergent business models. Publishers calibrate production investments and royalty structures differently for each slice, while platform algorithms and institutional procurement create distinct competitive arenas.
Product Type:
FTC collectible marketing guidelines apply most stringently to limited-run variants targeting speculative buyers, while Japanese METI export frameworks govern manga content classification for international licensing.
- Graphic Novels:Bound volumes exceeding 120 pages on coated stock command premium unit economics through bookstore and library procurement channels. Demand clusters in North American educational institutions consolidating purchases around curated lists, though margin pressure from return policies and extended payment cycles constrains independent publishers.
- Manga:Weekly serialized pamphlets and collected tankobon volumes dominate volume throughput through translated pipelines. Japan's METI-backed copyright enforcement accelerates licensed distribution while limiting gray-market scanlation competition in target export markets.
- Superhero:Corporate-owned franchise properties with decades of continuity maintenance.
- Independent:Creator-owned titles with film optioning and award recognition potential.
Leading the category by volume: Manga. Growing fastest: Graphic Novels.
Distribution Channel:
Cost tier separation runs deepest here, with physical retail carrying fixed overhead burdens against digital platforms' variable revenue-share economics.
- Online Platforms:Subscription infrastructure and smartphone-native serialization reduce per-title friction for casual readers who bypass physical retail entirely. EU Digital Services Act transparency mandates reshape algorithmic discovery rules, enabling smaller publishers to compete for visibility against catalog-dominant incumbents.
- Comic Shops:Direct-market specialty retailers with pull-list pre-order systems and community event programming. Concentrated in urban clusters where collector culture sustains weekly release traffic, though paper cost volatility and freight logistics squeeze margin structures.
- Retail Stores:Mass-market bookstores and big-box chains with graphic novel placement.
- Direct Sales:Publisher-controlled storefronts and convention circuit transactions.
Volume concentrates in Online Platforms. Steepest expansion trajectory: Comic Shops in secondary cities.
Customer Type:
Application logic separates preservation-oriented accumulation from access-oriented consumption, with each buyer type demanding different format and pricing configurations.
- Libraries:Institutional procurement of bound editions creates stable volume contracts with extended payment cycles. Demand concentrates in North American public and school systems where graphic novel consolidation supports diverse reader programming and literacy initiatives.
- Collectors:Speculative investors and completionists prioritizing variant covers, graded slabs, and limited print runs. Younger demographics are shifting this segment toward digital libraries and event-based merchandise as storage constraints in urban markets discourage physical accumulation.
- Casual Readers:Smartphone-native subscribers prioritizing completion and community discussion.
- Retailers:Intermediary buyers managing inventory risk and return liability across channels.
Revenue leadership: Libraries in institutional contracting. Climbing the fastest: Casual Readers through mobile conversion.
Market Segment:
Maturity differentiation separates established print formats from emerging digital-native production methods and derivative exploitation pipelines.
- Digital Comics:Subscription platforms and webtoon vertical-scroll formats reach casual readers in Southeast Asia and Latin America. AI-assisted coloring tools compress per-page production costs for mid-tier publishers, though platform dependency concentrates reader data control with distribution gatekeepers.
- Cross-media Adaptations:Gaming and streaming derivative production extends revenue lifecycles beyond core comic readership. Licensed property pipelines anchor publisher strategies, with Dark Horse Comics and similar players leveraging adaptation rights to sustain talent attraction.
- Print Comics:Single-issue pamphlets and periodical serialization in direct-market channels.
- Merchandise:Event-based collectibles and character-licensed consumer products.
Gaining share fastest: Digital Comics. Margin leadership: Cross-media Adaptations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's coated paper mills supply the substrate backbone for manga serialization, while US graphic novel printing clusters around Midwestern offset facilities and European distribution nodes concentrate in Benelux logistics corridors.
United States
Direct-market comic shops in Brooklyn and Los Angeles sustain weekly release culture, while library procurement consolidations in Chicago and Seattle drive graphic novel volume. The FTC monitors collectible marketing claims to prevent misrepresentation of print runs and speculative investment value. Image Comics anchors creator-owned talent pipelines in Portland, Oregon, competing against corporate-owned franchise publishers.
Japan
Weekly serialization in Tokyo and Osaka generates the highest volume throughput through translated tankobon exports. METI promotes manga as cultural export through coordinated copyright enforcement and trade fair participation. Yokohama-based translation houses accelerate licensed distribution pipelines into North American and European bookstore channels.
Germany
Frankfurt Book Fair participation drives manga licensing negotiations, while Berlin's independent publisher clusters experiment with webtoon vertical-scroll formats. The EU Digital Services Act imposes transparency obligations on online platforms distributing comics to minors. Munich's print fulfillment networks face margin compression from coated paper cost volatility and freight logistics strain.
France
Angoulême International Comics Festival sustains critical prestige recognition for bande dessinée and translated manga alike. ANSM and CNIL oversight shapes content classification for digital platform distribution. Paris-based editorial teams accelerate manga translation turnaround to compete with gray-market scanlation channels.
South Korea
Seoul's webtoon studios pioneer smartphone-native vertical-scroll production, reducing per-page costs while expanding into Southeast Asian and Latin American markets. The country's digital platform infrastructure enables subscription-based serialization that bypasses physical retail entirely. Busan-based animation houses increasingly partner with comic publishers for cross-media adaptation pipelines.
Comic Book Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue digital-native formats and cross-media IP exploitation. The vendor base spans corporate-owned franchise publishers, creator-owned rights platforms, and licensed property specialists. Three archetypes dominate: catalog-dominant incumbents with decades of continuity maintenance, creator-owned aggregators leveraging talent attraction through equity participation, and adaptation-focused players anchoring revenue through gaming and streaming derivatives. Competitive moves concentrate on strategic partnerships for platform distribution and portfolio diversification into webtoon vertical-scroll formats.
Within the creator-owned tier, Image Comics exemplifies equity-participation models that sustain talent attraction against corporate competitors. Dark Horse Comics occupies the licensed property specialist position, leveraging adaptation rights into gaming and streaming revenue streams. BOOM! Studios represents the younger-skewing original content archetype, competing with established superhero franchises through bookstore and library channel focus.
| Leading Market Players |
|---|
| BOOM! Studios |
| Fantagraphics Books |
| Image Comics |
| Antarctic Press |
| Vault Comics |
| Dark Horse Comics |
| Oni Press |
| Iron Circus Comics |
| IDW Publishing |
| Others |
Supply Flow & Price Mechanics
Creator-owned publishers operating as equity-participation platforms anchor supply discipline through talent royalty structures that compress margin flexibility, while platform dependency concentrates pricing power with digital distribution gatekeepers who extract revenue-share terms eroding creator pools.
Pricing Analysis
Subscription bundling dominates access pricing, with per-title unbundling reserved for collector-grade variants and limited print runs. Price differentiation rests on format tier—graphic novels command premium unit economics through institutional procurement, while digital serialization competes on volume scale. Cost compression in print fulfillment intensifies as coated paper volatility squeezes independent publishers with limited volume leverage. Libraries and educational buyers exhibit lowest price sensitivity due to consolidated procurement budgets, whereas casual smartphone readers demand friction-free entry pricing.
Supply Chain Analysis
Coated paper supply rests on Japanese specialty mills feeding Tokyo-Osaka serialization hubs, while US offset facilities in the Midwest anchor graphic novel production. Pulp and freight inputs draw from Canadian forestry networks and trans-Pacific logistics corridors. Single-source vulnerability concentrates in weekly manga serialization where artist burnout disrupts title continuity without substitution options. Distribution runs through direct-market comic shops with pull-list pre-order systems, platform intermediaries controlling recommendation algorithms, and institutional procurement channels with extended payment cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform dependency and paper cost volatility are forcing weaker independent publishers toward acquisition or exit, consolidating bargaining power with catalog-dominant incumbents and creator-owned aggregators.
For Market Incumbents: To counter algorithmic opacity from platform gatekeepers, anchor reader relationships through proprietary subscription infrastructure and deepen creator equity participation to lock talent pipelines. Channel control through direct-market comic shop networks provides defensive positioning against digital intermediaries extracting revenue share. For New Entrants and Emerging Players: EU Digital Services Act transparency mandates in European markets open a window for smaller publishers to compete for discovery visibility against catalog-dominant incumbents. White-space targets concentrate in webtoon vertical-scroll formats for Southeast Asian smartphone readers and library procurement channels for bound graphic novels. Go-to-market execution favors platform-native serialization bypassing physical retail entirely. For Investors and Strategic Acquirers: Distressed-cycle entries favor creator-owned publishers with established adaptation pipelines in North American markets. Long-term viability hinges on cross-media IP exploitation extending revenue lifecycles beyond core comic readership. The signal to watch is burnout-driven talent attrition disrupting weekly manga continuity and compressing valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Exclusivity Negotiation | Direct reader data control reduces algorithmic dependency on intermediary gatekeepers. |
| Cross-Media Adaptation Pipeline | Gaming and streaming derivatives extend revenue lifecycles for Image Comics-style creator-owned properties. |
| Library Procurement Consolidation | Institutional contracts with Chicago and Seattle systems stabilize volume for bound graphic novels. |
| Webtoon Format Expansion | Vertical-scroll production reduces per-page costs for Southeast Asian smartphone-native readers. |
| Creator Equity Restructuring | Revised royalty terms counter platform revenue-share erosion eroding talent attraction. |
Methodological Framework
Independent corroboration across publisher financial disclosures, distributor shipment data, and platform subscription metrics underwrites the qualitative findings. Primary interviews with editorial directors, licensing executives, comic shop owners, and library procurement officers combined with secondary validation from customs records, ISBN registration databases, and trade fair participation reports. Bottom-up title-level volume estimates triangulate against top-down market sizing from production facility capacity and paper consumption data.
Rate-of-change decomposition separates volume growth from value expansion across the analysis window. Segmentation dimensions modeled include format type, distribution channel, customer archetype, and regional regulatory cluster. CAGRs derive from trend-line fitting to historical shipment patterns adjusted for platform conversion rates and adaptation pipeline maturation. Forecast inputs incorporate METI-backed export acceleration, EU Digital Services Act implementation timelines, and coated paper cost volatility indices.
The model assumes a particular technology adoption path; alternative pathways for AI-assisted coloring and lettering tools would alter the outlook through compressed entry barriers and discovery algorithm strain. Forecasts reflect assumptions around platform exclusivity terms, creator burnout attrition rates, and cross-media adaptation success ratios. A small set of triggers—paper mill consolidation, platform merger activity, and copyright enforcement shifts—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Publishing
Children Illustration Book Market
Digital Publishing
Book Publishers Market
Digital Publishing
Digital Comics Platform Market
Digital Publishing
China Catalog Market
Digital Publishing
Digital Comics Distribution and Consumption Platforms Market
Digital Publishing
Mexico Commercial Printing Market
Digital Publishing
Newspaper Market
Digital Publishing
Magazine Subscription Service Market
Digital Publishing
Digital Music Publishing Market
Digital Publishing
France Catalog Market
Digital Publishing
Japan Catalog Market
Digital Publishing
Africa Catalog Market
Digital Publishing
Digital Reading Market
Digital Publishing
Middle East Catalog Market
Digital Publishing
Europe E-Book Market
Digital Publishing
US Newspaper Market