
 Africa Catalog Market | 2026-2036
Africa Catalog Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Catalog Market Insights
Enterprise-grade catalog taxonomy is bifurcating the Africa Catalog Market into formal procurement systems and informal trade digitization layers. SAP leverages its S/4HANA procurement modules to anchor public-sector catalog standardization across East African customs unions. Jumia Technologies AG competes through marketplace-native catalog APIs that synchronize SKU data across fragmented last-mile networks. Oracle sustains its position via cloud catalog hubs serving multinational mining and agricultural input distributors.
An Africa catalog constitutes a structured product database—encompassing digital, print, or hybrid formats—that organizes item specifications, pricing tiers, and supplier metadata for B2B or B2C transactions. These systems integrate GS1 barcode standards, multilingual attribute fields, and mobile-optimized rendering to accommodate low-bandwidth environments prevalent across the continent. Digital catalogs now lead volume growth as telecommunications infrastructure improves, while hybrid formats retain dominance in rural agricultural supply chains where printed collateral supplements intermittent connectivity. Interactive catalogs represent the fastest-expanding segment, embedding QR-linked video demonstrations and USSD ordering interfaces tailored to feature-phone penetration rates.
Nigeria's National Information Technology Development Agency and South Africa's Independent Communications Authority of South Africa enforce data-localization and consumer-protection standards that shape catalog platform architecture. The African Telecommunications Union coordinates cross-border mobile-commerce protocols affecting how catalog data traverses regional economic communities. Stakeholders must monitor divergent national data-sovereignty requirements as they architect pan-African catalog networks.
Market Dynamics
Mobile-first catalog architectures are decomposing traditional procurement hierarchies across African economic corridors, forcing vendors to restructure SKU taxonomies around USSD interfaces and low-bandwidth rendering protocols rather than desktop-native formats.
Growth Catalysts
- ATU Mobile-Commerce Protocols:The African Telecommunications Union's cross-border data standards harmonize catalog interoperability across regional economic communities, reducing vendor onboarding friction for pan-African marketplace operators.
- Informal Trade Digitization:Lagos-Ibadan distribution networks and Nairobi's Eastleigh trading cluster drive demand for hybrid print-digital catalogs that bridge feature-phone penetration with formal procurement systems.
- GS1 Barcode Integration:Standardized product identification enables real-time inventory synchronization between South African retail chains and upstream agricultural cooperatives in Limpopo and Western Cape provinces.
Market Restraints
- Data-Localization Compliance Costs:Nigeria's NITDA and South Africa's ICASA impose divergent server-location mandates that fragment cloud catalog architecture and duplicate infrastructure expenditure.
- Last-Mile Connectivity Gaps:Intermittent 2G coverage in rural agricultural supply chains forces continued reliance on printed collateral, constraining full digital-catalog adoption.
- Multilingual Attribute Complexity:Catalog platforms must maintain parallel taxonomies across English, French, Arabic, Portuguese, and indigenous language fields, inflating metadata management overhead.
Strategic Opportunities
- Kenyan Agricultural Input Networks:Underpenetrated cooperatives in Rift Valley and Central Province present white space for QR-linked video demonstrations embedded in interactive catalogs.
- East African Customs Union Procurement:Regional public-sector standardization creates consolidated demand for SAP-anchored catalog modules serving cross-border customs clearance.
- Voice-to-Text Catalog Interfaces:Convergence of natural language processing with USSD protocols enables illiterate vendor segments to navigate product databases via spoken queries.
Industry Challenges
- Taxonomy Engineering Talent Scarcity:Shortage of bilingual data architects capable of structuring product ontologies across Bantu, Nilo-Saharan, and Afro-Asiatic linguistic frameworks delays platform localization.
- Legacy ERP Integration Friction:Mining and agricultural distributors running on-premise Oracle systems face protracted API configuration timelines when connecting to cloud-native catalog hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Catalog Market |
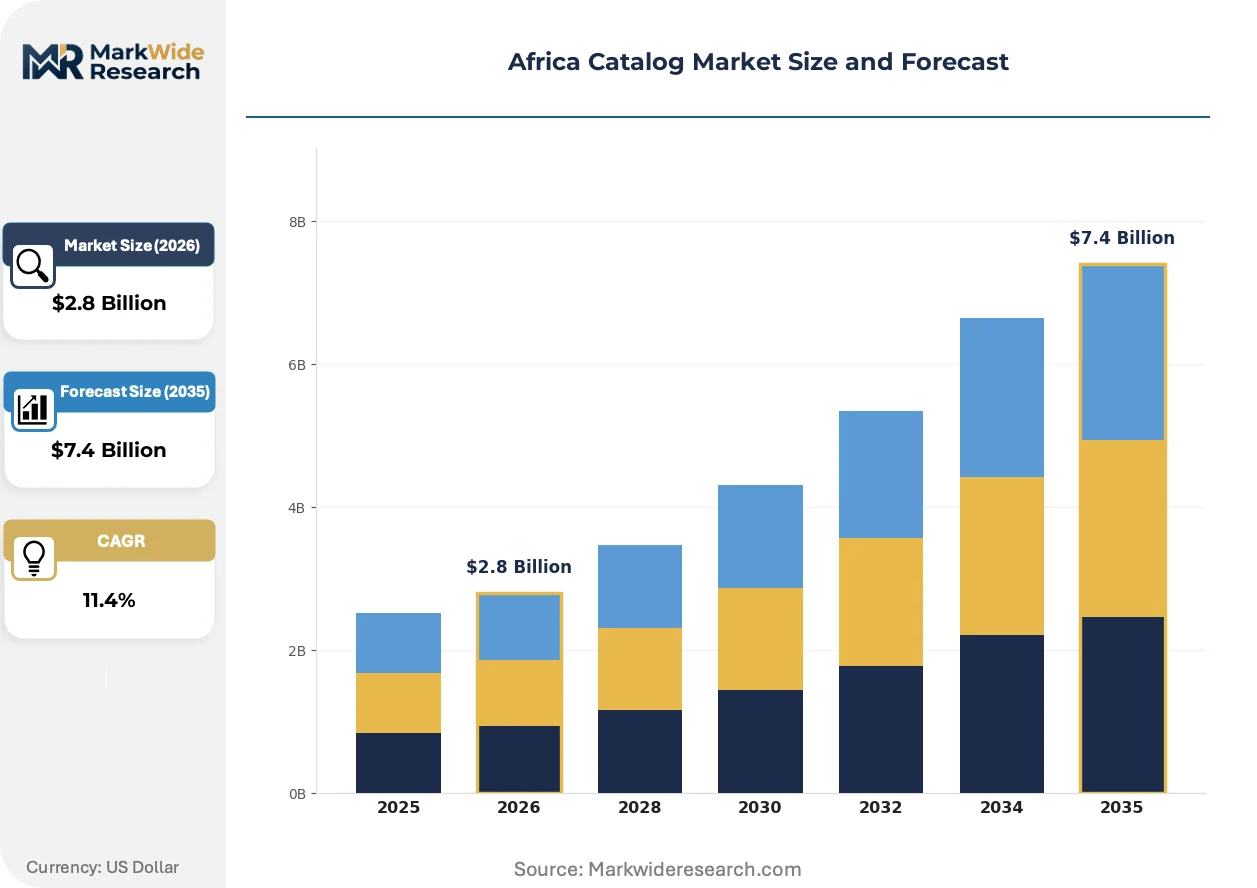
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Print Catalogs, Digital Catalogs, Hybrid Catalogs, Interactive Catalogs Industry Vertical: Retail, Automotive, Real Estate, E-commerce Distribution Channel: Online, Direct Mail, Telemarketing, In-store Customer Type: Consumers, Businesses, Government, Nonprofits |
| Companies Covered | IBM, SAP, Oracle, Salsify, Coupa Software, ServiceNow, Jumia Technologies AG, MTN Group, AGRA, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Catalog Market Trends and Innovations
Catalog technologies across Africa are pivoting from static product listings toward interactive, transaction-enabled interfaces that compress the gap between discovery and fulfillment in low-connectivity environments.
Headless catalog architecture is decomposing monolithic platform structures into modular microservices. Nigerian fintech-integrated marketplaces adopt API-first product databases that render independently across WhatsApp Business, USSD menus, and progressive web apps. This decomposition enables vendors to maintain single-source SKU truth while presenting context-optimized interfaces to buyers across feature-phone, smartphone, and desktop endpoints.
South Africa's ICASA enforces consumer-protection disclosure standards that mandate real-time price transparency and supplier-verification badges within digital catalog interfaces. Mining-input distributors serving the Northern Cape and Mpumalanga belts must reconfigure procurement portals to display landed-cost breakdowns and ethical-sourcing certifications before transaction completion. Agricultural cooperatives in the Western Cape wine region respond by embedding blockchain-traceability links directly into catalog product cards.
Informal traders in Nigeria's Alaba electronics cluster and Kenya's Gikomba market are abandoning physical sample-based purchasing for video-validated catalog orders. Buyers request timestamped warehouse footage via WhatsApp before committing to bulk procurement, displacing traditional intermediary inspection trips. This behavioral shift concentrates demand validation burden onto catalog platforms serving Lagos and Nairobi, forcing vendors to invest in localized content production capabilities.
Africa Catalog Market Segmentation
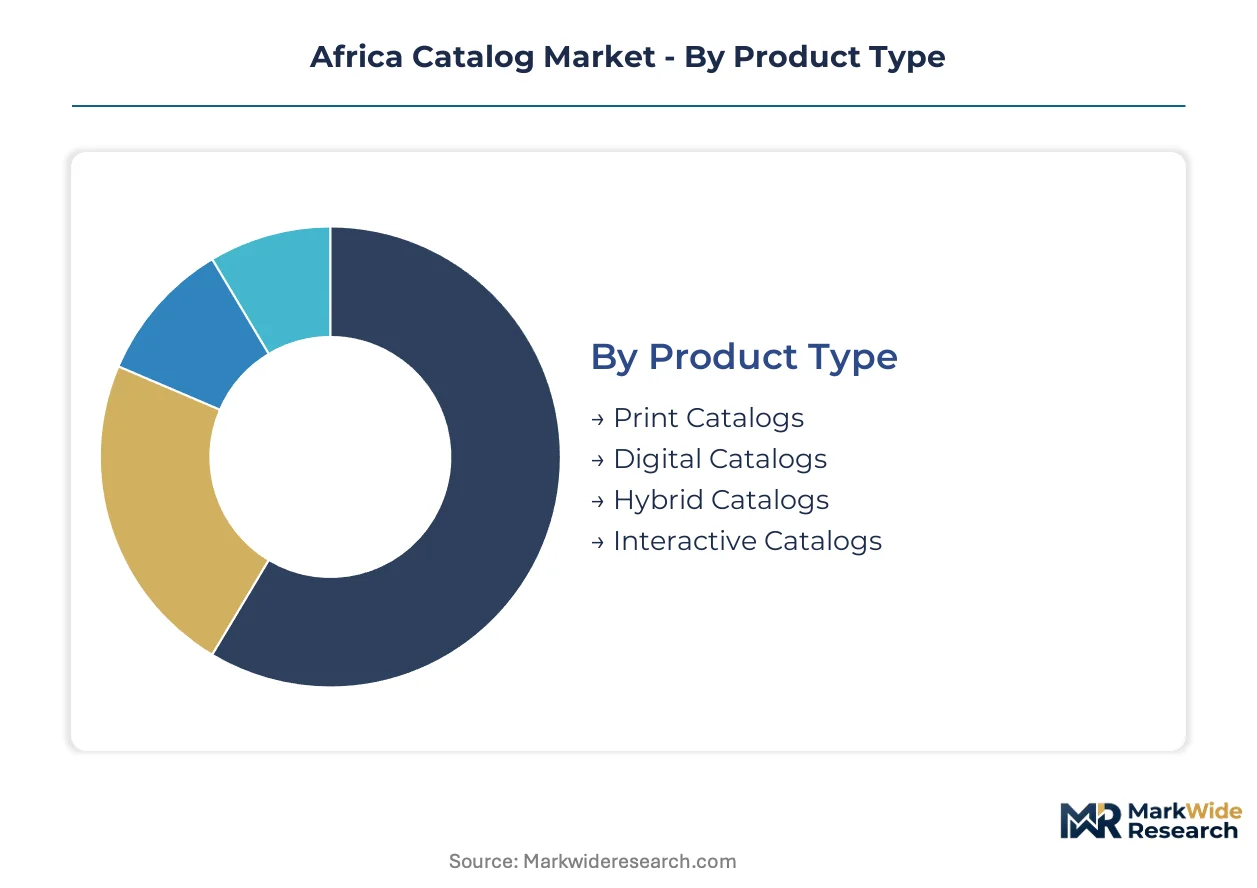
Segmentation reveals how catalog formats and delivery mechanisms diverge across Africa's connectivity gradients. Procurement stakeholders configure platform investments around specific customer types and channel economics rather than treating the market as monolithic.
Product Type:
Margin pools concentrate in formats that bridge low-bandwidth environments with transaction completion.
- Interactive Catalogs:These embed QR-linked video demonstrations, USSD ordering interfaces, and voice-to-text navigation. Demand clusters in Kenyan agricultural cooperatives across Rift Valley and Central Province, driven by NITDA and ICASA consumer-protection mandates requiring real-time price transparency.
- Digital Catalogs:Cloud-native product databases render across progressive web apps and WhatsApp Business interfaces. Lagos-Ibadan distribution networks and South Africa's formal retail corridor anchor volume, propelled by ATU mobile-commerce protocol harmonization.
- Hybrid Catalogs:Print collateral supplements intermittent 2G coverage in rural agricultural supply chains.
- Print Catalogs:Static product listings persist where telecommunications infrastructure remains underdeveloped.
The dominant share belongs to Digital Catalogs, while Interactive Catalogs are gaining share fastest.
Industry Vertical:
Application intensity varies by sector digitization maturity and procurement formalization.
- Retail:Enterprise-grade taxonomy anchors public-sector standardization across East African customs unions. SAP-anchored catalog modules serve cross-border customs clearance, with mining-input distributors in Northern Cape and Mpumalanga reconfiguring portals for landed-cost disclosure.
- E-commerce:Marketplace-native APIs synchronize SKU data across fragmented last-mile networks. Jumia Technologies AG competes through headless architecture decomposing monolithic platforms into modular microservices.
- Automotive:Spare parts procurement relies on GS1 barcode integration for real-time inventory synchronization.
- Real Estate:Property listings leverage multilingual attribute fields accommodating low-bandwidth rendering protocols.
Retail commands the largest deployment base, though E-commerce is climbing the fastest.
Distribution Channel:
Channel economics shift where feature-phone penetration dictates interface design.
- Online:API-first product databases render independently across endpoints. Nigerian fintech-integrated marketplaces adopt this architecture to maintain single-source SKU truth.
- In-store:Physical touchpoints anchor informal trade digitization in Nairobi's Eastleigh trading cluster and Nigeria's Alaba electronics market.
- Direct Mail:Printed collateral reaches segments beyond reliable mobile coverage.
- Telemarketing:Voice-assisted navigation serves illiterate vendor segments via spoken queries.
Online channels generate the highest transaction velocity, while In-store integration is expanding most quickly.
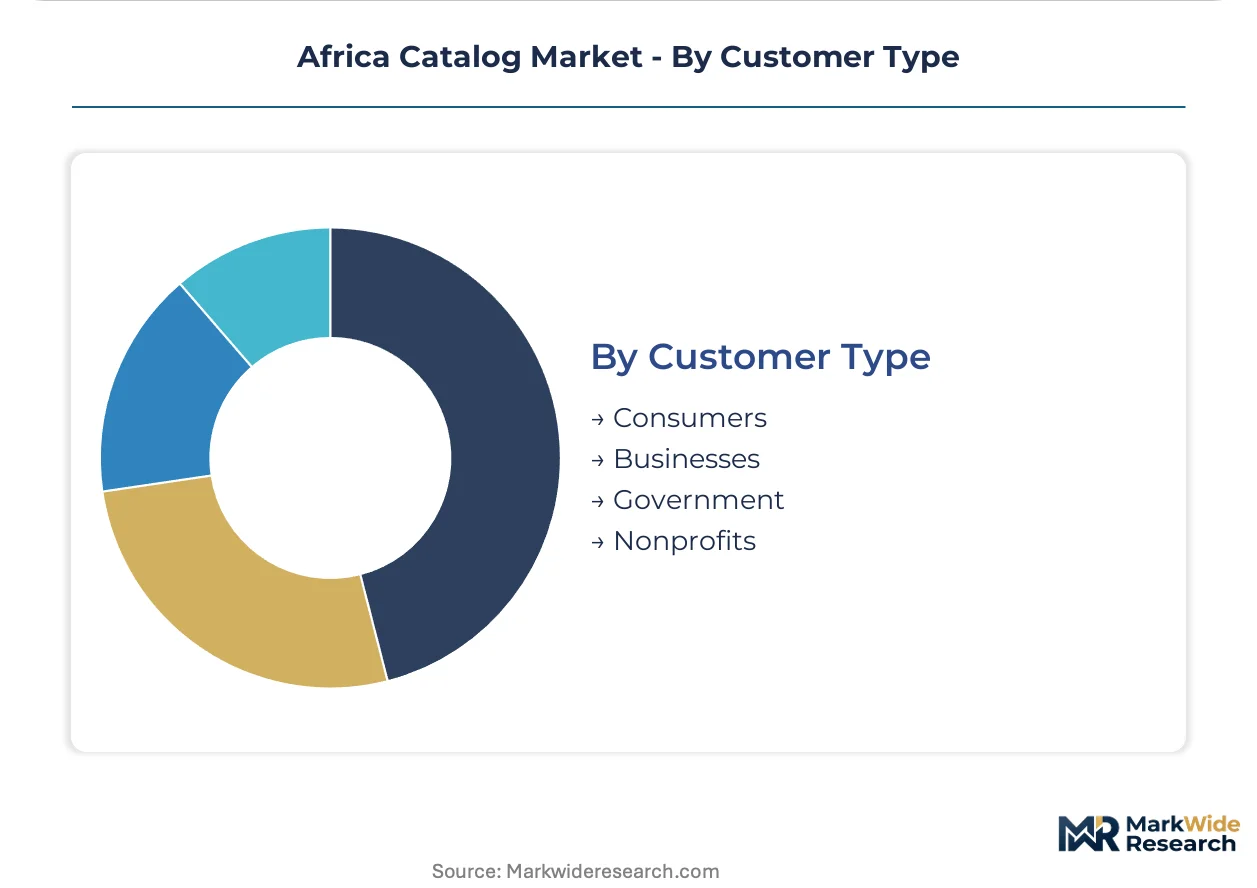
Customer Type:
Procurement complexity escalates with buyer organizational scale and compliance requirements.
- Government:Regional public-sector standardization creates consolidated demand for catalog modules serving cross-border procurement. East African customs unions enforce data-localization mandates fragmenting cloud architecture.
- Businesses:Multinational mining and agricultural input distributors require cloud catalog hubs with ethical-sourcing certification display.
- Consumers:Individual buyers navigate via WhatsApp-validated video orders displacing traditional intermediary inspection trips.
- Nonprofits:Development organizations demand mobile-optimized rendering for field-based procurement.
Government contracts represent the most concentrated revenue pool, while Business adoption is accelerating most steeply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Catalog platform supply concentrates in South Africa's formal retail corridor and Nigeria's Lagos-Ibadan distribution axis, with Kenya's Nairobi cluster emerging as East Africa's interoperability hub. These three markets anchor pan-African vendor onboarding and mobile-commerce protocol standardization.
South Africa
Enterprise procurement systems and mining-input distributors drive catalog demand across the Northern Cape and Mpumalanga belts. The Independent Communications Authority of South Africa enforces consumer-protection disclosure standards mandating real-time price transparency. Johannesburg anchors cloud catalog hub deployment serving multinational agricultural distributors.
Nigeria
Lagos-Ibadan distribution networks and Alaba electronics cluster demand hybrid print-digital catalogs bridging feature-phone penetration. The National Information Technology Development Agency imposes data-localization mandates fragmenting cloud architecture. Kano's informal trade networks are adopting video-validated catalog orders via WhatsApp.
Kenya
Agricultural cooperatives across Rift Valley and Central Province require QR-linked interactive catalogs with USSD ordering interfaces. The East African Community customs union drives regional public-sector standardization for cross-border procurement. Nairobi's Eastleigh trading cluster anchors marketplace-native catalog API development.
Ghana
Accra-Tema manufacturing corridor and agricultural input distributors in Ashanti Region generate demand for GS1-integrated catalog systems. The country's national information technology regulator shapes data-sovereignty requirements for pan-African platform operators. Kumasi's informal trade networks are transitioning from physical samples to video-validated procurement.
Egypt
Cairo-Alexandria industrial zone and Suez Canal logistics hubs concentrate B2B catalog demand for manufacturing inputs. The country's telecommunications regulator coordinates mobile-commerce protocols affecting cross-border catalog data flows. Port Said's free trade zone anchors cloud catalog infrastructure serving North African distribution networks.
Africa Catalog Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Enterprise software vendors anchor the premium tier with procurement-integrated modules, while marketplace-native operators compete on vendor onboarding velocity. Three archetypes dominate: multinational ERP-integrated platforms, regional marketplace operators, and mobile-first catalog specialists. Consolidation is accelerating through strategic partnerships between telecom infrastructure providers and cloud platform vendors, alongside geographic expansion into underpenetrated agricultural supply chains.
Among enterprise software vendors, SAP and Oracle occupy positions anchoring public-sector and multinational procurement standardization. Jumia Technologies AG exemplifies the marketplace-native archetype, competing through API-first architectures that synchronize SKU data across fragmented last-mile networks. These three companies represent the dominant competitive vectors shaping platform interoperability and vendor onboarding economics.
| Leading Market Players |
|---|
| IBM |
| SAP |
| Oracle |
| Salsify |
| Coupa Software |
| ServiceNow |
| Jumia Technologies AG |
| MTN Group |
| AGRA |
| Others |
Pricing and Supply Chain Analysis
ICASA consumer-protection disclosure standards in South Africa gate both vendor qualification and price differentiation simultaneously, forcing catalog platforms to absorb compliance costs before accessing premium procurement tiers while informal trade networks operate outside these certification boundaries.
Pricing Analysis
ICASA disclosure mandates dictate the pricing tier structure across South Africa's formal retail corridor, separating SAP-anchored enterprise modules with full landed-cost transparency from hybrid print-digital formats serving Nigeria's feature-phone penetration zones. Price differentiation hinges on GS1 barcode integration depth and real-time inventory synchronization capability, with mining-input distributors in Northern Cape commanding premiums for ethical-sourcing certification display. Cost compression in cloud-native tiers intensifies as Jumia's API-first architectures reduce vendor onboarding friction. Government procurement offices exhibit lowest price sensitivity due to compliance mandates, while Nairobi's Eastleigh trading cluster traders negotiate aggressively on per-transaction USSD fees.
Supply Chain Analysis
Lagos-Ibadan highway bandwidth constraints create a chokepoint that underwrites hybrid catalog logistics, forcing platforms to maintain parallel print production facilities alongside cloud infrastructure. Supply concentration centers on South Africa for enterprise software modules, Nigeria for marketplace-native APIs, and Kenya for agricultural cooperative interfaces. Raw material dependencies span telecommunications infrastructure from MTN Group, barcode certification from GS1, and multilingual taxonomy engineering talent. Single-source vulnerability runs through SAP's S/4HANA procurement module dominance in East African customs unions. Distribution feeds from Johannesburg cloud hubs through regional economic community corridors into last-mile WhatsApp Business and USSD endpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among East African customs union procurement consortia, consolidating demand for standardized catalog modules and compressing vendor margins across fragmented last-mile networks.
For Market Incumbents: Secure GS1 certification exclusivity in Kenyan agricultural cooperatives before AGRA-funded digitization programs expand. Lock in API rate-limiting contracts with MTN Group infrastructure to raise switching costs for Jumia-competing entrants. Threat of voice-to-text catalog interfaces from NLP specialists demands preemptive USSD protocol patent positioning. For New Entrants and Emerging Players: Anchor in Ghana's Ashanti Region agricultural input networks where GS1 integration remains underpenetrated and Kumasi's informal traders are transitioning to video-validated procurement. Target white space in Egyptian Port Said free trade zone cloud infrastructure serving North African distribution networks. Go-to-market angle: blockchain-traceability modules for Western Cape wine region cooperatives seeking ICASA-compliant ethical-sourcing badges. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across headless catalog microservices as Nigerian fintech-integrated marketplaces demonstrate API-first platform viability without monolithic infrastructure. Long-term viability favors acquisition targets with bilingual taxonomy engineering capabilities spanning Bantu and Nilo-Saharan linguistic frameworks. Signal to watch: Oracle on-premise ERP migration timelines to cloud-native hubs in mining and agricultural distributor segments.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Enables single-source SKU truth across WhatsApp Business, USSD, and progressive web app endpoints in Lagos-Ibadan networks. |
| GS1 Barcode Certification Program | Unlocks real-time inventory synchronization between South African retail chains and Limpopo agricultural cooperatives. |
| Voice-to-Text Interface Development | Captures illiterate vendor segments in Nigeria's Alaba electronics cluster via natural language processing convergence with USSD. |
| Blockchain Traceability Embedding | Satisfies ICASA ethical-sourcing mandates for Northern Cape mining-input distributors and Western Cape wine cooperatives. |
| East African Customs Union Partnership | Consolidates demand for SAP-anchored catalog modules serving cross-border procurement standardization. |
Research Methodology
Desk research of African Telecommunications Union protocol documentation, NITDA and ICASA regulatory filings, and GS1 barcode implementation reports preceded structured interviews with catalog platform CTOs, East African customs union procurement officers, agricultural cooperative supply chain managers, and MTN Group infrastructure planners. Primary fieldwork validated secondary projections through bottom-up vendor onboarding analysis and top-down regional economic community spend aggregation.
Variance decomposition across product type, industry vertical, distribution channel, and customer type dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level adoption curves weighted by telecommunications infrastructure investment trajectories. Forecast inputs incorporated USSD penetration rates in rural agricultural supply chains and mobile-commerce protocol harmonization timelines under ATU coordination.
Decision-makers should treat outputs as directional under assumptions of sustained ATU cross-border data standardization and stable NITDA-ICASA regulatory divergence; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as feature-phone-to-smartphone transition rates and voice-to-text NLP accuracy evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Publishing
Japan Catalog Market
Digital Publishing
Digital Comics Distribution and Consumption Platforms Market
Digital Publishing
Europe E-Book Market
Digital Publishing
Egypt Book Services Market
Digital Publishing
Online Comic Market
Digital Publishing
Children Illustration Book Market
Digital Publishing
China Catalog Market
Digital Publishing
US Newspaper Market
Digital Publishing
Mexico Commercial Printing Market
Digital Publishing
Digital Reading Market
Digital Publishing
France Catalog Market
Digital Publishing
Digital Publishing Platforms Market
Digital Publishing
Book Publishers Market
Digital Publishing
Ebook Publishing Platform Market
Digital Publishing
Editor App Market
Digital Publishing
Comic Book Market