
 Magazine Subscription Service Market | 2026-2036
Magazine Subscription Service Market Size, Share, and Industry Trends Forecast 2026-2036
Magazine Subscription Service Market Insights
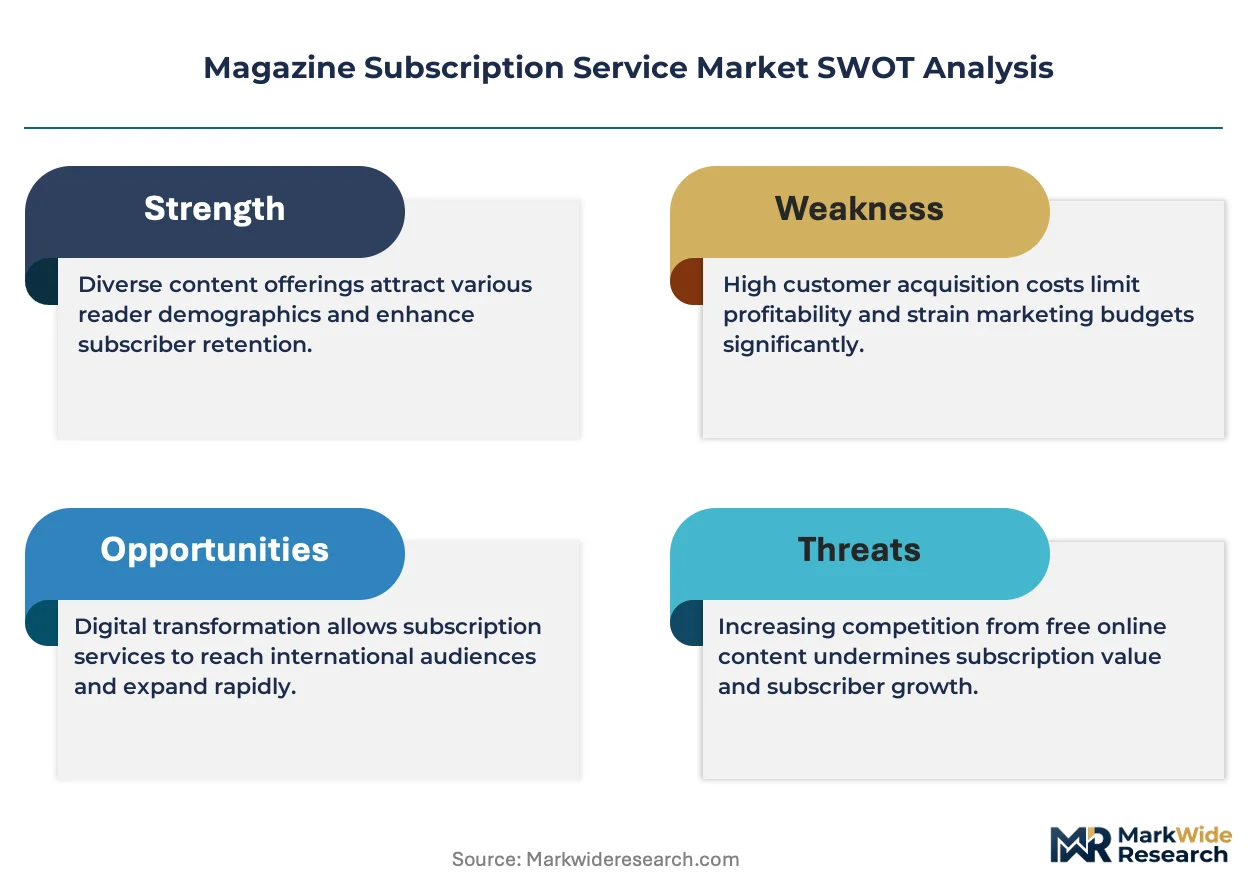
North American media conglomerates is consolidating control over subscriber data infrastructure and fulfillment networks. Conde Nast leverages its luxury brand portfolio to command premium pricing across fashion and lifestyle verticals. Hearst Communications Inc. anchors regional market presence through deep local news integration and diversified print-digital bundles. Bauer Media Group competes on entertainment specialization, particularly in sports and celebrity coverage.
A magazine subscription service constitutes a recurring-revenue distribution mechanism delivering serialized editorial content to paying members through physical mail, digital platforms, or hybrid access models, typically governed by auto-renewal terms and tiered entitlement levels. Monthly subscription models dominate consumer acquisition funnels due to low entry barriers, while yearly commitments capture higher lifetime value from retained hobbyist and professional segments. Digital delivery formats now outpace print in net subscriber additions across technology and news content types, though hybrid offerings preserve margin pools by bundling archive access with physical copies.
The Federal Trade Commission enforces auto-renewal transparency rules under the Restore Online Shoppers' Confidence Act, compelling publishers to disclose terms clearly and obtain affirmative consent. The EU's General Data Protection Regulation restricts cross-border subscriber data monetization, forcing platform operators to localize consent management. Publishers must monitor evolving platform fee structures and authentication standards as distribution economics shift toward direct-to-consumer channels.
Market Dynamics
Direct-to-consumer channel migration is fragmenting publisher-platform power relationships, forcing legacy operators to rebuild subscriber acquisition infrastructure outside dominant app store ecosystems.
Growth Catalysts
- Corporate Gifting Programs:Institutional procurement of bulk magazine subscriptions for employee engagement and client retention creates stable recurring revenue pools outside volatile consumer acquisition cycles.
- EU Digital Services Act:Platform content distribution rules now require algorithmic transparency for media recommendations, reducing gatekeeper power over subscriber funnel economics.
- Hybrid Fulfillment Networks:Integrated print-digital logistics infrastructure enables same-day digital access paired with scheduled physical delivery, capturing margin from subscribers unwilling to abandon tactile formats.
Market Restraints
- Paper and Ink Input Volatility:Newsprint pricing fluctuations and sustainable sourcing mandates compress physical edition margins, particularly affecting high-frequency weekly publications.
- Platform Fee Concentration:Apple and Google app store commission structures extract 15-30% of digital subscription revenue, forcing publishers toward web-direct acquisition with inferior conversion rates.
- Cross-Border Data Monetization Friction:GDPR consent localization requirements prevent subscriber data arbitrage across European national markets, fragmenting audience intelligence economies of scale.
Strategic Opportunities
- India's Vernacular Digital Expansion:Regional language smartphone penetration creates first-mover advantage for localized magazine content in underserved Hindi, Tamil, and Bengali markets.
- AI-Driven Personalization Convergence:Machine learning recommendation engines combined with editorial curation protocols enable dynamic content bundling that adapts to individual reading patterns.
- US IRA Cultural Institution Subsidies:Inflation Reduction Act provisions for nonprofit media sustainability create funding pathways for investigative journalism subscription models.
Industry Challenges
- Subscriber Identity Resolution:Fragmented authentication across print, web, and app environments complicates unified customer data platform construction and churn prediction accuracy.
- Auto-Renewal Compliance Complexity:FTC affirmative consent requirements demand continuous monitoring of disclosure language across fifty state jurisdictions with varying consumer protection standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magazine Subscription Service Market |
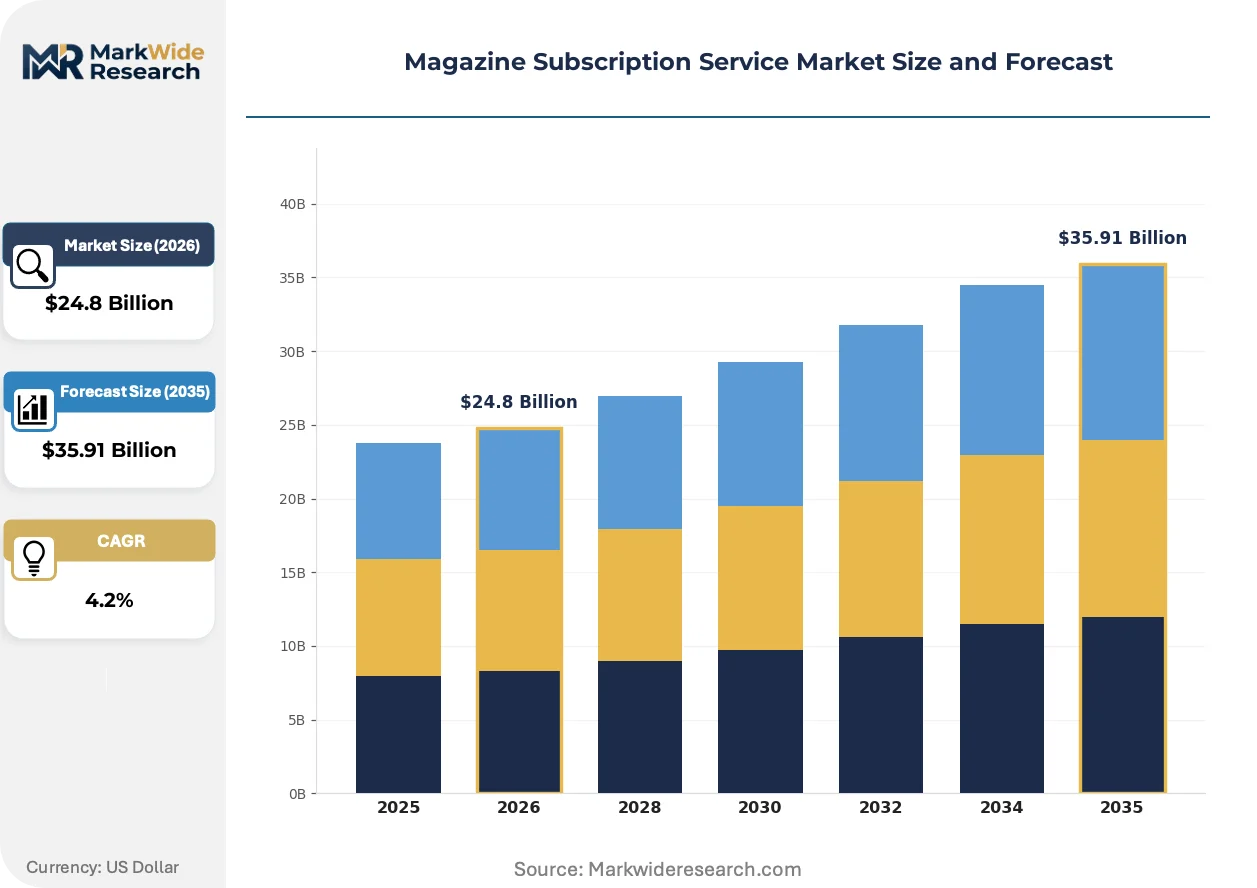
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $35.91 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Subscription Model: Monthly, Quarterly, Yearly, Biannual Content Type: Fashion, Sports, News, Technology Delivery Format: Digital, Print, Hybrid, Audio Target Audience: Students, Professionals, Hobbyists, Families |
| Companies Covered | Advance Publications Inc., Bauer Media Group, Conde Nast, Hearst Communications Inc., Meredith Corporation, Immediate Media Co. Ltd., Forbes Media LLC, Gannett Co. Inc., Guardian News & Media Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magazine Subscription Service Market Trends and Innovations
Machine learning infrastructure is rewriting how publishers predict subscriber lifetime value and intervene before cancellation decisions crystallize.
Natural language generation tools are automating personalized newsletter curation and dynamic paywall messaging. Mid-market publishers with 50,000-500,000 subscribers deploy these systems fastest, lacking legacy CRM complexity. The technology is automating previously manual audience segmentation workflows, compressing the operational gap between niche and mass-market operators.
FTC enforcement of the Restore Online Shoppers' Confidence Act tightens auto-renewal disclosure standards nationwide. Publishers now face civil penalty exposure for ambiguous trial-to-paid conversion language. Monthly subscription offerings in the US market bear the heaviest compliance burden, with legal teams mandating pre-checkout consent documentation.
B2B procurement departments now unbundle magazine subscriptions from consolidated media buying agreements. Individual department heads license vertical-specific titles through corporate card programs, bypassing centralized marketing procurement. This pattern concentrates in technology and financial services sectors where specialized information carries direct revenue implications.
Magazine Subscription Service Market Segmentation
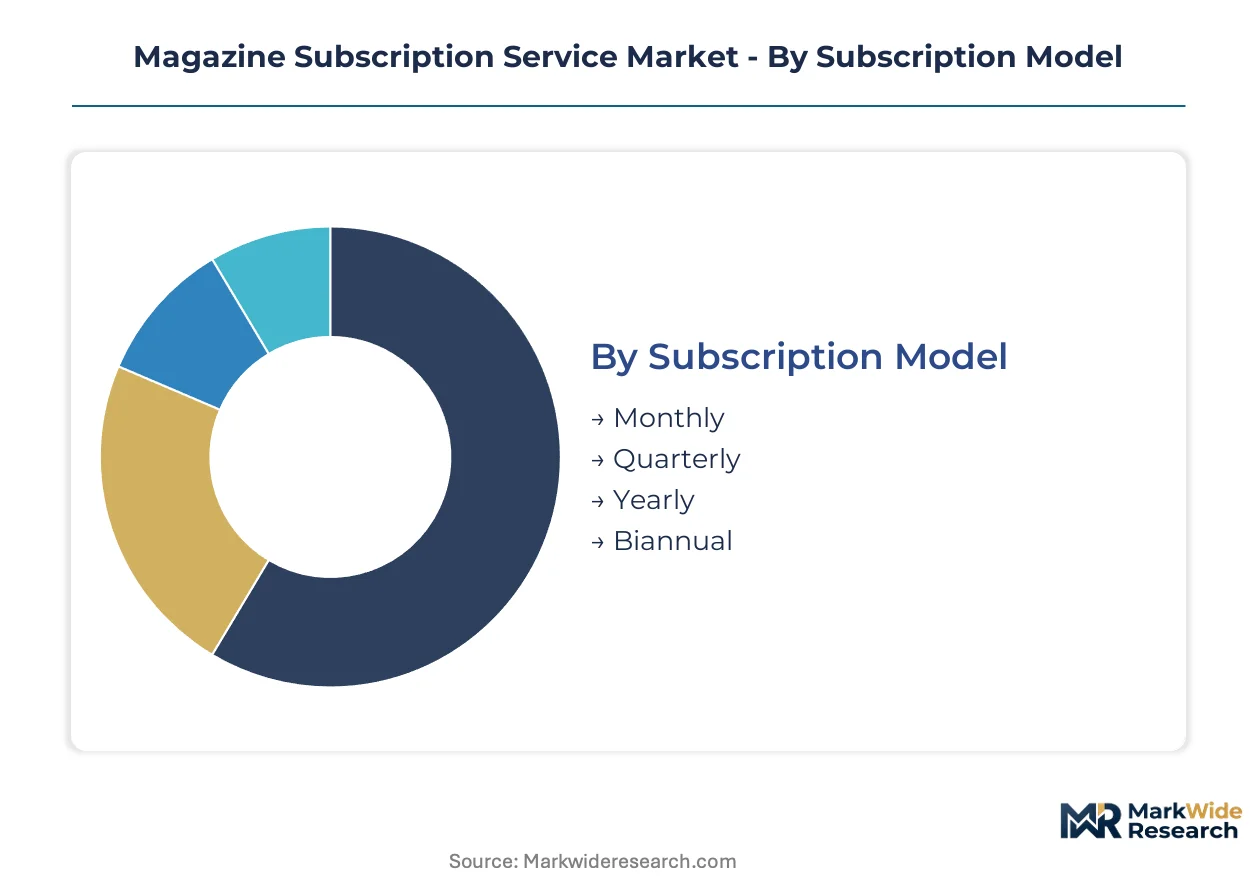
Magazine subscription services fragment across four distinct axes that determine pricing architecture, fulfillment complexity, and customer lifetime value. Each segmentation layer carries implications for auto-renewal engineering, content personalization algorithms, and channel economics. Publishers configure their technology stacks and partnership networks around priority segment combinations rather than pursuing undifferentiated scale.
Subscription Model:
Payment frequency structures cash flow predictability and churn exposure across publisher balance sheets. The technology layer enabling auto-renewal consent management varies substantially by billing cadence.
- Monthly:Lowest-friction acquisition mechanism with recurring payment authorization through stored credential systems. Demand concentrates in technology and news verticals where content freshness drives retention, though FTC affirmative consent requirements impose heavier compliance documentation on this tier.
- Yearly:Prepaid commitment capturing hobbyist and professional segments with demonstrated platform loyalty. Higher upfront payment reduces payment failure rates and customer acquisition cost amortization periods.
- Quarterly:Mid-frequency option balancing cash flow stability with subscriber flexibility. Seasonal publications in fashion and lifestyle verticals deploy this structure to align billing with issue release calendars.
- Biannual:Specialized cadence serving annual publication cycles and commemorative editions. Limited deployment outside luxury print portfolios and limited-run collector markets.
Mature deployment sits with Yearly commitments. Newer deployment is concentrated in Monthly auto-renewal with enhanced disclosure protocols.
Content Type:
Editorial specialization determines advertising yield, corporate gifting suitability, and cross-border licensing complexity. Content categories carry distinct regulatory exposure under platform distribution rules.
- Technology:Rapid obsolescence cycles demand continuous digital refresh, favoring monthly billing and app-native delivery. Professional readership in software and cybersecurity sub-verticals commands premium pricing for early-access product reviews.
- Fashion:Visual-heavy content requiring high-fidelity print reproduction or retina-optimized digital display. Conde Nast's luxury portfolio anchors this segment with integrated e-commerce affiliate revenue streams.
- Sports:Event-driven readership spikes around championship seasons and transfer windows. Bauer Media Group's specialization in celebrity athlete coverage captures advertising from wagering and athletic apparel brands.
- News:Highest regulatory exposure under EU Digital Services Act algorithmic transparency requirements. Hearst Communications leverages local news integration to differentiate against platform-aggregated content.
Established revenue concentration remains with Fashion. Technology content is expanding most quickly through B2B procurement channels.
Delivery Format:
Fulfillment infrastructure investments lock publishers into specific cost structures and margin profiles. Format choice constrains subscriber authentication complexity and cross-platform identity resolution.
- Digital:Platform-native delivery through iOS, Android, and web applications. Apple and Google app store commissions extract 15-30% of revenue, forcing publishers toward direct web acquisition with inferior conversion rates.
- Hybrid:Bundled print-digital access preserving tactile format preference while capturing digital engagement metrics. Same-day digital access paired with scheduled physical delivery commands price premiums from affluent subscriber cohorts.
- Print:Physical mail distribution requiring postal logistics partnerships and newsprint procurement exposure. Sustainable sourcing mandates and input price volatility compress margins on high-frequency weekly publications.
- Audio:Podcast and audiobook format extensions leveraging existing editorial production. Natural language generation tools automate personalized audio curation for commuter and fitness-oriented consumption contexts.
Subscriber preference is shifting fastest toward Hybrid configurations. Pure Print retains strongest position among retirement-age demographics and collector markets.
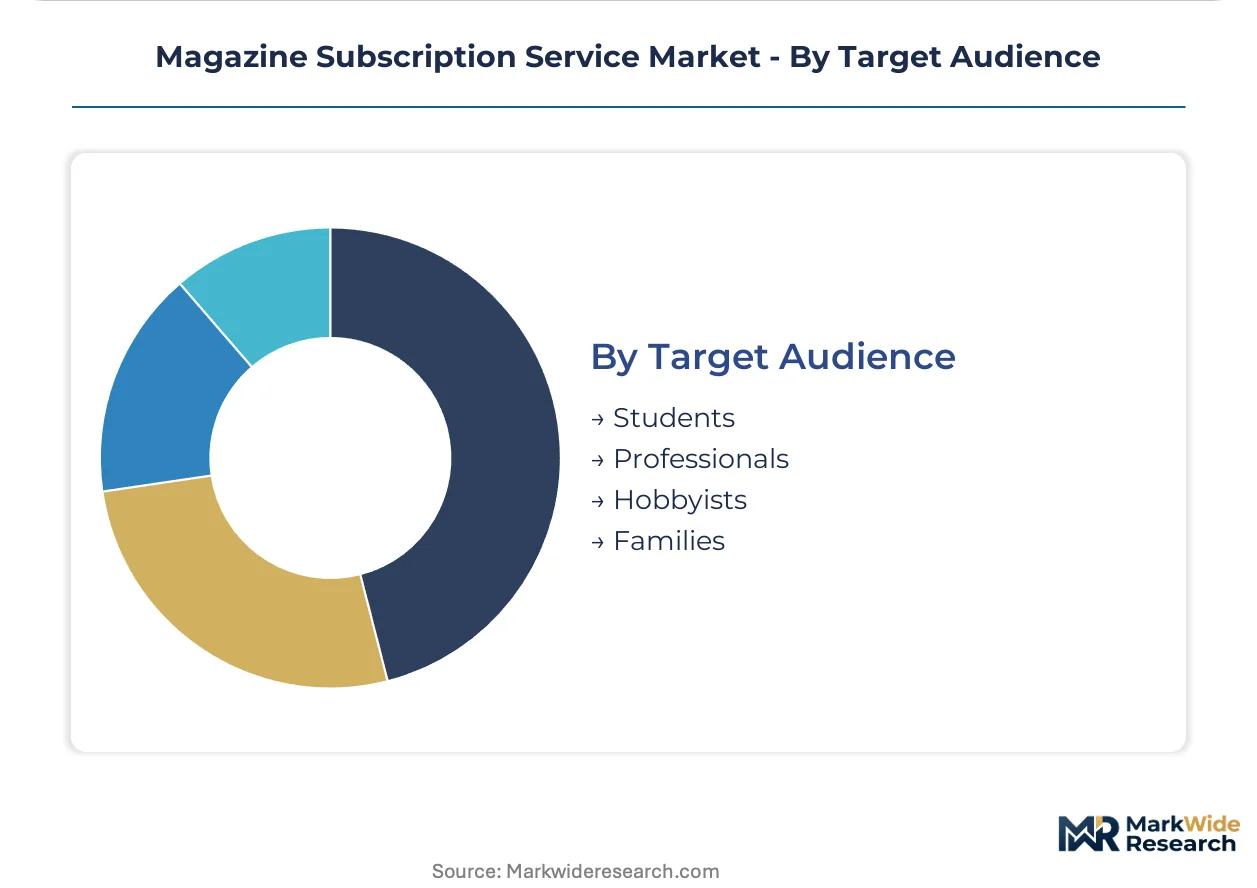
Target Audience:
Demographic and psychographic targeting shapes content bundling strategies, price sensitivity thresholds, and corporate sales channel design. Audience type determines GDPR consent management complexity and cross-border data localization requirements.
- Professionals:Expense-account-eligible subscriptions in finance, law, and consulting verticals. B2B procurement departments increasingly license vertical-specific titles through corporate card programs outside centralized media buying agreements.
- Hobbyists:Enthusiast communities with demonstrated willingness to prepay for annual commitments. Model building, photography, and culinary sub-verticals exhibit highest retention rates and lowest price elasticity.
- Students:Discounted educational pricing with institutional verification requirements. Limited lifetime value due to graduation-driven churn, though acquisition costs remain minimal through campus partnership channels.
- Families:Multi-user household accounts with parental control and content filtering requirements. Magazine bundles compete against streaming service household plans for discretionary subscription budget allocation.
Corporate gifting programs concentrate demand among Professionals. Student pricing is gaining share fastest through university library digital access partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Newsprint mills in Finland and Sweden supply coated paper stock anchoring European print subscription economics, while Indian hardwood pulp imports feed Asia-Pacific digital-physical hybrid growth.
United States
Corporate gifting programs and institutional procurement drive enterprise subscription volume across technology and finance verticals. The FTC enforces auto-renewal transparency under the Restore Online Shoppers' Confidence Act, mandating affirmative consent documentation. New York City hosts Condé Nast and Hearst Communications headquarters, where luxury portfolio bundling commands premium pricing.
Germany
Bauer Media Group anchors sports and celebrity coverage specialization with strong subscriber retention in automotive enthusiast segments. The EU Digital Services Act imposes algorithmic transparency requirements on platform content distribution, reducing gatekeeper leverage. Munich and Hamburg concentrate publishing operations where hybrid print-digital logistics networks optimize fulfillment costs.
India
Vernacular language smartphone penetration creates first-mover opportunity in Hindi, Tamil, and Bengali digital content markets. The country's central bank monitors cross-border payment flows for subscription services under evolving foreign exchange regulations. Maharashtra and Karnataka host emerging publisher clusters where regional language startups secure venture backing for subscription platform development.
United Kingdom
Immediate Media Co. leverages educational and children's content verticals with strong family household subscription penetration. GDPR consent localization requirements prevent subscriber data arbitrage across European national markets, fragmenting audience intelligence economies. London concentrates media technology talent where AI-driven personalization engines attract publisher R&D investment.
Japan
METI promotes digital content export initiatives supporting magazine subscription platform internationalization. Aging demographic cohorts sustain premium print collector markets alongside gradual digital migration. Tokyo and Osaka host publishing headquarters where hybrid fulfillment networks pair same-day digital access with scheduled physical delivery.
Magazine Subscription Service Market Competitive Landscape
Global majors compete with regional champions across content vertical specialization and subscriber data infrastructure ownership. The market structure shows moderate consolidation around diversified media conglomerates with portfolio bundling power, while mid-market specialists retain defensible positions in hobbyist and professional niches. Three archetypes dominate: luxury lifestyle portfolio operators, regional news integration specialists, and entertainment vertical pure-plays. Competitive moves concentrate on direct-to-consumer channel migration and AI-driven personalization engine deployment.
Within the diversified media conglomerate tier, Advance Publications Inc. and Hearst Communications Inc. exemplify portfolio-scale subscription economics, while Condé Nast occupies a position as the archetypal luxury vertical specialist. Bauer Media Group represents entertainment-focused competitive positioning. These anchors demonstrate how geographic origin and editorial specialization shape subscriber acquisition infrastructure investment priorities.
| Leading Market Players |
|---|
| Advance Publications Inc. |
| Bauer Media Group |
| Conde Nast |
| Hearst Communications Inc. |
| Meredith Corporation |
| Immediate Media Co. Ltd. |
| Forbes Media LLC |
| Gannett Co. Inc. |
| Guardian News & Media Ltd. |
| Others |
Pricing and Supply Chain Analysis
Newsprint futures indices cascading through Nordic pulp markets transmit cost volatility into magazine subscription pricing tiers, with coated paper benchmarks from Finnish and Swedish mills dictating margin compression rates for print-heavy publishers while digital-native operators decouple from physical input exposure.
Pricing Analysis
Archive-access bundling separates premium hybrid subscribers from standard digital-only and economy print-basic tiers, with price differentiation hinging on authentication complexity and cross-platform entitlement depth. FTC affirmative consent documentation requirements add compliance overhead to monthly auto-renewal tiers, compressing margins at the entry level. Pricing pressure stems from Apple and Google app store commission extraction, forcing publishers toward web-direct acquisition with inferior conversion mechanics. Corporate gifting programs exhibit lowest price sensitivity, while student discount tiers face highest elasticity.
Supply Chain Analysis
Direct-to-consumer web channels handle subscriber acquisition outside app store ecosystems, though fulfillment still draws from Finland, Sweden, and Canada for coated paper stock. Newsprint procurement, ink formulation chemicals, and postal logistics partnerships constitute core input dependencies. Single-source vulnerability concentrates in Nordic pulp mill capacity for premium print editions. Distribution runs through hybrid print-digital networks pairing same-day digital access with scheduled physical delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race, with subscriber data infrastructure ownership serving as the decisive upstream lever separating consolidated media conglomerates from platform-dependent mid-market operators.
For Market Incumbents: Acquire proprietary authentication and entitlement management systems to reduce platform gatekeeper dependency. Consolidate regional fulfillment networks through logistics partnership buyouts, defending against direct-to-consumer channel fragmentation. Lock in corporate gifting procurement relationships before B2B unbundling accelerates.
For New Entrants and Emerging Players: Enter via vernacular language digital content in underserved Indian regional markets, where Hindi, Tamil, and Bengali smartphone penetration outpaces localized supply. Target hobbyist enthusiast segments with demonstrated annual prepay willingness and lowest churn rates. Deploy AI-driven personalization engines as primary go-to-market differentiation.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-market publishers with 50,000-500,000 subscriber bases and clean subscriber data platform architecture in North American markets. Long-term viability hinges on direct channel revenue share exceeding platform-mediated flows. Watch FTC enforcement intensity on auto-renewal disclosure as inflection signal for compliance-cost repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Subscriber Data Platform Acquisition | Owns authentication infrastructure reducing Apple and Google commission exposure. |
| Hybrid Fulfillment Network Expansion | Captures margin from affluent subscribers unwilling to abandon tactile formats. |
| Vernacular Content Localization | Secures first-mover positioning in Hindi, Tamil, and Bengali digital markets. |
| AI Personalization Engine Deployment | Automates churn prediction and dynamic paywall messaging for mid-market publishers. |
| Corporate Gifting Program Buildout | Creates stable recurring revenue pools outside volatile consumer acquisition cycles. |
Research Methodology
Multi-period observation of subscriber acquisition costs, churn rates, and platform revenue shares anchored the trend analysis, supplemented by interviews with publishing executives, subscription platform engineers, corporate procurement officers, and postal logistics managers. Secondary validation drew from SEC filings of diversified media conglomerates, EU Digital Services Act regulatory filings, FTC enforcement action records, and postal service rate disclosures. Bottom-up subscriber cohort modeling and top-down market sizing triangulation ensured cross-verification.
Segment-weighting across subscription model, content type, delivery format, and target audience dimensions structured the analytical framework across the projection horizon. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and technology adoption S-curves. Forecast inputs incorporated auto-renewal compliance cost trajectories, app store commission evolution scenarios, and vernacular digital penetration rates.
Revisions become necessary when EU algorithmic transparency enforcement intensifies, FTC auto-renewal penalties escalate, or platform fee structures shift materially. Forecasts reflect assumptions about subscriber identity resolution technology maturation and corporate gifting procurement pattern stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Publishing
Europe E-Book Market
Digital Publishing
Africa Catalog Market
Digital Publishing
Digital Newspapers and Magazines Market
Digital Publishing
Digital Publishing Platforms Market
Digital Publishing
Global E-Book Market
Digital Publishing
Mexico Commercial Printing Market
Digital Publishing
Book Publishers Market
Digital Publishing
US Newspaper Market
Digital Publishing
China Catalog Market
Digital Publishing
Children Illustration Book Market
Digital Publishing
Digital Music Publishing Market
Digital Publishing
Books Market
Digital Publishing
Adaptive Content Publishing Market
Digital Publishing
France Catalog Market
Digital Publishing
Japan Catalog Market
Digital Publishing
Middle East Catalog Market