
 Digital Comics Market | 2026-2036
Digital Comics Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Comics Market Insights
The young adult reader base is hardening as the most monetizable demographic for digital comics publishers. Webtoon leverages its vertical-scroll format and creator economy tools to dominate mobile-first markets across Asia and North America. Marvel Comics sustains its position through cinematic universe tie-ins that drive traffic to proprietary digital storefronts. DC Comics anchors its strategy in subscription bundling with broader streaming services, deepening reader retention through exclusive content windows.
Digital comics are electronic graphic narrative works distributed through internet-connected devices, typically rendered at 72-300 DPI for screen optimization and employing DRM-protected file formats such as CBZ, CBR, or platform-native containers. Their primary commercial purpose is to deliver serialized or complete visual storytelling to consumers without physical production or retail intermediaries. Webtoons now occupy the fastest-growing content type slot as vertical-scroll formats reduce production barriers and accelerate release cadences. Subscription services control the most defensible margin pool by converting episodic readers into recurring revenue streams, while direct sales and crowdfunding compete for premium collector segments seeking ownership outside platform ecosystems.
The US Federal Trade Commission monitors in-app purchase disclosures and child-directed advertising under COPPA, while the European Union's Digital Services Act imposes content moderation and algorithmic transparency obligations on platforms distributing user-generated comics. Japan's Consumer Affairs Agency enforces specific labeling for gacha-style monetization mechanics prevalent in manga apps. Stakeholders must monitor how fragmented regulatory regimes across these jurisdictions influence platform architecture, creator compensation structures, and the viability of cross-border content licensing.
Market Dynamics
Mobile-first vertical-scroll formats are hardening as the dominant consumption pattern, compressing production cycles and forcing legacy page-based publishers to re-architect their release cadences and creator compensation models around episodic, algorithmically distributed content.
Growth Catalysts
- GDPR compliance investments:European platforms embedding consent management and data portability tools are unlocking cross-border licensing deals previously blocked by privacy fragmentation. This regulatory alignment is accelerating pan-European content distribution.
- Teen and young adult mobile consumption:This demographic cluster generates the highest per-session engagement metrics and in-app purchase conversion rates. Their preference for smartphone-native formats is pulling publisher investment away from tablet-optimized products.
- Webtoon vertical-scroll technology:The format reduces art production complexity by eliminating panel layout constraints. Creator onboarding velocity has increased as artistic skill requirements shift toward continuous canvas composition rather than traditional page design.
Market Restraints
- COPPA advertising restrictions:US platforms face structural revenue limitations on child-directed content. The FTC's enforcement of verifiable parental consent requirements constrains ad targeting precision for youth-skewing titles.
- Creator economy input costs:Platform-side investments in discovery algorithms, payment infrastructure, and localized translation services are compressing net revenue shares available to original content producers.
- Platform dependency concentration:Distribution gravity centers on three to five mobile-native applications in each major market. Publisher margin negotiation leverage weakens as gatekeeper platforms consolidate reader attention.
Strategic Opportunities
- India's underpenetrated smartphone base:Affordable data pricing and local language content gaps create whitespace for vertical-scroll formats adapted to regional narrative traditions. Early entrants are establishing creator academy infrastructure.
- Audio-digital convergence:Synchronized sound design and voice-acted panel transitions are expanding the addressable market to commuter audiences. This multimodal format commands premium subscription tier placement.
- EU Digital Services Act transparency mandates:Algorithmic disclosure requirements are creating openings for publisher-direct reader relationships outside platform intermediation. First-party data strategies are becoming competitively viable.
Industry Challenges
- Cross-border IP licensing complexity:Fragmented moral rights regimes and divergent work-for-hire definitions across jurisdictions create legal friction for global content rollouts. Contract standardization remains elusive.
- Legacy CMS integration:Established publishers with decades of page-based archival content face technical debt in migrating back catalogs to responsive vertical formats. Automated conversion tools degrade artistic intent.
- Content moderation at scale:Real-time review of user-generated episodes across multiple languages strains operational capacity. False positive takedowns damage creator relations and platform credibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Comics Market |
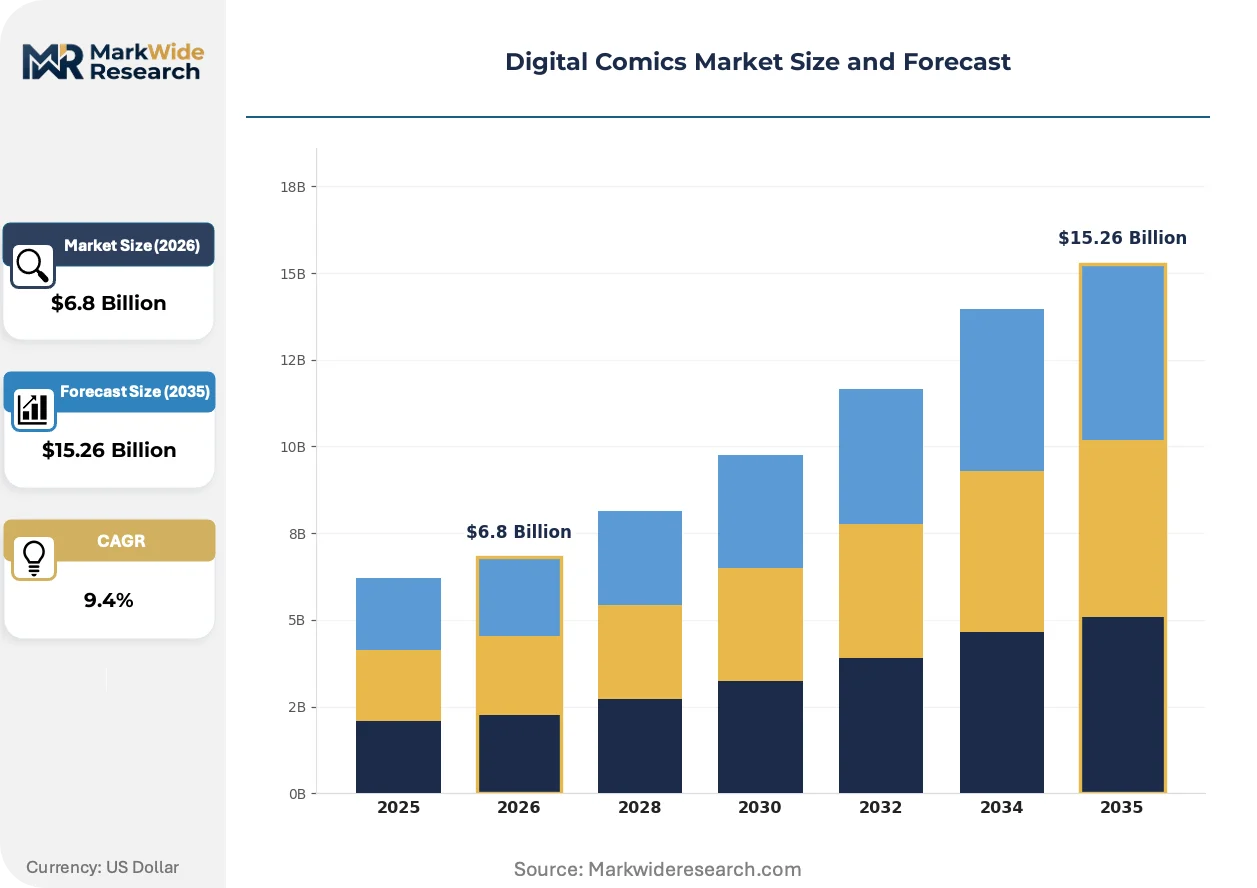
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Content Type: Webtoons, Graphic Novels, Manga, Superhero Comics Platform: Mobile Apps, Online Portals, e-Readers, Subscription Services Distribution Model: Direct Sales, In-App Purchases, Advertising, Crowdfunding User Demographic: Teens, Young Adults, Adults, Families |
| Companies Covered | Webtoon, Tapas, Marvel Comics, Dark Horse Comics, IDW Publishing, DC Comics, Comixology, Kindle Comic Creator (Amazon), Image Comics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Comics Market Trends and Innovations
Generative tooling and immersive media formats are compressing production timelines while fragmenting audience attention across an expanding array of content modalities and interactive narrative structures.
AI-assisted background generation and automated coloring pipelines are expanding into mid-tier production houses in South Korea and Japan. These tools reduce per-episode labor hours by thirty to fifty percent for established artists. The technology is compressing time-to-market for weekly series and enabling smaller studios to sustain competitive release frequencies against better-capitalized competitors.
The EU Digital Services Act's algorithmic transparency requirements are forcing platforms to disclose recommendation system parameters. Publishers are responding by diversifying traffic acquisition through newsletter and community direct channels. This regulatory pressure is most acute in France and Germany, where national regulators have initiated early enforcement actions against non-compliant content distribution applications.
Reader subscription stacking is displacing single-platform loyalty as the dominant spending pattern. Young adult consumers maintain three to five overlapping memberships to access exclusive content windows. This behavior is most visible in the United States, where bundled streaming and comics subscriptions have normalized fragmented content access as the default consumption model.
Digital Comics Market Segmentation
Content format and platform architecture define monetization pathways in digital comics. Publishers must align production workflows with consumption patterns across vertical-scroll, page-based, and hybrid formats.
Content Type:
Standalone native formats dominate mobile consumption, while embedded page-based content persists in proprietary ecosystems and archival catalogs.
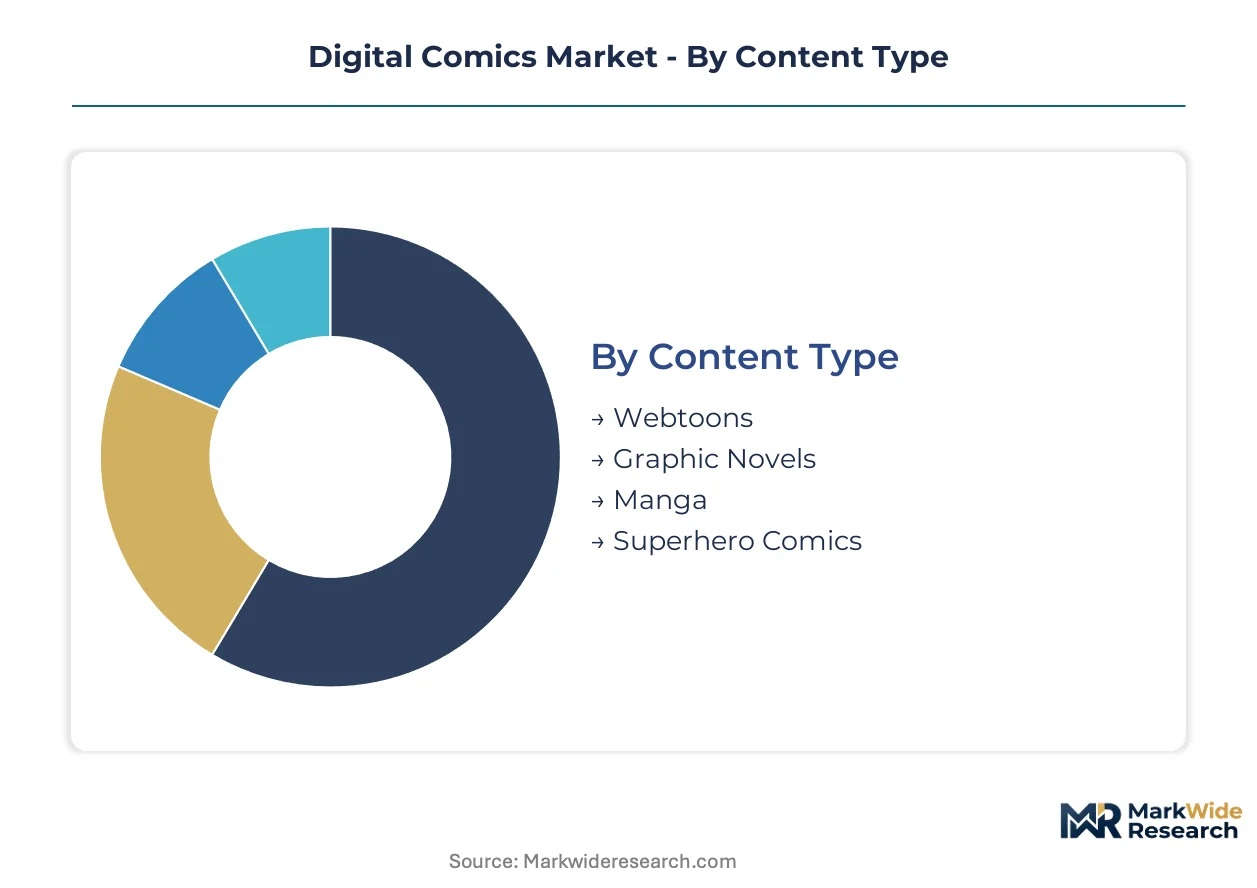
- Webtoons:Vertical-scroll compositions optimized for smartphone displays eliminate panel gutters and enable infinite canvas storytelling. Demand concentrates in South Korea and North America where mobile-first teens and young adults drive the highest per-user session frequencies. The format's reduced production complexity accelerates creator onboarding velocity.
- Graphic Novels:Long-form narrative collections maintain premium positioning through cinematic adaptations and literary award recognition. North American public library digital lending and educational institutional procurement sustain this segment's revenue stability against shorter-form competition.
- Manga:Traditional right-to-left page layouts persist in Japan's mature market with simultaneous English localization expanding Western readership.
- Superhero Comics:Cinematic universe tie-ins from Marvel and DC anchor proprietary platform subscriptions and direct-to-consumer storefront traffic.
Webtoons lead volumes today; graphic novels command the highest per-unit revenue premiums.
Platform:
Cost tier stratification separates free-ad-supported entry points from premium subscription ecosystems and hardware-locked experiences.
- Mobile Apps:Native iOS and Android applications control reader attention through push notification distribution and algorithmic episode feeds. South Korean platforms Naver and Kakao leverage this channel for creator economy monetization at scale.
- Subscription Services:Recurring revenue models from Comixology Unlimited and Marvel Unlimited convert episodic readers into predictable ARPU streams. Bundling with video streaming services deepens retention in the United States.
- Online Portals:Browser-based access reduces friction for casual sampling but struggles with offline functionality and payment conversion.
- e-Readers:Dedicated E Ink hardware from Amazon Kindle and Rakuten Kobo serves collector demographics prioritizing eye comfort and ownership permanence.
Mobile apps capture the largest user base; subscription services deliver the most defensible margin pools.
Distribution Model:
Customer type and purchase intent separate impulse microtransactions from deliberate premium acquisition and patronage-based funding.
- In-App Purchases:Gacha-style unlock mechanics and episode-by-episode micropayments dominate Asian market revenue structures. Japan's Consumer Affairs Agency enforces disclosure mandates on probability-based monetization.
- Direct Sales:DRM-free downloads and perpetual ownership appeal to archivist demographics in North America and Europe. GDPR data portability requirements influence platform architecture for cross-device content access.
- Advertising:COPPA restrictions in the United States constrain youth-targeted ad inventory and CPM rates for teen-skewing titles.
- Crowdfunding:Kickstarter and Patreon integration enables creator-direct relationships outside platform intermediation, particularly for mature and niche genre content.
In-app purchases generate the highest transaction velocity; direct sales deliver superior per-unit economics.
User Demographic:
Application maturity and content sophistication stratify across age-defined consumption clusters with distinct platform loyalty patterns.
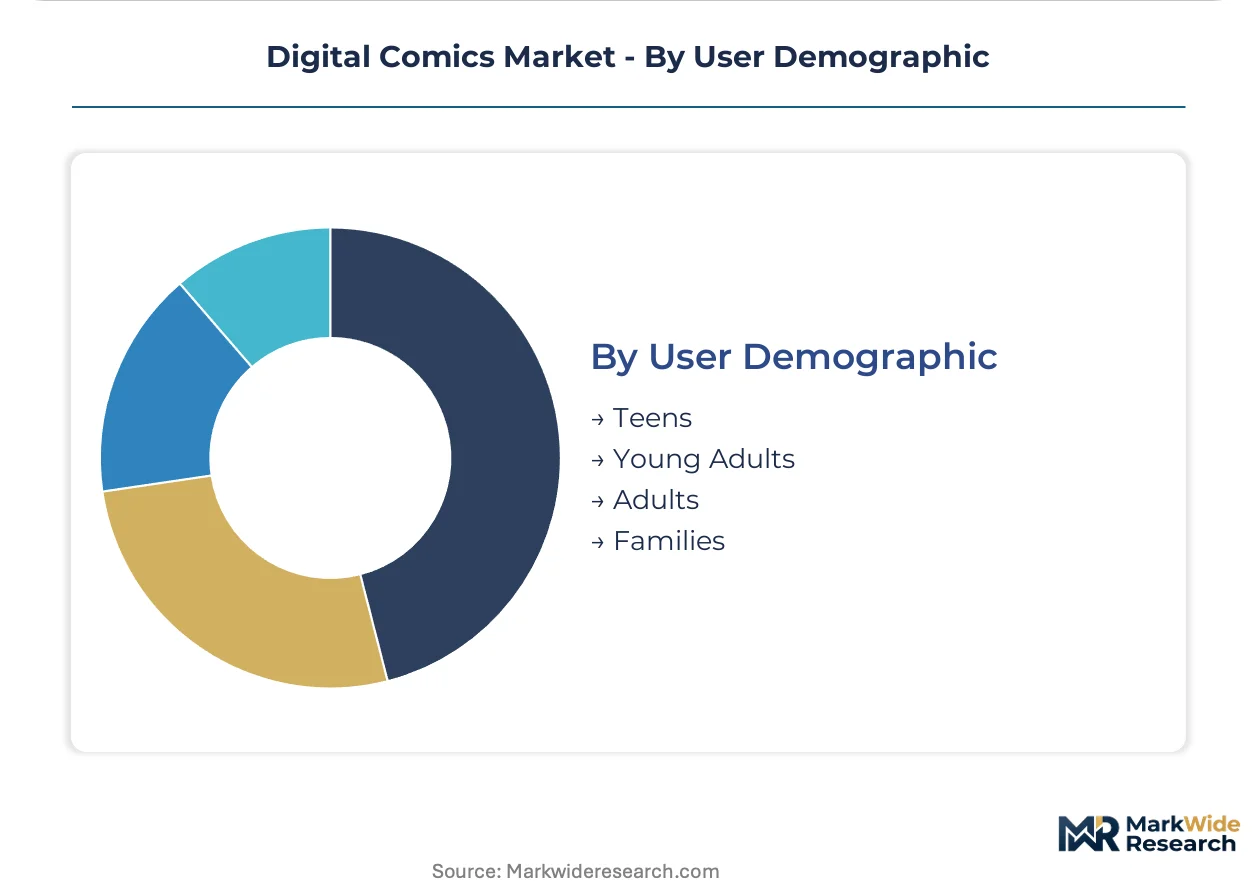
- Young Adults:Ages 18-34 maintain three to five overlapping platform subscriptions and drive audio-digital convergence adoption. This cluster generates the highest lifetime value through sustained engagement and cross-media merchandise purchases.
- Teens:Mobile-native discovery through TikTok and Instagram Reels funnels into vertical-scroll platform onboarding. Parental consent requirements under COPPA and GDPR constrain data collection and personalized recommendation precision.
- Adults:Ages 35-55 favor graphic novel completions and literary nonfiction comics, with public library digital lending as primary access point.
- Families:Shared account usage and content filtering priorities concentrate in subscription bundles with parental control features.
Young adults anchor revenue concentration today; teens represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where digital comics platforms concentrate infrastructure investment, with GDPR-compliant European operations commanding premium licensing multiples while Asian markets exploit lower creator-economy compliance costs to accelerate content velocity.
United States
Teen mobile consumption and cinematic universe tie-ins drive platform traffic concentration. The FTC enforces COPPA advertising restrictions that constrain youth-targeted monetization precision. Los Angeles anchors creator economy infrastructure as major studios integrate digital comics into transmedia production pipelines.
South Korea
Vertical-scroll format innovation and webtoon export licensing generate the highest per-user spending metrics in Asia. The Korea Communications Commission oversees content classification frameworks for mobile-native distribution. Seoul's Gangnam district concentrates platform headquarters and creator academy networks scaling regional talent pipelines.
Japan
Manga serialization traditions and gacha-style monetization mechanics sustain mature market density. The Consumer Affairs Agency enforces probability disclosure mandates on randomized digital goods. Tokyo's Shibuya ward hosts platform engineering clusters optimizing translation pipelines for simultaneous English localization.
Germany
Digital Services Act compliance investments unlock pan-European content distribution previously blocked by privacy fragmentation. GDPR consent management tools embed directly into platform architecture. Berlin's Kreuzberg district emerging as a localization hub for Turkish and Arabic-language vertical-scroll adaptations targeting diaspora readership.
India
Affordable data pricing and local language content gaps create whitespace for format adaptation. The Ministry of Electronics and Information Technology monitors platform content moderation obligations under emerging digital safety frameworks. Bengaluru's HSR Layout corridor attracts venture deployment for creator economy infrastructure targeting Hindi and Tamil-language production.
Digital Comics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with mobile-native platforms commanding reader attention through algorithmic distribution while legacy publishers defend proprietary ecosystems through cinematic tie-ins. The vendor base concentrates around three to five gatekeeper applications per major market, compressing publisher margin negotiation leverage. Two strategic archetypes dominate: vertically integrated platform-creators controlling end-to-end production and distribution, and IP licensors leveraging transmedia franchises to drive subscription conversion. Competitive moves center on exclusive content windowing and bundled streaming partnerships deepening retention.
Within the mobile-native platform tier, Webtoon and Tapas exemplify vertical-scroll format pioneers that have re-architected creator compensation around episodic, algorithmically distributed release cadences. Among legacy IP holders, Marvel Comics and DC Comics anchor proprietary ecosystem strategies where cinematic universe synchronization drives traffic to controlled digital storefronts. Dark Horse Comics occupies a position representing mid-tier publishers pursuing direct-to-consumer relationships outside consolidated platform intermediation.
| Leading Market Players |
|---|
| Webtoon |
| Tapas |
| Marvel Comics |
| Dark Horse Comics |
| IDW Publishing |
| DC Comics |
| Comixology |
| Kindle Comic Creator (Amazon) |
| Image Comics |
| Others |
Pricing and Supply Chain Analysis
Vertical-scroll production automation compresses per-episode labor hours while concentrating creator talent pools in Seoul and Tokyo, simultaneously lowering unit economics and tightening platform control over rate-setting power. This technology shift feeds back into supply choices as publishers abandon page-based workflows entirely.
Pricing Analysis
Platform commission layers absorb 50-70 percent of gross transaction value before creator payout, with subscription bundling commanding deeper discounts than direct-to-consumer storefronts. Price differentiation rests on exclusivity windows and audio-digital feature tiers rather than content length or genre classification. Pricing pressure stems from algorithmic discovery auctions where creators bid visibility spend against royalty income. Young adult subscribers show lowest price sensitivity for early-access tiers; teen ad-supported readers exhibit highest sensitivity to micropayment friction.
Supply Chain Analysis
Illustrator workforce availability in South Korea, Japan, and the Philippines anchors global webtoon production capacity with localized academy pipelines feeding platform talent programs. Raw material inputs draw from proprietary rendering engines, cloud storage infrastructure, and translation localization services concentrated in platform-owned facilities. Supply chain risk centers on single-platform dependency where three mobile applications control 80 percent of reader attention in major markets. Distribution runs through app store gatekeepers with 30 percent revenue share extraction on in-app transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital comics quality stratification hardens as young adult readers abandon ad-supported tiers for premium subscription bundles with exclusive audio features and early-release windows.
For Market Incumbents: Deploy exclusive content windowing to lock creator talent into multi-year platform commitments before competitor poaching accelerates. Defensive consolidation should prioritize acquisition of audio-digital production studios in Los Angeles and Seoul to capture multimodal format premiums. Threat vectors include TikTok-native discovery algorithms disintermediating traditional platform onboarding funnels. For New Entrants and Emerging Players: AI-assisted background generation tools offer entry wedge into mid-tier production segments where established studios maintain cost disadvantages on weekly release schedules. White-space targets include Hindi and Tamil-language vertical-scroll formats for India's underpenetrated smartphone base, plus synchronized sound design for commuter audiences in Germany and France. Go-to-market should emphasize creator academy infrastructure with revenue-share terms exceeding incumbent platform splits. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier publishers with proprietary IP catalogs and direct-to-consumer storefronts outside consolidated platform intermediation. Long-term viability favors assets with transmedia adaptation pipelines and cinematic universe tie-in potential. Signal to watch is regulatory enforcement velocity under EU Digital Services Act transparency mandates creating publisher-direct reader relationship openings.| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Content Windowing | Locks creator talent and deepens subscriber retention against competitor poaching. |
| Audio-Digital Format Investment | Captures premium commuter audience segments in United States and European markets. |
| Creator Academy Infrastructure | Scales regional talent pipelines for Hindi and Tamil-language production in India. |
| Direct-to-Consumer Storefront | Bypasses platform gatekeeper commissions and builds first-party reader data assets. |
| Transmedia IP Development | Converts comic properties into cinematic and merchandise revenue streams. |
Research Methodology
Bottom-up mobile app engagement modeling reconciled against top-down platform revenue tracking forms the analytical core. Primary interviews with digital comics platform executives, creator economy leads, localization studio heads, and mobile app store partnership managers combined with secondary validation from SEC filings, Sensor Tower download metrics, and national content regulator disclosure databases. Triangulation across stakeholder perspectives and data sources ensures segmentation integrity.
Input-output matrices map content format adoption curves to monetization pathway conversion rates across the projection horizon. Segmentation dimensions modeled include content type, platform architecture, distribution model, and user demographic cluster with regional regulatory framework overlays. CAGRs derive from fitted growth curves calibrated to historical platform revenue disclosures and creator payout trend lines. Forecast inputs incorporate GDPR compliance cost trajectories and COPPA enforcement intensity indices.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to algorithmic transparency regulatory expansion and generative AI production disruption. Forecasts reflect documented assumptions on mobile data pricing trajectories and platform commission rate stability. Material deviation in regulatory enforcement velocity or creator unionization movements warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Publishing
Newspaper Market
Digital Publishing
Digital Publishing Platforms Market
Digital Publishing
Online Comic Market
Digital Publishing
Digital Reading Market
Digital Publishing
Ebook Publishing Platform Market
Digital Publishing
Middle East Catalog Market
Digital Publishing
Egypt Book Services Market
Digital Publishing
Digital Music Publishing Market
Digital Publishing
Adaptive Content Publishing Market
Digital Publishing
Europe E-Book Market
Digital Publishing
Books Market
Digital Publishing
Comic Book Market
Digital Publishing
Japan Catalog Market
Digital Publishing
Africa Catalog Market
Digital Publishing
US Newspaper Market
Digital Publishing
Mexico Commercial Printing Market