
 Ebook Publishing Platform Market | 2026-2036
Ebook Publishing Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Ebook Publishing Platform Market Insights
The author base is broadening beyond established publishers to include independent writers, micro-publishers, and institutional content creators. Amazon Kindle Direct Publishing dominates this expanded field through its print-on-demand integration and royalty structure. Apple Books differentiates via its closed-ecosystem distribution and premium formatting standards. Kobo Writing Life competes aggressively in non-English language markets, particularly across Canadian and European territories.
An ebook publishing platform is a digital infrastructure system that enables manuscript upload, automated formatting, DRM protection, and multi-channel distribution through EPUB, MOBI, or proprietary file standards. Cloud-based solutions lead the technology segment due to scalability and real-time collaboration features, while DRM solutions command disproportionate margin contribution from enterprise and educational contracts. Self-publishing generates the highest transaction volume, though subscription services now capture recurring revenue streams that traditional per-unit sales cannot match.
The Federal Trade Commission scrutinizes platform pricing transparency and author contract terms in the United States, while the EU AI Act imposes disclosure requirements on automated content recommendation engines. The General Data Protection Regulation limits reader data harvesting that underpins targeted ebook marketing in Europe. Stakeholders must weigh regulatory compliance costs against the revenue potential of personalized discovery algorithms and direct reader relationships.
Market Dynamics
The ebook publishing platform market is being fundamentally restructured by the FTC's intensifying scrutiny of platform pricing transparency and author contract terms, which is forcing operators to redesign revenue-sharing models and disclosure protocols.
Growth Catalysts
- GDPR-Driven Data Governance:European publishers are investing in compliant reader analytics infrastructure, creating demand for platforms with built-in privacy-by-design architectures.
- AI-Assisted Manuscript Tools:Automated editing and formatting systems are reducing production costs for independent authors, expanding the addressable creator base.
- Direct-to-Reader Sales Channels:United States self-publishers are bypassing traditional aggregators, driving platform adoption of integrated storefront and payment processing capabilities.
Market Restraints
- Amazon Kindle Direct Publishing Concentration:Single-platform dependency creates margin compression and terms-of-service vulnerability for non-exclusive publishers.
- EPUB/MOBI Format Fragmentation:Technical interoperability gaps between proprietary and open standards increase development overhead for multi-channel distribution.
- EU AI Act Disclosure Requirements:Automated content recommendation engines face compliance friction that slows algorithm deployment cycles.
Strategic Opportunities
- Canadian Francophone Markets:Kobo Writing Life's established presence provides a template for English-language platform expansion into underserved bilingual territories.
- Institutional Content Creators:Universities and research libraries represent an emerging application segment requiring specialized DRM and annotation features.
- Cloud-Native Collaboration:Real-time co-authoring tools are converging with version control systems to attract enterprise publishing workflows.
Industry Challenges
- Metadata Standardization Delays:ONIX 3.0 implementation gaps between distributors and retailers create listing errors and revenue leakage.
- Legacy System Integration:Established publishers face friction connecting modern cloud platforms to on-premise rights management databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ebook Publishing Platform Market |
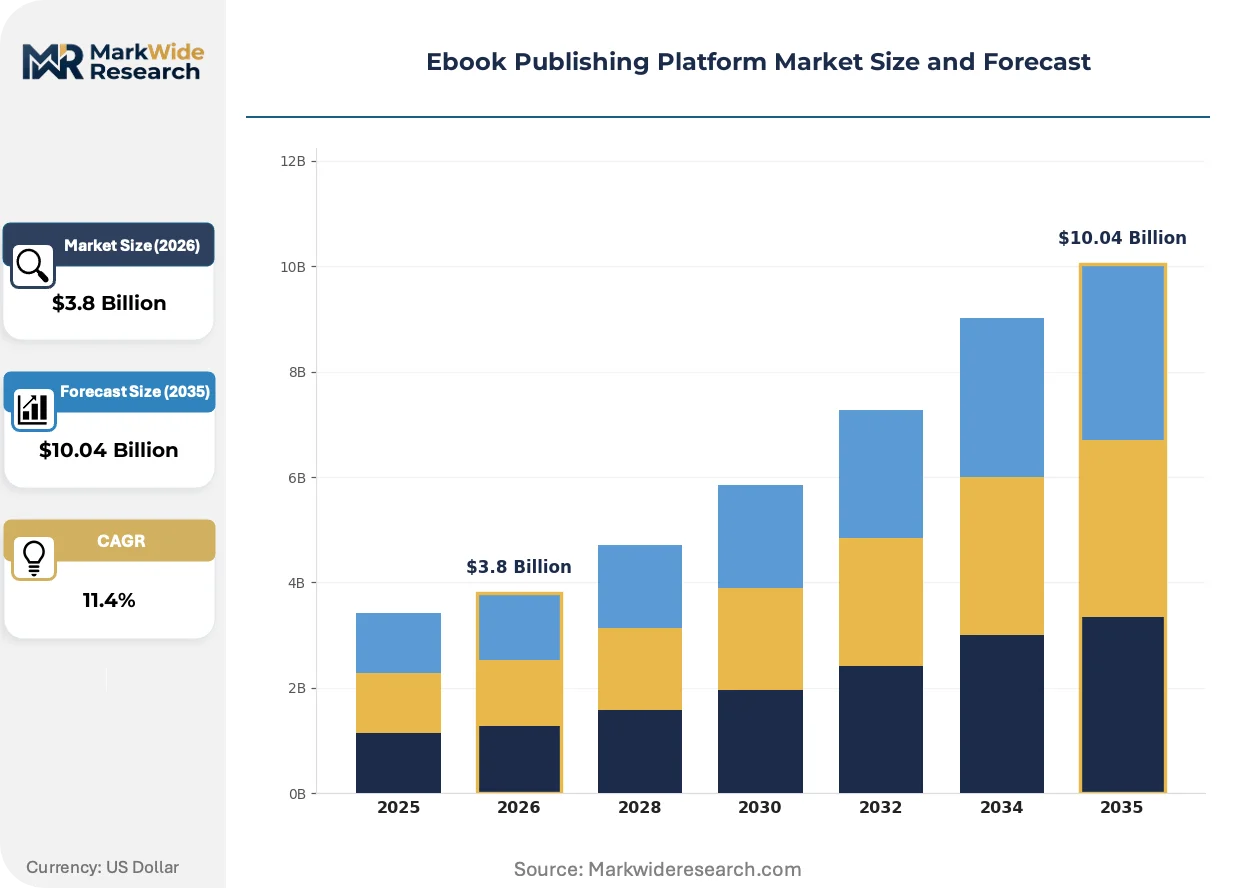
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Publishing, Traditional Publishing, Hybrid Publishing, Subscription Services End User: Authors, Publishers, Educational Institutions, Corporates Distribution Channel: Direct Sales, Online Retailers, Marketplaces, Social Media Technology: Cloud-Based Solutions, Mobile Applications, E-reader Formats, DRM Solutions |
| Companies Covered | Amazon Kindle Direct Publishing, Apple Books, Google Play Books, Smashwords, Draft2Digital, IngramSpark, Lulu, Kobo Writing Life, Barnes & Noble Press, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ebook Publishing Platform Market Trends and Innovations
Artificial intelligence is penetrating manuscript production workflows at an accelerating pace, compressing editorial timelines and reshaping competitive differentiation among platform providers.
Generative AI editing tools are absorbing proofreading and structural revision tasks previously performed by human freelancers. Independent authors in the United States are adopting these systems faster than traditional publishers, cutting production cycles from months to weeks. This compression is absorbing mid-tier editorial service providers into platform-integrated feature sets.
The EU AI Act mandates disclosure of automated content recommendations to European readers, imposing algorithmic transparency obligations on discovery engines. Publishers operating across German, French, and Italian markets must now document how machine learning ranks titles in consumer-facing interfaces. Educational and academic segments are responding fastest, retrofitting recommendation systems with explainable AI modules to satisfy auditor requirements.
Subscription bundling is displacing unit-based purchasing as the dominant reader acquisition model. Kindle Unlimited's penetration in the United States has conditioned consumers to expect all-you-can-read access, pressuring standalone retailers to launch competing programs. This shift is most visible among genre fiction readers, where platform-hopping behavior has shortened publisher reader-retention cycles dramatically.
Ebook Publishing Platform Market Segmentation
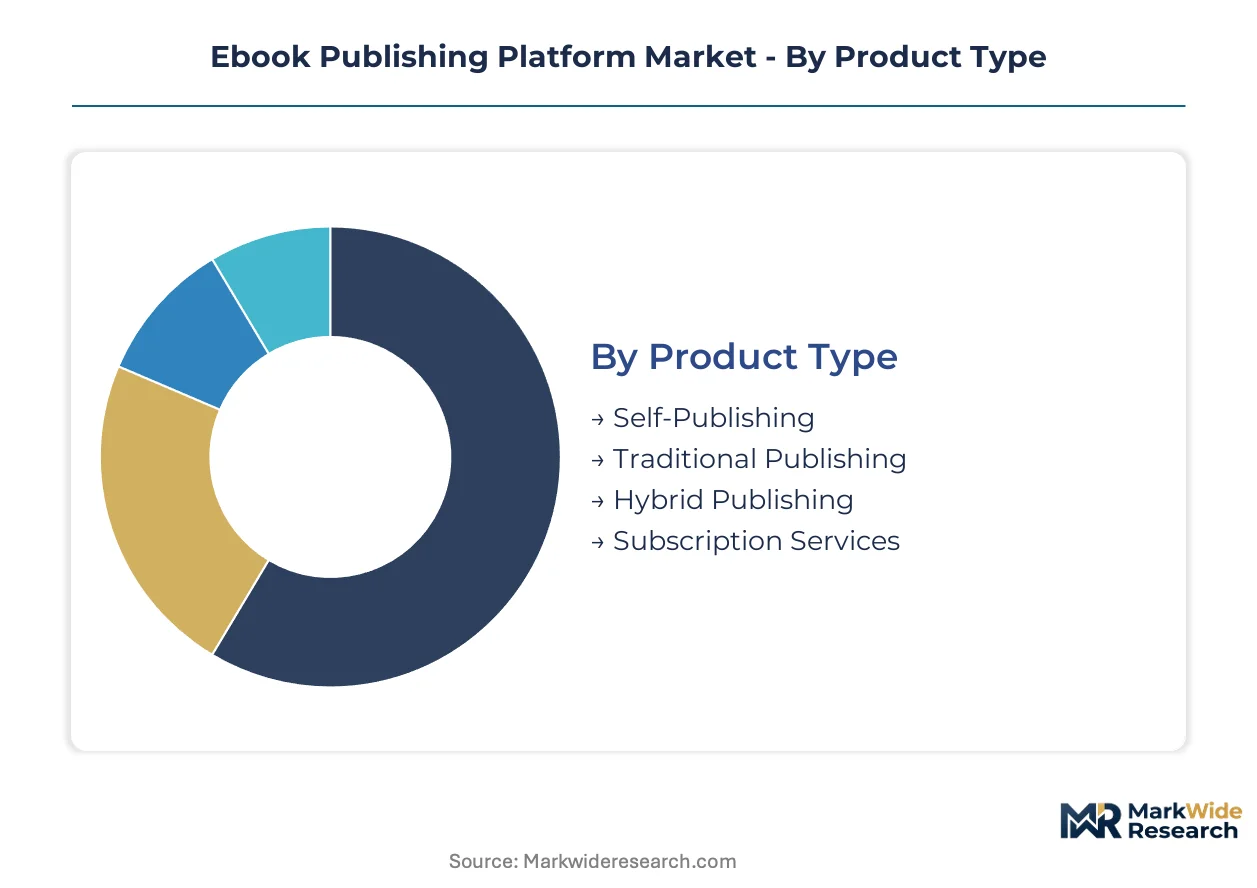
Segmentation in ebook publishing platforms reveals how technology choices, user workflows, and distribution economics create distinct revenue pools. Each category reflects divergent cost structures and compliance burdens that reshape vendor positioning.
Product Type:
Customization spans fully automated self-service portals to white-glove managed publishing programs, with cost tiers clustering at opposite ends of this spectrum.
- Self-Publishing:Automated manuscript upload and royalty calculation systems enable independent authors to retain full rights. United States demand concentrates here, driven by Kindle Unlimited subscription penetration and direct-to-reader sales channel maturity.
- Subscription Services:Recurring revenue models bundle unlimited access across catalog titles, shifting publisher economics from unit sales to engagement-based payouts. This segment is expanding most quickly as reader acquisition costs rise in competitive markets.
- Traditional Publishing:Established houses utilize enterprise-grade workflow management and rights tracking modules.
- Hybrid Publishing:Blends author investment with professional editorial and distribution services.
Leading the category by volume: Self-Publishing. Climbing the fastest: Subscription Services.
End User:
Customer sophistication ranges from individual creators requiring minimal onboarding to enterprise procurement teams demanding SLA-backed integrations.
- Authors:Individual writers and collectives seeking royalty optimization and multi-channel distribution tools. United States independent authors dominate transaction volumes, though GDPR compliance costs in Europe are reshaping platform feature prioritization.
- Publishers:Mid-size and large houses requiring batch processing, rights management, and metadata standardization. These buyers face friction connecting cloud platforms to legacy on-premise systems.
- Educational Institutions:Universities and research libraries need specialized DRM, annotation layers, and accessibility compliance.
- Corporates:Internal training and documentation teams utilizing private distribution channels.
Authors generate the highest transaction frequency. Educational Institutions show the steepest expansion trajectory as institutional licensing models mature.
Distribution Channel:
Channel selection determines margin capture versus reach trade-offs, with direct sales preserving the most value per transaction.
- Direct Sales:Publisher-operated storefronts with integrated payment processing. United States self-publishers are bypassing traditional aggregators fastest here, though platform development costs concentrate demand among higher-volume operators.
- Online Retailers:Established ebook stores with existing customer bases and discovery algorithms.
- Marketplaces:Multi-vendor platforms aggregating titles across publishers with revenue-sharing terms.
- Social Media:Emerging purchase pathways through integrated commerce features on content platforms.
Online Retailers retain the largest revenue share. Direct Sales is gaining share fastest as author tools lower storefront deployment barriers.
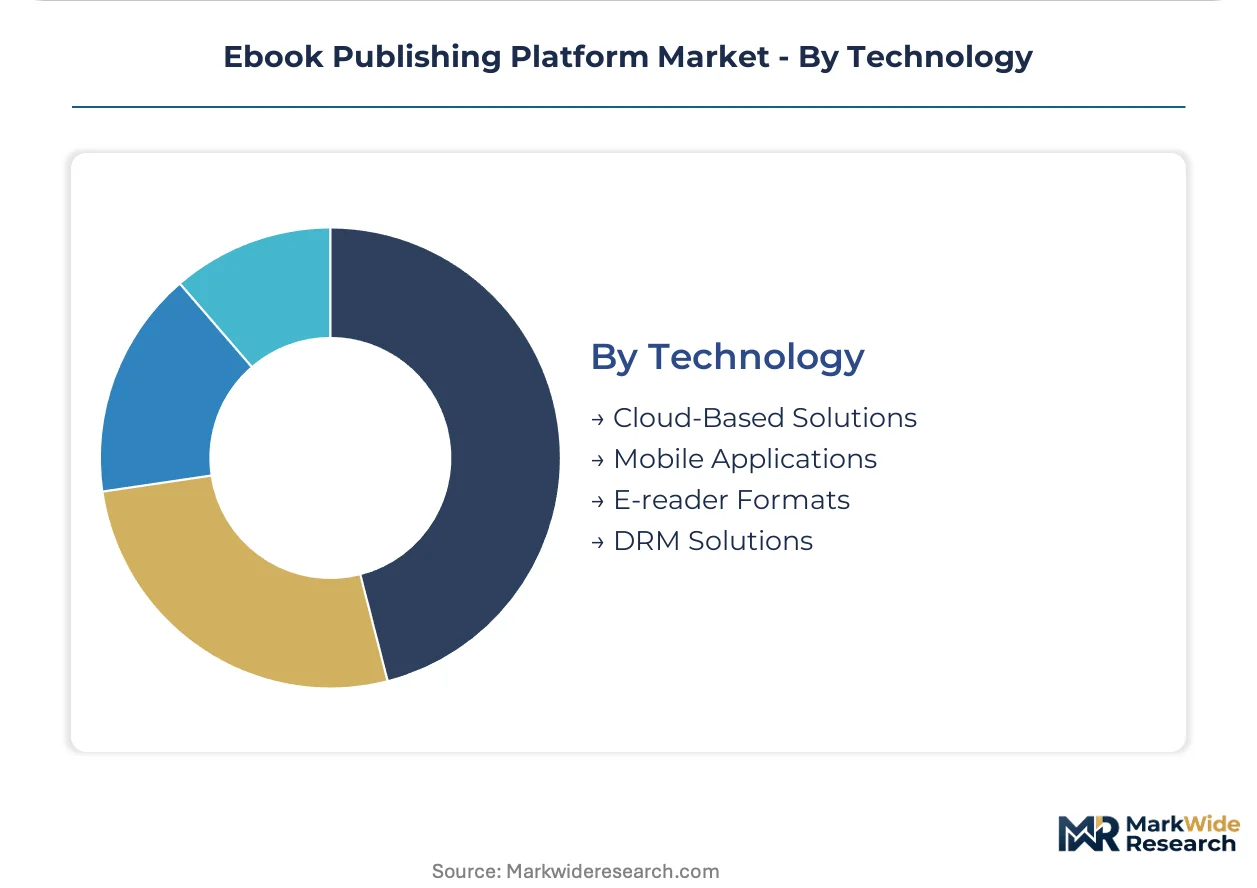
Technology:
Infrastructure deployment models span fully managed cloud services to client-side hardware-dependent formats, with security architectures diverging sharply across segments.
- Cloud-Based Solutions:Scalable hosting with real-time collaboration and version control features. Enterprise and educational contracts in North America and Western Europe drive adoption, though GDPR data residency requirements add deployment complexity.
- DRM Solutions:Encryption and access control systems commanding premium pricing from institutional buyers. These solutions disproportionately contribute margin from enterprise and educational segments.
- Mobile Applications:Native reading apps with offline synchronization and device optimization.
- E-reader Formats:Proprietary and open-standard file specifications for dedicated hardware devices.
Cloud-Based Solutions lead by deployment volume. DRM Solutions carries the highest margin concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's cloud infrastructure density anchors North American platform development, while Frankfurt's data center concentration shapes European compliance architectures. Talent pipelines in Bangalore and Shenzhen feed engineering capacity for mobile-first distribution tools.
United States
Kindle Unlimited subscription penetration and direct-to-reader sales channels drive the world's largest self-publishing revenue pool. FTC scrutiny of platform pricing transparency and author contract terms forces operators to redesign revenue-sharing models. Seattle hosts Amazon's KDP engineering hub, where print-on-demand integration receives continuous investment.
Germany
GDPR compliance requirements and the EU AI Act's disclosure mandates reshape publisher technology investments toward privacy-by-design architectures. The Federal Network Authority enforces data residency rules that complicate cross-border reader analytics. Berlin's startup ecosystem produces specialized metadata standardization tools addressing ONIX 3.0 implementation gaps.
United Kingdom
Independent author adoption of AI-assisted manuscript tools outpaces traditional publishing houses, compressing editorial timelines. The Information Commissioner's Office enforces GDPR-aligned reader data harvesting limits that constrain targeted marketing. London's financial technology cluster supplies payment processing infrastructure for direct sales channels.
Canada
Kobo Writing Life's established presence in Toronto provides a template for bilingual platform expansion into underserved Francophone markets. The Office of the Privacy Commissioner applies PIPEDA requirements to reader analytics infrastructure. Montreal's gaming industry talent pool migrates toward interactive ebook development and annotation layer engineering.
India
English-language content creation and mobile-first reading habits expand the addressable creator base beyond established publishers. The Ministry of Electronics and Information Technology's data localization policies influence cloud deployment decisions. Bangalore's SaaS engineering clusters produce white-label platform solutions for regional language publishers.
Ebook Publishing Platform Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue niche specialization and regional language dominance. The vendor base clusters around three control points: retail marketplace integration, proprietary hardware-software ecosystems, and aggregation services for multi-channel distribution. Strategic archetypes include retail-captive platforms, ecosystem-locked distributors, and author-agnostic aggregators. Competitive moves concentrate on API-based partnership networks and compliance-forward feature differentiation.
Among retail-captive platforms, Amazon Kindle Direct Publishing and Apple Books exemplify divergent ecosystem strategies, while Kobo Writing Life anchors the regional-specialist archetype. These three occupy positions that reflect scale advantages, closed-loop hardware integration, and geographic focus respectively. Their competitive positioning illustrates how control over reader discovery algorithms and payment infrastructure determines margin capture in subscription and unit-sale models alike.
| Leading Market Players |
|---|
| Amazon Kindle Direct Publishing |
| Apple Books |
| Google Play Books |
| Smashwords |
| Draft2Digital |
| IngramSpark |
| Lulu |
| Kobo Writing Life |
| Barnes & Noble Press |
| Others |
Pricing and Supply Chain Analysis
Cloud engineering talent concentration in Bangalore and Seattle creates labor-cost differentials that widen pricing-tier spreads between premium managed-publishing services and self-service automation tiers. Platform providers source development capacity from Indian SaaS clusters while maintaining premium pricing for enterprise contracts in North America and Western Europe.
Pricing Analysis
Volume concentrates in self-publishing tiers with thin per-transaction margins, while enterprise DRM and institutional licensing command premium pricing. Three-tier pricing structure across premium managed services, standard self-service tools, and economy aggregators reflects brand premium and customization level differentials. Pricing pressure stems from Amazon KDP's royalty compression and zero upfront cost model, squeezing competing platforms. Independent authors show highest price sensitivity, while educational institutions demonstrate lowest sensitivity due to budgeted licensing cycles.
Supply Chain Analysis
Workforce availability for AI engineering and cloud infrastructure spans the United States, India, and Germany, with talent scarcity in specialized metadata standardization driving cost premiums. Raw material dependencies include proprietary encryption modules, server hardware from Taiwanese manufacturers, and open-source formatting libraries. Single-source vulnerability concentrates in Amazon Web Services hosting for mid-tier platforms, creating operational risk. Distribution runs through API-based aggregator networks connecting publishers to retailer storefronts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform consolidation accelerates as FTC scrutiny of contract transparency forces sub-scale operators toward acquisition or exit. Regulatory compliance costs and AI infrastructure investments disproportionately burden smaller competitors.
For Market Incumbents: Extend API partnership ecosystems to lock in multi-channel distribution relationships before emerging aggregators gain scale. Acquire specialized metadata standardization firms addressing ONIX 3.0 implementation gaps. Deepen backward integration into cloud infrastructure to reduce AWS dependency and margin leakage.
For New Entrants and Emerging Players: Capture institutional content creator segments in Canadian Francophone markets and European educational licensing where Kobo's template remains underexploited. Penetrate university and research library workflows requiring specialized annotation and DRM features. Lead with privacy-by-design architectures that preempt GDPR compliance costs for European expansion.
For Investors and Strategic Acquirers: Re-rating potential sits with vertical specialists holding compliant AI-assisted manuscript tools given EU AI Act disclosure mandates accelerating enterprise procurement. Long-term viability favors platforms with diversified retailer relationships beyond Amazon's ecosystem. Watch Kindle Unlimited payout rate adjustments as the inflection signal for author-platform migration patterns.
| Strategic Initiative | Industry Significance |
|---|---|
| API Partnership Network Expansion | Secures multi-channel distribution lock-in against emerging aggregator competition. |
| Privacy-by-Design Architecture Investment | Preempts GDPR compliance costs and accelerates European market entry timelines. |
| AI-Assisted Manuscript Tool Acquisition | Compresses editorial timelines and absorbs mid-tier freelance service providers. |
| Institutional Licensing Program Launch | Captures university and research library budgets requiring specialized DRM layers. |
| Direct Sales Channel Infrastructure Buildout | Preserves margin per transaction against aggregator revenue-sharing compression. |
Research Methodology
Document review covered SEC filings from platform operators, EU regulatory submissions, and FTC enforcement records, complemented by interviews with platform product managers, independent author collectives, educational procurement officers, and cloud infrastructure architects. Secondary sources included App Annie mobile download data, ONIX metadata implementation reports, and hyperscaler capex disclosures. Bottom-up transaction volume estimates triangulated against top-down market sizing from publisher revenue disclosures.
Segmentation outputs across product type, end user, distribution channel, and technology deployment model informed volume projections over the projection horizon. CAGRs derived from fitted growth curves adjusted for regulatory inflection points and technology adoption S-cycles. Forecast inputs incorporated Kindle Unlimited subscriber penetration rates and GDPR enforcement intensity indices.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FTC pricing transparency rulings and EU AI Act implementation variance. Forecasts reflect assumptions on author migration elasticity and cloud infrastructure cost trajectories. Material deviation in Amazon KDP policy changes or European data residency enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Publishing
Online Comic Market
Digital Publishing
GCC Commercial Printing Market
Digital Publishing
Adaptive Content Publishing Market
Digital Publishing
Digital Newspapers and Magazines Market
Digital Publishing
Middle East Catalog Market
Digital Publishing
Book Publishers Market
Digital Publishing
Digital Comics Platform Market
Digital Publishing
Digital Music Publishing Market
Digital Publishing
Comic Book Market
Digital Publishing
Digital Comics Market
Digital Publishing
Digital Reading Market
Digital Publishing
News and Magazines App Market
Digital Publishing
Digital Comics Distribution and Consumption Platforms Market
Digital Publishing
Magazine Subscription Service Market
Digital Publishing
Global E-Book Market
Digital Publishing
Egypt Book Services Market