
 Europe E-Book Market | 2026-2036
Europe E-Book Market Size, Share, and Industry Trends Forecast 2026-2036
Europe E-Book Market Foresight
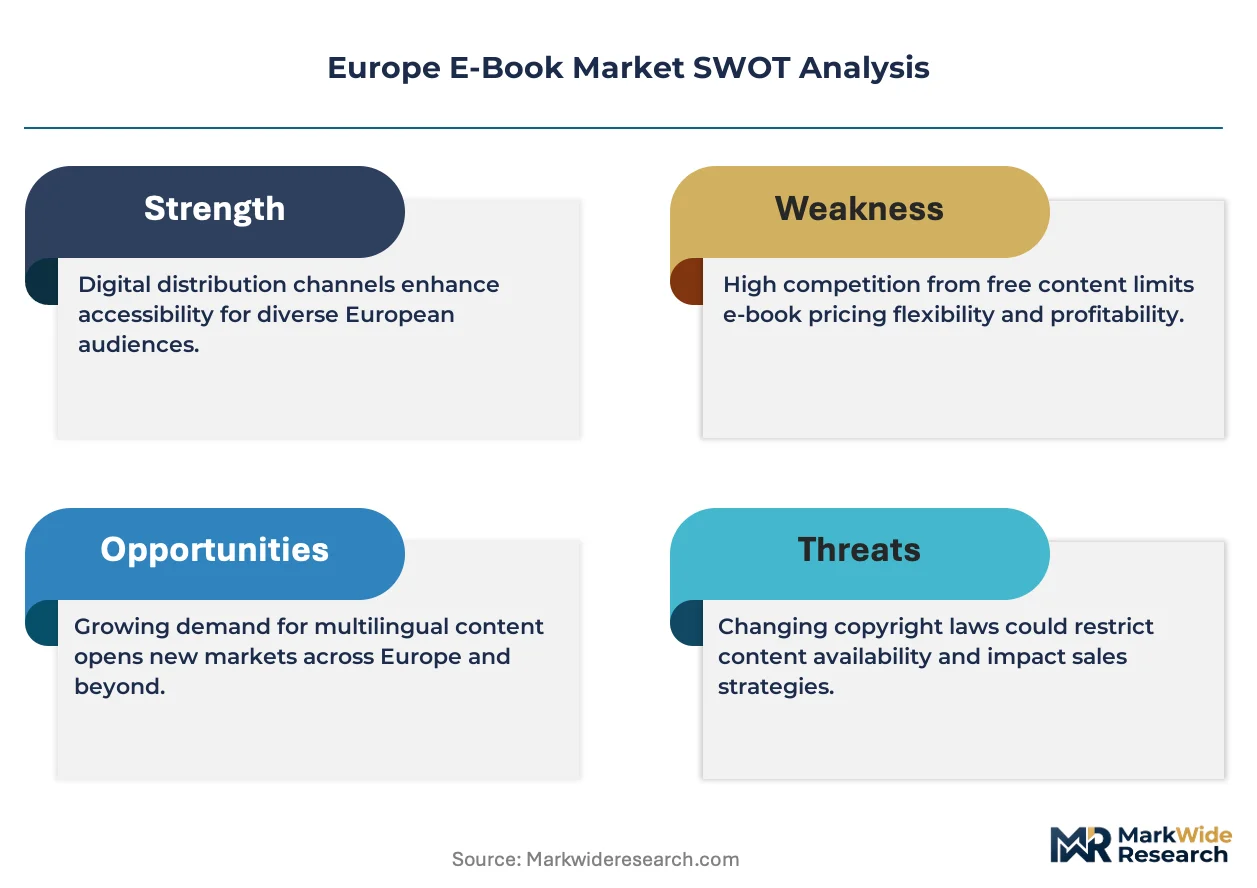
Digital publishing talent pools across Southern Europe is collapsing, creating bottlenecks for localized content pipelines. Amazon.com Inc. leverages its Kindle ecosystem to sustain distribution dominance across France and Italy. Storytel AB anchors its position through audiobook-e-book bundling in Nordic markets. Rakuten Kobo Inc. competes via hardware-software integration and library partnership networks.
An e-book is a digital publication formatted for electronic display, utilizing reflowable text encoded in EPUB, MOBI, or PDF standards with DRM protection layers, designed for distribution and consumption without physical printing infrastructure. E-reader devices with E Ink displays remain the preferred hardware for extended reading sessions due to reduced eye strain and battery longevity. Fiction and non-fiction content types command the largest revenue pools, while academic segments show the fastest structural growth as universities replace print course materials. Subscription pricing models now capture recurring revenue streams that one-time purchases cannot match, particularly in German and Dutch markets.
The EU Digital Services Act, GDPR, and national e-lending regulations under the EU Copyright Directive collectively shape platform liability, data handling, and library lending terms across member states. France's CNIL and Germany's KBA-adjacent consumer protection bodies enforce compliance thresholds that determine market access for foreign distributors. Stakeholders must monitor evolving national e-lending caps and interoperability mandates that could fragment or unify the continental marketplace.
Market Dynamics
The EU Digital Services Act is reshaping platform liability frameworks across continental distribution networks, forcing publishers and aggregators to restructure content moderation pipelines and algorithmic transparency protocols before enforcement deadlines crystallize.
Growth Catalysts
- Academic digital transition:Universities across Germany and France are replacing print course materials with licensed e-textbook repositories, creating institutional demand pools that individual consumer sales cannot replicate.
- E-lending framework maturation:National implementations of the EU Copyright Directive's e-lending provisions are standardizing library access terms, reducing legal friction for cross-border content circulation.
- Reflowable text standards:EPUB 3 adoption is enabling accessibility features and multimedia integration that static PDF distribution cannot support.
Market Restraints
- GDPR compliance costs:Data localization and consent management requirements impose operational burdens on smaller distributors that Amazon and Rakuten absorb through scale.
- Southern European talent scarcity:Digital publishing expertise concentrates in Nordic and German-speaking markets, creating localization bottlenecks for Italian and Spanish content pipelines.
- DRM interoperability failures:Proprietary protection layers lock consumers into single-ecosystem purchases, suppressing secondary market liquidity and price competition.
Strategic Opportunities
- Audiobook-e-book bundling:Nordic markets demonstrate that subscription services capturing dual-format consumption achieve retention rates that standalone e-book offerings cannot match.
- CSRD disclosure mandates:Large publishers face sustainability reporting requirements that create competitive differentiation for carbon-neutral digital distribution claims.
- Library partnership networks:Municipal systems in the Netherlands and Belgium seek integrated lending platforms that hardware-software vendors can provision through API-first architectures.
Industry Challenges
- Skilled localization deficit:EPUB production and metadata tagging expertise remains scarce in Portugal, Greece, and Eastern European markets, delaying regional catalog expansion.
- Legacy print contract renegotiation:Author and agent agreements drafted for physical royalty structures create legal complexity when migrating titles to subscription or pay-per-page models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe E-Book Market |
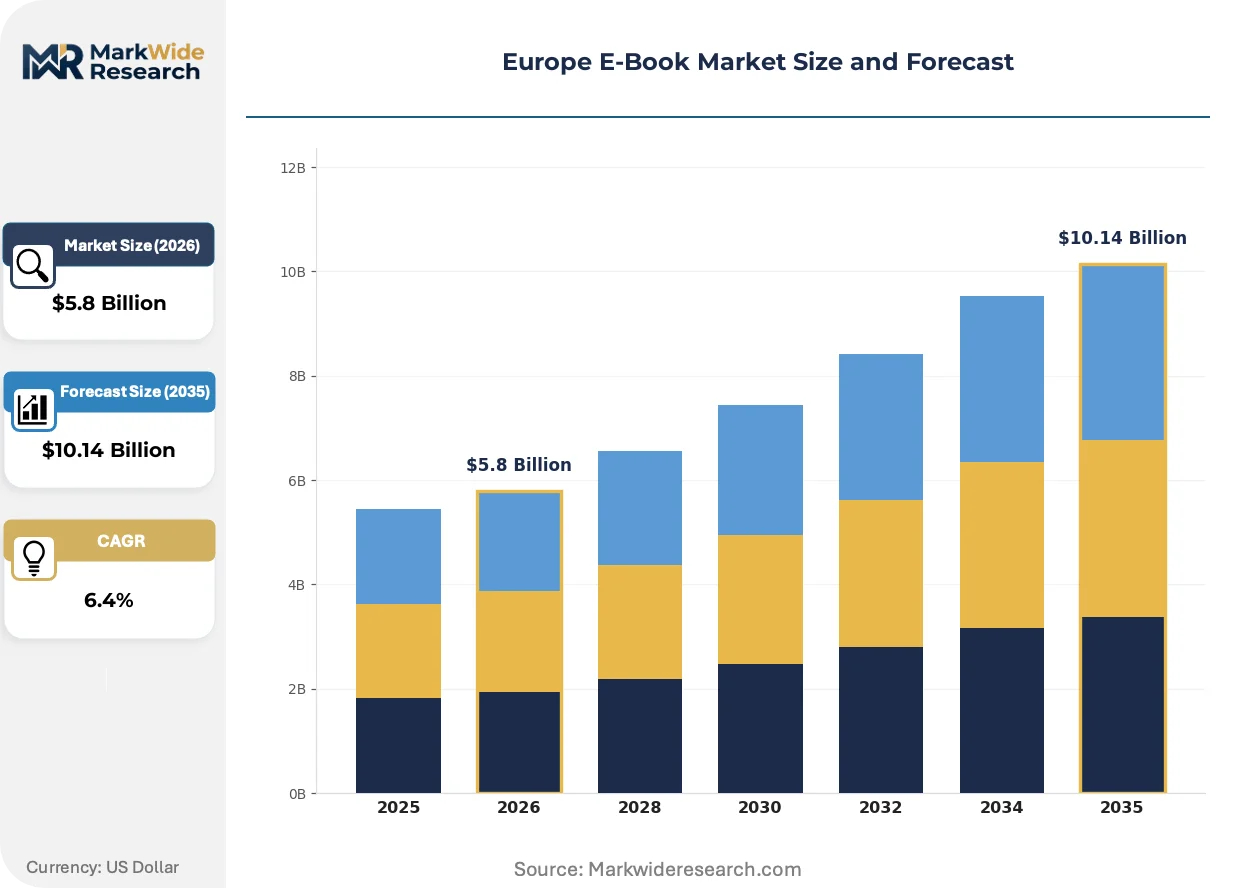
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Content Type: Fiction, Non-Fiction, Academic, Professional Device Type: Tablets, E-Readers, Smartphones, Computers Distribution Channel: Online Retailers, Publisher Websites, Libraries, Direct Sales Pricing Model: Subscription, Pay-Per-View, Free, One-Time Purchase |
| Companies Covered | Alphabet Inc., Storytel AB, Amazon.com Inc., PocketBook International, BookBeat GmbH, Rakuten Kobo Inc., Tolino Media GmbH & Co. KG, Bookeen, Apple Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe E-Book Market Shifts & Advancements
Artificial intelligence tools are penetrating editorial workflows and consumer discovery layers simultaneously, compressing production timelines while fragmenting attention economics across competing content formats.
AI-assisted narration is displacing human voice talent in audiobook production for backlist titles and mid-tier genres. German and Dutch publishers are deploying synthetic voices for non-fiction and instructional content where emotional range matters less than speed-to-market. This technology is displacing traditional studio recording budgets and reshaping royalty structures for narrators guild agreements.
The EU AI Act's transparency requirements for generative systems are forcing disclosure of automated content creation in metadata fields. Publishers using synthetic narration must label outputs, creating consumer-facing friction that human-narrated premium tiers exploit for positioning. French regulators through CNIL are already probing whether undisclosed AI narration violates consumer protection statutes.
Subscription fatigue is compressing household willingness to maintain multiple reading services simultaneously. Dutch and German consumers are consolidating around single-platform bundles that combine e-books, audiobooks, and adjacent media. This consolidation is visible in Nordic churn data, where standalone e-book services lose subscribers to integrated entertainment packages unless they anchor exclusive original content catalogs.
Europe E-Book Market Segmentation
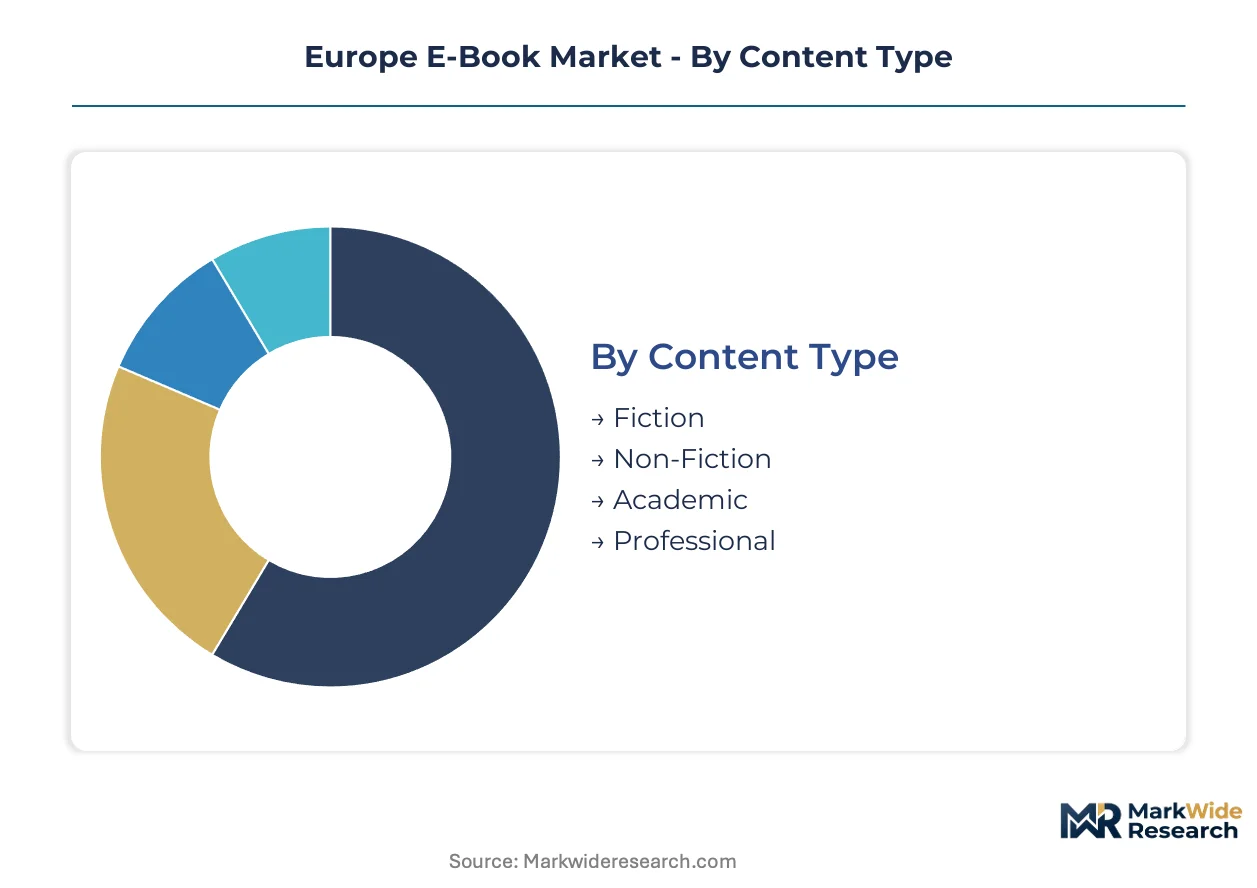
Segmentation reveals how revenue pools concentrate across content formats, hardware preferences, and distribution economics. Publishers and platforms configure strategy around which combinations of device, pricing, and channel capture the highest lifetime value per reader.
Content Type:
Fiction and non-fiction command the deepest margin pools through volume-driven consumer sales, while academic licensing generates premium per-unit economics despite smaller transaction counts.
- Fiction:Genre narratives across romance, thriller, and literary categories dominate transaction volume. German and French-language fiction drives the largest revenue concentration in consumer-facing platforms, supported by subscription bundling that reduces per-title price sensitivity.
- Non-Fiction:Biography, history, and self-improvement titles attract older demographics with higher disposable income. Dutch and Nordic markets show particular strength in non-fiction subscription attachment rates, where readers demonstrate lower churn than fiction-only subscribers.
- Academic:Licensed e-textbook repositories serve institutional procurement cycles across German universities and French grandes écoles.
- Professional:Legal, medical, and technical reference works target credential maintenance requirements and continuing education mandates.
The dominant share belongs to Fiction, while Academic is closing the gap fastest.
Device Type:
Hardware preferences split between dedicated reading experiences and multi-function convenience, with E Ink technology defending its position against LCD proliferation through battery endurance and eye strain reduction.
- E-Readers:Dedicated devices with E Ink displays and front-lighting systems deliver week-long battery life and paper-like readability. Germany and the Netherlands maintain the highest per-capita E-reader ownership in Europe, where consumers prioritize extended reading sessions over app ecosystem breadth.
- Smartphones:Ubiquitous penetration enables impulse purchases and snippet reading during commutes. Southern European markets show disproportionate smartphone-first consumption due to lower E-reader penetration and younger demographic skew.
- Tablets:Multi-purpose devices serve readers who alternate between e-books, video, and productivity applications.
- Computers:Large-screen PDF consumption dominates academic and professional segments where fixed-layout formatting preserves complex diagrams and tables.
E-Readers retain the installed base leadership, yet Smartphones are expanding most quickly among new reader acquisition.
Distribution Channel:
Channel economics diverge sharply between aggregator platforms that capture customer data and publisher-direct relationships that preserve margin but demand marketing investment.
- Online Retailers:Aggregator platforms with recommendation algorithms and one-click purchasing infrastructure. Amazon's Kindle store and Rakuten Kobo dominate France and Italy through device-software integration that locks consumers into proprietary ecosystems.
- Publisher Websites:Direct-to-consumer sales bypass platform fees but require independent payment processing and fulfillment infrastructure. German mid-size publishers are rebuilding direct channels to escape aggregator dependency.
- Libraries:Municipal and university lending systems under national e-lending frameworks. Netherlands and Belgium are integrating API-first lending platforms that reduce friction between patron discovery and content access.
- Direct Sales:Author platforms and niche publishers selling through email lists and community relationships.
Online Retailers capture the dominant transaction volume, while Libraries are climbing the fastest as e-lending frameworks mature.
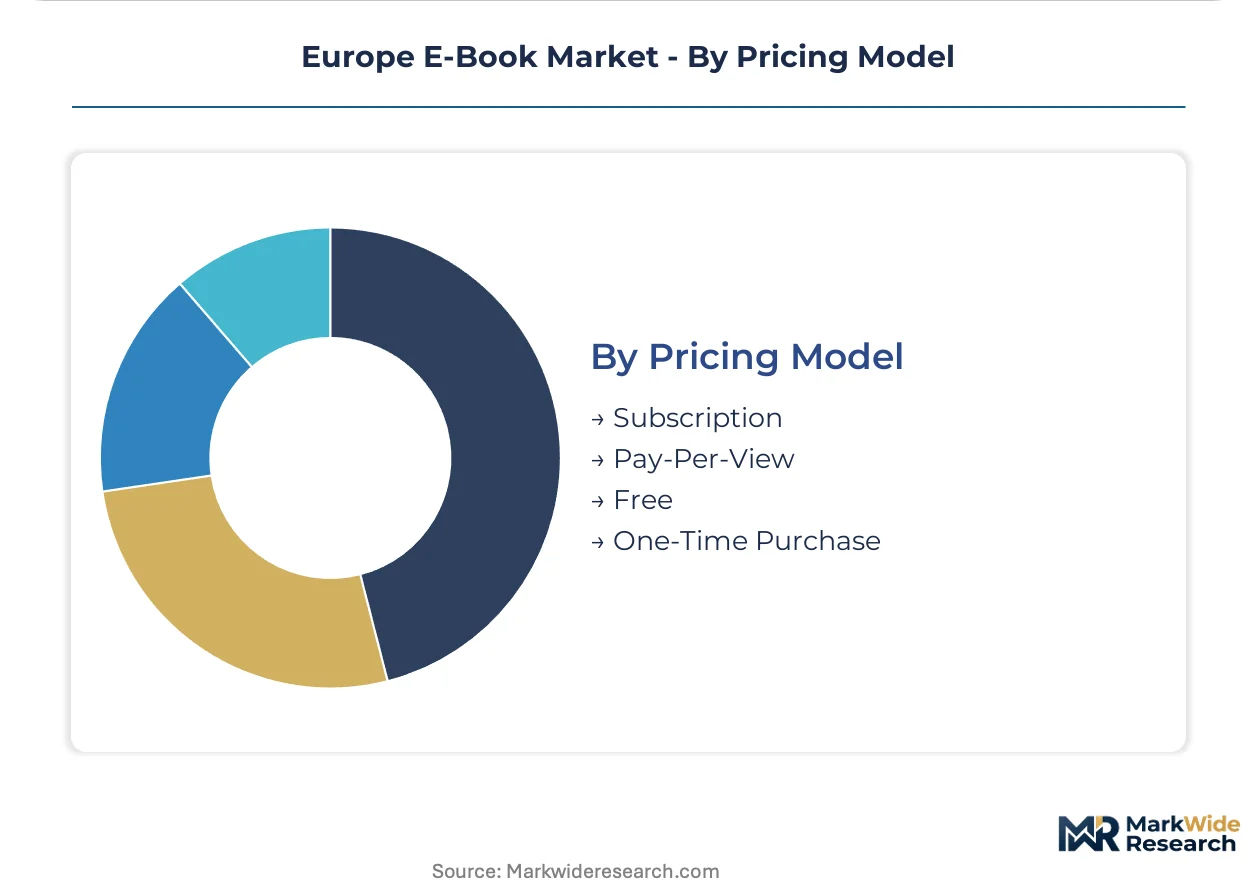
Pricing Model:
Revenue predictability versus transaction value trade-offs define competitive positioning, with subscription services capturing recurring commitment that one-time purchases cannot replicate.
- Subscription:Flat-fee access to catalogs with unlimited or capped monthly downloads. Storytel and equivalent services in Nordic and German-speaking markets demonstrate that dual-format bundling achieves retention rates standalone e-book offerings fail to match.
- One-Time Purchase:Perpetual license models with DRM restrictions that limit device transfers and resale. France and Italy maintain stronger one-time purchase preference than Northern Europe due to weaker subscription infrastructure.
- Pay-Per-View:Micro-transaction access to individual chapters or time-limited rentals.
- Free:Ad-supported or promotional distribution that builds readership for series or backlist monetization.
Subscription holds the dominant revenue share trajectory, while One-Time Purchase is defending position through premium frontlist releases and collector editions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's KBA-adjacent consumer protection bodies enforce compliance thresholds that determine market access for foreign distributors across the continent. Digital textbook adoption accelerates fastest in German and French academic corridors. Nordic subscription penetration outpaces Southern European markets by significant margins.
Germany
Institutional procurement of licensed e-textbook repositories drives structural demand growth across universities and Fachhochschulen. The KBA-adjacent consumer protection framework imposes data localization requirements that favor domestic platform operators. Berlin-Brandenburg hosts the densest concentration of EPUB production studios serving German-language markets.
France
Consumer preference for one-time purchases over subscription models sustains perpetual license revenue pools in fiction and non-fiction segments. CNIL probes undisclosed AI narration under consumer protection statutes, creating compliance visibility requirements for synthetic voice deployments. Paris anchors the largest French-language digital publishing workforce on the continent.
Netherlands
Municipal library systems seek API-first lending platforms that reduce friction between patron discovery and content access. National e-lending caps under EU Copyright Directive implementation standardize cross-border circulation terms. Randstad metropolitan clusters concentrate E-reader ownership at the highest per-capita rates in Europe.
Sweden
Dual-format bundling of audiobooks and e-books achieves retention rates that standalone offerings fail to replicate. GDPR consent management requirements impose lighter operational burdens on established Nordic platforms through scale advantages. Stockholm hosts Storytel's operational headquarters for regional subscription service expansion.
Italy
Smartphone-first consumption patterns dominate due to lower E-reader penetration and younger demographic skew across the peninsula. Digital publishing talent scarcity creates localization bottlenecks for EPUB production and metadata tagging pipelines. Milan concentrates the limited domestic expertise for reflowable text standard implementation.
Europe E-Book Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the European e-book ecosystem. Aggregator platforms with device-software integration capture consumer lock-in through proprietary DRM ecosystems, while hardware-software specialists compete via library partnership networks. Three archetypes dominate: ecosystem-integrated giants, regional subscription bundlers, and hardware-centric specialists. Competitive moves concentrate on exclusive content catalog acquisition and API-first municipal lending platform provisioning.
Among ecosystem-integrated players, Amazon.com Inc. and Rakuten Kobo Inc. exemplify the device-software lock-in model that sustains distribution dominance across France and Italy. Storytel AB anchors the regional subscription bundler archetype through Nordic audiobook-e-book integration. These three companies represent the strategic poles—ecosystem integration, format bundling, and hardware specialization—around which mid-tier competitors must differentiate.
| Leading Market Players |
|---|
| Alphabet Inc. |
| Storytel AB |
| Amazon.com Inc. |
| PocketBook International |
| BookBeat GmbH |
| Rakuten Kobo Inc. |
| Tolino Media GmbH & Co. KG |
| Bookeen |
| Apple Inc. |
| Others |
Supply & Pricing Matrix
EPUB 3 replacing legacy PDF workflows is redrawing production geography toward Berlin-Brandenburg and Amsterdam clusters while compressing unit economics for fixed-layout formats. This substitution simultaneously elevates subscription pricing power in German-speaking markets and erodes per-title transactional margins in Southern Europe where smartphone-first consumption dominates.
Pricing Analysis
German and Dutch markets command premium subscription rates that Italian and Spanish markets cannot sustain. Three-tier pricing structure across premium human-narrated audiobooks, standard reflowable e-books, and economy synthetic-voice tiers separates willingness-to-pay segments. Cost compression in the economy tier is intensifying because AI narration tools collapse production timelines. Academic procurement officers show lowest price sensitivity while smartphone-first casual readers exhibit highest churn at marginal price increases.
Supply Chain Analysis
Digital inventory eliminates physical lead times yet creates dependency on cloud infrastructure latency and DRM authentication servers. Content production concentrates in Germany, the Netherlands, and Sweden where EPUB expertise and metadata tagging talent pools are deepest. Raw material inputs draw from human narrator guilds, synthetic voice engines, and publishing rights databases. Single-source vulnerability sits with Amazon Web Services hosting dominance for major distributor platforms. Distribution runs through aggregator APIs, publisher-direct storefronts, and library lending integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against short-form video and social media fragmenting reader attention spans. Incumbents must demonstrate that immersive long-form consumption retains value propositions that algorithmic feeds cannot replicate.
For Market Incumbents: Secure exclusive original content catalogs that anchor subscriber retention against entertainment bundle competitors. Deepen backward integration into synthetic narration production to capture margin from AI-displaced studio costs. Defend against subscription fatigue by demonstrating measurable reading outcomes that justify recurring fees.
For New Entrants and Emerging Players: Anchor in municipal library API partnerships across Belgium and the Netherlands where procurement friction remains highest. Target professional and legal reference segments where credential maintenance mandates create sticky demand. Pursue direct-to-institution sales bypassing aggregator fees through compliance with national e-lending frameworks.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform-integrated players with device-software lock-in capabilities. Long-term viability hinges on controlling discovery algorithms and retention data rather than content production alone. Watch Nordic churn rates as the inflection indicator for subscription model saturation across continental markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Audiobook-E-book Bundling | Dual-format subscriptions in Nordic markets achieve retention rates that standalone offerings fail to match. |
| Library API Integration | Municipal systems in Netherlands and Belgium seek API-first lending platforms reducing patron friction. |
| Synthetic Voice Production | AI narration collapses studio timelines for German non-fiction and instructional content backlists. |
| Academic Licensing Expansion | German Fachhochschulen procurement cycles create institutional demand pools beyond consumer sales. |
| EPUB 3 Accessibility Compliance | Reflowable text standards enable multimedia integration that static PDF distribution cannot support. |
Research Methodology
Operator-level perspectives from platform product managers, publisher digital directors, library systems integrators, and narrator guild representatives anchored the qualitative base. Secondary validation drew from EU Digital Services Act implementation documents, national e-lending framework filings, GDPR enforcement actions by CNIL, and academic procurement database disclosures. Bottom-up segment sizing triangulated against top-down market envelope estimates from trade association releases and device shipment tracking.
Sensitivity analysis tested forecast robustness across alternative DRM interoperability scenarios and AI narration adoption curves over the projection horizon. The analytical framework modeled content type, device preference, distribution channel, and pricing model dimensions alongside regional regulatory cluster variations. CAGRs derived from segment-level growth rate blending weighted by revenue concentration. Forecast inputs incorporated university digital transition timelines and synthetic voice quality improvement trajectories.
Material uncertainties — regulatory enforcement timing for EU AI Act disclosure mandates, national e-lending cap revisions, and subscription fatigue inflection points — sit outside the modeled envelope. Forecasts reflect documented assumptions about platform consolidation pace and hardware-software integration durability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Publishing
Middle East Catalog Market
Digital Publishing
Digital Comics Platform Market
Digital Publishing
Digital Publishing Platforms Market
Digital Publishing
Africa Catalog Market
Digital Publishing
Adaptive Content Publishing Market
Digital Publishing
Magazine Subscription Service Market
Digital Publishing
Ebook Publishing Platform Market
Digital Publishing
Children Illustration Book Market
Digital Publishing
Mexico Commercial Printing Market
Digital Publishing
Comic Book Market
Digital Publishing
GCC Commercial Printing Market
Digital Publishing
Digital Newspapers and Magazines Market
Digital Publishing
Newspaper Market
Digital Publishing
Global E-Book Market
Digital Publishing
Digital Comics Distribution and Consumption Platforms Market
Digital Publishing
Digital Music Publishing Market