
 Plant Asset Management (PAM) Market | 2026-2036
Plant Asset Management (PAM) Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Asset Management (PAM) Market Analysis
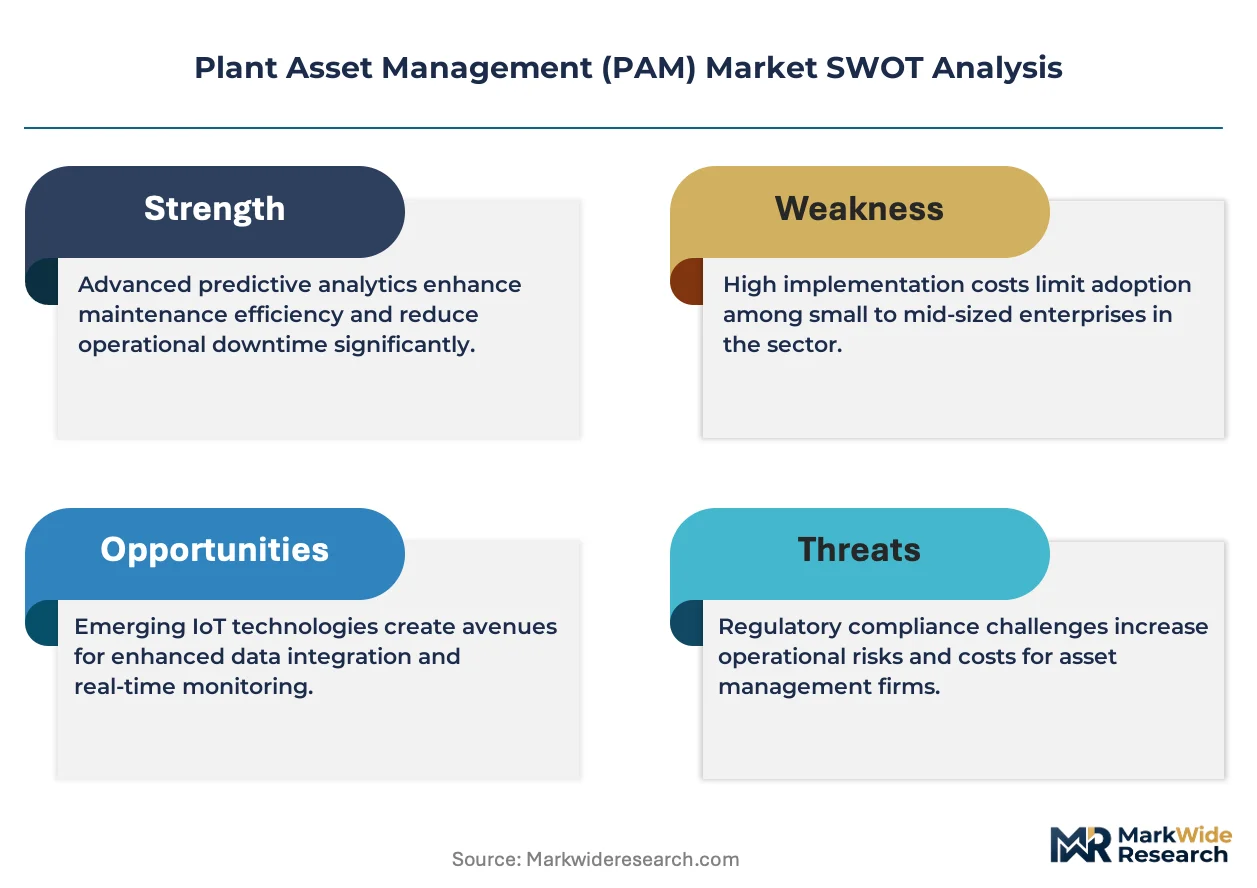
Asset-light leasing and subscription-based financing for industrial software is fragmenting competitive dynamics across the PAM landscape. Emerson Electric leverages its embedded hardware-software stack to anchor long-term service contracts. Siemens competes through its digital twin integration, while Yokogawa Electric Corporation specializes in process-industry deployments across energy and chemical verticals.
Plant Asset Management encompasses integrated software and hardware systems that monitor, diagnose, and optimize physical industrial equipment through real-time data acquisition, condition-based analytics, and automated workflow orchestration. These systems typically interface with distributed control systems and enterprise asset management platforms to reduce unplanned downtime and extend operational life. Software and services currently capture the dominant margin pool as recurring revenue models replace perpetual licenses. IoT and AI segments are expanding fastest as edge-computing architectures enable predictive maintenance at scale, while hardware remains comparatively mature with slower replacement cycles.
ISO 55000 asset management standards, OSHA process safety mandates, and EPA emissions monitoring requirements collectively shape product specifications and procurement criteria across industrial end users. The EU AI Act and emerging MEE guidelines in China are adding algorithmic transparency and data governance layers to PAM system design. Stakeholders must weigh interoperability investments against regulatory compliance timelines as jurisdiction-specific requirements diverge.
Market Dynamics
Cloud-native architectures are dismantling the installed base of on-premise Plant Asset Management systems, forcing incumbents to restructure pricing models and channel relationships around recurring revenue streams rather than perpetual licensing.
Growth Catalysts
- OSHA Process Safety Management:Mandates for continuous monitoring of high-hazard chemical processes drive replacement of manual inspection regimes with automated condition monitoring systems across US refineries and petrochemical complexes.
- Edge AI inference:On-device machine learning models enable real-time anomaly detection without cloud latency, accelerating predictive maintenance deployment in offshore oil platforms with intermittent connectivity.
- Germany:Industrial clusters in the Ruhr and Bavaria concentrate demand for integrated PAM solutions as chemical and automotive manufacturers pursue ISO 55000 certification to access export markets.
Market Restraints
- Semiconductor component volatility:Lead times for industrial-grade sensors and edge processors fluctuate unpredictably, compressing hardware margins and delaying system deployment schedules.
- EU AI Act algorithmic transparency:Documentation requirements for automated decision-making systems add compliance overhead to predictive maintenance deployments, slowing procurement cycles for European operators.
- Substitute: In-house data science teams:Large oil and gas majors build proprietary analytics capabilities using open-source frameworks, bypassing vendor platforms for non-critical asset classes.
Strategic Opportunities
- India:PLI scheme incentives for chemical and pharmaceutical manufacturing create first-mover advantage for PAM vendors establishing localized service infrastructure before competitive saturation.
- Digital twin convergence with PAM:Unified platforms combining asset health monitoring with process simulation command premium pricing in complex continuous-process industries.
- China MEE emissions monitoring:Mandatory continuous emissions monitoring systems for heavy industry create bundled demand for integrated environmental and asset performance management.
Industry Challenges
- Cyber-physical systems engineering expertise:Shortage of professionals capable of bridging operational technology and information technology domains constrains implementation velocity for integrated PAM deployments.
- Legacy DCS integration complexity:Proprietary communication protocols in decades-old distributed control systems require costly middleware development to enable seamless data extraction for modern analytics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Asset Management (PAM) Market |
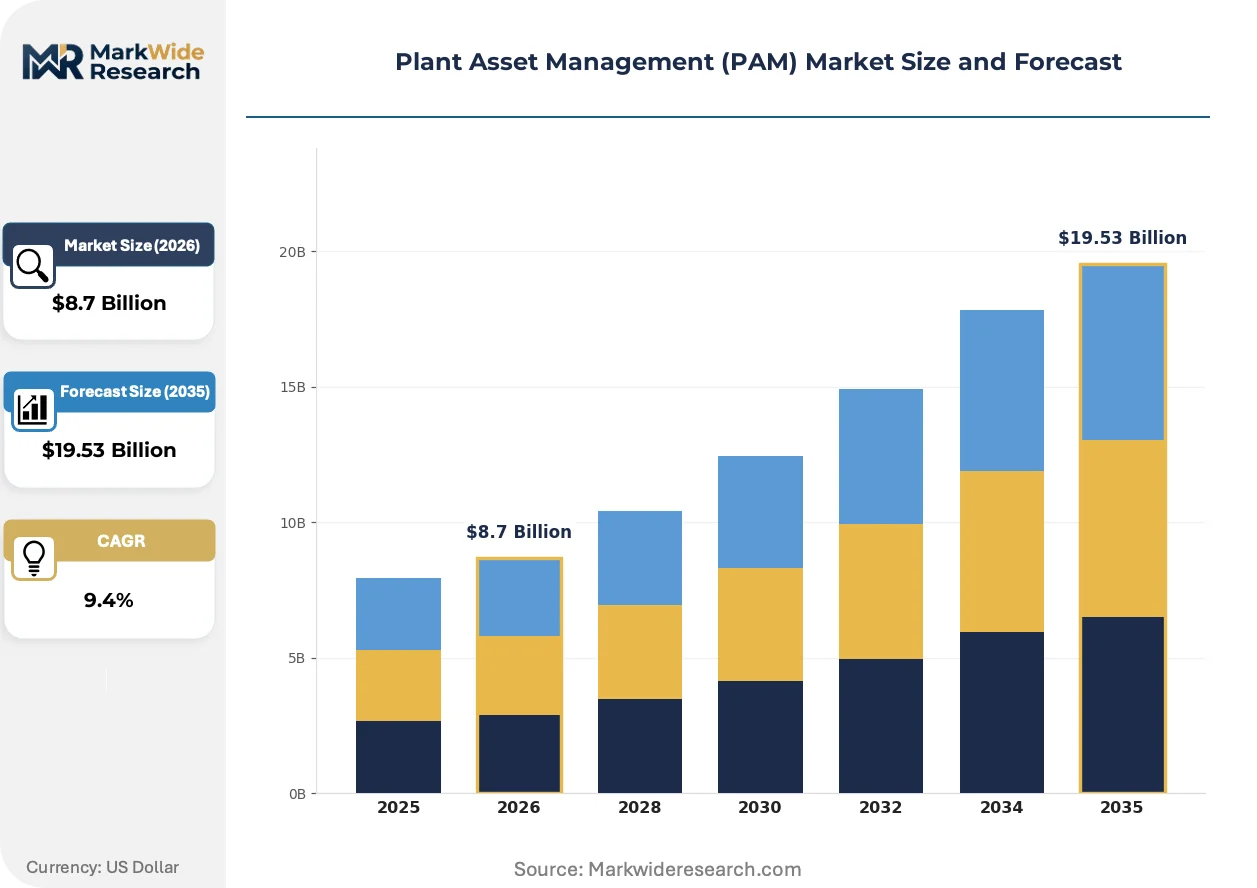
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Services, Solutions Technology: IoT, AI, Cloud Computing, Big Data End User: Manufacturing, Utilities, Oil & Gas, Transportation Application: Predictive Maintenance, Compliance Management, Asset Optimization, Risk Management |
| Companies Covered | Rockwell Automation, Honeywell International, Emerson Electric, AVEVA Group, Aspen Technology, Siemens, Schneider Electric, Yokogawa Electric Corporation, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Asset Management (PAM) Market Emerging Trajectories
Computational architectures and contracting frameworks are converging to compress deployment timelines and shift value capture toward software layers, altering competitive positioning across the PAM ecosystem.
Digital twin platforms are virtualizing physical asset representation by creating persistent software models that mirror equipment behavior in real time. Chemical manufacturers in Germany and the Netherlands adopt these systems fastest, driven by regulatory pressure for documented asset integrity. This virtualization is compressing the distinction between design-phase simulation and operational-phase monitoring, enabling closed-loop optimization that was previously technically infeasible.
The EU AI Act imposes risk-based classification and human oversight requirements on automated maintenance recommendation systems. Industrial software vendors must now embed explainability features and audit trails into predictive algorithms, increasing development costs but creating compliance-based differentiation. Process industries with safety-critical assets face the steepest adaptation burden, with German chemical operators already restructuring procurement criteria to prioritize certified algorithmic transparency.
Asset-as-a-service contracting is displacing capital purchase models for monitoring hardware, with operators preferring per-asset monthly fees that bundle sensors, connectivity, and analytics. This unbundling of ownership from operation disrupts traditional distributor relationships and concentrates buyer power among large fleet operators. The shift is most advanced in US shale basins, where private equity-backed producers prioritize operational flexibility over balance sheet asset ownership.
Plant Asset Management (PAM) Market Segmentation
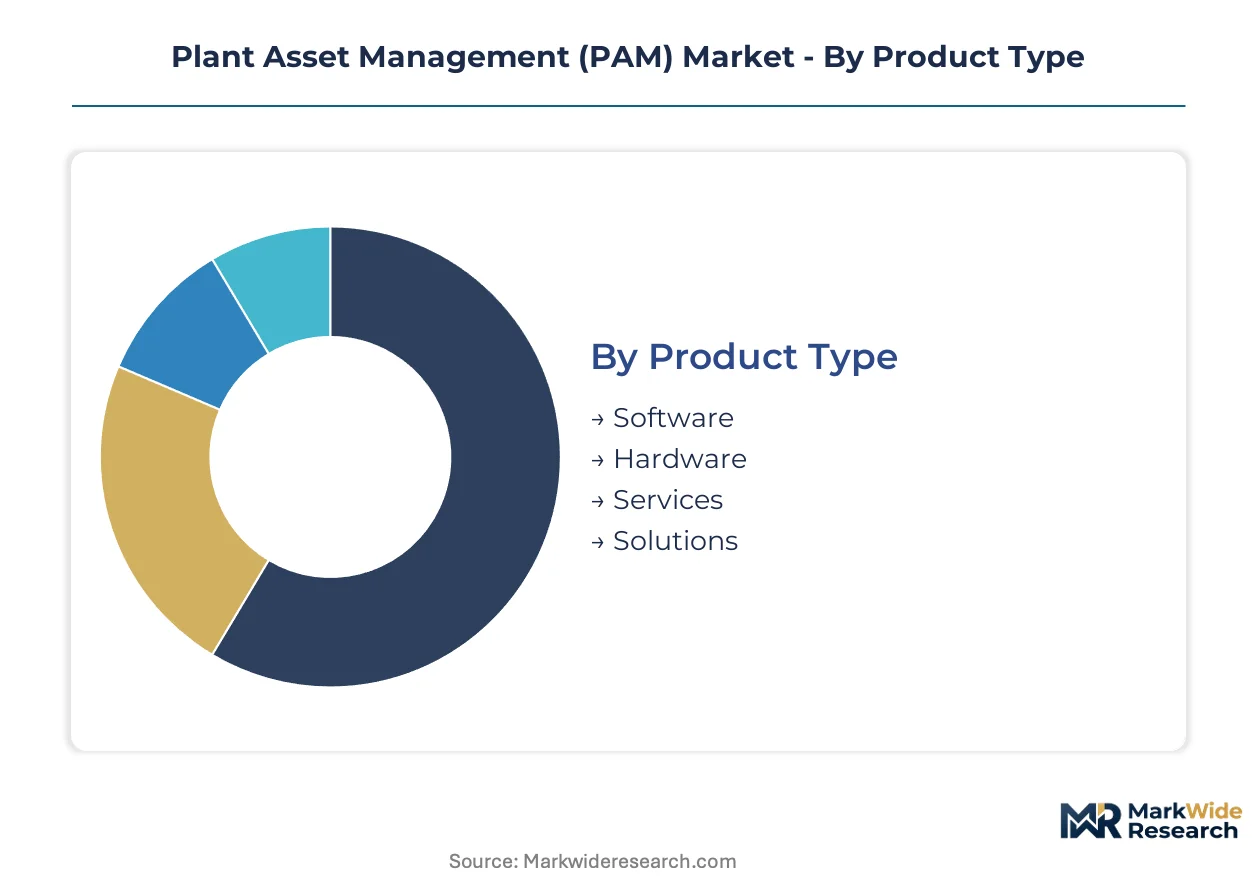
Plant Asset Management systems fragment across multiple technical and commercial dimensions, with software and services exhibiting shorter replacement cycles than hardware infrastructure. Understanding these segment dynamics clarifies where procurement budgets concentrate and how vendor business models must adapt to capture recurring revenue streams.
Product Type:
Software turns over fastest as cloud-native architectures displace perpetual licenses, while hardware sensors and edge devices operate on multi-year depreciation schedules.
- Software:Cloud-deployed analytics platforms and mobile-native diagnostic applications dominate new procurement. US refineries and German chemical clusters drive replacement of legacy on-premise systems with subscription-based condition monitoring tools.
- Services:Implementation consulting, system integration, and ongoing technical support capture expanding margin pools as operators lack internal OT-IT expertise. Demand concentrates among mid-sized manufacturers in India seeking PLI scheme compliance without building captive capabilities.
- Hardware:Industrial-grade sensors, edge processors, and communication gateways with slower replacement cycles.
- Solutions:Bundled hardware-software-service packages tailored to specific vertical requirements.
Software anchors the volume base while Services gains share at the steepest rate.
Technology:
Cost tier separates proven connectivity infrastructure from emerging AI layers commanding premium pricing.
- IoT:Sensor networks and edge connectivity form the foundational data acquisition layer. Oil and gas operators in US shale basins deploy ruggedized IoT hardware for remote asset monitoring where connectivity is intermittent.
- AI:Machine learning models for predictive maintenance and anomaly detection represent the highest-value software layer. EU AI Act compliance requirements add development overhead but create differentiation for vendors with certified algorithmic transparency.
- Cloud Computing:Scalable compute and storage infrastructure displacing on-premise data centers.
- Big Data:Historical data lakes and batch analytics for long-term asset degradation modeling.
IoT generates the broadest deployment footprint while AI commands the steepest expansion trajectory.
End User:
Application maturity varies sharply across verticals, with process industries leading continuous monitoring adoption.
- Oil & Gas:Upstream, midstream, and downstream operators deploy PAM for safety-critical pressure vessel monitoring and emissions compliance. OSHA Process Safety Management mandates drive automated condition monitoring across US refineries and petrochemical complexes.
- Manufacturing:Discrete and process manufacturers pursue ISO 55000 certification for export market access. German automotive and industrial machinery producers in Bavaria and Baden-Württemberg concentrate demand for integrated asset health platforms.
- Utilities:Power generation and grid infrastructure operators managing aging asset bases.
- Transportation:Rail, maritime, and logistics fleets requiring mobile asset tracking.
Oil & Gas anchors capital deployment while Manufacturing climbs fastest as certification requirements spread.
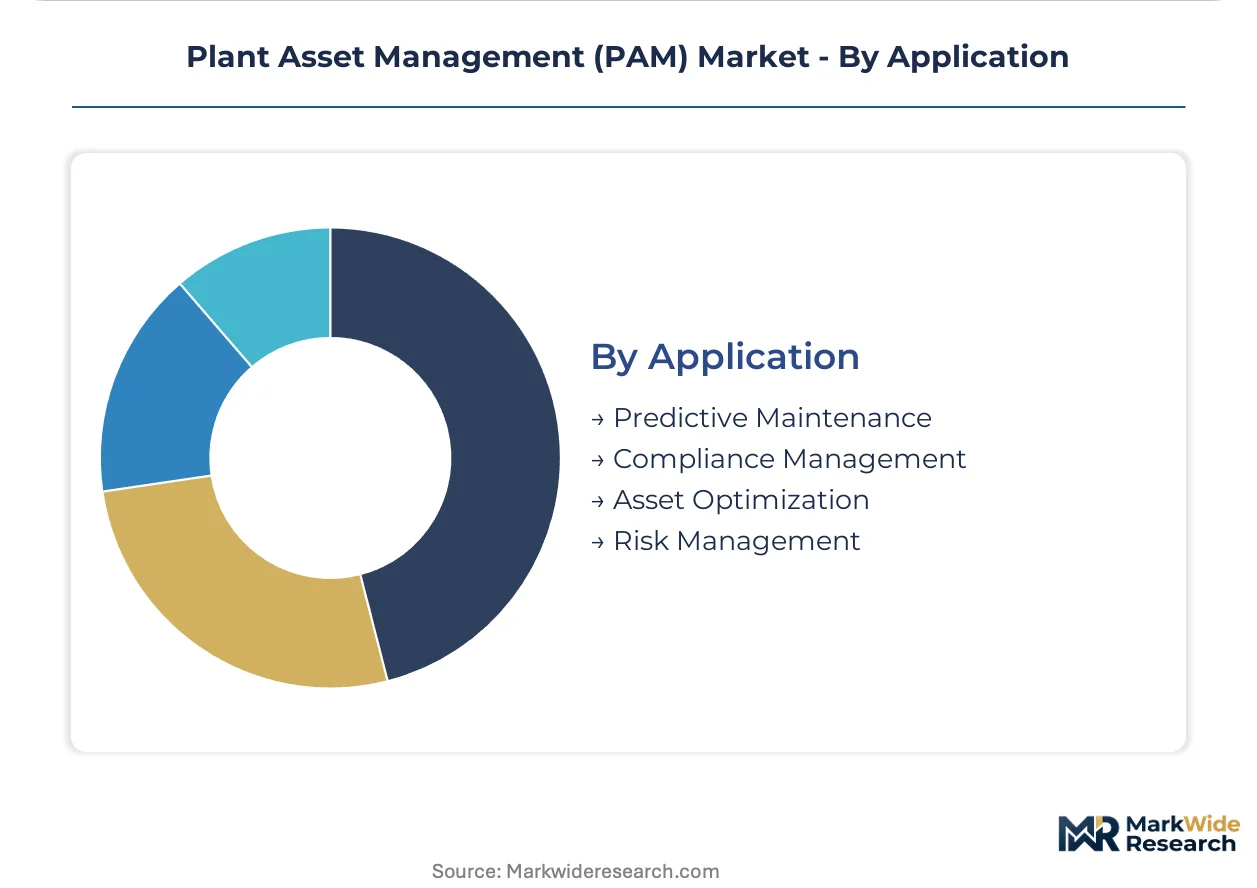
Application:
Customer type separates compliance-driven procurement from discretionary optimization spending.
- Predictive Maintenance:Real-time anomaly detection and failure forecasting to minimize unplanned downtime. Offshore oil platforms with intermittent satellite connectivity deploy edge AI inference for immediate equipment intervention without cloud dependency.
- Compliance Management:Regulatory documentation and audit trails for safety and environmental mandates. China MEE emissions monitoring requirements create bundled demand for integrated environmental and asset performance tracking in heavy industry.
- Asset Optimization:Performance tuning and lifecycle extension beyond basic reliability.
- Risk Management:Quantified reliability engineering and insurance-linked asset valuation.
Compliance Management anchors procurement volume while Predictive Maintenance expands most quickly as edge computing matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government incentives and regulatory mandates are redirecting capital flows toward digital infrastructure upgrades across major industrial economies. National emissions monitoring programs and process safety requirements accelerate PAM procurement timelines. Industrial clusters in chemical, automotive, and energy verticals concentrate deployment activity.
United States
OSHA Process Safety Management mandates drive automated condition monitoring replacement across Gulf Coast refineries and Appalachian shale basins. The EPA's continuous emissions monitoring requirements for petroleum refineries bundle environmental compliance with asset health tracking. Houston and Beaumont industrial corridors anchor demand for edge-computing architectures that operate with intermittent connectivity.
Germany
ISO 55000 certification requirements for export market access push chemical and automotive manufacturers toward integrated asset platforms. The EU AI Act's algorithmic transparency rules reshape procurement criteria for predictive maintenance systems in safety-critical applications. Ruhr Valley chemical complexes and Bavarian automotive plants in Munich-Stuttgart corridor lead digital twin adoption for asset integrity documentation.
China
MEE mandatory continuous emissions monitoring systems for heavy industry create bundled demand for integrated environmental and asset performance management. Dual carbon goals accelerate replacement of manual inspection regimes with automated monitoring across steel and petrochemical facilities. Yangtze River Delta manufacturing clusters in Shanghai-Jiangsu-Zhejiang concentrate procurement for cloud-native PAM platforms.
India
PLI scheme incentives for chemical and pharmaceutical manufacturing attract first-mover PAM vendors establishing localized service infrastructure. Central Electricity Authority grid modernization mandates drive asset monitoring deployment across aging thermal power plants. Gujarat and Maharashtra industrial corridors in Vadodara-Surat and Mumbai-Pune clusters exhibit fastest adoption growth for subscription-based condition monitoring.
Japan
METI industrial digitalization subsidies support predictive maintenance deployment across aging downstream oil infrastructure and chemical complexes. JIS standards for industrial IoT interoperability reduce integration friction for multi-vendor sensor networks. Keiyo Coastal Industrial Zone in Chiba and Osaka Bay petrochemical clusters prioritize edge AI inference for real-time anomaly detection.
Plant Asset Management (PAM) Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where bundled hardware-software-service packages command premium positioning against modular component vendors. The market exhibits consolidated leadership at the platform layer with fragmented specialization in vertical-specific applications. Three archetypes dominate: integrated automation conglomerates with embedded hardware-software stacks, pure-play software vendors with cloud-native analytics platforms, and regional system integrators with localized implementation expertise. Competitive dynamics center on strategic partnerships for edge computing deployment and portfolio diversification into digital twin convergence.
Among integrated automation conglomerates, Emerson Electric, Siemens, and Yokogawa Electric Corporation occupy positions that exemplify distinct competitive vectors. Emerson Electric represents the hardware-anchored service contract model. Siemens exemplifies digital twin integration capabilities. Yokogawa Electric Corporation sits within the process-industry specialization archetype for energy and chemical verticals. These three anchors illustrate how geographic origin and corporate structure shape strategic positioning without converging on identical capability stacks.
| Leading Market Players |
|---|
| Rockwell Automation |
| Honeywell International |
| Emerson Electric |
| AVEVA Group |
| Aspen Technology |
| Siemens |
| Schneider Electric |
| Yokogawa Electric Corporation |
| ABB |
| Others |
Supply Flow & Price Mechanics
Ruhr Valley industrial clusters anchor sensor and edge hardware production for European PAM deployments, with capacity utilization rates directly transmitting into pricing leverage for system integrators serving German chemical manufacturers. Cloud-native software layers decouple from this hardware base, enabling SaaS vendors to capture margin expansion even when sensor supply tightens.
Pricing Analysis
Certification level (ISO 55000/CE/FDA-grade) creates the primary spread between premium and standard tiers. Three-tier pricing structure across certified, compliant, and basic levels dominates, with subscription SaaS models displacing perpetual licenses fastest. Pricing pressure stems from open-source analytics alternatives in non-critical asset monitoring. Mid-sized manufacturers in India exhibit highest price sensitivity, while US oil and gas majors prioritize certified algorithmic transparency over cost.
Supply Chain Analysis
Tariff exposure between US and China dominates supply chain risk planning for edge processor procurement. Semiconductor fabrication concentrates in Taiwan, South Korea, and China, with industrial-grade sensor assembly anchored in Germany and Japan. Raw material dependencies span rare earth elements for magnetic sensors, silicon wafers for edge chips, and specialized polymers for ruggedized housings. Single-source vulnerability persists for radiation-hardened components used in nuclear and aerospace applications. Distribution runs through authorized system integrators with OT-IT certification rather than direct OEM sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plant Asset Management is approaching a platform-economics inflection where interoperability standards determine winner-take-most dynamics. The convergence of digital twin architectures with edge AI inference is rewiring competitive moats around ecosystem integration rather than point-product superiority.
For Market Incumbents: Insulate recurring revenue streams by embedding proprietary hardware-software stacks into long-term service contracts. Deepen backward integration into edge processor design to reduce exposure to semiconductor lead time volatility. Prioritize ISO 55000 certification pre-qualification for procurement shortlists in German chemical and automotive verticals. For New Entrants and Emerging Players: Pursue white-space opportunities in India's PLI scheme-subsidized chemical and pharmaceutical manufacturing corridors, where localized service infrastructure remains underdeveloped. Target mid-tier manufacturers seeking compliance-managed subscriptions without captive OT-IT expertise. Lead with mobile-native diagnostic applications that bypass legacy DCS integration complexity. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors cloud-native analytics platforms with proven EU AI Act compliance pathways. Long-term viability hinges on recurring revenue share expansion and vertical integration depth. Watch for inflection signals in edge AI inference deployment velocity at offshore oil platforms with intermittent connectivity.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Integration | Unifies asset health monitoring with process simulation for German chemical operators seeking ISO 55000 certification. |
| Edge AI Inference Deployment | Enables real-time anomaly detection without cloud latency for offshore oil platforms with satellite connectivity constraints. |
| Backward Integration into Sensors | Captures margin pool and reduces lead time exposure for industrial-grade edge processors and communication gateways. |
| EU AI Act Compliance Certification | Creates procurement differentiation as German chemical operators restructure criteria around algorithmic transparency mandates. |
| India PLI Scheme Localization | Establishes first-mover service infrastructure before competitive saturation in Gujarat and Maharashtra industrial corridors. |
Methodological Framework
A standing panel of maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads provided ongoing calibration against operating reality. Primary fieldwork combined structured interviews with secondary validation through SEC 10-K filings, customs and trade data, and industrial automation association reports. Bottom-up deployment tracking across oil refineries, chemical complexes, and automotive plants triangulated against top-down vendor revenue analysis.
Scenario-bracketing around regulatory implementation timelines and semiconductor supply recovery paths bounded the projection range. Segmentation dimensions spanned deployment architecture, end-user vertical, application criticality, and regional regulatory cluster. CAGRs derived from fitted growth curves against historical replacement cycle data and announced capacity expansion timelines. Edge AI adoption velocity and cloud-native migration rates served as key forecast sensitivity inputs.
Sensitivities concentrate around EU AI Act enforcement pacing, China MEE emissions monitoring mandate rollout, and industrial semiconductor lead time normalization. Forecasts embed assumptions regarding regulatory compliance cost pass-through and substitution elasticity for open-source analytics alternatives. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
API Monetization Platform Market
Digital Solutions
Contactless Ticketing Ics Market
Digital Solutions
Electronic Data Interchange (EDI) Market
Digital Solutions
Webrtc Market
Digital Solutions
Container Orchestration Market
Digital Solutions
Fuel Management Software Market
Digital Solutions
Cloud-Based Product Lifecycle Management (PLM) Market
Digital Solutions
Product Design and Development Services Market
Digital Solutions
Asia-Pacific Digital Marketing Software Market
Digital Solutions
North America Digital Signage Market
Digital Solutions
Next Generation Search Engines Market
Digital Solutions
North America Digital Pen Market
Digital Solutions
Video Management System Market
Digital Solutions
Data Integration Market
Digital Solutions
Super Apps Market
Digital Solutions
Epedigree Software Market