
 Enterprise Web Development Outsourcing Services Market | 2026-2036
Enterprise Web Development Outsourcing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise Web Development Outsourcing Services Market Insights
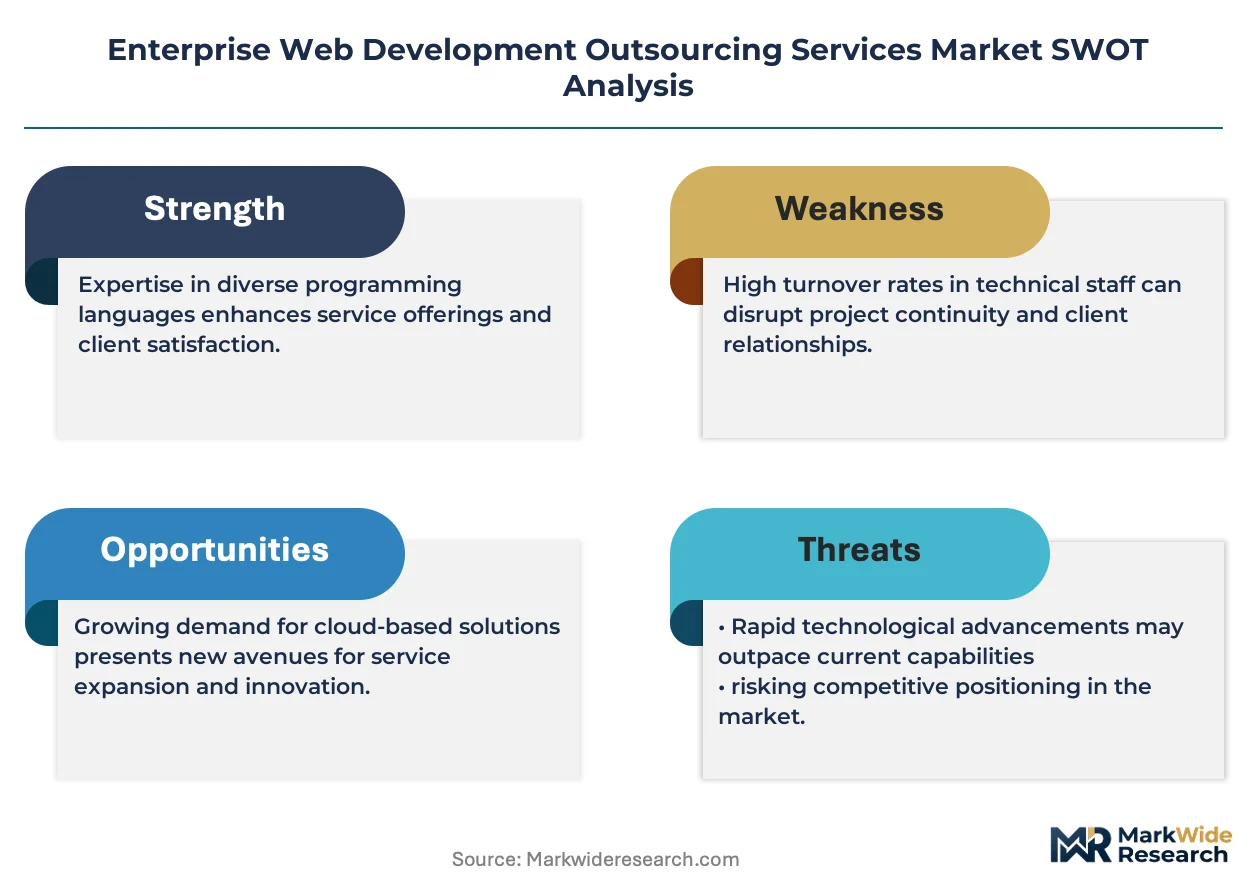
Healthcare provider investment in patient portals and compliance-driven web infrastructure is repositioning the buyer mix toward regulated industries. ScienceSoft leverages deep vertical expertise in HIPAA-compliant healthcare platforms to sustain premium positioning. Radixweb anchors its competitive stance through specialized fintech and telecom delivery centers in Eastern Europe. Intellectsoft differentiates via concentrated R&D in enterprise blockchain-integrated web architectures.
Enterprise web development outsourcing services encompass the external procurement of full-stack design, engineering, deployment, and maintenance for complex organizational web platforms, typically delivered through distributed agile teams operating across multiple time zones. These services integrate continuous integration pipelines, automated testing protocols, and API-first architectures to ensure scalable performance under enterprise-grade security and uptime requirements. Custom Web Applications and E-Commerce Platforms command the largest current revenue pools, while Cloud-Based and Multi-Cloud deployment models represent the fastest-expanding structural segments as enterprises retire on-premises legacy stacks. Agile and DevOps methodologies dominate delivery contracts, though Waterfall persists in government and banking procurement where audit trails and fixed-scope compliance override velocity metrics.
US HIPAA and SEC cybersecurity disclosure rules tighten vendor qualification standards, while EU GDPR and the EU AI Act impose cross-border data governance obligations on outsourced development teams handling European enterprise data. India's BIS IT service standards and PLI scheme incentives shape supplier certification requirements for export-oriented delivery centers. Stakeholders must monitor how fragmented regulatory compliance costs across multiple jurisdictions alter total cost of ownership calculations for multi-country outsourcing arrangements.
Market Dynamics
Cloud-native architecture migration is compressing procurement cycles as enterprises retire monolithic stacks, forcing vendors to restructure delivery teams around containerization and microservices expertise.
Growth Catalysts
- HIPAA compliance mandates:US healthcare providers are expanding outsourced patient portal budgets as HIPAA security rule enforcement tightens, creating specialized demand for compliant development workflows.
- India's PLI scheme incentives:Export-oriented IT service clusters in Bengaluru and Hyderabad receive production-linked incentives that lower talent acquisition costs for Western buyers.
- API-first architecture adoption:Enterprise buyers are mandating headless commerce and service mesh integration, pulling demand toward vendors with mature DevOps pipelines.
Market Restraints
- GDPR cross-border friction:EU data governance obligations impose legal complexity on Indian and Eastern European delivery centers handling European enterprise data.
- Cloud infrastructure cost volatility:AWS, Azure, and GCP pricing fluctuations compress margins on fixed-bid outsourcing contracts.
- Legacy system entrenchment:COBOL and mainframe-dependent financial institutions resist full-stack replacement, fragmenting vendor addressable market.
Strategic Opportunities
- EU AI Act compliance services:European enterprises require outsourced development teams to embed algorithmic accountability into web platforms, creating premium service tiers.
- Blockchain-integrated architectures:Convergence of distributed ledger technology with enterprise web platforms opens specialized R&D contracting for supply chain and finance verticals.
- Nearshore Eastern Europe expansion:Poland and Romania delivery centers capture German and Nordic buyers seeking timezone alignment with GDPR-native operations.
Industry Challenges
- Kubernetes and service mesh skill scarcity:Container orchestration expertise concentrates in senior engineers, inflating compensation and extending project ramp times.
- Multi-jurisdiction certification timelines:SOC 2, ISO 27001, and BIS IT service standard audits delay vendor qualification by six to twelve months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise Web Development Outsourcing Services Market |
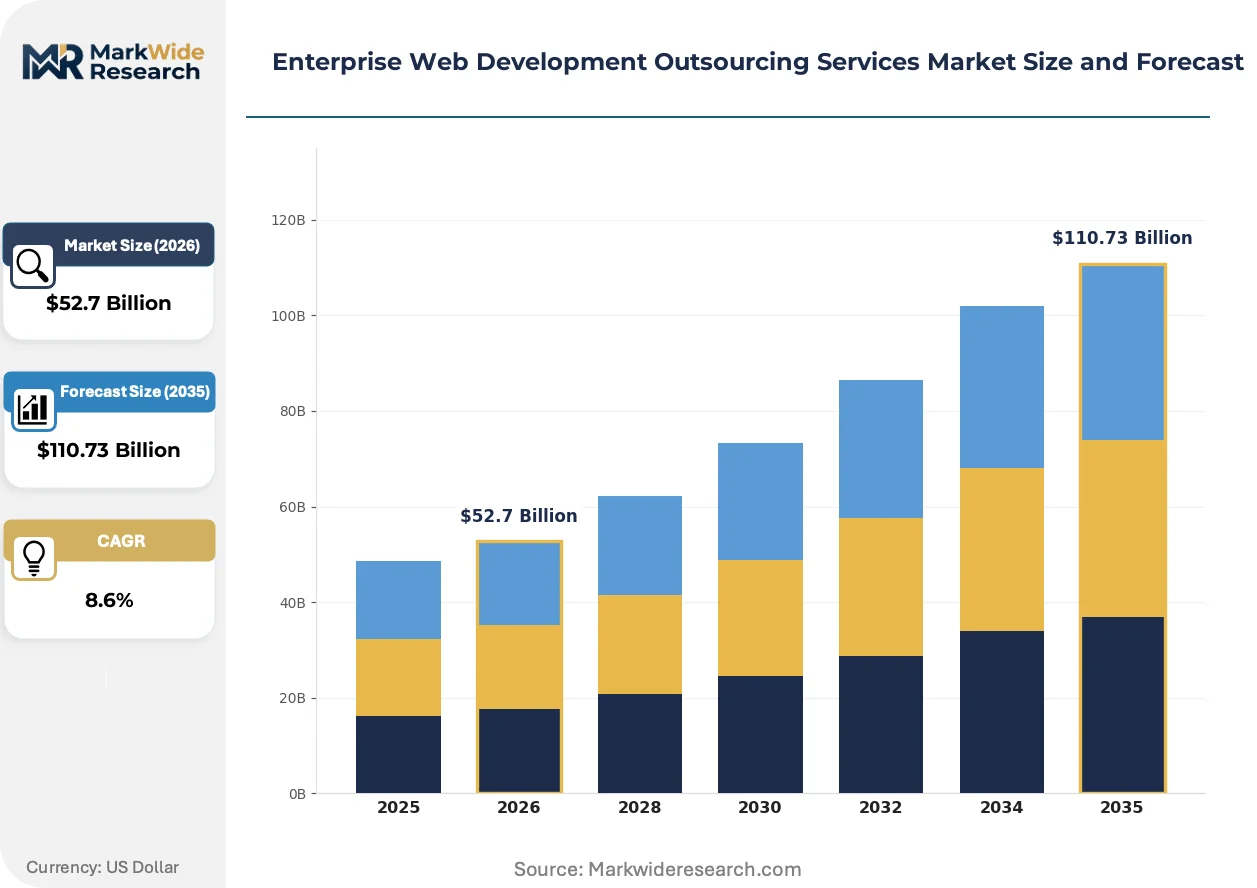
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $110.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Custom Web Applications, CMS Development, E-Commerce Platforms, Web Portal Development, Legacy System Migration Deployment Model: On-Premises, Cloud-Based, Hybrid, Multi-Cloud, Private Cloud Client Industry: Banking, Telecommunications, Education, Government, Consumer Electronics Development Methodology: Agile, Waterfall, DevOps, Scrum, Lean |
| Companies Covered | Suffescom Solutions, Devox Software, Radixweb, ScienceSoft, Classic Informatics, Intellectsoft, Digital Silk, Dotsquares, Infinum, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise Web Development Outsourcing Services Market Trends and Innovations
Enterprise web development is restructuring around platform engineering disciplines and compliance-embedded delivery models. Vendors are repositioning talent pools and certification portfolios to match.
Platform engineering is absorbing traditional DevOps functions as enterprises internalize self-service infrastructure tooling. Healthcare and fintech buyers are adopting internal developer platforms at the fastest clip. This consolidation is absorbing mid-tier managed service providers into specialized platform consultancies.
The EU AI Act is mandating algorithmic transparency documentation for high-risk web applications. Development contracts now require embedded ethics review and bias testing protocols. Healthcare portals and credit-scoring platforms face the steepest compliance retrofit costs.
Fixed-scope waterfall contracts are losing share to sprint-based engagement models with embedded quality gates. Banking and government buyers remain the holdouts, though even these segments are piloting hybrid frameworks. Germany and France show the fastest erosion of traditional procurement patterns.
Enterprise Web Development Outsourcing Services Market Segmentation
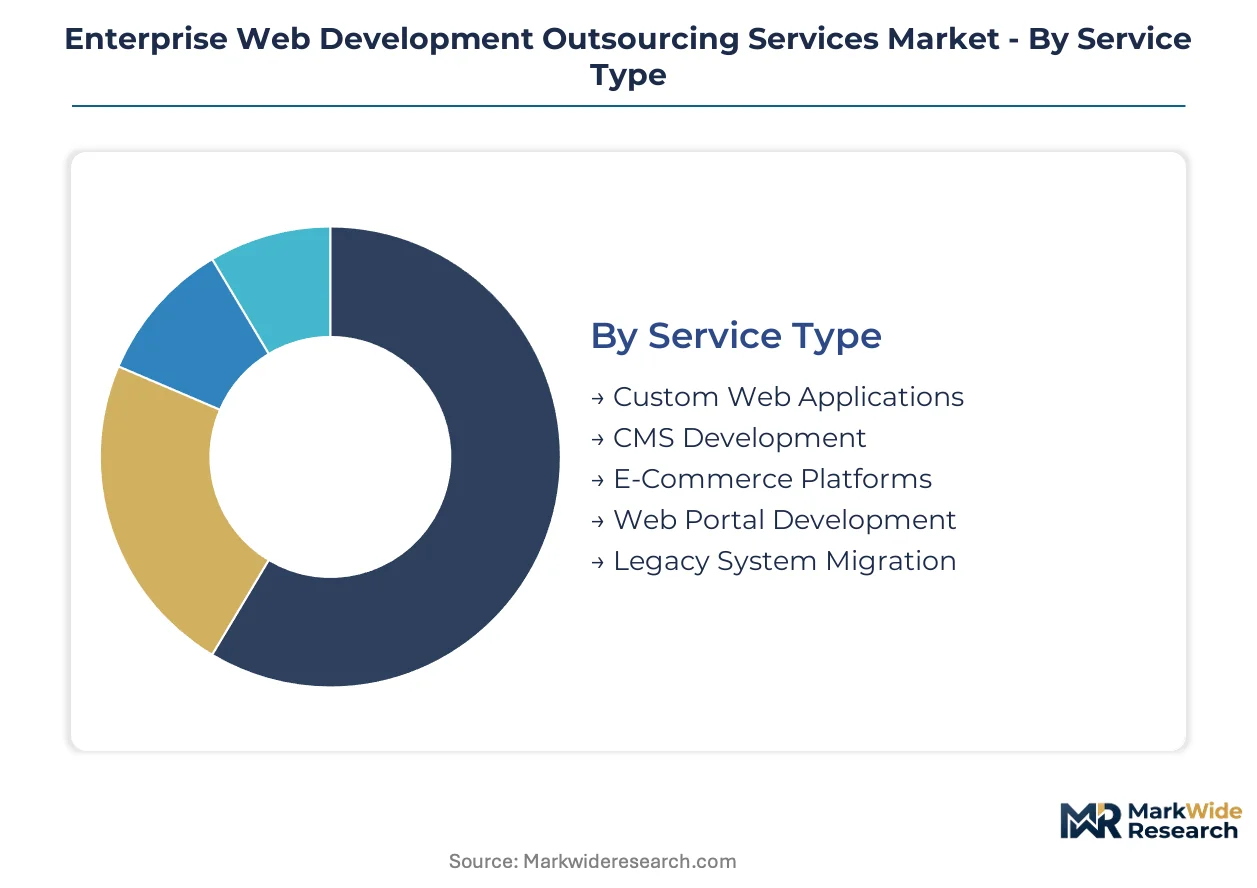
Enterprise web development outsourcing contracts fragment across technical specifications, delivery architectures, and compliance requirements. Procurement teams use these axes to match vendor capabilities against internal governance constraints and modernization timelines.
Service Type:
Technical complexity and integration depth determine pricing tiers and vendor qualification requirements across service categories.
- Custom Web Applications:Full-stack engineering of proprietary business logic with API-first architecture and microservices deployment. Healthcare providers and fintechs drive demand as HIPAA and PCI-DSS compliance requirements tighten development workflow standards.
- E-Commerce Platforms:Headless commerce implementations with service mesh integration and omnichannel inventory synchronization. Retailers in Germany and the United States expand budgets for composable commerce architectures that decouple frontend experience from backend fulfillment systems.
- CMS Development:Enterprise content management with multi-language localization and editorial workflow automation.
- Web Portal Development:Employee and customer self-service hubs with single sign-on and role-based access control.
- Legacy System Migration:COBOL and mainframe modernization with phased API wrapper deployment and database refactoring.
Custom Web Applications leads on scale; E-Commerce Platforms leads on momentum.
Deployment Model:
Cost structures and operational control trade-offs shape buyer preferences across infrastructure arrangements.
- Cloud-Based:Scalable compute with managed Kubernetes and serverless function deployment. Indian delivery centers in Bengaluru and Hyderabad capture volume as AWS, Azure, and GCP certifications become baseline vendor requirements.
- Multi-Cloud:Workload distribution across two or more hyperscalers with unified orchestration and failover automation. Financial institutions in Singapore and Switzerland adopt this model to avoid vendor lock-in and satisfy regulator diversity mandates.
- On-Premises:Dedicated hardware with air-gapped security for classified government workloads.
- Hybrid:Split architecture with sensitive data on-premises and burst capacity in public cloud.
- Private Cloud:Single-tenant infrastructure with dedicated physical isolation for defense and healthcare buyers.
Cloud-Based dominates contract volume; Multi-Cloud expands most quickly.
Client Industry:
Regulatory intensity and digital maturity create divergent procurement patterns across verticals.
- Banking:Core platform modernization with real-time payment integration and open banking API compliance. Polish and Romanian delivery centers capture German and Nordic contracts seeking GDPR-native operations with timezone alignment.
- Telecommunications:Customer experience platforms with billing integration and network operations dashboards. 5G rollout timelines in South Korea and Japan accelerate demand for subscriber-facing web interfaces.
- Government:Citizen service portals with accessibility mandates and audit-trail documentation.
- Education:Learning management systems with video streaming and assessment proctoring.
- Consumer Electronics:Product configuration tools with augmented reality visualization and supply chain transparency.
Banking commands the highest contract values; Telecommunications shows the steepest expansion trajectory.
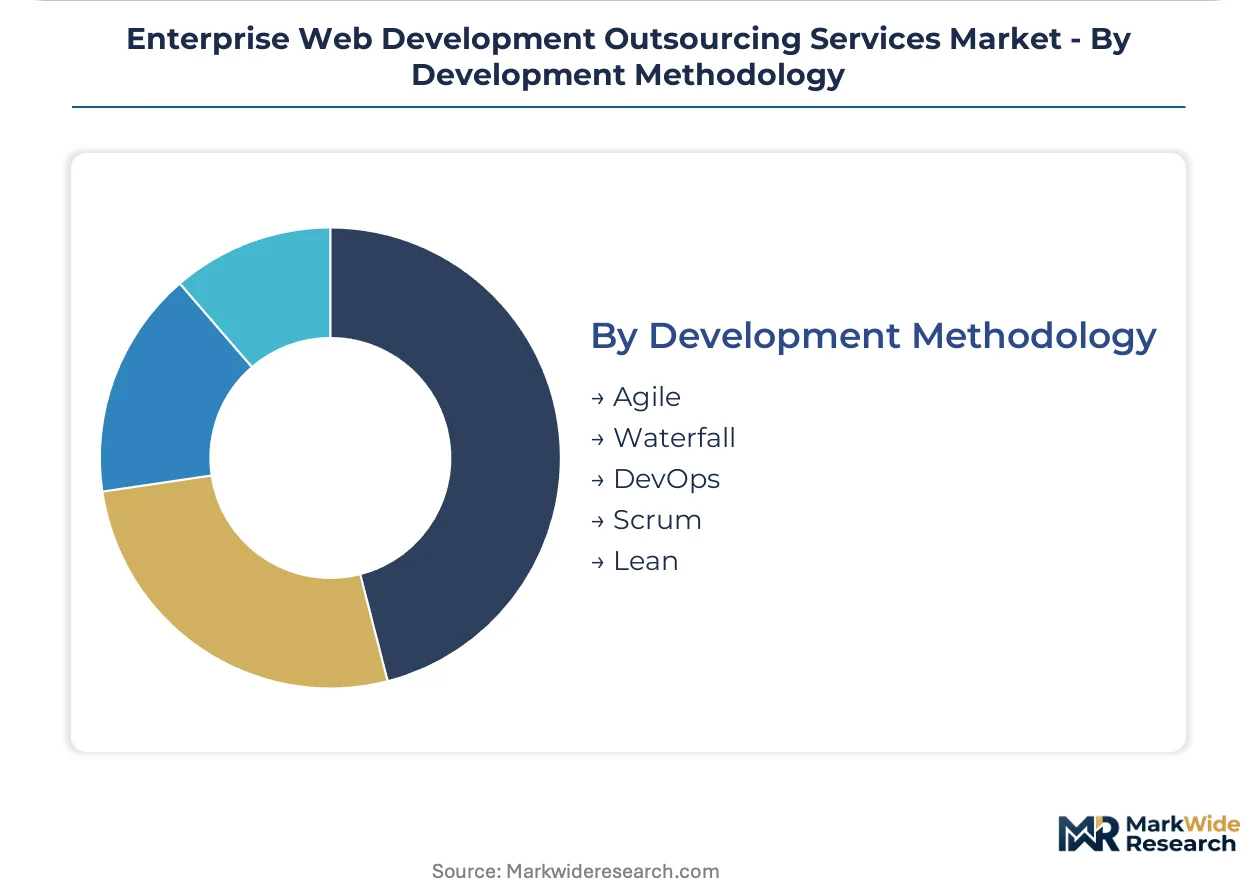
Development Methodology:
Delivery governance models determine risk allocation and vendor accountability structures.
- Agile:Sprint-based delivery with embedded quality gates and continuous stakeholder feedback. French and German enterprises show the fastest erosion of traditional procurement patterns as hybrid frameworks displace pure Waterfall.
- DevOps:Integrated development and operations with automated CI/CD pipelines and infrastructure-as-code. Platform engineering disciplines in healthcare and fintech absorb traditional managed service functions into self-service internal tooling.
- Scrum:Time-boxed iterations with defined roles and ceremony structures.
- Waterfall:Fixed-scope sequential phases with comprehensive documentation and audit trails.
- Lean:Waste reduction focus with value stream mapping and continuous flow optimization.
Agile holds the largest contract share; DevOps gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bengaluru and Hyderabad service clusters anchor procurement gravity for enterprise web development outsourcing, with Indian delivery centers capturing volume contracts as Western buyers seek cost-optimized talent pipelines. HIPAA compliance mandates in the United States and GDPR obligations in Europe reshape vendor qualification standards across sourcing geographies.
United States
Healthcare providers and fintechs drive specialized demand for HIPAA-compliant patient portals and SEC-disclosure-ready cybersecurity infrastructure. The SEC's cybersecurity disclosure rules tighten vendor due diligence timelines for publicly traded enterprises. Austin and Boston metro areas concentrate insourced platform engineering teams that compete with offshore alternatives.
Germany
Industrial manufacturers and automotive OEMs mandate GDPR-native development workflows for supplier-facing web platforms. The EU AI Act imposes algorithmic accountability documentation requirements on high-risk enterprise applications. Berlin and Munich host delivery centers serving DAX-listed companies seeking timezone-aligned nearshore options.
India
Export-oriented IT service clusters in Bengaluru and Hyderabad receive PLI scheme incentives that lower talent acquisition costs for Western buyers. BIS IT service standards shape supplier certification requirements for delivery centers handling regulated industry data. Pune and Chennai expand capacity as secondary hubs for cloud-native architecture migration projects.
Poland
German and Nordic buyers concentrate procurement in Kraków and Wrocław delivery centers seeking GDPR-native operations with timezone alignment. The country's national data protection authority enforces cross-border data governance standards matching EU baseline requirements. Warsaw hosts fintech-specialized development teams capturing open banking API compliance contracts.
United Kingdom
Financial services and insurance verticals drive demand for legacy system modernization with phased API wrapper deployment. The Financial Conduct Authority's operational resilience requirements extend to outsourced development team governance. London's fintech corridor concentrates boutique agencies serving challenger banks with composable commerce architectures.
Enterprise Web Development Outsourcing Services Market Competitive Landscape
Specialized vertical expertise dominates the current landscape as vendors reposition around HIPAA-compliant healthcare platforms and GDPR-native European delivery. The vendor base organizes into three tiers: global scale players with multi-country certification portfolios, regional specialists with deep vertical knowledge, and boutique agencies serving narrow compliance requirements. Two strategic archetypes have emerged: platform engineering consolidators absorbing traditional DevOps functions, and compliance-embedded consultancies embedding regulatory workflows into delivery models. Portfolio diversification and nearshore geographic expansion represent the dominant competitive moves.
Within the healthcare-specialized tier, ScienceSoft anchors premium positioning through vertical expertise in HIPAA-compliant platform delivery. Radixweb occupies a position exemplifying the Eastern European nearshore archetype with concentrated fintech and telecom delivery capabilities. Intellectsoft represents the R&D-intensive segment through its focus on enterprise blockchain-integrated web architectures.
| Leading Market Players |
|---|
| Suffescom Solutions |
| Devox Software |
| Radixweb |
| ScienceSoft |
| Classic Informatics |
| Intellectsoft |
| Digital Silk |
| Dotsquares |
| Infinum |
| Others |
Pricing and Supply Chain Analysis
HIPAA compliance mandates and GDPR cross-border obligations are forcing Western buyers to requalify vendor portfolios, compressing addressable supplier pools and amplifying rate premiums for certified delivery centers in India and Eastern Europe. This procurement tightening feeds directly into cost structures as talent scarcity at the certified tier intensifies bidding competition.
Pricing Analysis
Cloud infrastructure cost pass-through from AWS, Azure, and GCP rate fluctuations is compressing margins on fixed-bid enterprise contracts. Three-tier pricing structure across premium, standard, and economy levels separates HIPAA-certified healthcare specialists from generalist DevOps shops and offshore volume players. Price differentiation hinges on vertical certification depth and timezone overlap quality. Pricing pressure stems from hyperscaler pricing volatility and Kubernetes skill scarcity inflating senior engineer compensation. Mid-market retail buyers show highest price sensitivity; regulated healthcare and banking verticals accept premium tiers for compliance assurance.
Supply Chain Analysis
Freight costs for hardware provisioning and on-premise deployment equipment factor marginally into total project economics compared to talent logistics. Supply concentrates in India, Poland, and Romania as primary delivery geographies, with Bengaluru and Hyderabad clusters anchoring volume. Raw material dependencies center on cloud compute credits, developer tooling licenses, and certification audit services. Single-source vulnerability concentrates in senior container orchestration engineers, where skill scarcity creates bottleneck risk. Distribution runs through direct enterprise sales teams, systems integrator partnerships, and cloud marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunity concentrates in compliance-embedded service tiers as HIPAA and GDPR certification scarcity supports rate premiums, while India's PLI scheme incentives partially offset talent cost inflation for export-oriented delivery centers.
For Market Incumbents: Cement platform engineering consolidation by absorbing mid-tier DevOps managed services into specialized internal developer platform consultancies. Defend against emerging low-code automation substitutes by deepening vertical expertise in healthcare and fintech compliance workflows. Prioritize certification investment in EU AI Act algorithmic accountability documentation capabilities. For New Entrants and Emerging Players: Cloud marketplace routes offer lowest-friction customer acquisition for container-native migration tooling and service mesh implementation services. Target German and Nordic mid-market manufacturers seeking GDPR-native nearshore delivery with timezone alignment. White-space opportunity sits in EU AI Act compliance retrofit services for legacy credit-scoring and patient portal platforms. For Investors and Strategic Acquirers: Asymmetric upside sits with boutique compliance-embedded consultancies possessing multi-jurisdiction certification portfolios and concentrated healthcare or fintech vertical relationships. Long-term viability favors platform engineering consolidators over pure staff-augmentation models. Watch Kubernetes and service mesh skill pipeline development at Indian technical universities as inflection signal for talent cost trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| HIPAA Certification Portfolio Expansion | Captures healthcare provider procurement as security rule enforcement tightens audit requirements. |
| Platform Engineering Capability Buildout | Absorbs traditional DevOps functions into self-service internal tooling for enterprise buyers. |
| Eastern European Nearshore Expansion | Secures German and Nordic contracts through GDPR-native operations with timezone alignment. |
| EU AI Act Compliance Service Tier | Opens premium contracting for algorithmic transparency documentation in high-risk applications. |
| Multi-Cloud Orchestration Specialization | Serves Singapore and Swiss financial institutions avoiding vendor lock-in through hyperscaler diversity. |
Research Methodology
Coverage spans North America, Western Europe, and South Asia, with primary inputs from each region synthesized through structured interviews with CTOs, IT procurement officers, platform engineers, and channel partners. Secondary validation draws from SEC filings, hyperscaler capex disclosures, cloud marketplace transaction data, and BIS IT service standard certification registries. Bottom-up project pipeline analysis triangulates against top-down enterprise IT spend surveys.
Granularity-level modeling disaggregates revenue across service type, deployment model, client industry, and development methodology dimensions throughout the forecast period. CAGRs derive from segment-level growth rate blending anchored to historical contract value trajectories and projected certification demand curves. Forecast inputs include PLI scheme incentive disbursement schedules and EU AI Act implementation timeline assumptions.
The model assumes a particular technology adoption path; alternative pathways for container-native architecture migration would alter the outlook if legacy entrenchment persists longer than projected. Forecasts reflect documented assumptions around regulatory enforcement intensity and hyperscaler pricing stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Global Managed Infrastructure Service Market
Enterprise Services
Shared Services Center Market
Enterprise Services
HR Tech Consulting Market
Enterprise Services
Telecom Enterprise Services Market
Enterprise Services
Contingent Staffing Solutions Market
Enterprise Services
Asia Pacific Enterprise Collaboration Market
Enterprise Services
Enterprise Collaboration Service Market
Enterprise Services
Electronics Contract Manufacturing Services (EMS) Market
Enterprise Services
Global Remote Infrastructure Management Market
Enterprise Services
Enterprise A2P SMS Market
Enterprise Services
Global Intranet As a Service Market
Enterprise Services
Consumer Technical Support Services Market
Enterprise Services
US Enterprise Asset Management Market
Enterprise Services
Global Small Office Home Office (SOHO) Service Market
Enterprise Services
Global AWS Managed Services Market
Enterprise Services
Europe Warehouse Management Systems Market