
 Erasable Ink Pen Market | 2026-2036
Erasable Ink Pen Market Size, Share, and Industry Trends Forecast 2026-2036
Erasable Ink Pen Market Insights
Educational procurement is rebalancing toward revision-capable instruments as standardized testing and digital-notebook hybrid workflows expand. Pilot Corporation leverages its thermal-ink R&D pipeline to sustain premium positioning in Japanese and North American academic channels. Pentel Co. Ltd. anchors its competitive stance through polymer-based erasable formulations that dominate East Asian student segments. BIC Group competes on manufacturing scale, extending mass-market distribution across European retail chains with cost-optimized ballpoint-erasable hybrids.
Erasable ink pens employ thermochromic or friction-reactive pigments that decolorize under localized heat from rubber erasers, typically formulated with microencapsulated leuco dyes suspended in water-based or gel carriers for clean rewriting. Their primary commercial purpose centers on error correction without page damage, serving students, professionals, and artists who demand document cleanliness. Gel pens command the largest volume share within product type segmentation due to smoother laydown and superior erasability versus traditional ballpoint formulations. Thermal erasable technology leads technology segmentation as Japanese manufacturers refine precision heating mechanisms, while eco-friendly ink represents the fastest-growing category as REACH and state-level chemical restrictions tighten volatile organic compound limits.
Japan's Ministry of Economy, Trade and Industry (METI) sets industrial standards for writing instrument safety and chemical disclosure, directly influencing export compliance costs for regional manufacturers. The European Chemicals Agency (ECHA) enforces REACH substance restrictions that force reformulation of solvent-based erasable inks toward water-compatible alternatives. Stakeholders must monitor evolving chemical hazard classifications across multiple jurisdictions to anticipate supply chain adjustments and product registration burdens.
Market Dynamics
REACH compliance is forcing wholesale reformulation of solvent-based erasable inks across European supply chains, compressing margins for legacy manufacturers while accelerating water-compatible chemistry R&D investments.
Growth Catalysts
- Educational procurement mandates:Japanese school districts now specify revision-friendly instruments for standardized testing environments, creating institutional pull for thermal-erasable gel pens.
- ECHA substance restrictions:REACH Annex XVII limitations on volatile organic compounds are redirecting formulation investments toward water-based microencapsulated dye systems.
- Hybrid workflow adoption:Students combining digital note-taking with physical revision cycles are elevating demand for clean-erase instruments that preserve page integrity.
Market Restraints
- Leuco dye supply concentration:Three Japanese chemical houses control global production of thermochromic pigments, creating input vulnerability for non-Asian manufacturers.
- Temperature sensitivity limitations:Thermal-erasable inks decolorize above 60°C, rendering them unsuitable for archival documents or hot-climate logistics.
- Ballpoint substitution threat:Low-cost conventional ballpoints retain cost advantage in price-sensitive emerging markets, limiting premium erasable penetration.
Strategic Opportunities
- Underpenetrated Indian education sector:Government school procurement in Maharashtra and Karnataka remains dominated by conventional instruments, presenting white space for erasable introductions.
- EU Green Deal alignment:Biodegradable pen bodies paired with water-based erasable inks qualify for public-sector sustainable procurement preferences.
- Friction-erasable + smart paper convergence:Digital writing tablets with physical erase functions are opening hybrid hardware-ink partnerships for precision pen manufacturers.
Industry Challenges
- Polymer chemistry talent scarcity:Formulation expertise for microencapsulation resides disproportionately in Osaka and Tokyo industrial clusters, complicating geographic diversification.
- REACH registration timelines:New water-based ink chemistries require 18-24 month ECHA dossier preparation, delaying product launches versus conventional formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Erasable Ink Pen Market |
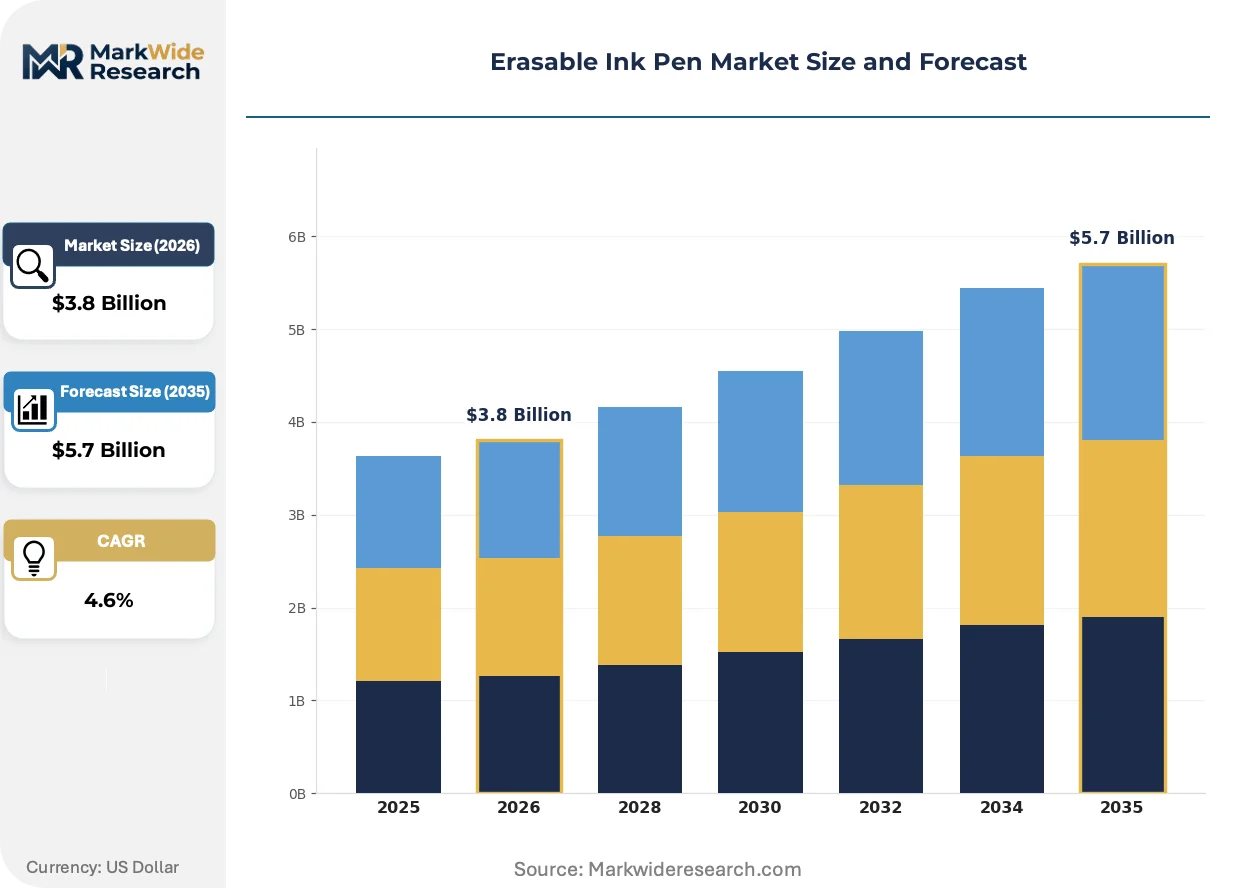
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gel Pens, Ballpoint Pens, Fountain Pens, Felt Tip Pens End User: Students, Professionals, Artists, Office Workers Technology: Thermal Erasable, Polymer-Based, Regular Ink, Eco-Friendly Ink Packaging Type: Bulk Packs, Individual Packs, Refillable, Gift Sets |
| Companies Covered | Pilot Corporation, Pentel Co. Ltd., Uni Mitsubishi Pencil Co. Ltd., BIC Group, Zebra Pen Corporation, Paper Mate, Faber-Castell, M&G Chenguang Stationery, Deli Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Erasable Ink Pen Market Trends and Innovations
Formulation chemistry and regulatory chemistry are converging to redefine competitive advantage in erasable writing instruments, with sustainability compliance now inseparable from product performance.
Microencapsulated leuco dye technology is automating the transition from solvent-based to water-compatible ink carriers. German and French stationery distributors are accelerating adoption of these reformulated products ahead of 2026 REACH enforcement milestones. This automation is compressing the competitive window for manufacturers still dependent on legacy volatile organic compound formulations.
REACH Annex XVII restrictions on N-methyl-2-pyrrolidone and other solvent carriers are mandating aqueous system investments. European ink blenders are rebuilding supply chains around water-miscible polymer bases, with compliance costs absorbed through premium positioning in academic channels. Gel pen formulations face the steepest reformulation burden given their higher solvent legacy content.
Institutional procurement in Japanese prefectural school systems is consolidating around single-source contracts for examination-grade writing instruments. Specialty retailers in Osaka and Nagoya are losing share to direct-district agreements, with Pilot Corporation and Pentel capturing multi-year supply commitments. This concentration is most visible in Tokyo and Kanagawa, where unified testing schedules drive synchronized purchasing cycles.
Erasable Ink Pen Market Segmentation
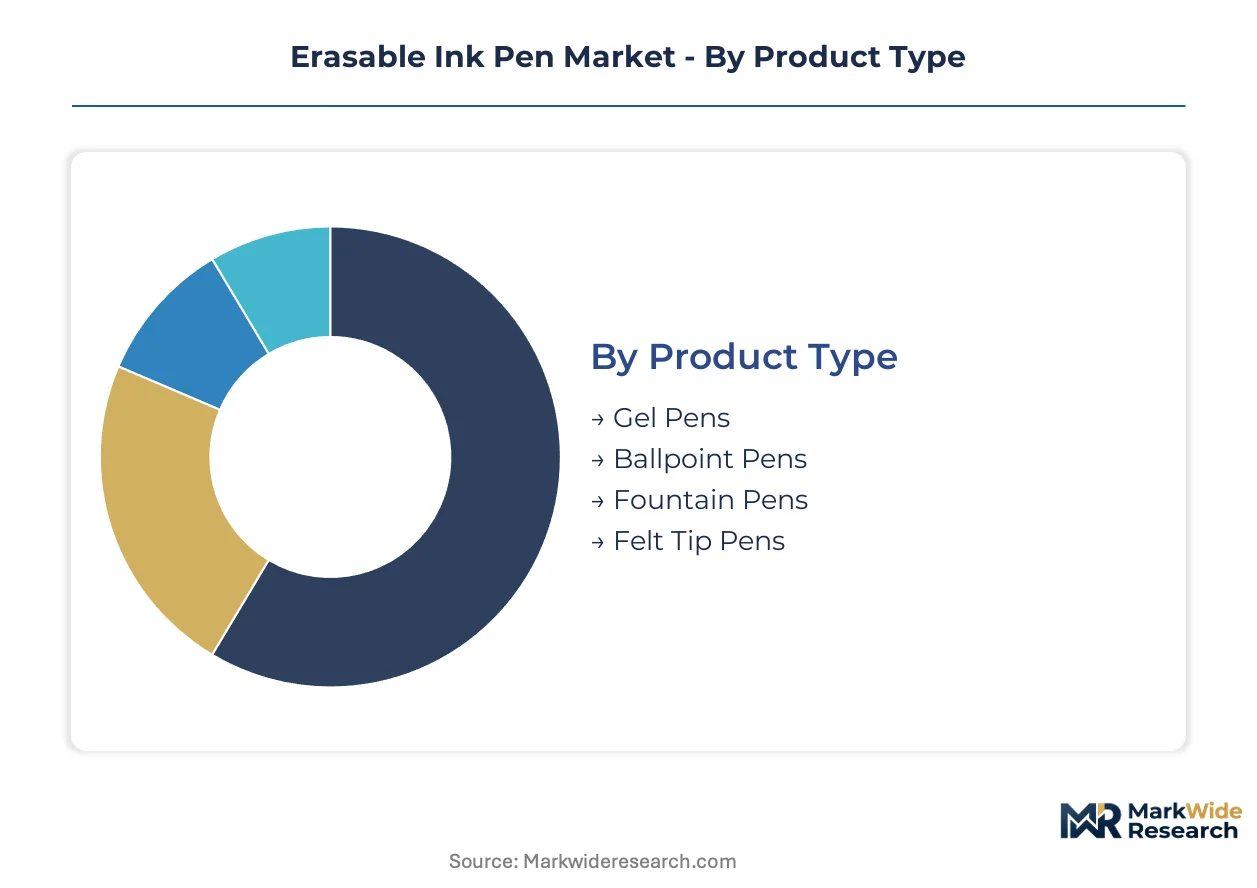
Erasable ink pen segmentation reveals how formulation chemistry, end-use requirements, and distribution economics create distinct competitive arenas. Each category carries different regulatory burdens and margin structures that determine manufacturer positioning.
Product Type:
REACH Annex XVII compliance costs vary sharply across product types, with gel formulations facing the steepest reformulation burden due to higher legacy solvent content versus ballpoint alternatives.
- Gel Pens:Water-based gel carriers suspend microencapsulated leuco dyes for smoother laydown and superior erasability. Japanese prefectural school districts specify these for standardized testing environments, driving institutional procurement consolidation.
- Ballpoint Pens:Oil-based ink systems with friction-reactive additives offer cost-optimized erasability through simpler thermal mechanisms. BIC Group leverages manufacturing scale to dominate European retail chains with mass-market ballpoint-erasable hybrids.
- Fountain Pens:Nib-fed liquid ink systems with erasable formulations remain niche due to complexity and price point.
- Felt Tip Pens:Fiber-tip delivery of erasable ink serves artistic and diagramming applications requiring bold line weights.
Gel pens sit at the top of the volume ranking, with eco-friendly formulations climbing the fastest.
End User:
Procurement patterns diverge sharply between institutional buyers with compliance mandates and individual consumers prioritizing price-performance tradeoffs.
- Students:Revision-friendly instruments dominate as digital-notebook hybrid workflows expand. Maharashtra and Karnataka government schools present underpenetrated white space for erasable introductions.
- Professionals:Document cleanliness requirements in legal and financial services sustain premium positioning for precision thermal-erasable instruments.
- Artists:Specialized felt-tip and gel formulations support sketching workflows where clean erasure preserves surface integrity.
- Office Workers:Bulk procurement through corporate supply channels favors cost-optimized ballpoint-erasable hybrids with standardized refill systems.
Students command the largest addressable base, with professionals generating the highest per-unit margins.
Technology:
Patent concentration in Osaka and Tokyo industrial clusters limits geographic diversification for advanced microencapsulation capabilities.
- Thermal Erasable:Friction-generated heat decolorizes leuco dyes through precision temperature control. Pilot Corporation refines this mechanism for premium academic channels in Japan and North America.
- Polymer-Based:Synthetic rubber erasers lift pigment from specialized polymer carriers without heat. Pentel anchors its competitive stance through these formulations in East Asian student segments.
- Regular Ink:Conventional formulations with limited erasability serve price-sensitive emerging markets where ballpoint substitution threat persists.
- Eco-Friendly Ink:Water-based microencapsulated systems with biodegradable carriers qualify for EU Green Deal procurement preferences.
Thermal erasable technology leads current volume, while eco-friendly ink gains share fastest on regulatory tailwinds.
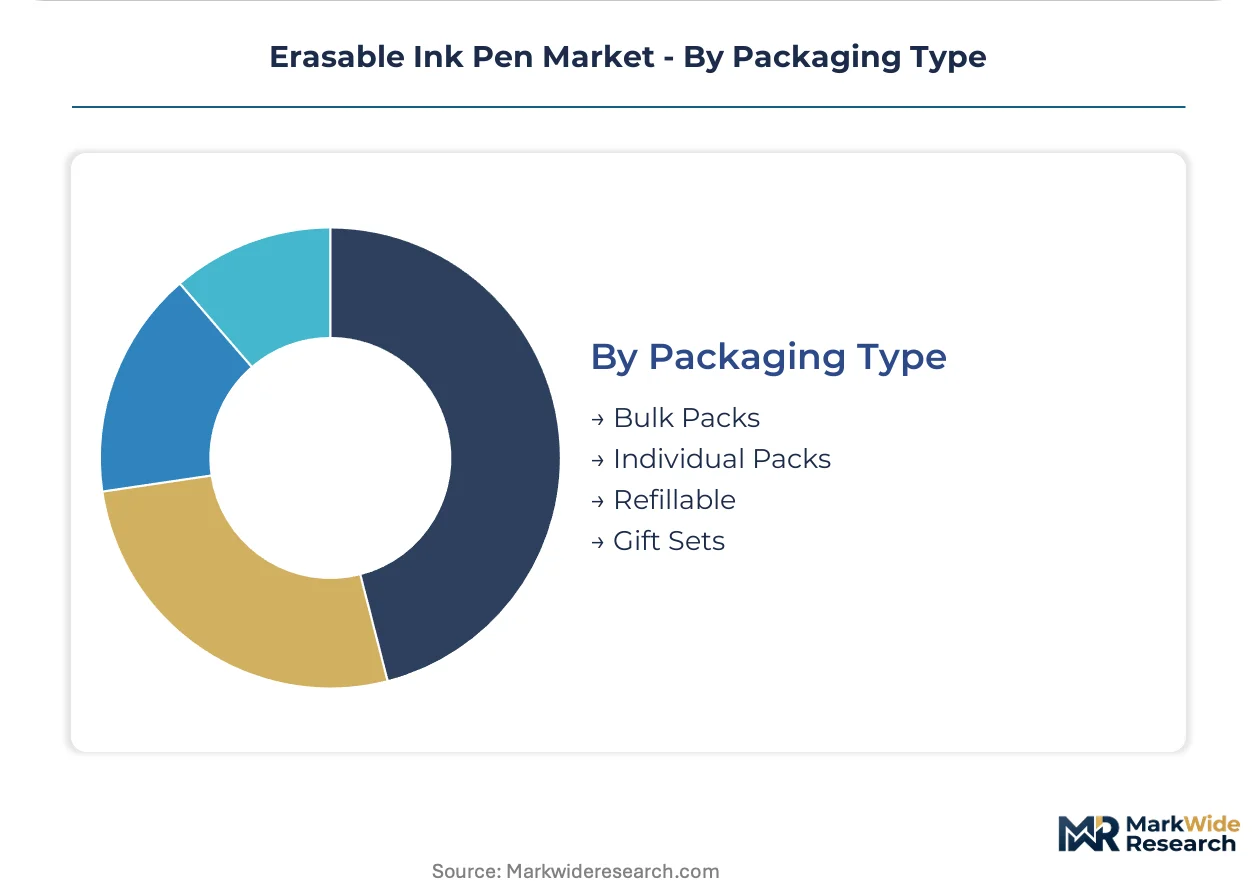
Packaging Type:
Distribution economics favor bulk formats for institutional penetration and premium packaging for gift and specialty retail channels.
- Bulk Packs:Carton-scale procurement serves district-level educational contracts and corporate supply programs.
- Individual Packs:Single-unit retail distribution dominates convenience and back-to-school seasonal purchasing.
- Refillable:Cartridge systems reduce per-use cost and align with sustainability positioning in European markets.
- Gift Sets:Premium presentation packaging captures seasonal gifting demand and collector segments in Japanese specialty retail.
Bulk packs dominate institutional volume, with refillable formats expanding most quickly on circular economy mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are relocating water-based ink formulation capacity to jurisdictions with streamlined chemical registration timelines, exploiting gaps between REACH dossier burdens and faster domestic approval pathways in Asia-Pacific production hubs.
Japan
Prefectural school districts in Tokyo and Kanagawa consolidate procurement around thermal-erasable gel pens for unified testing schedules. METI industrial standards for writing instrument safety elevate export compliance costs for regional manufacturers. Osaka and Nagoya industrial clusters anchor precision microencapsulation R&D for leuco dye chemistry.
Germany
ECHA Annex XVII enforcement is redirecting formulation investments toward water-miscible polymer bases ahead of 2026 milestones. German stationery distributors accelerate adoption of reformulated products to preempt regulatory penalties. The Rhine-Ruhr industrial corridor hosts ink blenders rebuilding supply chains around aqueous systems.
United States
Hybrid digital-physical note-taking workflows in academic institutions elevate demand for clean-erase instruments that preserve page integrity. State-level chemical restrictions in California and New York complement federal EPA volatile organic compound guidelines. Boston and Austin metropolitan areas concentrate ed-tech procurement decision-making for district-level contracts.
India
Government school procurement in Maharashtra and Karnataka remains dominated by conventional instruments, presenting white space for erasable introductions. BIS standards for writing instrument safety create compliance thresholds for imported formulations. The Mumbai-Pune industrial corridor hosts emerging domestic assembly operations for cost-optimized ballpoint-erasable hybrids.
China
Dual carbon goals and MEE environmental enforcement are accelerating water-based ink investments in domestic manufacturing. GB standards for student stationery safety align with stricter chemical disclosure requirements. The Yangtze River Delta manufacturing belt concentrates pen body production and refill cartridge assembly for export markets.
Erasable Ink Pen Market Competitive Landscape
Technology licensing dominates the current landscape as manufacturers secure access to microencapsulation patents held by Osaka and Tokyo chemical houses. The vendor base stratifies across three tiers: integrated Japanese precision specialists with captive dye production, European brand licensors relying on contract formulation, and Chinese scale fabricants competing on manufacturing throughput. Two strategic archetypes have emerged: chemistry-forward innovators controlling pigment supply chains, and distribution-heavy brand owners optimizing retail channel presence. M&A activity targets regional ink blenders with REACH-ready water-based formulations, while capacity expansion concentrates in Vietnamese and Indonesian production zones serving European export markets.
Within the integrated specialist tier, Pilot Corporation and Pentel Co. Ltd. exemplify chemistry-forward positioning through thermal-ink and polymer-based formulation expertise respectively. BIC Group occupies a position at the scale-driven end of the spectrum, leveraging mass-market distribution architecture across European retail chains. These three anchors illustrate how competitive advantage splits between pigment control and channel density in the current market structure.
| Leading Market Players |
|---|
| Pilot Corporation |
| Pentel Co. Ltd. |
| Uni Mitsubishi Pencil Co. Ltd. |
| BIC Group |
| Zebra Pen Corporation |
| Paper Mate |
| Faber-Castell |
| M&G Chenguang Stationery |
| Deli Group |
| Others |
Pricing and Supply Chain Analysis
Water-based ink reformulation under REACH Annex XVII simultaneously escalates R&D amortization costs and consolidates manufacturing leverage among Osaka and Tokyo chemical houses with captive leuco dye production. Japanese prefectural school districts now specify thermal-erasable gel pens for standardized testing, concentrating procurement volume and compressing margin negotiation space for European distributors dependent on contract formulation.
Pricing Analysis
Distributor margin layers absorb the steepest compression as German and French stationery channels front-load compliance costs ahead of ECHA enforcement milestones. Three-tier pricing structure across premium, standard, and economy levels separates examination-grade thermal instruments from mass-market ballpoint-erasable hybrids and private-label economy alternatives. Pricing pressure stems from leuco dye supply concentration among three Japanese chemical houses. Government school procurement in Maharashtra and Karnataka exhibits highest price sensitivity; legal and financial services professionals show least sensitivity due to document cleanliness mandates.
Supply Chain Analysis
Dual-sourcing requirements from European distributors now mandate multi-supplier qualification for water-based ink formulations, extending procurement cycles. Manufacturing concentrates in Japan, China, and Germany. Raw material dependencies center on microencapsulated leuco dyes, water-miscible polymer bases, and precision pen body molding. Single-source vulnerability persists for thermochromic pigment supply. Distribution runs through consolidated academic procurement channels in Japanese prefectures and European retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The erasable ink pen market represents a late-cycle quality story as institutional buyers prioritize REACH-compliant formulations over cost-optimized alternatives. Japanese prefectural school districts exemplify this specification shift toward premium thermal-erasable gel instruments.
For Market Incumbents: Hedge leuco dye supply exposure through backward integration into microencapsulation chemistry or captive partnerships with Osaka chemical houses. Defend Japanese prefectural contract positions against polymer-based substitution from Pentel by accelerating water-based R&D pipelines. Channel control through direct-district agreements in Tokyo and Kanagawa offers defensive leverage against distributor disintermediation.
For New Entrants and Emerging Players: Government school procurement managers in Maharashtra and Karnataka present an underserved buyer archetype with minimal erasable penetration and expanding education budgets. White-space targets include cost-optimized ballpoint-erasable hybrids for price-sensitive Indian institutional channels and biodegradable pen body systems aligned with EU Green Deal procurement preferences. Direct engagement with state education departments offers the most penetrable go-to-market angle.
For Investors and Strategic Acquirers: Valuations sit cheapest among European ink blenders with REACH-ready water-based formulations and stranded solvent-based legacy capacity. Long-term viability hinges on chemistry-forward positioning controlling pigment supply chains rather than distribution-heavy brand licensing. The signal to watch is ECHA enforcement acceleration compressing competitive windows for non-compliant manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Leuco Dye Production | Captive pigment supply secures margin control against Osaka chemical house pricing power. |
| REACH-Ready Water-Based Formulation Launch | Preemptive compliance positioning captures German distributor channel consolidation ahead of enforcement. |
| Direct-District Academic Procurement Contracts | Bypasses specialty retail erosion in Japanese prefectural school systems. |
| Biodegradable Pen Body Development | Qualifies for EU Green Deal public-sector sustainable procurement preferences. |
| Polymer-Based Formulation Licensing | Expands Pentel's East Asian student segment positioning into European markets. |
Research Methodology
Multiple input streams — formulation chemistry specialists, educational procurement officers, European stationery distributors, and regulatory affairs leads — were reconciled against customs records, ECHA registration databases, and METI industrial standard filings. Primary interviews with plant managers at Japanese chemical houses, category buyers at German retail chains, and technical R&D directors at ink blenders informed supply-side dynamics. Secondary validation drew from prefectural school district procurement disclosures, SEC filings of listed stationery manufacturers, and trade flow data. Bottom-up unit economics and top-down market sizing were triangulated for coherence.
Historical volume trajectories were cross-referenced against panel input from industry stakeholders to anchor growth assumptions across the analysis window. Segmentation dimensions modeled include product type, technology mechanism, end-user archetype, packaging format, and regional regulatory cluster. CAGRs were derived from slope analysis of normalized adoption curves and elasticity-adjusted price-volume relationships. Forecast inputs incorporated REACH compliance timeline uncertainty and leuco dye supply concentration risk premiums.
Underlying measurement precision varies by segment; gel pen and thermal-erasable technology categories carry tighter precision than emerging eco-friendly ink alternatives due to longer commercial track records. Forecasts reflect assumptions about ECHA enforcement intensity, prefectural procurement consolidation continuity, and water-based formulation yield rates. Deviation in leuco dye supply availability or REACH Annex XVII interpretation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Supplies
Flash Cards and USB Flash Drives Market
Office Supplies
Writing Instruments Market
Office Supplies
Copiers Market
Office Supplies
Letter Opener Market
Office Supplies
Dictionary Pen Market
Office Supplies
Stamp Pad Market
Office Supplies
Business Card Holder Market
Office Supplies
Cutter Staplers Market
Office Supplies
Custom Binders Market
Office Supplies
Malaysia Stationery Market
Office Supplies
Stationery Products Market
Office Supplies
Acrylic Marker Pen Market
Office Supplies
Global Stationery and Supplies Market
Office Supplies
School Stationery Supplies Market
Office Supplies
Office Supplies Market
Office Supplies
Thumb Hole Book Page Holder Market