
 Data Marketplace Platform Market | 2026-2036
Data Marketplace Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Data Marketplace Platform Market Intelligence
The shift from single-source data procurement to multi-vendor marketplace sourcing is broadening competitive dynamics across the sector. Snowflake sustains technology leadership in cloud-native data sharing architectures. Databricks leverages its unified analytics stack to anchor enterprise-grade marketplace deployments. Palantir Technologies differentiates through specialized offerings for government and defense data exchange protocols.
A data marketplace platform constitutes a digital exchange infrastructure enabling organizations to discover, procure, license, and distribute structured and unstructured datasets through standardized APIs, semantic metadata catalogs, and usage-based pricing mechanisms. These systems integrate data quality scoring, provenance tracking, and access control layers to facilitate governed commercial transactions between data providers and consumers. Cloud-based deployment models currently lead segment adoption due to elastic scalability and reduced capital overhead, while hybrid configurations are gaining traction among enterprises with stringent residency requirements. The data monetization service category commands attention from platform operators seeking recurring revenue streams, whereas data integration services retain structural importance for buyers consolidating fragmented internal and external sources.
The EU AI Act and GDPR impose strict requirements on training data provenance and consent documentation, directly shaping platform architecture priorities across European deployments. The US lacks comprehensive federal data privacy legislation, though sectoral HIPAA and FTC oversight creates compliance complexity for health and consumer data marketplaces. Stakeholders must monitor evolving cross-border data transfer restrictions and emerging certification standards for ethical data sourcing as governance fragmentation intensifies.
Market Dynamics
The EU AI Act's training data provenance mandates are forcing platform operators to rebuild data lineage infrastructure from ingestion through transaction settlement, compressing deployment timelines and elevating compliance costs across European deployments.
Growth Catalysts
- GDPR Article 20 portability rights:German automotive supply chains are deploying marketplace platforms to automate compliant data transfers between OEMs and tier suppliers, reducing bilateral negotiation overhead.
- Synthetic data generation pipelines:Financial services firms in France are licensing privacy-preserving datasets to circumvent direct personal data sharing restrictions under CNIL guidance.
- Industrial data consortia formation:Manufacturing clusters across Baden-Württemberg are pooling operational telemetry through shared marketplace infrastructure to train collective AI models without proprietary leakage.
Market Restraints
- Cloud egress cost volatility:AWS, Azure, and Google Cloud data transfer fees consume 15-30% of transaction value for high-frequency dataset exchanges, compressing platform operator margins.
- Cross-border transfer uncertainty:Schrems II litigation and evolving EU-US Data Privacy Framework adequacy determinations create legal friction for transatlantic marketplace participants.
- Semantic interoperability gaps:Inconsistent metadata standards between healthcare HL7 FHIR implementations and financial services ISO 20022 schemas force costly custom integration work.
Strategic Opportunities
- CSRD-mandated sustainability data:EU corporate sustainability reporting requirements are generating demand for verified environmental datasets that marketplace platforms can certify and monetize.
- Edge-to-cloud federated architectures:Converging 5G network slicing with confidential computing enables real-time industrial data marketplaces without centralizing sensitive operational technology feeds.
- Subscription-based data co-ops:Agricultural collectives in the Netherlands are piloting member-owned marketplace structures for sharing precision farming telemetry outside traditional vendor-controlled channels.
Industry Challenges
- Data steward talent scarcity:Shortages of professionals certified in both domain-specific data governance and platform engineering are extending implementation timelines for enterprise deployments.
- Legacy system integration complexity:Mainframe-based core banking systems at major European financial institutions require expensive middleware layers to connect with modern API-first marketplace architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Marketplace Platform Market |
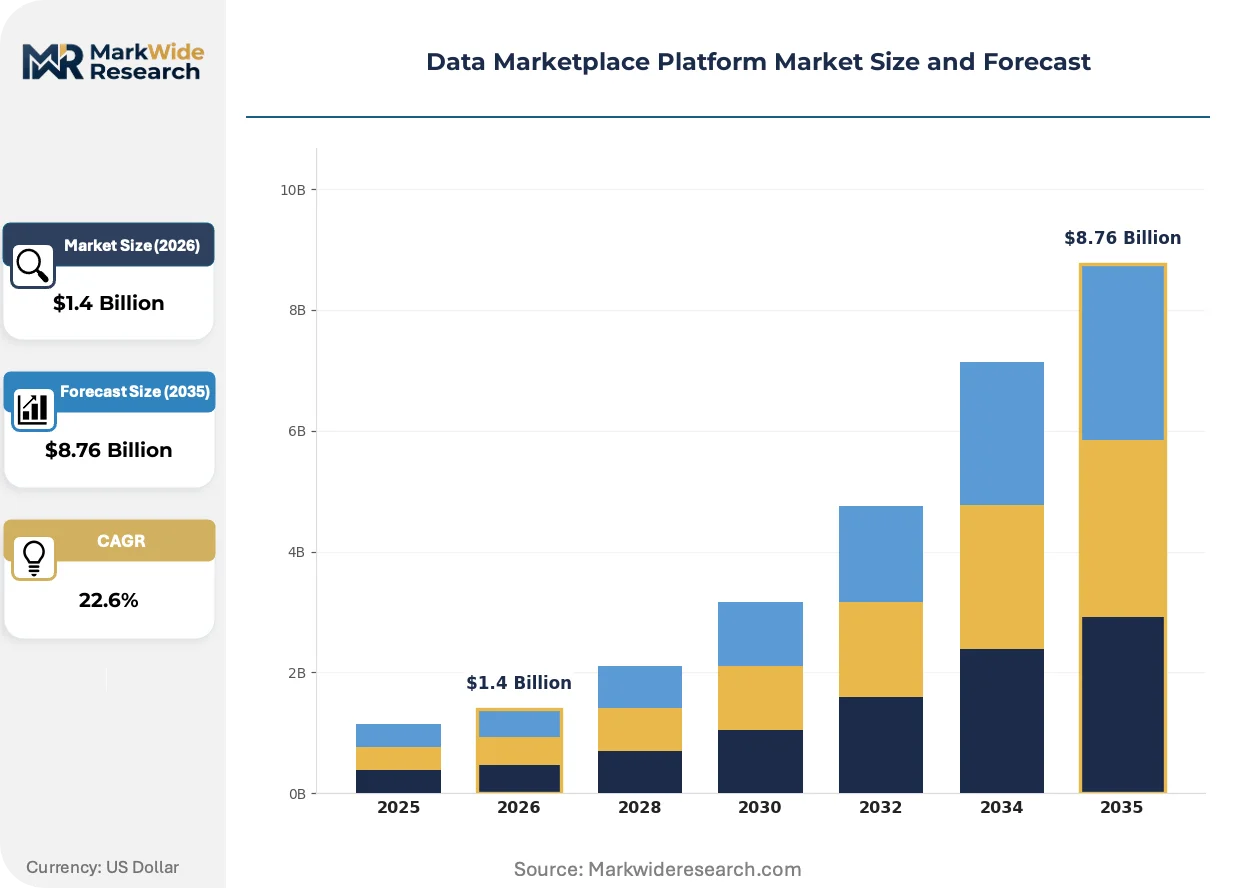
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $8.76 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Public Data, Private Data, Hybrid Data, API Data Deployment Model: On-Premise, Cloud-Based, Hybrid, Multi-Cloud End User: Enterprises, Startups, Government Agencies, Academic Institutions Service Type: Data Analytics, Data Monetization, Data Integration, Data Storage |
| Companies Covered | Collibra, Google Cloud, Snowflake, Oracle, Amazon Web Services, Crunchbase, Talend, Palantir Technologies, Databricks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Marketplace Platform Market Strategic Shifts & Innovations
Knowledge graph technology is unifying previously siloed dataset discovery across enterprise data catalogs, external vendor repositories, and open government portals into single query interfaces.
Semantic layer platforms are unifying disparate schema definitions through automated ontology mapping, enabling cross-domain dataset joins without manual transformation engineering. Pharmaceutical researchers at EMA-regulated institutions are adopting these tools to integrate clinical trial data with real-world evidence registries. The structural consequence is collapsing data preparation cycles from weeks to hours, is unifying procurement decisions around data usability rather than raw volume metrics.
The EU AI Act's risk classification framework is mandating documented training data provenance for high-risk AI applications, forcing marketplace operators to embed immutable audit trails into transaction records. Healthcare AI developers in Germany face expanded documentation burdens under overlapping MDR and AI Act requirements. Platform vendors are responding by pre-certifying datasets against combined regulatory standards, creating premium pricing tiers for compliance-guaranteed inventory.
Consolidated procurement functions at multinational enterprises are displacing decentralized business unit data buying with centralized marketplace contracts negotiated at group level. Automotive OEM procurement teams in Stuttgart and Munich are mandating preferred vendor lists for external data sourcing, compressing supplier counts from dozens to single-digit platform relationships. France and the Netherlands show similar concentration patterns as CSRD reporting requirements elevate data spend visibility to CFO-level oversight.
Data Marketplace Platform Market Segmentation
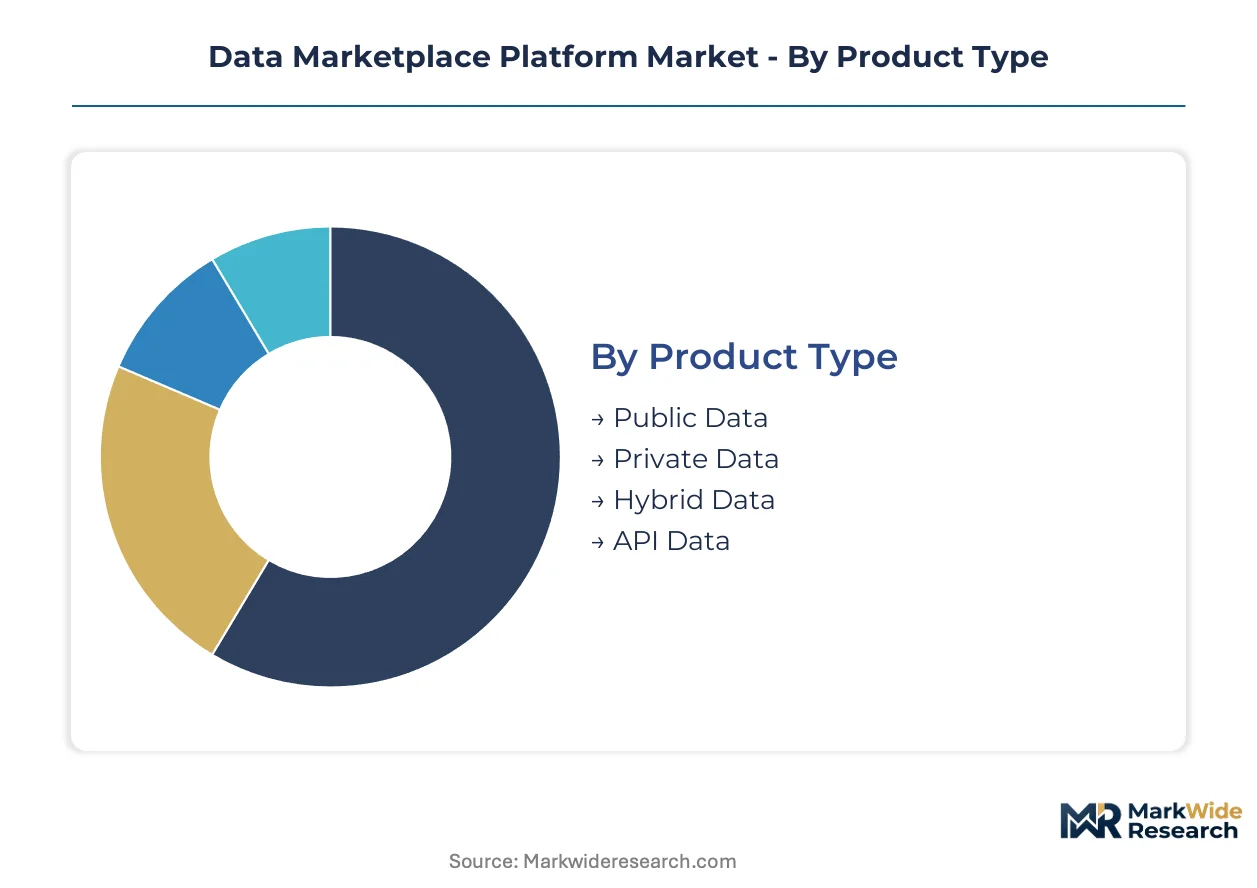
Data marketplace platforms fragment across four structural dimensions that determine procurement complexity, compliance burden, and revenue model design. Each segmentation axis carries distinct capital requirements and margin profiles that shape vendor positioning.
Product Type:
Capital intensity peaks with hybrid data deployments requiring dual infrastructure for public and private dataset orchestration.
- Public Data:Government-sourced open datasets with standardized licensing terms require minimal governance overhead. German federal open data portals and French data.gouv.fr integrations concentrate procurement demand where public sector transparency mandates eliminate bilateral negotiation friction.
- Private Data:Proprietary commercial datasets carry elevated compliance infrastructure for consent documentation and provenance tracking. EU AI Act training data mandates are forcing platform operators to embed immutable audit layers, compressing margins for operators lacking pre-certified inventory.
- Hybrid Data:Blended public-private datasets enable cross-referencing without full proprietary exposure. Dutch agricultural collectives pilot member-owned structures combining government weather data with private farm telemetry.
- API Data:Real-time programmatic data feeds through standardized endpoints. Financial services firms in France license synthetic generation pipelines to circumvent CNIL personal data restrictions.
Private data absorbs the bulk of installed capacity; API data is expanding most quickly.
Deployment Model:
Customer risk tolerance and data residency requirements segment infrastructure choices across enterprise tiers.
- Cloud-Based:Elastic scalability with reduced capital overhead dominates segment adoption. AWS, Azure, and Google Cloud deployments face 15-30% transaction value erosion from egress fees, compressing operator margins on high-frequency exchanges.
- On-Premise:Dedicated hardware installations serving stringent residency mandates. German automotive OEMs in Stuttgart and Munich mandate on-premise cores for operational technology telemetry governed by supply chain confidentiality protocols.
- Hybrid:Split architectures balancing sensitive data local processing with scalable cloud analytics. Manufacturing clusters across Baden-Württemberg pool operational telemetry through shared infrastructure without centralizing proprietary feeds.
- Multi-Cloud:Distributed deployments across competing hyperscaler environments to mitigate vendor lock-in. Cross-border transfer uncertainty from Schrems II litigation elevates legal friction for transatlantic configurations.
Cloud-based deployments capture the largest revenue base; hybrid configurations are gaining share fastest.
End User:
Procurement centralization patterns differentiate volume buyers from price-sensitive entrants.
- Enterprises:Consolidated group-level contracts displacing decentralized business unit buying. Automotive OEM procurement teams compress supplier counts from dozens to single-digit platform relationships under CFO-level data spend oversight.
- Startups:Usage-based pricing sensitivity with minimal governance infrastructure requirements. France and Netherlands show similar concentration patterns as CSRD reporting elevates data visibility to senior management.
- Government Agencies:Mandatory competitive bidding and sovereign data classification standards. EMA-regulated pharmaceutical researchers adopt semantic layer tools for clinical trial integration with real-world evidence registries.
- Academic Institutions:Discounted licensing tiers with publication rights and attribution requirements. Knowledge graph technology unifies siloed discovery across enterprise catalogs, vendor repositories, and open government portals.
Enterprises command the dominant procurement volume; government agencies are expanding most rapidly.
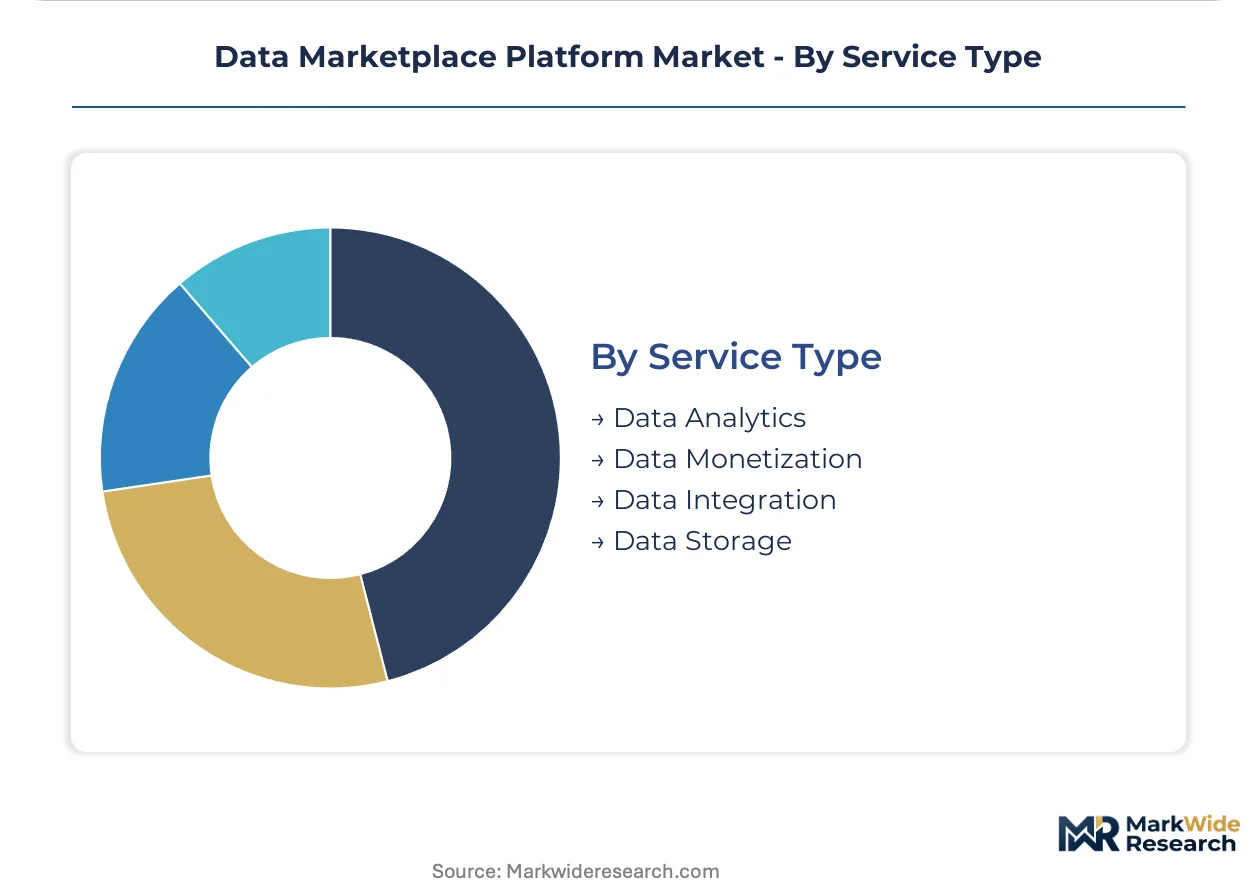
Service Type:
Recurring revenue potential versus one-time implementation fees structures vendor economics.
- Data Monetization:Recurring revenue streams from dataset licensing and transaction fees. Platform operators seek premium pricing tiers for compliance-guaranteed inventory pre-certified against combined MDR and AI Act standards.
- Data Integration:One-time and ongoing fees for consolidating fragmented internal and external sources. Semantic interoperability gaps between healthcare HL7 FHIR and financial ISO 20022 schemas force costly custom engineering.
- Data Analytics:Value-added processing and insight generation layered atop raw dataset access. Data steward talent scarcity extends implementation timelines for enterprises lacking certified governance professionals.
- Data Storage:Infrastructure fees for dataset hosting and retrieval optimization. Legacy mainframe-based core banking systems at major European financial institutions require expensive middleware layers for API-first connectivity.
Data integration retains structural importance for buyer consolidation; data monetization is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany, where industrial data consortia and automotive supply chain platforms are scaling rapidly. Financial services firms across France and the Netherlands are expanding third-party data procurement infrastructure. Compliance mandates from the EU AI Act and GDPR are accelerating investment in governed data exchange architecture.
Germany
Automotive OEM procurement teams in Stuttgart and Munich mandate preferred vendor lists for external data sourcing. The EU AI Act and GDPR impose strict training data provenance requirements. Manufacturing clusters across Baden-Württemberg pool operational telemetry through shared marketplace infrastructure without centralizing proprietary feeds.
France
Financial services firms license synthetic data generation pipelines to circumvent direct personal data sharing restrictions. CNIL guidance shapes privacy-preserving dataset licensing practices. Paris-based pharmaceutical researchers adopt semantic layer tools to integrate clinical trial data with real-world evidence registries.
Netherlands
Agricultural collectives pilot member-owned marketplace structures for sharing precision farming telemetry. CSRD reporting requirements elevate data spend visibility to CFO-level oversight. Amsterdam and Rotterdam clusters show similar procurement centralization patterns as consolidated group-level contracts displace decentralized buying.
United Kingdom
Knowledge graph technology unifies siloed dataset discovery across enterprise catalogs and vendor repositories. The UK lacks comprehensive federal data privacy legislation, though sectoral oversight creates compliance complexity. London-based financial institutions face expensive middleware requirements to connect mainframe systems with API-first marketplace architectures.
United States
Cloud-native data sharing architectures dominate enterprise adoption despite HIPAA and FTC sectoral oversight creating compliance complexity. Healthcare and consumer data marketplaces navigate fragmented regulatory requirements. Silicon Valley and New York Metro clusters drive technology leadership in elastic scalability and reduced capital overhead deployment models.
Data Marketplace Platform Market Key Industry Players
Strategic partnerships dominate the current landscape as platform operators seek to anchor enterprise-grade deployments. The vendor base organizes around three archetypes: cloud hyperscalers with elastic infrastructure, unified analytics specialists with integrated governance stacks, and defense-focused providers with hardened security protocols. M&A activity and technology licensing agreements represent the primary competitive moves as operators race to embed compliance-guaranteed inventory.
Within the cloud-native tier, Snowflake and Databricks exemplify divergent positioning strategies. Snowflake occupies a position anchored in cloud-native data sharing architectures with reduced capital overhead. Databricks represents the unified analytics stack approach, leveraging integrated governance to anchor enterprise marketplace deployments. Palantir Technologies sits within the specialized tier, occupying a position shaped by government and defense data exchange protocol requirements.
| Leading Market Players |
|---|
| Collibra |
| Google Cloud |
| Snowflake |
| Oracle |
| Amazon Web Services |
| Crunchbase |
| Talend |
| Palantir Technologies |
| Databricks |
| Others |
Cost & Logistics Intelligence
Consolidated procurement functions at multinational enterprises are forcing platform operators to restructure commercial terms around volume commitments and long-term contracts, compressing spot-market flexibility and anchoring price discovery to enterprise-scale negotiations rather than transactional usage metrics.
Pricing Analysis
Volume-based enterprise contracts capture the dominant revenue share while smaller buyers face per-transaction premiums. Three-tier pricing structure across premium, standard, and economy levels separates compliance-guaranteed inventory pre-certified against EU AI Act and MDR standards from basic catalog access. Pricing pressure stems from hyperscaler cloud egress fees consuming substantial transaction value on high-frequency dataset exchanges. Startups and academic institutions exhibit the highest price sensitivity, whereas automotive OEM procurement teams in Stuttgart and Munich accept premium tiers for supply chain confidentiality guarantees.
Supply Chain Analysis
Cross-border data transfer costs and latency constraints are reshaping infrastructure deployment patterns across marketplace architectures. Cloud infrastructure supply concentrates in the United States, Germany, and Ireland, with hyperscaler regions anchoring platform operator hosting decisions. Compute and storage resources, semantic metadata engines, and confidential computing hardware constitute critical input dependencies. Single-source vulnerability around AWS, Azure, and Google Cloud creates concentration risk for operators lacking multi-cloud redundancy. Distribution runs through direct enterprise sales teams for large accounts and self-service portals for smaller buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The data marketplace platform sector sits at a technology-transition inflection where knowledge graph and semantic layer architectures are displacing traditional schema-mapping and manual data preparation workflows.
For Market Incumbents: Hedge against margin compression from hyperscaler egress fees by developing edge-to-cloud federated architectures that minimize centralized data movement. Invest in pre-certification infrastructure against combined EU AI Act and MDR standards to capture premium pricing tiers before regulatory requirements harden. Threat substitution from unified analytics stacks embedding native marketplace capabilities demands defensive platform integration moves. For New Entrants and Emerging Players: Begin with agricultural collectives and precision farming telemetry in the Netherlands, where member-owned marketplace structures remain underpenetrated by established vendors. Target synthetic data generation pipelines for French financial services firms navigating CNIL personal data restrictions. A compliance-first go-to-market angle anchored to EU AI Act training data provenance mandates offers differentiation against incumbent catalog breadth. For Investors and Strategic Acquirers: The window for entry favors semantic layer specialists with automated ontology mapping capabilities and proven healthcare or pharmaceutical deployments. Long-term viability rests on regulatory complexity intensifying rather than harmonizing across jurisdictions. Watch for inflection signals in Schrems II litigation outcomes and EU-US Data Privacy Framework adequacy determinations that would reshape transatlantic marketplace economics.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Semantic layer unification collapses data preparation cycles from weeks to hours for EMA-regulated researchers. |
| Strategic Partnership | Industrial data consortia in Baden-Württemberg pool operational telemetry without proprietary leakage risks. |
| Acquisition of Specialist Firm | Knowledge graph vendors enable single-query interfaces across siloed enterprise catalogs and government portals. |
| Geographic Expansion | German automotive supply chains automate compliant data transfers between OEMs and tier suppliers under GDPR Article 20. |
| Product Launch | Confidential computing-enabled marketplaces address real-time industrial data exchange without centralizing sensitive OT feeds. |
Research Approach
Document review covered SEC filings from cloud hyperscalers and platform operators, EU regulatory guidance from EMA and CNIL, and clinical trial registry data, complemented by interviews with data platform engineering leads, enterprise procurement officers, and regulatory compliance specialists. Secondary sources included customs and trade flow databases, hyperscaler capex disclosures, and hospital procurement system records. Bottom-up segment sizing and top-down macro validation were cross-referenced for triangulation.
Historical revenue trajectories were cross-referenced against panel input from platform operators and enterprise buyers to anchor growth assumptions. Segmentation modeling spanned deployment model, data type, end-user organization size, and regional regulatory cluster dimensions. CAGRs were derived from slope analysis of adoption curves and compliance investment timelines. Forecast inputs incorporated EU AI Act implementation pacing and synthetic data generation technology maturation.
Underlying measurement precision varies by segment; cloud-based deployments and financial services end-use carry tighter precision than emerging hybrid configurations and agricultural applications. Forecasts reflect documented assumptions around regulatory enforcement intensity and cross-border transfer policy stability. Stakeholders should weight assumptions against their own operating context and compliance infrastructure maturity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Online Voting System Market
Digital Solutions
Web Performance Market
Digital Solutions
Customer Engagement Hub (CEH) Market
Digital Solutions
Inventory Management Market
Digital Solutions
Global DDI Market
Digital Solutions
Europe Digital Twin Market
Digital Solutions
Digital Signature Market
Digital Solutions
Decision Management Applications Market
Digital Solutions
Digital Evidence Management System Market
Digital Solutions
Mock Interview Platforms Market
Digital Solutions
Ad Network Software Market
Digital Solutions
Cultivation Management Software Market
Digital Solutions
UK and Germany Diet and Nutrition Apps Market
Digital Solutions
Smart Recording Pen Market
Digital Solutions
Data Converter Market
Digital Solutions
Messaging Platform Market