
 Cocomonoethanolamide (CMEA) Market | 2026-2036
Cocomonoethanolamide (CMEA) Market Size, Share, and Industry Trends Forecast 2026-2036
Cocomonoethanolamide (CMEA) Market Analytics
Aftermarket technical service revenue is reshaping how specialty surfactant suppliers capture value beyond commodity sales. BASF leverages its global technical centers to embed CMEA formulations into customer R&D pipelines early, sustaining long-term offtake agreements. Galaxy Surfactants anchors its competitiveness on backward integration into Indian fatty alcohol streams, while Croda International differentiates through RSPO-certified supply chains that command premium positioning in European personal care markets.
Cocomonoethanolamide is a non-ionic surfactant synthesized from coconut fatty acids and monoethanolamine, typically exhibiting an amine value between 45-65 mg KOH/g and functioning primarily as a viscosity builder, foam stabilizer, and emulsifier in aqueous formulations. The liquid product type dominates current production volumes due to easier handling in automated blending operations, though powder grades claim disproportionate margins from dry shampoo and solid bar cosmetic segments where waterless formulation trends accelerate. Personal care applications lead absolute consumption, while agricultural adjuvant formulations represent the fastest-expanding application as CMEA's low phytotoxicity profile meets drift-reduction requirements for modern crop protection sprays.
EPA aquatic toxicity screening under the Clean Water Act and REACH Annex XIV substance evaluation shape permissible surfactant chemistries in North American and European markets, directly influencing CMEA substitution rates for traditional alkanolamides. BIS certification requirements for imported cosmetic raw materials in India create compliance thresholds that favor established suppliers with documented supply chain traceability. Stakeholders must monitor evolving biobased content verification standards and oleochemical feedstock certification schemes as these become decisive in procurement decisions by multinational personal care brands.
Market Dynamics
Sulfate-free formulation mandates from multinational personal care brands are restructuring surfactant procurement, forcing formulators to validate CMEA performance in cold-process manufacturing workflows previously optimized for conventional alkanolamides.
Growth Catalysts
- REACH Annex XIV substance evaluation:ECHA's scrutiny of diethanolamine derivatives accelerates substitution toward monoethanolamide chemistries in European cosmetic formulations.
- Palm-kernel oil processing concentration:Integrated oleochemical complexes in Malaysia and Indonesia deliver captive fatty acid feedstock at scale, compressing CMEA production costs versus fragmented Western supply chains.
- Drift-reduction adjuvant demand:CMEA's low phytotoxicity profile satisfies EPA requirements for modern crop protection spray formulations, opening agricultural channels beyond traditional personal care anchors.
Market Restraints
- Coconut oil price volatility:Weather-driven supply disruptions in Southeast Asian producing regions transmit directly to CMEA margin compression, with limited hedging instruments available for specialty oleochemicals.
- Amine value consistency:Batch-to-batch variation in coconut fatty acid composition forces downstream formulators to maintain broader specification tolerances, increasing quality control overhead.
- Alkyl polyglucoside substitution:Sugar-derived surfactants with comparable foam stabilization profiles are capturing sulfate-free positioning in mass-market shampoo segments price-sensitive to CMEA premiums.
Strategic Opportunities
- Dry shampoo solid formats:Powder-grade CMEA specifications command disproportionate margins as waterless cosmetic bars bypass liquid handling infrastructure entirely.
- RSPO-certified supply chain premiums:Segregated mass-balance certification creates pricing stratification that rewards suppliers with documented traceability from plantation through monoethanolamide reaction.
- Indian BIS import compliance:Certification thresholds for cosmetic raw materials favor established suppliers with testing documentation, creating defensive moats against opportunistic traders.
Industry Challenges
- Reaction optimization expertise:Monoethanolamine amidation kinetics require precise temperature and pressure control that few contract manufacturers outside integrated oleochemical hubs possess.
- Biodegradability testing backlog:OECD 301B validation timelines stretch 28-60 days, delaying formulation approvals for brands with compressed product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cocomonoethanolamide (CMEA) Market |
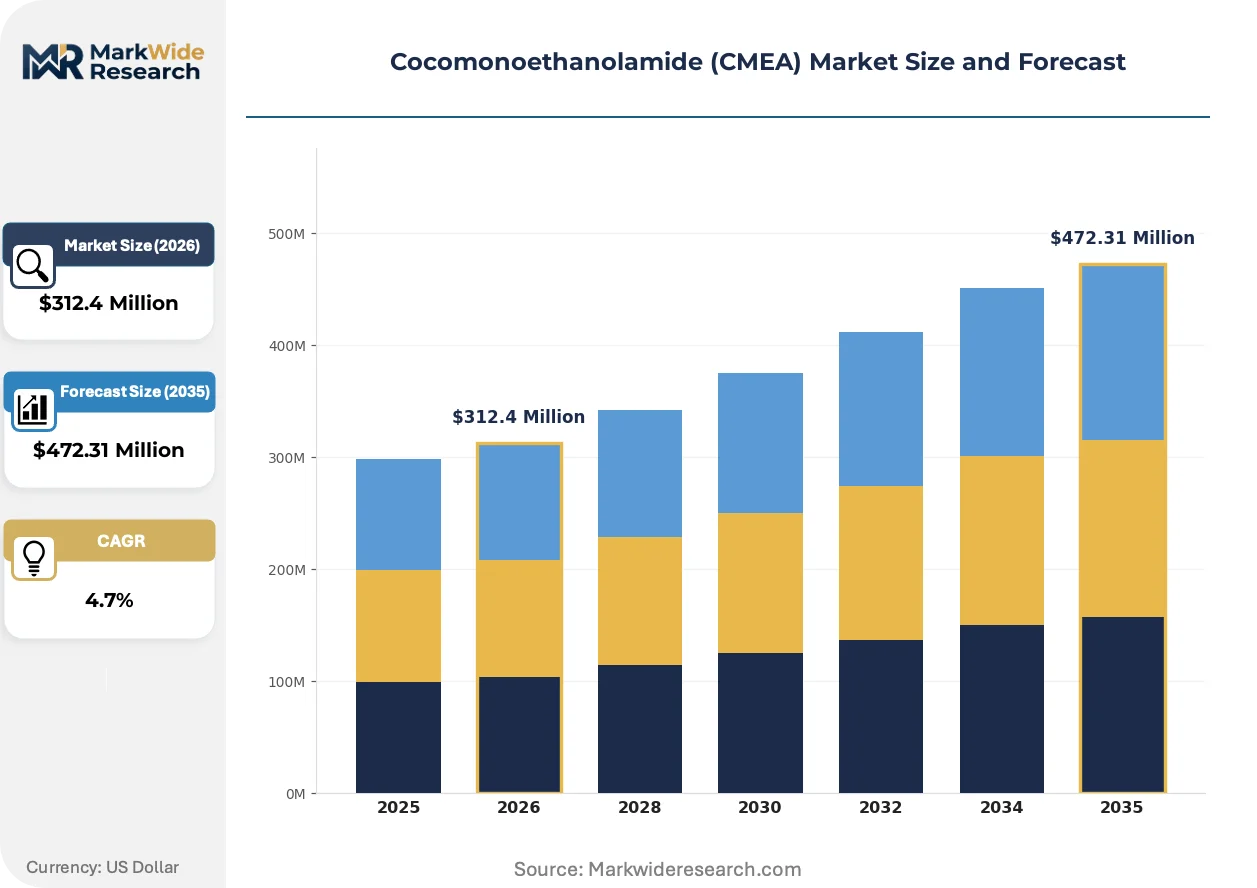
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Solid, Semi-solid, Powder Application: Personal Care, Household, Industrial, Agricultural End User: Cosmetics Manufacturers, Cleaning Products, Textile Industry, Food Industry Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | BASF, Croda International, Galaxy Surfactants, Kao Chemicals, Solvay, Evonik, Clariant, KLK OLEO, AkzoNobel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cocomonoethanolamide (CMEA) Market Evolving Landscape
Continuous flow reactor technology is displacing batch amidation processes, enabling real-time viscosity control that aligns CMEA output specifications with automated personal care manufacturing lines.
Enzymatic esterification catalysts are rendering obsolete traditional alkaline amidation routes for high-purity cosmetic grades. Specialty surfactant houses in Germany and Switzerland are retrofitting pilot plants with lipase-mediated systems that operate at ambient pressure. The technology compresses energy intensity by approximately half while eliminating secondary amine contamination that complicates REACH dossier preparation.
EPA aquatic toxicity screening under the Clean Water Act is narrowing permissible surfactant chemistries in North American markets. The 2024 updated methodology for chronic invertebrate testing elevates biodegradability thresholds that CMEA satisfies more readily than ethoxylated alternatives. Agricultural adjuvant formulators are responding by specifying coconut-derived amides in drift-reduction product lines submitted for state-level pesticide registrations.
Direct technical service embedding is restructuring how specialty surfactant suppliers capture value. BASF operates dedicated formulation laboratories in Ludwigshafen and Shanghai where customer R&D teams co-develop CMEA-containing prototypes. The model replaces transactional spot purchasing with multi-year offtake agreements indexed to personal care brand pipeline commitments rather than commodity surfactant benchmarks.
Cocomonoethanolamide (CMEA) Market Segmentation
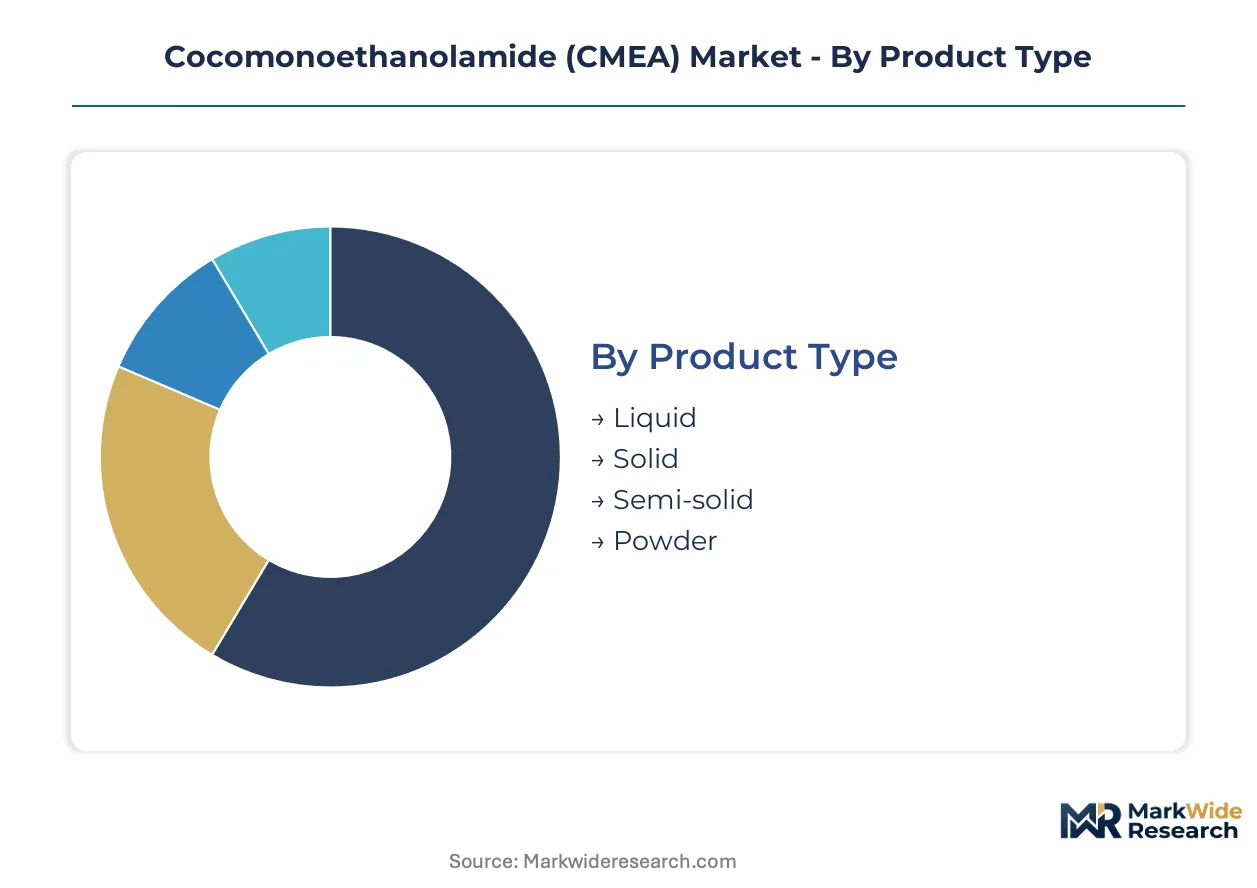
Cocomonoethanolamide procurement patterns diverge sharply across physical form factors and end-use specifications, with viscosity requirements and automated handling infrastructure dictating grade selection. Personal care multinationals maintain parallel qualification tracks for liquid and powder specifications to hedge against formulation trend shifts.
Product Type:
Mature liquid formats dominate current installed capacity, while emerging solid and powder specifications capture disproportionate margins from waterless cosmetic trends.
- Liquid:Standard aqueous solutions with 80-85% active content enable automated metering in continuous blending operations. Personal care manufacturers in Germany and the United States specify liquid CMEA for cold-process shampoo workflows that minimize energy input. The format handles the majority of throughput; powder specifications are climbing the fastest on share.
- Powder:Spray-dried granules with controlled particle size distribution serve solid shampoo bars and dry aerosol formulations where water elimination reduces preservation requirements. Southeast Asian producers are expanding dedicated powder lines to supply European waterless cosmetic brands. The segment commands premium positioning over liquid equivalents due to handling complexity and lower transport costs.
- Solid:Flaked or pastille forms suit small-batch cosmetic compounders lacking liquid storage infrastructure, particularly in India and Brazil.
- Semi-solid:Intermediate consistency grades bridge handling properties for regional formulators with variable temperature-controlled logistics.
Liquid throughput remains the volume anchor; powder specifications are expanding most quickly as solid format adoption accelerates.
Application:
Cost tier stratification separates premium personal care positioning from commodity industrial consumption, with agricultural adjuvants emerging as a mid-tier growth corridor.
- Personal Care:Sulfate-free shampoo and body wash formulations leverage CMEA as a primary viscosity builder and foam stabilizer, replacing conventional alkanolamides under REACH pressure. Formulators in France and the United Kingdom specify amine values between 50-60 mg KOH/g for optimal aesthetic performance. The segment absorbs the dominant share of high-purity cosmetic grades; agricultural applications are gaining share fastest.
- Agricultural:Drift-reduction adjuvants for crop protection sprays exploit CMEA's low phytotoxicity profile and rapid biodegradability under EPA aquatic toxicity protocols. State-level pesticide registration requirements in Iowa and Illinois are specifying coconut-derived amides over ethoxylated alternatives. The segment represents the steepest expansion trajectory as precision agriculture intensifies.
- Household:Laundry and hard surface cleaners utilize standard-grade CMEA for cost-effective foam stabilization, competing with alkyl polyglucoside substitution in mass-market positioning.
- Industrial:Metalworking fluids and textile processing employ technical-grade specifications where performance tolerances accommodate broader amine value ranges.
Personal care commands premium grade absorption; agricultural channels are expanding most rapidly on volume contribution.
End User:
Customer type concentration clusters around formulated product manufacturers with internal compounding capabilities, distinct from toll processors and merchant market traders.
- Cosmetics Manufacturers:Integrated personal care brands with captive formulation laboratories specify CMEA at the R&D stage, locking in multi-year supply agreements indexed to pipeline commitments rather than spot commodity benchmarks. L'Oréal and Unilever procurement teams in Paris and Rotterdam conduct joint specification development with surfactant suppliers.
- Cleaning Products:Detergent compounders prioritize cost-optimized liquid grades for high-volume automated production lines, with specification tolerances wider than cosmetic applications.
- Textile Industry:Fiber processing and dyeing auxiliaries employ CMEA as a wetting agent and antistatic modifier, with demand concentrated in Tamil Nadu and Gujarat manufacturing clusters.
- Food Industry:Limited food-grade applications in processing equipment cleaning utilize refined specifications meeting FDA indirect food contact requirements.
Cosmetics manufacturers drive specification evolution; cleaning product compounders anchor volume throughput.
Distribution Channel:
Supply concentration favors direct technical relationships for specification-critical grades, while distributor networks handle commoditized industrial volumes.
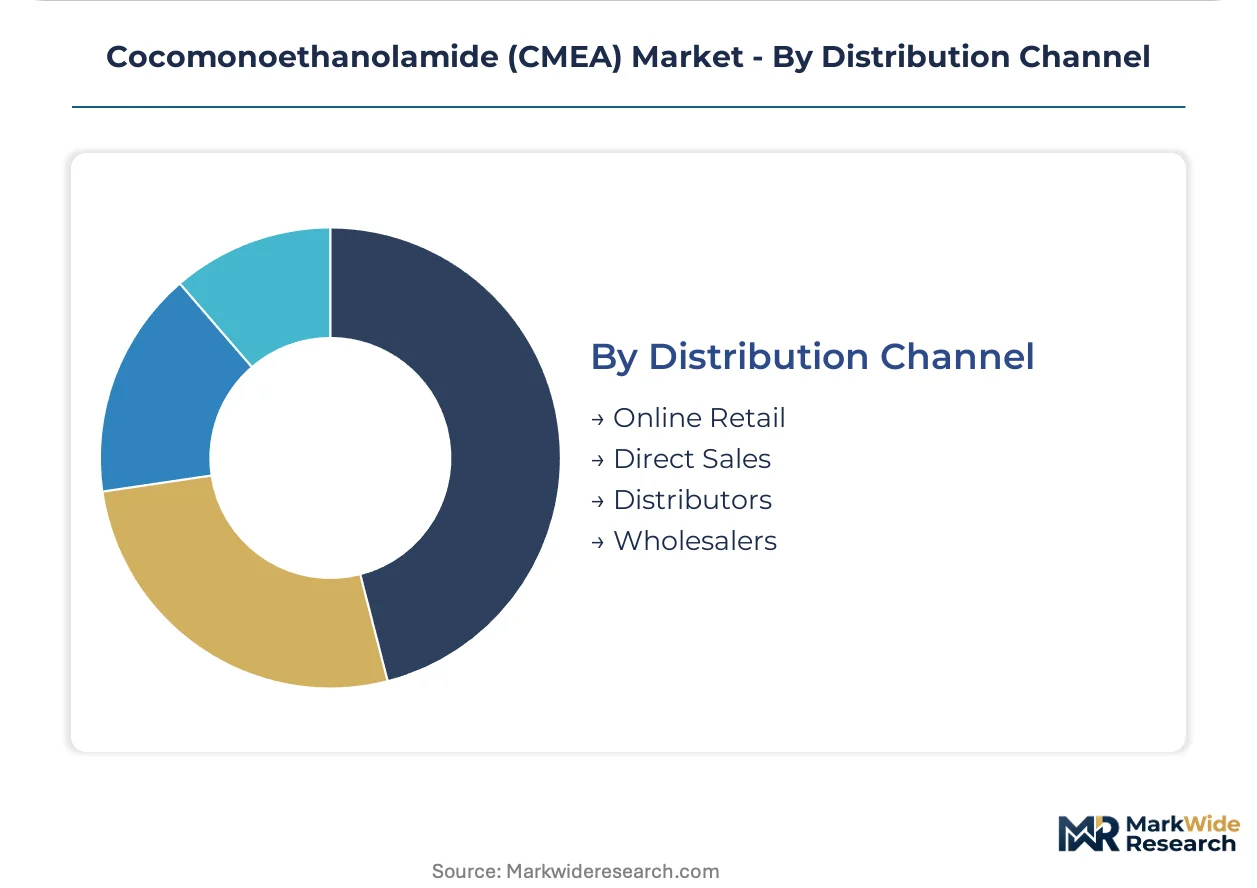
- Direct Sales:Technical service embedding through dedicated account teams enables co-development of CMEA-containing prototypes in customer R&D facilities. BASF and Croda International operate this model for European and North American personal care multinationals, replacing transactional purchasing with pipeline-indexed agreements.
- Distributors:Regional chemical distributors stock standard liquid grades for mid-tier formulators lacking volume leverage for direct supplier contracts, particularly in Eastern European and Latin American markets.
- Online Retail:E-commerce platforms serve small-batch cosmetic compounders and independent formulators with packaged quantities below bulk truckload minimums.
- Wholesalers:Merchant traders handle opportunistic spot volumes for industrial applications with less stringent specification consistency requirements.
Direct sales capture the premium tier; distributor networks handle the broadest geographic spread.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coconut fatty acid processing concentrates in Southeast Asian oleochemical corridors, with integrated amidation complexes in Malaysia and Indonesia feeding downstream CMEA output. European and North American markets rely on imported specifications shaped by REACH and EPA compliance thresholds.
United States
Drift-reduction adjuvant specifications from Iowa and Illinois crop protection formulators absorb technical-grade CMEA volumes. EPA aquatic toxicity screening under the Clean Water Act elevates coconut-derived amides over ethoxylated alternatives in state pesticide registrations. Houston and New Jersey chemical corridors host toll amidation capacity serving agricultural adjuvant compounders.
Germany
Personal care multinationals in Ludwigshafen and Düsseldorf specify cosmetic-grade CMEA for sulfate-free shampoo pipelines. ECHA REACH Annex XIV scrutiny of diethanolamine derivatives accelerates monoethanolamide substitution in European formulations. BASF technical centers embed formulation support directly into customer R&D workflows.
Malaysia
Integrated palm-kernel oil complexes in Klang Valley deliver captive fatty acid feedstock at scale. Malaysian oleochemical producers leverage backward integration into plantation operations to compress CMEA production costs versus fragmented Western supply chains. Port Klang export infrastructure serves Indian and Chinese surfactant formulators.
India
BIS certification requirements for imported cosmetic raw materials create compliance thresholds favoring established suppliers with documented traceability. Galaxy Surfactants anchors production in Mumbai and Tarapur with captive fatty alcohol streams from Indian palm-kernel processing. Maharashtra and Gujarat manufacturing clusters drive domestic absorption for personal care and textile applications.
Indonesia
Medan and Surabaya oleochemical hubs process palm-kernel oil into fatty acid methyl esters feeding regional amidation capacity. Indonesian producers supply powder-grade specifications to European waterless cosmetic brands expanding solid shampoo bar portfolios. Integrated plantation-to-reactor complexes rival Malaysian cost structures in Southeast Asian export markets.
Cocomonoethanolamide (CMEA) Market Competitive Landscape
Vertically integrated oleochemical majors and specialty surfactant houses split the market along feedstock control versus formulation expertise lines. The vendor base clusters around three strategic archetypes: plantation-integrated producers with captive fatty acid supply, technical service embedders co-developing customer pipelines, and regional compounders serving price-sensitive industrial grades. Dominant competitive moves include backward integration into palm-kernel processing and direct technical center embedding to lock in multi-year offtake agreements.
Within the plantation-integrated tier, KLK OLEO and Kao Chemicals exemplify feedstock control strategies spanning Southeast Asian oleochemical corridors. BASF occupies a position as the technical service embedder archetype, leveraging global formulation laboratories to anchor customer R&D pipelines early. Croda International represents the certification-premium vector, with RSPO-segregated supply chains commanding positioning in European personal care markets. Galaxy Surfactants sits within the regional specialist tier, anchoring Indian production with backward integration into domestic fatty alcohol streams.
| Leading Market Players |
|---|
| BASF |
| Croda International |
| Galaxy Surfactants |
| Kao Chemicals |
| Solvay |
| Evonik |
| Clariant |
| KLK OLEO |
| AkzoNobel |
| Others |
Value Network & Pricing Analysis
Idle amidation capacity in Malaysian oleochemical corridors is compressing spot quotations for standard liquid grades while tightening availability of powder specifications for European waterless cosmetic brands. This utilization asymmetry rewards integrated producers with captive palm-kernel oil supply while forcing toll processors to absorb margin compression on commodity volumes.
Pricing Analysis
REACH Annex XIV substance evaluation dictates the pricing tier structure across European cosmetic specifications, with RSPO-segregated certification commanding premium positioning over mass-balance alternatives. Three-tier pricing structure across premium, standard, and economy levels separates cosmetic-grade amine value precision from agricultural adjuvant tolerances and industrial technical grades. Pricing pressure stems from alkyl polyglucoside substitution in mass-market sulfate-free shampoos, with household compounders exhibiting highest price sensitivity and integrated personal care multinationals least responsive to spot fluctuations.
Supply Chain Analysis
Palm-kernel oil methyl ester availability anchors upstream feedstock security, with Malaysian and Indonesian plantation-integrated complexes dominating fatty acid output. CMEA production draws from coconut fatty acid distillates, monoethanolamine petrochemical or bio-based streams, and specialized amidation catalysts. Single-source vulnerability concentrates in Southeast Asian oleochemical hubs exposed to El Niño-driven feedstock disruptions. Distribution runs through direct technical service relationships for premium cosmetic grades and regional distributor networks for standard industrial specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping value capture as continuous flow reactor technology enables real-time specification alignment between CMEA output and automated personal care manufacturing lines, creating interoperability premiums for suppliers embedding early in customer R&D pipelines.
For Market Incumbents: Build certification moats through RSPO-segregated supply chain documentation that defends European personal care positioning against emerging plantation-integrated entrants from Indonesia. Deepen backward integration into palm-kernel processing to compress production costs below toll amidation competitors, while expanding dedicated powder capacity to capture waterless cosmetic format premiums before substitution by spray-dried alkyl polyglucoside alternatives accelerates. For New Entrants and Emerging Players: Agricultural adjuvant underpenetration in North American state-level pesticide registration channels offers the most penetrable white-space target, with drift-reduction specifications specifying coconut-derived amides over ethoxylated alternatives. Target toll amidation partnerships with Indian oleochemical feedstock suppliers to bypass BIS certification barriers for imported cosmetic raw materials, leveraging technical-grade volume accumulation before cosmetic-grade qualification. For Investors and Strategic Acquirers: Capital is best deployed toward plantation-integrated mid-caps with captive fatty acid supply and existing amidation infrastructure across the analysis window, as feedstock control determines margin sustainability against commodity surfactant cycles. Monitor EPA aquatic toxicity screening methodology revisions as the signal indicating accelerated CMEA substitution for diethanolamide derivatives in agricultural and personal care formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Reactor Adoption | Real-time viscosity control aligns CMEA output with automated personal care manufacturing specifications. |
| RSPO Certification Investment | Segregated supply chain documentation commands premium positioning in European REACH-compliant markets. |
| Backward Integration into Palm-Kernel Processing | Captive fatty acid feedstock compresses production costs versus fragmented Western toll amidation chains. |
| Powder Grade Capacity Expansion | Spray-dried specifications capture disproportionate margins from waterless solid shampoo bar trends. |
| Direct Technical Service Embedding | Early R&D pipeline integration replaces transactional spot purchasing with multi-year offtake agreements. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, ECHA REACH dossier filings, and SEC disclosures from listed oleochemical majors. The analysis combines structured interviews with plant managers at Southeast Asian amidation facilities, procurement leads at European personal care multinationals, and technical R&D directors at specialty surfactant houses with bottom-up capacity modeling and top-down demand validation across personal care, agricultural, and industrial end-uses.
Forecast inputs incorporate grade tier stratification, end-use industry absorption patterns, and regional production hub competitiveness across the projection horizon. CAGRs derive from segment-level volume build-ups adjusted for substitution elasticity between CMEA and alkyl polyglucoside alternatives, feedstock cost pass-through coefficients, and regulatory-driven specification shifts in REACH and EPA jurisdictions.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Indonesian plantation-integrated producers or accelerated enzymatic esterification adoption by German specialty houses would shift outcomes beyond modeled ranges. Cross-checking against OECD 301B biodegradability validation timelines and state-level pesticide registration databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Glycol Monostearate Market
Surfactants
Soap Salts Market
Surfactants
Dodecanol Market
Surfactants
Sulfosuccinate Market
Surfactants
Micellar Water Market
Surfactants
Amino Acid Surfactants Market
Surfactants
Surfactant Cleansers and Adjuvants Market
Surfactants
MDEA Esterquats Market
Surfactants
Isopropyl Myristate Market
Surfactants
Powder Defoamers Market
Surfactants
Wax Emulsion Market
Surfactants
Specialty Surfactants Market
Surfactants
Alkyl Polyglycoside (APG) Market
Surfactants
Global Sodium Cocoyl Glutamate Market
Surfactants
Cyclopentasiloxane Market
Surfactants
Sodium Lauryl Sulphate Market