
 Secondary Alkane Sulfonate Market | 2026-2036
Secondary Alkane Sulfonate Market Size, Share, and Industry Trends Forecast 2026-2036
Secondary Alkane Sulfonate Market Analysis
A shortage of skilled process chemists familiar with sulfonation reactor optimization is redrawing competitive boundaries across the secondary alkane sulfonate value chain. BASF leverages its integrated C12-C18 feedstock infrastructure to sustain cost advantages in European supply. Clariant AG anchors its position through specialty surfactant R&D intensity at its Frankfurt-area facilities. Stepan Company competes on manufacturing scale across North American detergent chemical channels.
Secondary alkane sulfonate is an anionic surfactant produced via sulfoxidation of paraffinic hydrocarbons, typically yielding C13-C17 chain lengths with active matter content ranging from 30% to 60% depending on liquid or solid formulation grade. The compound functions primarily as a wetting agent and emulsifier in hard-surface cleaners and textile processing baths where alkali stability and foam control prove critical. Liquid formulations dominate volume flows into industrial detergent blending operations, while powder grades command margin premiums in household laundry applications where dissolution kinetics and storage stability differentiate performance. The textile chemicals application segment is expanding fastest as fiber processors seek surfactants compatible with closed-loop water systems.
EPA registration requirements under the Toxic Substances Control Act constrain new sulfonate entrants into US cleaning product supply chains, while REACH substance evaluation in Europe drives reformulation toward lower aquatic toxicity profiles. Germany's Federal Environment Agency and the EU ECHA framework jointly elevate compliance costs for non-European producers seeking market access. Stakeholders must monitor evolving biodegradability test protocols under OECD guidelines and assess captive sulfonation capacity decisions before feedstock contract renewals.
Market Dynamics
REACH substance evaluation and the EU Green Deal are compressing permissible specifications for petrochemical-derived surfactants, forcing detergent formulators to requalify supply chains around bio-based alternatives and closed-loop water compatibility.
Growth Catalysts
- EU Green Deal compliance mandates:Germany's Federal Environment Agency and ECHA jointly tighten biodegradability thresholds, accelerating procurement of alkali-stable anionic surfactants in industrial detergent blending.
- Textile chemical processors:Fiber manufacturers in the Netherlands and Belgium seek surfactants compatible with closed-loop water systems, expanding application scope beyond traditional household laundry.
- Sulfonation reactor optimization:Captive production investments by specialty chemical clusters in Frankfurt-Rhine-Main and Rotterdam-Antwerp corridor reduce feedstock transit costs for C12-C18 paraffinic supply.
Market Restraints
- Petrochemical feedstock volatility:Paraffinic hydrocarbon pricing swings constrain margin predictability for C13-C17 chain sulfonate producers dependent on naphtha-cracker output.
- EPA registration barriers:Toxic Substances Control Act compliance timelines extend 18-24 months for new sulfonate entrants seeking US cleaning product channel access.
- Alcohol ether sulfate substitution:Lower-cost anionic alternatives displace secondary alkane sulfonate in price-sensitive industrial degreaser formulations.
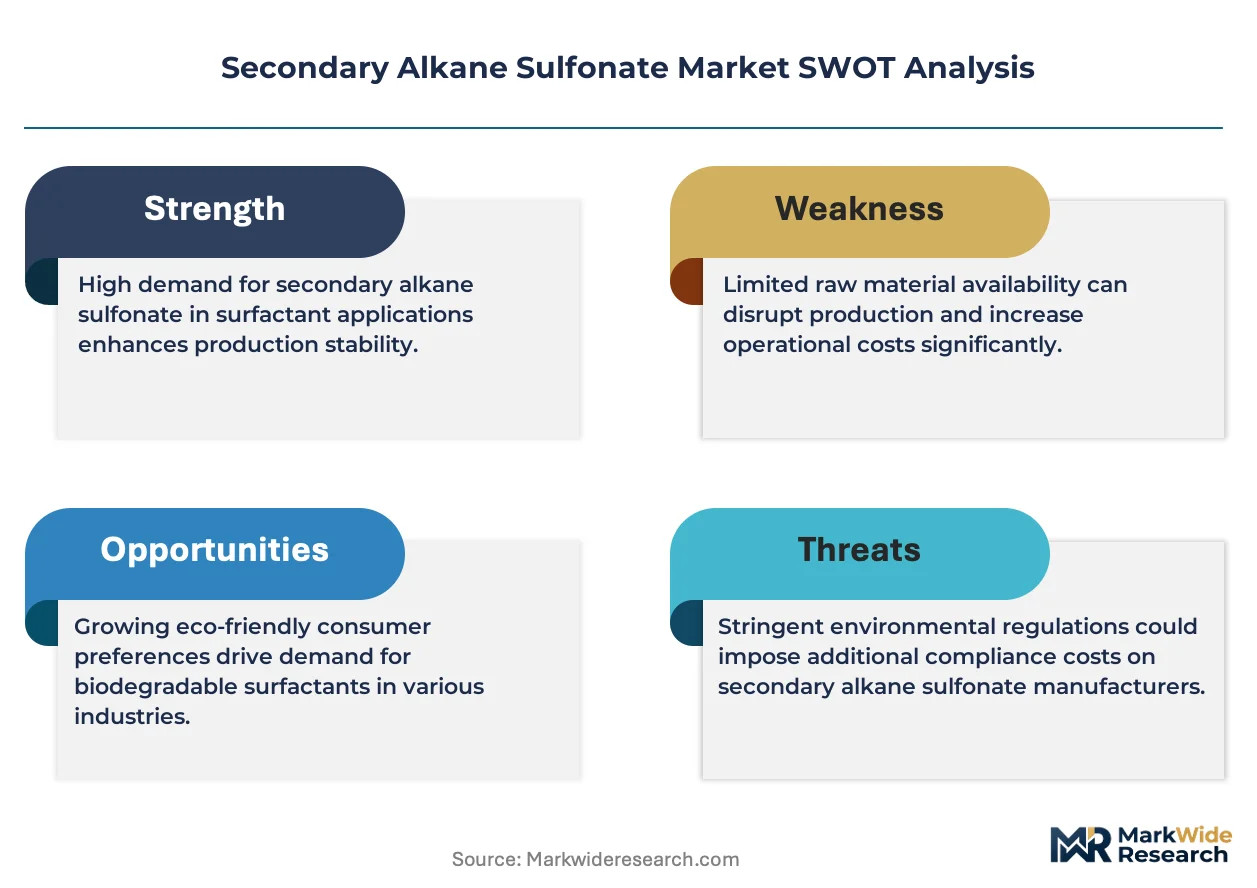
Strategic Opportunities
- Closed-loop textile processing:Fiber finishing operations in Portugal and Spain present underpenetrated demand for surfactants with hard-water tolerance and low aquatic toxicity profiles.
- OECD 301 biodegradability certification:Anticipated protocol revisions create first-mover advantage for producers pre-validating powder-grade dissolution kinetics against updated test methods.
- Direct-to-blender digital channels:Industrial detergent compounders in Poland and Czech Republic adopt platform-based procurement, disintermediating traditional distribution tiers.
Industry Challenges
- Sulfonation reactor engineering expertise:Shortage of process chemists capable of optimizing SO3/air ratio control and heat removal limits capacity expansion at mid-scale European facilities.
- Multi-jurisdiction registration synchronization:Divergent biodegradability test protocols between EU ECHA, EPA Office of Chemical Safety, and OECD guideline updates extend product qualification timelines.
- Legacy emulsifier system integration:Textile processors face reformulation complexity when substituting secondary alkane sulfonate for nonylphenol ethoxylates in existing bath chemistry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Secondary Alkane Sulfonate Market |
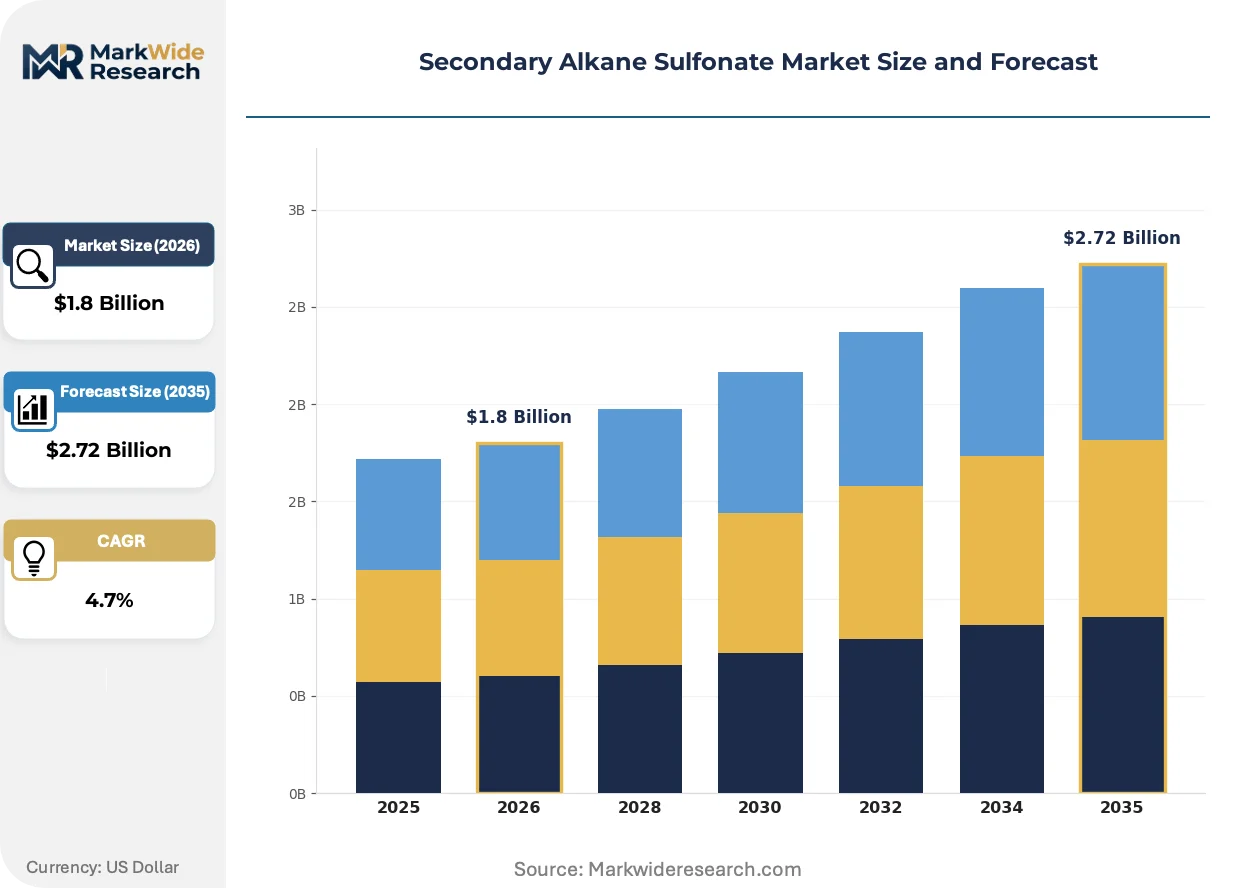
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granule, Pellet Application: Detergents, Emulsifiers, Surfactants, Textile Chemicals End User: Household, Industrial, Commercial, Personal Care Distribution Channel: Online, Retail, Direct Sales, Wholesale |
| Companies Covered | BASF, WeylChem Performance Products GmbH, Clariant AG, S.C. Johnson & Son, BIG SUN Chemical Corporation, Lanxess AG, Chevron Phillips Chemical, Sasol, Stepan Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Secondary Alkane Sulfonate Market Emerging Trajectories
Bio-based feedstock qualification and sulfonation process intensification are restructuring how surfactant producers configure asset footprints and customer technical service capabilities across European supply chains.
Continuous film sulfonation reactor technology is bifurcating the competitive landscape between integrated petrochemical players and specialized surfactant houses. German chemical clusters adopt falling-film reactors for C12-C18 feedstock conversion at higher active matter yields. This equipment shift is compressing economics for batch-reactor operators while enabling just-in-time liquid formulation supply to detergent blenders.
REACH Annex XIV authorization requirements for persistent, bioaccumulative substances are tightening emulsifier specifications in textile wet processing. Industrial laundries and fiber finishers face reformulation deadlines that disqualify legacy alkylphenol ethoxylates. The Netherlands and Belgium witness accelerated technical trials of secondary alkane sulfonate in scouring and mercerizing applications.
Compounders now specify surfactant performance through total cost-in-use metrics rather than unit price procurement. Large industrial detergent buyers in France and Italy unbundle technical service from material supply, contracting directly with sulfonation operators for custom C13-C17 chain length blends. This purchasing behavior concentrates volume with producers maintaining captive sulfonation and application laboratories.
Secondary Alkane Sulfonate Market Segmentation
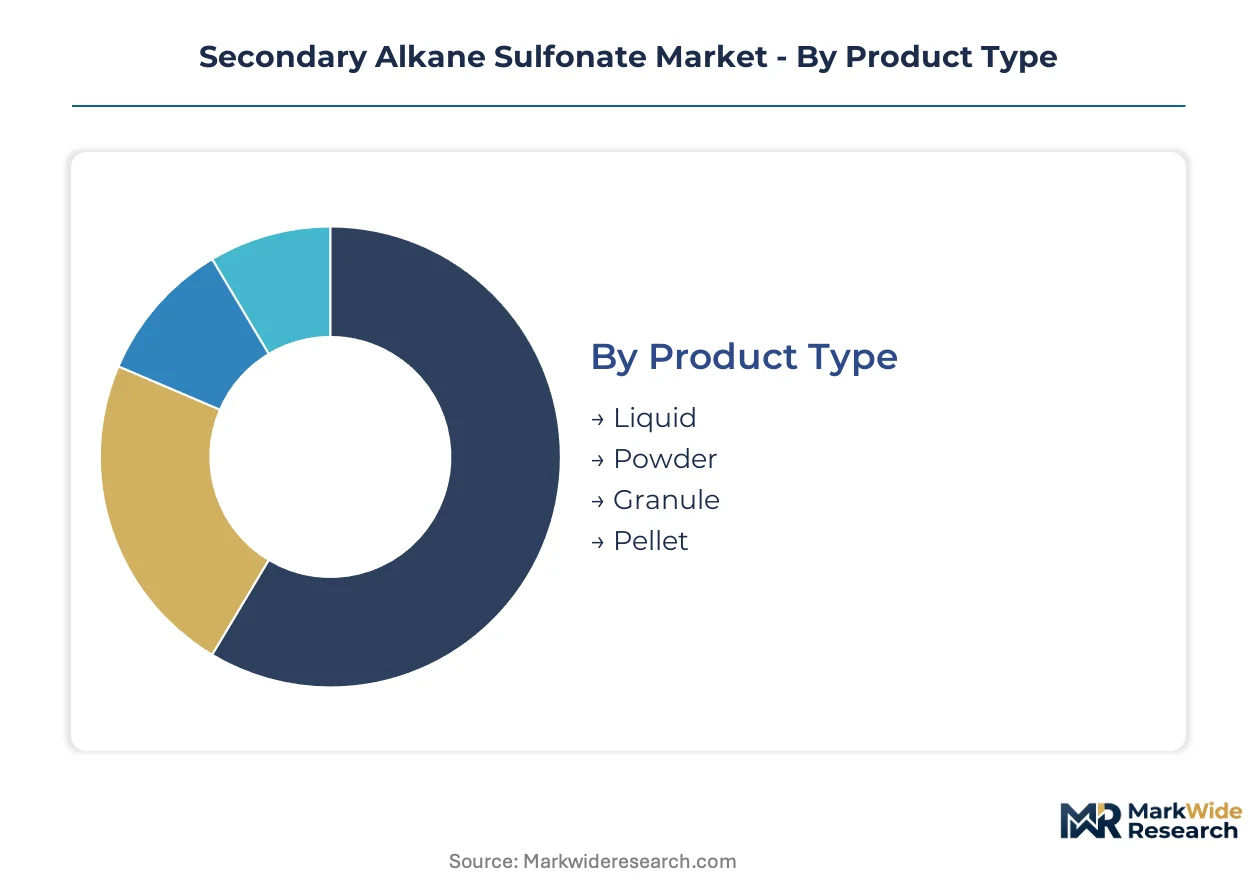
Secondary alkane sulfonate procurement patterns diverge sharply between industrial compounders seeking bulk liquid delivery and household brands prioritizing powder dissolution performance. Channel economics and formulation requirements dictate how producers allocate sulfonation capacity across physical form factors and customer tiers.
Product Type:
Liquid formulations flow predominantly through direct sales channels to industrial detergent blenders, while powder and solid grades reach household markets via distribution intermediaries.
- Liquid:Contains 30-60% active matter in aqueous solution, optimized for bulk tanker delivery to industrial laundries and textile processing facilities. Demand concentrates in Germany and the Netherlands where specialty chemical clusters support just-in-time blending operations. REACH compliance timelines favor liquid supply chains with established biodegradability documentation.
- Powder:Spray-dried granules with superior dissolution kinetics command margin premiums in household laundry applications. French and Italian detergent manufacturers specify powder grades for compact detergent formulations where storage stability and metering precision prove critical.
- Granule:Intermediate particle size distribution targets industrial compounders requiring controlled dust properties during pneumatic conveying.
- Pellet:High-density solid form minimizes packaging and transport costs for remote industrial users in Poland and Czech Republic.
By volume, Liquid leads. By growth pace, Powder is ahead.
Application:
Cost tier differentiation separates commodity detergent applications from specialty emulsifier and textile chemical segments where technical service capabilities command pricing power.
- Detergents:Hard-surface cleaners and laundry formulations represent the baseline volume application, with C13-C17 chain lengths selected for alkali stability and foam control. Industrial laundries in Belgium specify secondary alkane sulfonate for compatibility with closed-loop water recovery systems.
- Textile Chemicals:Fiber scouring and mercerizing operations drive the steepest expansion trajectory as Portuguese and Spanish processors replace alkylphenol ethoxylates ahead of EU authorization deadlines. ECHA substance evaluation protocols favor secondary alkane sulfonate for aquatic toxicity profiles.
- Emulsifiers:Metalworking fluids and agrochemical formulations require precise HLB balance achievable through custom C12-C18 chain length blending.
- Surfactants:General-purpose wetting agent sales concentrate through wholesale distribution to smaller compounders lacking captive sulfonation.
By revenue scale, Detergents dominates. By margin structure, Textile Chemicals outperforms.
End User:
Customer type determines specification intensity, with industrial buyers unbundling technical service from material supply while household brands consolidate procurement through platform channels.
- Industrial:Large-scale detergent compounders in France and Italy contract directly with sulfonation operators for custom chain length blends, specifying total cost-in-use metrics rather than unit pricing. Captive application laboratories differentiate supplier relationships.
- Household:Consumer laundry brands prioritize dissolution kinetics and fragrance compatibility, driving powder grade specifications with extended shelf-life requirements.
- Commercial:Institutional laundries and food service cleaning operations seek mid-tier liquid formulations balancing performance with regulatory compliance documentation.
- Personal Care:Cosmetic and toiletry applications represent a constrained niche due to stringent EU Cosmetics Regulation purity requirements and extended safety assessment timelines.
By procurement volume, Industrial leads. By specification complexity, Personal Care demands the most.
Distribution Channel:
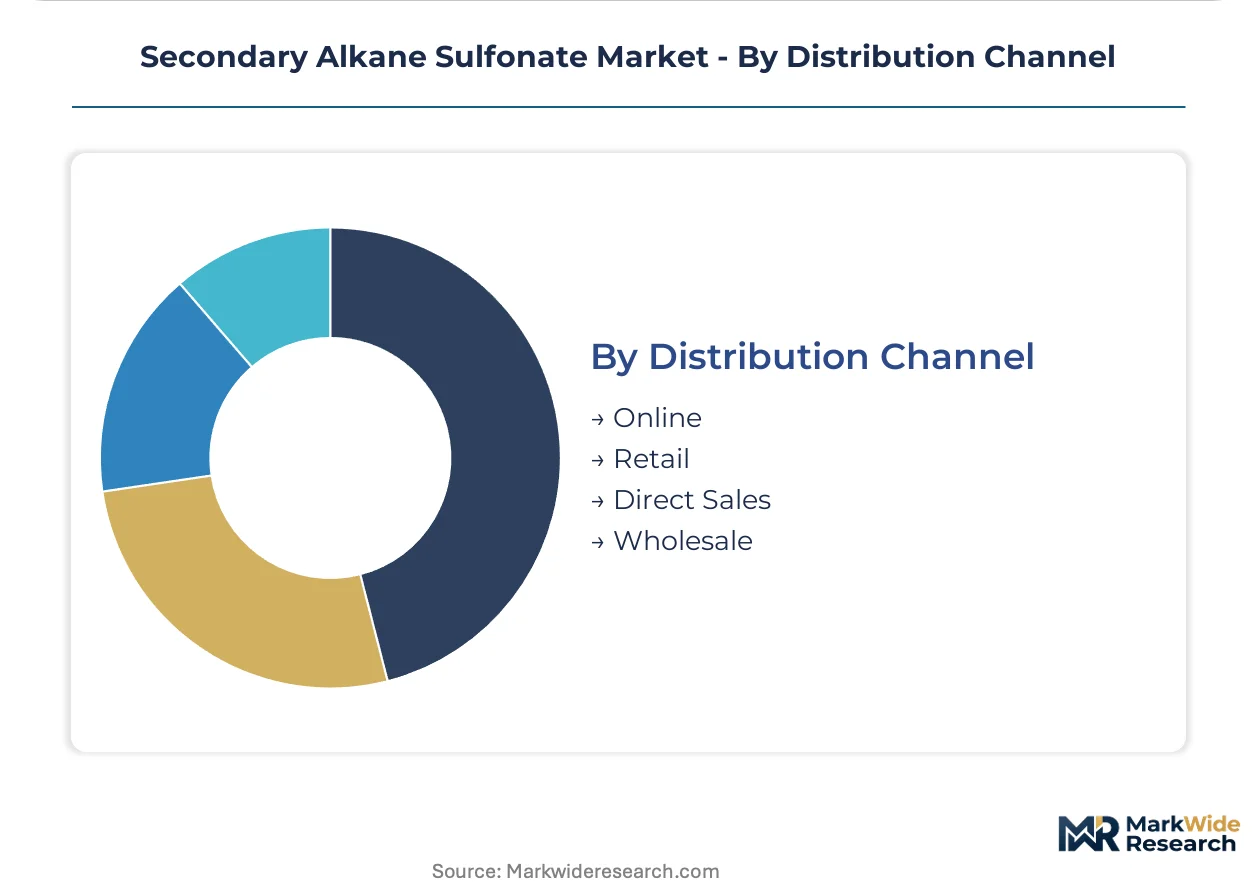
Supply concentration in German and Dutch chemical clusters shapes channel economics, with direct sales capturing value from proximity while digital platforms disintermediate traditional tiers in Eastern European markets.
- Direct Sales:Integrated producers BASF and Clariant AG leverage Frankfurt-Rhine-Main and Rotterdam-Antwerp corridor proximity to supply detergent blenders via dedicated tanker logistics. Technical service bundling reinforces customer retention.
- Wholesale:Regional distributors inventory standard liquid grades for mid-scale compounders in Poland and Czech Republic lacking volume to justify direct contracts.
- Online:Platform-based procurement gains traction among industrial detergent compounders seeking price transparency and reduced order cycle times.
- Retail:Packaged powder and granule sales to small commercial users and maintenance operations flow through specialty chemical distributors with regional warehousing.
By value capture, Direct Sales leads. By expansion velocity, Online is climbing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA substance evaluation protocols under REACH anchor European demand patterns for secondary alkane sulfonate, with Germany's Federal Environment Agency setting biodegradability thresholds that cascade across neighboring jurisdictions.
Germany
Industrial detergent compounders in the Frankfurt-Rhine-Main corridor drive procurement volumes for C13-C17 chain liquid formulations. The Federal Environment Agency enforces stricter aquatic toxicity standards than baseline REACH requirements. Specialty chemical clusters around Frankfurt sustain captive sulfonation capacity for just-in-time supply to textile processors.
Netherlands
Fiber finishers in the Rotterdam-Antwerp corridor seek surfactants compatible with closed-loop water recovery systems. Dutch regulators align with ECHA substance evaluation timelines while accelerating authorization deadlines for persistent organic pollutants. Chemical processing facilities near Rotterdam expand technical trials of alkali-stable anionic surfactants in mercerizing applications.
United States
EPA registration requirements under the Toxic Substances Control Act constrain new sulfonate entrants into cleaning product supply chains. Industrial laundries in the Midwest specify secondary alkane sulfonate for hard-water tolerance in institutional formulations. Stepan Company leverages North American manufacturing scale across detergent chemical channels.
France
Household detergent manufacturers prioritize powder-grade specifications with superior dissolution kinetics for compact laundry formulations. ANSM and environmental regulators enforce EU Green Deal compliance timelines for surfactant biodegradability. Lyon-area chemical processors contract directly with sulfonation operators for custom chain length blends.
Belgium
Textile scouring operations in Flanders replace alkylphenol ethoxylates ahead of EU authorization deadlines. Federal Public Service Health coordinates with ECHA on substance evaluation protocols for industrial emulsifiers. Ghent-based fiber processors validate secondary alkane sulfonate performance in closed-loop water systems.
Secondary Alkane Sulfonate Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with the former commanding captive feedstock infrastructure and the latter competing on application-specific technical service. The market structures around sulfonation reactor ownership and C12-C18 paraffin supply chain control. Three archetypes dominate: integrated petrochemical majors with backward feedstock integration, specialty surfactant houses with dedicated R&D laboratories, and regional compounders sourcing merchant sulfonate. Capacity expansion and portfolio diversification toward bio-based alternatives represent the primary competitive vectors.
Among integrated German chemical producers, BASF and Lanxess AG occupy positions anchored by Rhine-Ruhr feedstock infrastructure. Clariant AG exemplifies the specialty surfactant archetype through its Frankfurt-area technical service capabilities. Stepan Company represents North American manufacturing scale across detergent chemical channels. WeylChem Performance Products GmbH sits within the mid-tier specialist segment serving custom formulation demand.
| Leading Market Players |
|---|
| BASF |
| WeylChem Performance Products GmbH |
| Clariant AG |
| S.C. Johnson & Son |
| BIG SUN Chemical Corporation |
| Lanxess AG |
| Chevron Phillips Chemical |
| Sasol |
| Stepan Company |
| Others |
Supply Flow & Price Mechanics
Thirty-to-forty-five day inventory cycles for C12-C18 paraffinic feedstock in the Rotterdam-Antwerp corridor concentrate pricing power with integrated producers possessing captive sulfonation capacity, while merchant buyers absorb volatility through formula-based contract structures tied to naphtha-cracker output indices.
Pricing Analysis
Price spreads between German and Polish delivery points for liquid C13-C17 grades reflect differential logistics burdens and REACH documentation completeness. Contract-based long-term offtake dominates procurement, with price differentiation resting on active matter concentration and OECD 301 biodegradability certification tier. Cost compression in standard-grade liquid formulations is intensifying because alcohol ether sulfate substitution threatens volume share. Industrial detergent compounders in France and Italy exhibit lowest price sensitivity due to total cost-in-use procurement metrics, while mid-scale Polish blenders face highest sensitivity to unit price fluctuations.
Supply Chain Analysis
Port congestion on Rhine barge routes and container availability constraints in the Hamburg-Rotterdam trade lane elevate inbound logistics costs for merchant sulfonate sourced outside integrated chemical clusters. Supply concentrates in Germany, the Netherlands, and Belgium, with production drawing from C12-C18 paraffinic feedstock, SO3/air sulfonation reagents, and spray-drying energy inputs. Single-source vulnerability around specialized process chemists capable of reactor optimization limits capacity expansion at mid-scale facilities. Distribution runs through direct tanker logistics to industrial blenders, wholesale regional stocking for mid-tier compounders, and emerging platform channels in Eastern European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Secondary alkane sulfonate sits in early-cycle expansion as EU Green Deal compliance deadlines accelerate displacement of alkylphenol ethoxylates in textile wet processing, creating substantive penetration headroom ahead of authorization cliff effects.
For Market Incumbents: Fortify captive sulfonation capacity in the Frankfurt-Rhine-Main corridor to defend against merchant feedstock cost volatility, while deepening technical service laboratories to anchor industrial compounder relationships against specialty surfactant house encroachment. Prioritize OECD 301 pre-validation investments ahead of protocol revisions to lock in premium positioning. For New Entrants and Emerging Players: Custom chain length blending services for metalworking fluid emulsifiers represent an under-served technical niche where incumbent R&D intensity lags, particularly in Portugal and Spain where fiber processors seek hard-water-tolerant alternatives. Penetrate through direct technical sales engagement with mid-scale textile finishers bypassing traditional distribution tiers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because REACH Annex XIV authorization timelines create predictable substitution demand windows with multi-year visibility. Target mid-tier specialists with captive sulfonation assets and established ECHA substance evaluation dossiers. Monitor ECHA substance evaluation protocol publication schedules as inflection indicators for reformulation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into C12-C18 Paraffin Supply | Rhine-Ruhr feedstock control insulates margin against naphtha-cracker volatility. |
| OECD 301 Biodegradability Pre-Certification | First-mover validation against anticipated protocol revisions captures premium tier positioning. |
| Joint Venture with Textile Chemical Compounders | Portuguese and Spanish fiber processor partnerships accelerate alkylphenol ethoxylate displacement. |
| Long-term Supply Agreement with Industrial Laundries | Belgian closed-loop water system compatibility trials anchor volume through reformulation cycles. |
| Green Manufacturing Transition to Bio-Based Feedstock | EU Green Deal compliance positioning ahead of petrochemical-derived surfactant specification tightening. |
Methodological Framework
Operator-level perspectives from sulfonation plant managers, procurement leads at detergent compounders, distribution channel partners, and technical R&D directors anchored the qualitative base for this analysis. Primary interview insights combined with secondary validation from customs/trade data, Cefic surfactant reports, SEC 10-K filings, and ECHA substance evaluation databases. Bottom-up volume modeling across product type, application, end user, and distribution channel dimensions triangulated against top-down market sizing from regional production cluster analysis.
Sensitivity analysis around feedstock price volatility, REACH compliance timeline acceleration, and substitution elasticity informed the analytical framework across the projection horizon. Segmentation dimensions modeled include physical form factor, end-use industry, customer scale tier, and regional regulatory cluster. CAGRs derived from regression analysis of historical volume flows and penetration rate assumptions for textile chemical applications. Industry-specific inputs encompassed sulfonation reactor capacity utilization rates and ECHA authorization deadline phasing.
Forecasts assume regulatory continuity in EU REACH and EPA TSCA regimes; material policy shifts would require re-modeling. Specific risk factors include OECD 301 protocol revision timing, paraffinic feedstock supply disruptions from naphtha-cracker economics, and alcohol ether sulfate substitution acceleration in industrial degreaser segments. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Specialty Surfactants Market
Surfactants
Non-Ionic Surfactants Market
Surfactants
Sodium Lauroyl Glycinate Market
Surfactants
Polysorbate 40 Market
Surfactants
Global Demulsifiers Market
Surfactants
Global Rhamnolipid Market
Surfactants
North America Non-Ionic Surfactants Market
Surfactants
Procream Market
Surfactants
Amino Silicone Oil Market
Surfactants
Global Fluorosurfactants Market
Surfactants
Cyclopentasiloxane Market
Surfactants
Anionic Surfactants Market
Surfactants
Global Methyl Soyate Market
Surfactants
Cetyl Chloride Market
Surfactants
Selenium Sulphide Market
Surfactants
Micellar Water Market