
 Semiconductor Test Socket Market | 2026-2036
Semiconductor Test Socket Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Test Socket Market Insights
Software-defined test configuration is shifting how socket vendors monetize hardware. Cohu leverages remote diagnostics and predictive calibration to extend customer lifetime value. Yamaichi Electronics sustains its position through deep backward integration into precision machining. Enplas differentiates via proprietary elastomer contact technologies for high-pin-count applications.
A semiconductor test socket is a mechanical interface that establishes temporary electrical contact between a device under test and automated test equipment, typically engineered with beryllium copper or nickel alloys for signal integrity and cycle durability exceeding one million insertions. Its primary purpose is enabling wafer-level and package-level validation of integrated circuits before volume shipment. Multi-site sockets command premium positioning as throughput demands intensify in memory and logic testing, while thermal technology segments capture expanding margin pools from automotive-grade and data-center chip qualification. Customized sockets for RF devices and MEMS sensors represent the fastest-growing application dimension, driven by heterogeneous integration trends.
FCC equipment authorization rules in the United States, REACH substance restrictions in Europe, and Taiwan's NCC electromagnetic compatibility standards collectively govern contact material composition and signal integrity benchmarks across major demand centers. These frameworks elevate engineering costs for new socket platforms but simultaneously lock out undifferentiated competitors lacking certified material traceability. Stakeholders must weigh thermal expansion coefficient matching against emerging co-packaged optical interconnect requirements when allocating R&D budgets.
Market Dynamics
Advanced packaging architectures—chiplet integration, 2.5D interposers, and 3D stacking—are forcing socket vendors to redesign contact geometries for finer pitches and higher thermal loads. This structural pressure cascades through material selection, precision machining tolerances, and calibration protocols.
Growth Catalysts
- High-performance computing clusters:Data-center GPU and AI accelerator qualification cycles demand multi-site sockets with sub-50-micron alignment accuracy. Taiwan's NCC electromagnetic compatibility standards accelerate certified product deployment.
- EU F-Gas Regulation:Phasedown of hydrofluorocarbon-based thermal interface materials pushes socket manufacturers toward phase-change metal alloys and graphite composites for automotive-grade temperature cycling.
- Wafer-level probing migration:Fan-out wafer-level packaging adoption in South Korean memory fabs extends socket utilization from final test to intermediate burn-in stages.
Market Restraints
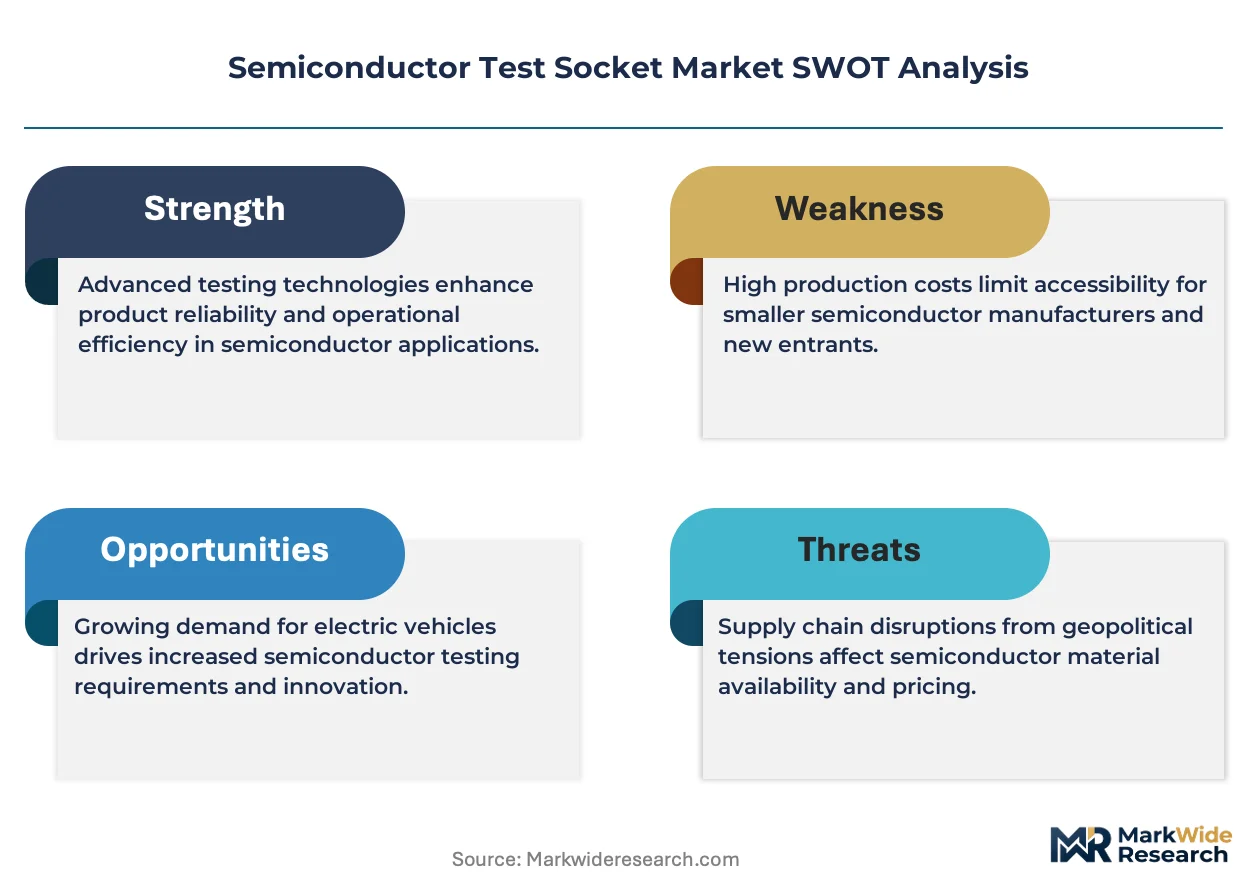
- Beryllium copper supply concentration:Over 70% of high-conductivity alloy feedstock originates from a single US smelter complex, exposing socket producers to price volatility and export license delays.
- REACH substance restrictions:ECHA candidate list expansion for nickel release thresholds forces reformulation of contact plating chemistries, extending qualification timelines by 8-14 months.
- Probe card substitution:Vertical probe card technology advancement for known-good-die testing captures margin pool in high-volume memory segments previously served by package-level sockets.
Strategic Opportunities
- Co-packaged optical interconnect qualification:Silicon photonics test requirements create demand for hybrid electrical-optical sockets combining RF signal integrity with fiber alignment precision.
- India semiconductor manufacturing incentives:PLI scheme disbursements for domestic packaging facilities generate localized socket sourcing mandates from 2026 qualification windows.
- Software-defined test cell integration:API-native socket configuration enables remote reconfiguration between logic and memory test programs, reducing hardware swap downtime.
Industry Challenges
- Thermal-mechanical simulation expertise:Finite element modeling for coefficient-of-thermal-expansion matching across heterogeneous substrate stacks requires scarce cross-trained materials and electrical engineers.
- ISO 9001 and IATF 16949 dual certification:Automotive socket qualification demands concurrent quality management audits, compressing supplier onboarding schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Test Socket Market |
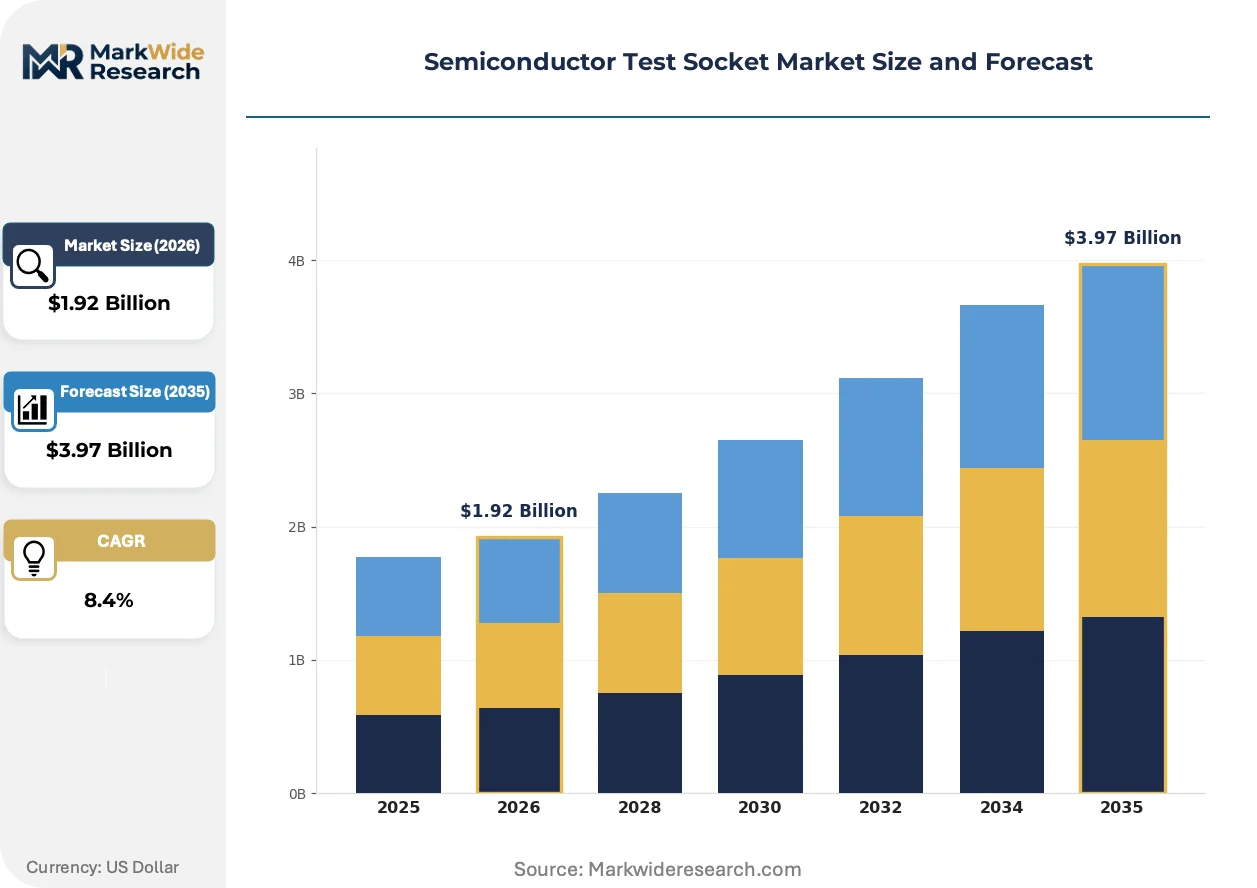
| Market Size in 2026 | $1.92 Billion |
| Market Size in 2035 | $3.97 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Site, Multi-Site, Universal, Customized Technology: Manual, Automated, Semi-Automated, Thermal End User: Semiconductor Manufacturers, Testing Facilities, OEMs, R&D Labs Application: Integrated Circuits, MEMS, RF Devices, Power Devices |
| Companies Covered | ISC Technology, Yokowo, Yamaichi Electronics, Boyd Corporation, Ironwood Electronics, Cohu, Smiths Interconnect, WinWay, Enplas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Test Socket Market Trends and Innovations
Socket architecture is fragmenting into application-specific platforms rather than universal designs. Vendors now optimize contact force profiles, thermal management, and signal routing independently for logic, memory, RF, and power device categories.
Spring probe contact technology is modularizing. These pogo-pin arrays now serve 0.35mm pitch devices with insertion forces below 30 grams per pin. Advanced packaging houses in Taiwan and South Korea specify spring probe sockets for 2.5D interposer qualification. The technology is modularizing test cell layouts, enabling rapid reconfiguration between device families without mechanical retooling.
REACH substance restrictions are tightening material disclosure requirements. ECHA SCIP database obligations now mandate full supply chain transparency for beryllium and nickel alloys above 0.1% concentration. European automotive OEMs are pushing this compliance burden upstream to socket vendors. Memory test socket producers with certified material traceability systems capture preferential placement in German and French fab qualification programs.
Buyers are unbundling socket hardware from calibration service contracts. IDMs and OSATs now procure test interfaces through capital equipment budgets while sourcing predictive maintenance and contact wear monitoring separately. This procurement split concentrates among US and Taiwanese firms with internal metrology capabilities. Korean packaging houses lag this transition, maintaining bundled purchasing patterns through captive equipment divisions.
Semiconductor Test Socket Market Segmentation
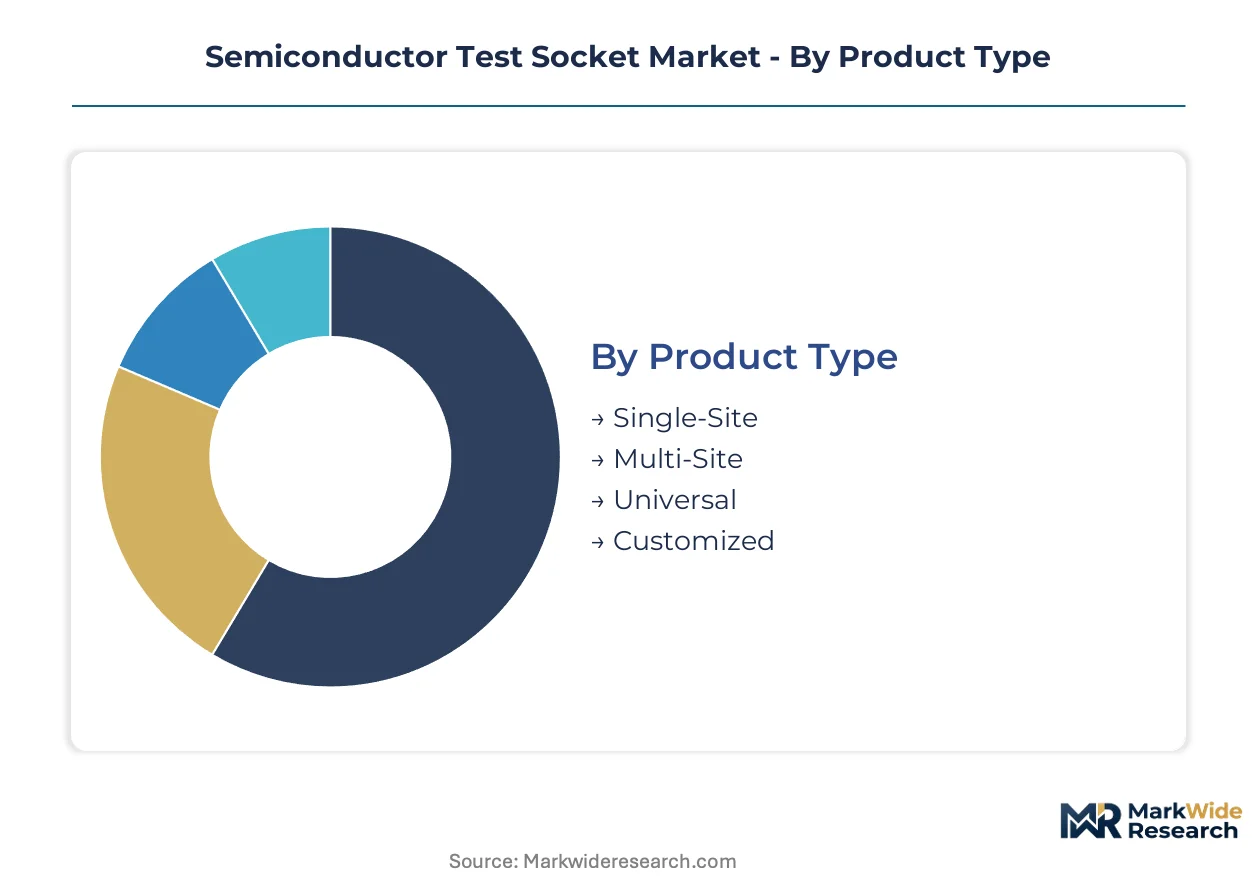
Socket architecture fragments along application-specific performance thresholds rather than universal compatibility. Buyers now select contact geometries, thermal management systems, and signal routing independently based on device category qualification requirements.
Product Type:
Capital equipment budgets and throughput targets determine socket procurement patterns across IDM and OSAT facilities.
- Multi-Site:Parallel testing arrays accommodate 4-16 devices simultaneously, reducing cost-per-test for high-volume memory and logic qualification. Taiwan's leading-edge packaging houses specify multi-site configurations for data-center GPU burn-in cycles where throughput directly determines fab economics.
- Customized:Application-specific designs integrate proprietary contact force profiles and thermal interface geometries for heterogeneous integration architectures. South Korean memory fabs commission customized sockets for 3D NAND stack validation where standard pitch tolerances prove insufficient.
- Single-Site:Individual device testing platforms serve low-volume, high-mix qualification environments.
- Universal:Reconfigurable contact arrays adapt across multiple package formats through interchangeable insert plates.
Volume sits with Multi-Site configurations; growth tilts toward Customized solutions for advanced packaging qualification.
Technology:
Automation intensity correlates with fab scale and labor cost structures in major manufacturing clusters.
- Thermal:Integrated temperature cycling systems combine electrical contact with active heating and cooling for automotive-grade reliability testing. EU F-Gas Regulation compliance drives phase-change metal alloy adoption over hydrofluorocarbon-based thermal interfaces in German automotive qualification facilities.
- Automated:Robotic handler integration enables continuous operation with sub-50-micron alignment accuracy for fine-pitch devices. United States-based IDMs deploy automated test cells for AI accelerator qualification where manual intervention introduces contamination risk.
- Semi-Automated:Operator-assisted loading combines throughput efficiency with flexibility for medium-volume production.
- Manual:Benchtop configurations serve prototype validation and engineering characterization.
Revenue concentrates in Thermal technology; expansion accelerates most quickly in Automated systems for high-volume logic testing.
End User:
Procurement authority and technical specification ownership vary dramatically across the value chain.
- Semiconductor Manufacturers:Captive test engineering teams specify sockets for in-house wafer probe and final test operations. Taiwan's integrated device manufacturers maintain direct vendor relationships for leading-edge process node qualification.
- Testing Facilities:Independent validation laboratories source configurable platforms serving multiple client qualification programs. United States-based third-party test houses unbundle hardware procurement from calibration service contracts.
- OEMs:System-level manufacturers specify sockets for component incoming inspection and failure analysis.
- R&D Labs:Research institutions prioritize measurement precision and flexibility over throughput metrics.
Socket shipments flow predominantly to Semiconductor Manufacturers; Testing Facilities expand procurement fastest as OSATs outsource qualification capacity.
Application:
Signal integrity requirements and thermal loads diverge sharply across device physics.
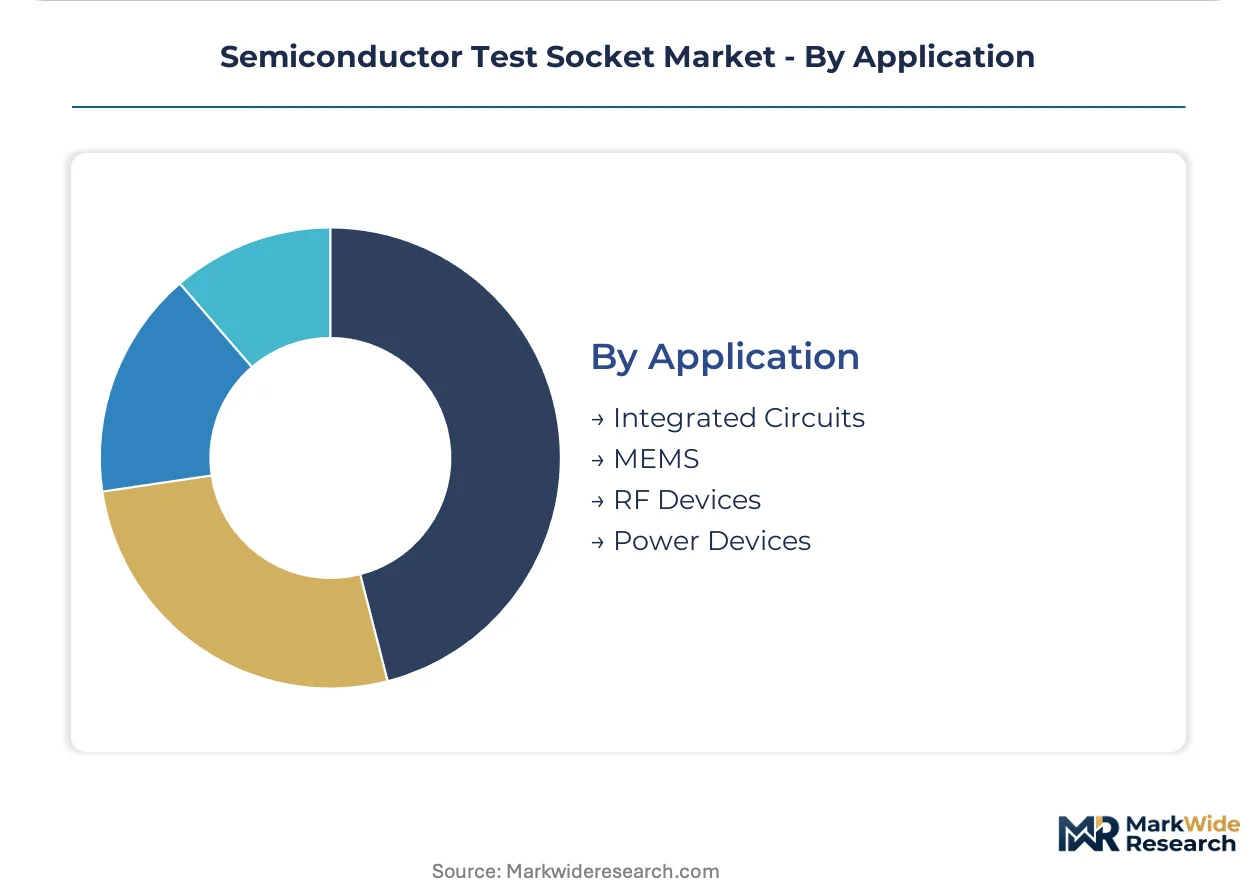
- RF Devices:Coaxial contact structures preserve impedance matching through 110 GHz for 5G baseband and millimeter-wave components. Taiwan's NCC electromagnetic compatibility standards mandate specific shielding geometries for cellular modem qualification.
- MEMS:Specialized force-controlled insertion protects fragile microelectromechanical structures during electrical verification. South Korean sensor fabs require MEMS-specific sockets for automotive accelerometer and gyroscope testing.
- Integrated Circuits:General-purpose digital and analog device qualification represents the established volume base.
- Power Devices:High-current contact designs accommodate thermal dissipation requirements for discrete and module-level power electronics.
Integrated Circuits anchor current volume; RF Devices climb the fastest as silicon photonics and heterogeneous integration multiply test complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Socket consumption concentrates where leading-edge fabs operate, while production capacity clusters near precision machining ecosystems and beryllium copper supply chains. Taiwan, South Korea, and the United States absorb the majority of high-performance test socket shipments.
Taiwan
TSMC's advanced packaging expansion at the Southern Taiwan Science Park drives multi-site socket procurement for 3nm and 2nm node qualification. NCC electromagnetic compatibility standards mandate specific contact geometries for cellular modem and AI accelerator testing. Hsinchu Science Park hosts the densest concentration of socket validation labs serving global IDM customers.
South Korea
Samsung and SK Hynix memory fab expansions in Pyeongtaek and Icheon sustain demand for customized sockets handling 3D NAND stack validation. MFDS alignment with REACH substance restrictions accelerates certified material traceability requirements for automotive-grade socket shipments. Yongin and Suwon house specialized test engineering centers specifying thermal cycling interfaces for reliability qualification.
United States
Intel's Arizona and Ohio fab investments plus NVIDIA's AI accelerator qualification cycles sustain premium socket procurement. FCC equipment authorization rules govern RF signal integrity benchmarks for 5G and millimeter-wave device testing. Greater Phoenix and Silicon Valley concentrate third-party test facilities unbundling hardware procurement from calibration services.
Germany
Automotive semiconductor qualification for Bosch and Infineon drives thermal socket demand exceeding 150°C cycling requirements. EU F-Gas Regulation compliance forces phase-change metal alloy adoption over hydrofluorocarbon-based thermal interfaces. Dresden's Silicon Saxony cluster anchors European socket sourcing for power electronics and sensor testing.
Japan
Tokyo Electron and Advantest equipment integration requirements shape socket mechanical specifications for domestic test cell deployments. METI semiconductor resilience initiatives subsidize local socket sourcing for critical automotive and industrial chip qualification. Kumamoto and Hiroshima prefectures concentrate legacy memory fab operations sustaining single-site socket utilization.
Semiconductor Test Socket Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent margin structures. The vendor base organizes around three tiers: integrated test equipment suppliers, precision machining specialists, and contact technology pure-plays. Strategic differentiation flows from backward integration into beryllium copper supply chains, captive thermal interface material formulation, and software-enabled remote calibration capabilities. Competitive intensity centers on qualification timeline compression and automotive certification breadth rather than unit pricing alone.
Among Japanese fabricators, Yamaichi Electronics exemplifies precision machining depth, while Yokowo occupies a position emphasizing miniaturized contact geometries. Enplas represents the elastomer contact specialization archetype for high-pin-count applications. Cohu anchors the test equipment integration tier, leveraging diagnostic software to extend customer lifetime value beyond hardware shipment. These three archetypes—machining-integrated, materials-specialized, and software-augmented—capture divergent margin pools across logic, memory, and RF testing segments.
| Leading Market Players |
|---|
| ISC Technology |
| Yokowo |
| Yamaichi Electronics |
| Boyd Corporation |
| Ironwood Electronics |
| Cohu |
| Smiths Interconnect |
| WinWay |
| Enplas |
| Others |
Pricing and Supply Chain Analysis
Beryllium copper alloy feedstock flows from a single US smelter complex through three pricing tiers before reaching socket manufacturers, with raw material concentration upstream translating directly into margin compression downstream for non-integrated fabricators.
Pricing Analysis
Margin tightening in standard-grade sockets reflects probe card substitution pressure in high-volume memory testing. Three-tier pricing structure across premium, standard, and economy levels separates automotive-certified thermal platforms from benchtop configurations. Price differentiation hinges on REACH material traceability certification and multi-site throughput capability. IDM procurement teams exhibit highest price sensitivity for universal socket formats, while automotive qualification programs absorb premium positioning for thermal cycling interfaces.
Supply Chain Analysis
Single-source vulnerability sits with the US-based beryllium copper smelter supplying over seventy percent of high-conductivity alloy feedstock. Precision machining capacity clusters in Japan, Taiwan, and Germany, drawing from nickel plating chemistries and graphite thermal interface materials. Tariff exposure on raw metal imports threatens margin stability for European socket vendors. Distribution runs through direct OEM relationships and captive equipment divisions at Korean packaging houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where EU F-Gas Regulation and REACH substance restrictions erect engineering barriers that favor incumbents with certified material traceability systems.
For Market Incumbents: Cement automotive certification breadth through concurrent ISO 9001 and IATF 16949 audits, compressing supplier onboarding timelines that lock out undifferentiated competitors. Deepen backward integration into beryllium copper supply chains to offset feedstock price volatility from the US smelter concentration. Probe card substitution in memory testing represents the primary margin threat requiring defensive thermal technology investment. For New Entrants and Emerging Players: Direct-to-equipment-manufacturer digital channels bypass bundled procurement patterns at Korean OSATs, opening white-space access for API-native socket configuration tools. Target independent US and Taiwanese test facilities unbundling hardware from calibration service contracts. MEMS sensor socket specialization offers the most penetrable entry vector given heterogeneous integration trends and limited incumbent focus. For Investors and Strategic Acquirers: India's PLI scheme disbursement for domestic packaging facilities is the leading indicator that localized socket sourcing mandates will reshape regional supply structures. Long-term viability favors precision machining specialists with captive thermal interface material formulation over asset-light designers lacking backward integration. Watch for silicon photonics qualification program awards as the inflection signal for hybrid electrical-optical socket demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Beryllium Copper Supply | Mitigates single-source feedstock risk from the US smelter complex. |
| REACH Material Traceability Certification | Locks in European automotive OEM placement against non-compliant competitors. |
| Software-Defined Test Cell Integration | Enables remote reconfiguration between logic and memory test programs. |
| Silicon Photonics Socket Development | Captures emerging hybrid electrical-optical qualification requirements. |
| India Localized Production Footprint | Qualifies for PLI scheme disbursements and domestic sourcing mandates. |
Research Methodology
Multi-period observation of socket shipment volumes, fab capacity expansion timelines, and regulatory compliance certification rates anchored the trend analysis, supplemented by interviews with test engineering directors at IDMs, procurement leads at OSATs, thermal interface material formulators, and precision machining specialists. Secondary validation drew from SEC filings of listed test equipment suppliers, Taiwan NCC electromagnetic compatibility standard updates, ECHA SCIP database disclosures, and customs trade data for beryllium copper alloy imports. Bottom-up socket demand modeling triangulated against top-down fab equipment capex forecasts.
Input-output matrices mapped contact geometry specifications, thermal cycling requirements, and automation intensity across product type, technology, and application segments. CAGRs were derived from regression analysis of historical socket procurement patterns against leading-edge node transition schedules. Forecast inputs incorporated EU F-Gas Regulation phasedown timelines and India PLI scheme qualification windows across the projection horizon.
The model holds under stable regulatory enforcement and continued advanced packaging adoption; deviation in REACH substance restriction expansion pace or beryllium copper export licensing would shift socket availability timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Semiconductor Metrology and Inspection Equipment Market
Test and Measurement
EMC Testing Market
Test and Measurement
Backside Power Delivery Network (BPDN) Analysis Test Equipment Market
Test and Measurement
Digital Depth Gauges Market
Test and Measurement
Dosimeter Market
Test and Measurement
Test and Measurement Sensors Market
Test and Measurement
Digital Weighing Terminal Market
Test and Measurement
Continuous Friction Tester Market
Test and Measurement
Europe NDT Equipment Market
Test and Measurement
Ground Grid Tester Market
Test and Measurement
Active Dosimeter Market
Test and Measurement
Density Meter Market
Test and Measurement
UPS Battery and Supercapacitor Health Diagnostics Test Equipment Market
Test and Measurement
Global General Purpose Test Equipment (GPTE) Market
Test and Measurement
Telescopic Inspection Mirror Market
Test and Measurement
Advanced Node Wafer Defect Inspection Systems Market