
 Corn Wet-Milling Market | 2026-2036
Corn Wet-Milling Market Size, Share, and Industry Trends Forecast 2026-2036
Corn Wet-Milling Market Analysis
Food-grade starch specifications is bifurcating the competitive landscape as buyers separate premium native starches from commodity modified grades. Cargill leverages its integrated supply chain from Iowa grain elevators to finished ingredient plants. Ingredion differentiates through specialty starch formulations targeting beverage texture and stability. Tate & Lyle anchors European demand with its London-based technical application centers.
Corn wet-milling is the industrial process of steeping corn kernels in dilute sulfurous acid, separating the grain into starch, germ, fiber, and gluten components through a series of grinding, screening, and centrifugation steps, with starch yields typically reaching sixty-five to seventy percent of kernel dry weight. The primary purpose is to produce refined carbohydrates, oils, and proteins for food manufacturing, animal nutrition, and industrial fermentation. Sweeteners derived from wet-milled starch occupy the largest value share as high-fructose corn syrup remains entrenched in beverage formulations. Bioplastics applications represent the fastest-expanding demand channel as polylactic acid producers seek consistent dextrose feedstock. Enzymatic processing technology leads margin pools through reduced energy intensity and higher extraction yields compared to mechanical alternatives.
The U.S. EPA administers Renewable Fuel Standard volume obligations that direct corn starch into ethanol production, while the FDA governs food-grade starch purity and labeling standards for human consumption. EFSA and REACH in Europe impose migration limits and chemical registration requirements on starch-based food contact materials and industrial derivatives. Stakeholders must monitor how biofuel policy revisions and clean-label certification programs redirect margin pools between fuel, food, and materials end uses.
Market Dynamics
Enzymatic processing technology is compressing energy margins across the corn wet-milling sector, forcing mechanical separation assets toward obsolescence while redirecting capital toward biocatalytic extraction systems.
Growth Catalysts
- EPA Renewable Fuel Standard:Volume obligations for corn-starch ethanol create guaranteed offtake for dextrose streams, locking in baseline demand from fuel blenders.
- Bioplastics feedstock specifications:Polylactic acid manufacturers require consistent dextrose purity, pulling higher-grade starch fractions away from commodity sweetener channels.
- Clean-label starch migration:Food and beverage formulators are reformulating around native starches, rewarding processors with segregated handling capabilities.
Market Restraints
- Natural gas price volatility:Drying and evaporation stages consume substantial thermal energy, exposing margin structures to input cost swings.
- Supply concentration in the Corn Belt:Iowa and Illinois processing clusters create geographic vulnerability to localized weather events and logistics disruptions.
- High-fructose corn syrup substitution:Beverage manufacturers are reformulating with cane sugar and alternative sweeteners in response to consumer health concerns.
Strategic Opportunities
- Bioplastics scale-up in the European Union:EFSA migration limits and REACH registration requirements favor established wet-millers with compliance infrastructure already in place.
- Specialty beverage texture systems:Premium carbonated and ready-to-drink coffee categories seek modified starches with specific shear stability and mouthfeel profiles.
- Carbon capture integration:Fermentation CO2 streams from ethanol production offer monetization pathways under emerging emissions accounting frameworks.
Industry Challenges
- Enzyme engineering talent scarcity:Biocatalytic process optimization requires specialized protein chemists and fermentation scientists in short supply across the Midwest.
- Segregated handling infrastructure:Clean-label and organic starch certifications demand parallel processing lines, doubling capital intensity for multi-grade producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corn Wet-Milling Market |
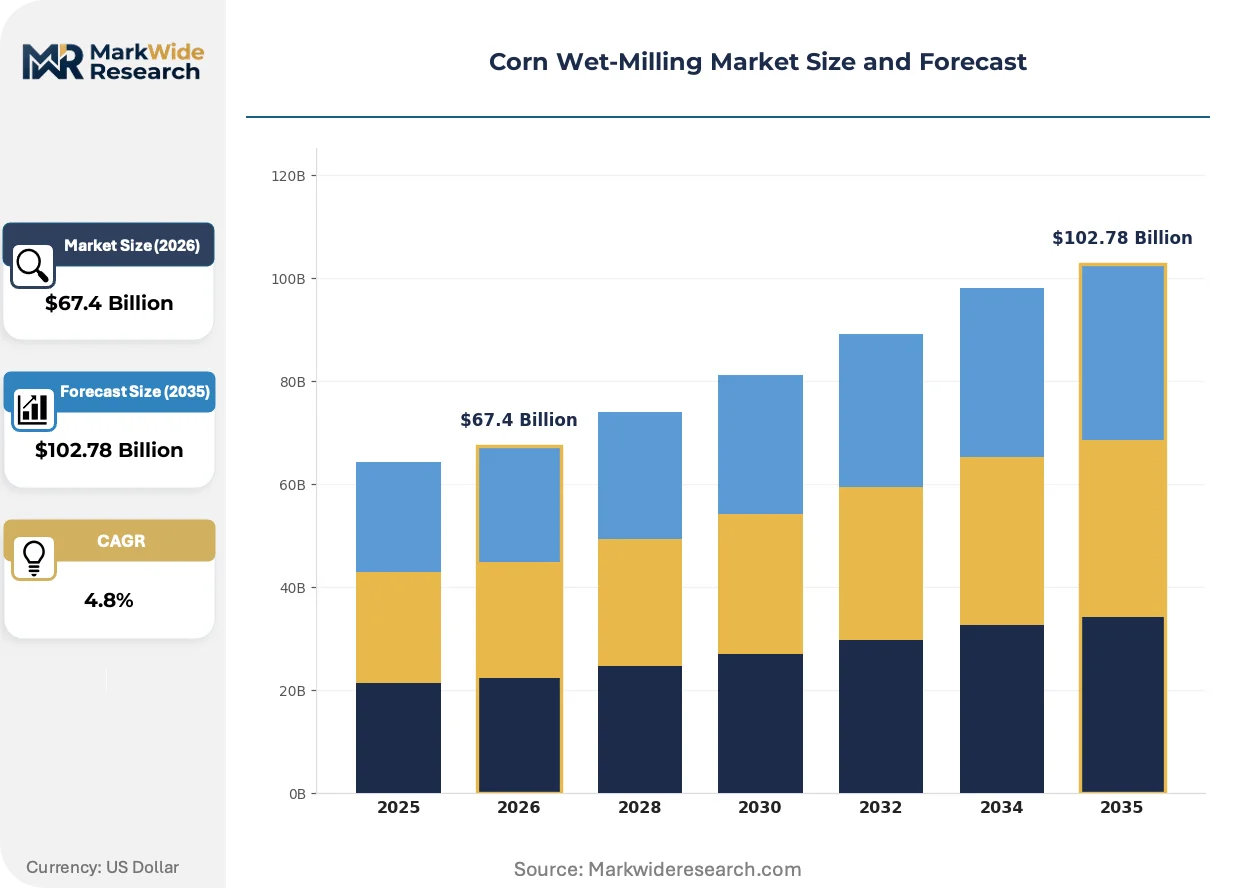
| Market Size in 2026 | $67.4 Billion |
| Market Size in 2035 | $102.78 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Starch, Corn Oil, Sweeteners, Gluten Application: Food & Beverage, Animal Feed, Bioplastics, Pharmaceuticals End User: Food Manufacturers, Beverage Producers, Animal Nutrition Companies, Industrial Users Technology: Batch Processing, Continuous Processing, Enzymatic Processing, Mechanical Processing |
| Companies Covered | Archer Daniels Midland Company, Cargill, Tate & Lyle, Ingredion, Agrana Beteiligungs, Roquette Freres, Grain Processing Corporation, Global Bio-Chem Technology Group Company, Bunge Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corn Wet-Milling Market Emerging Trajectories
Biocatalytic extraction systems are displacing mechanical separation across front-end processing, while regulatory carbon accounting and buyer procurement centralization reshape downstream value capture.
Membrane filtration technology is miniaturizing separation footprints in germ and fiber recovery stages. Mid-scale processors in Nebraska and Indiana are adopting ceramic microfiltration units that slash water consumption per bushel. This compression is enabling distributed processing models closer to farm gate collection points, challenging the historical dominance of large central wet-mills.
REACH chemical registration requirements in Europe are tightening purity specifications for starch derivatives used in food contact materials. Manufacturers exporting to the European Union must document migration limits for sulfurous acid residues and processing aids. Specialty grade producers with existing EFSA compliance infrastructure are capturing margin premiums as commodity exporters face exclusion.
Consolidated procurement by multinational beverage and food manufacturers is compressing supplier rosters. Buyers are centralizing starch sourcing through single-source agreements with integrated processors who control elevator-to-ingredient supply chains. This concentration is most visible in the carbonated soft drink sector, where three national brands now account for the majority of high-fructose corn syrup contract volumes.
Corn Wet-Milling Market Segmentation
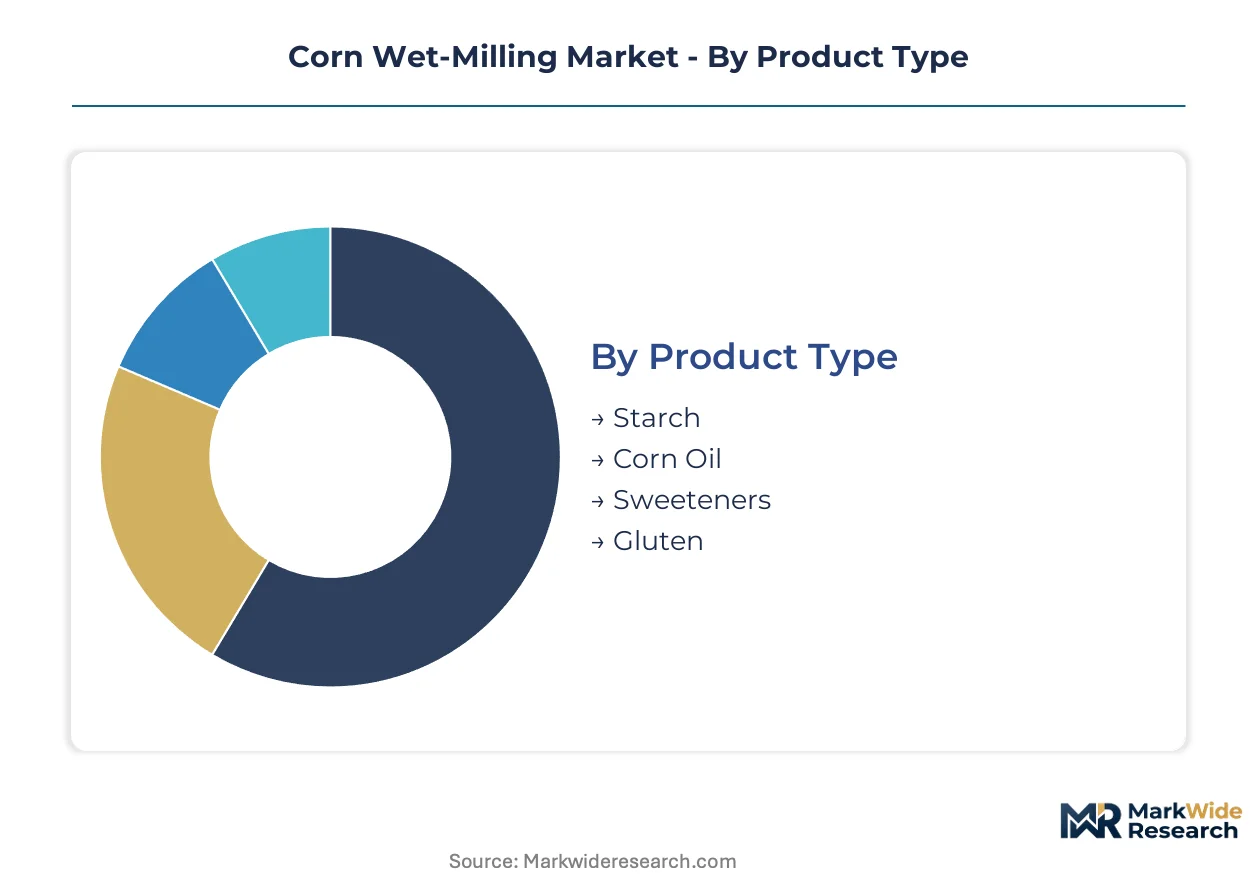
Corn wet-milling output splits into distinct commercial channels with divergent margin profiles and geographic pull. Each segment category carries different regulatory exposure, from EPA fuel mandates to EFSA food-contact standards, reshaping how processors allocate capacity across product lines.
Product Type:
Starch and sweetener demand concentrates heavily in domestic U.S. markets tied to fuel blending and beverage manufacturing, while corn oil and gluten fractions serve more export-oriented nutrition and industrial channels.
- Starch:Native and modified grades constitute the primary carbohydrate output, with specifications bifurcating between food-grade purity and industrial fermentation feedstock. U.S. ethanol producers under EPA Renewable Fuel Standard obligations absorb substantial volumes, though bioplastics manufacturers in Europe are pulling higher-purity fractions into polylactic acid supply chains.
- Sweeteners:High-fructose corn syrup dominates beverage applications despite reformulation pressures, while dextrose serves pharmaceutical and fermentation end uses. Carbonated soft drink procurement consolidation has compressed supplier rosters to integrated processors with captive corn supply.
- Corn Oil:Refined edible grades compete with soybean and canola oils in food service, while crude oil streams enter biodiesel and animal feed formulations.
- Gluten:Corn gluten meal supplies protein concentrate to poultry and aquaculture nutrition, with export demand concentrated in Southeast Asian livestock markets.
Starch commands the established base. The steepest expansion runs through sweeteners as bioplastics pull dextrose into non-food channels.
Application:
Cost tier differentiation separates commodity fuel and feed applications from premium food and pharmaceutical grades requiring segregated handling and certification documentation.
- Food & Beverage:Clean-label starch migration is forcing processors to maintain parallel native and modified production lines. Beverage texture systems and bakery stabilizers reward processors with application-specific formulation capabilities.
- Bioplastics:Polylactic acid producers require consistent dextrose purity above standard sweetener grades, creating margin premiums for processors with enzymatic refining capacity. European Union REACH registration requirements favor established wet-millers with existing compliance infrastructure.
- Animal Feed:Gluten meal and steep liquor supply protein and energy to poultry, swine, and aquaculture operations, with pricing indexed to soybean meal alternatives.
- Pharmaceuticals:USP-grade dextrose and excipient starches demand documented purity chains and FDA-compliant manufacturing protocols, limiting qualified suppliers.
Food and beverage anchors current revenue. Bioplastics is climbing the fastest as carbon accounting frameworks redirect capital into renewable materials.
End User:
Customer type determines contract structure, with multinational beverage manufacturers driving procurement centralization while animal nutrition companies maintain spot-market flexibility.
- Food Manufacturers:Clean-label reformulation is forcing starch suppliers to segregate organic and non-GMO streams, doubling capital intensity for multi-grade producers.
- Beverage Producers:Three national carbonated brands now account for the majority of high-fructose corn syrup contract volumes, concentrating pricing power among buyers.
- Animal Nutrition Companies:Feed compounders source gluten meal and steep liquor on protein-equivalent pricing, with demand fluctuating with livestock cycle economics.
- Industrial Users:Ethanol blenders operate under EPA-mandated volume obligations that guarantee baseline offtake, while bioplastics producers negotiate long-term dextrose supply agreements.
Beverage producers dominate contract volumes. Industrial users are gaining share fastest as biofuel and bioplastics capacity scales.
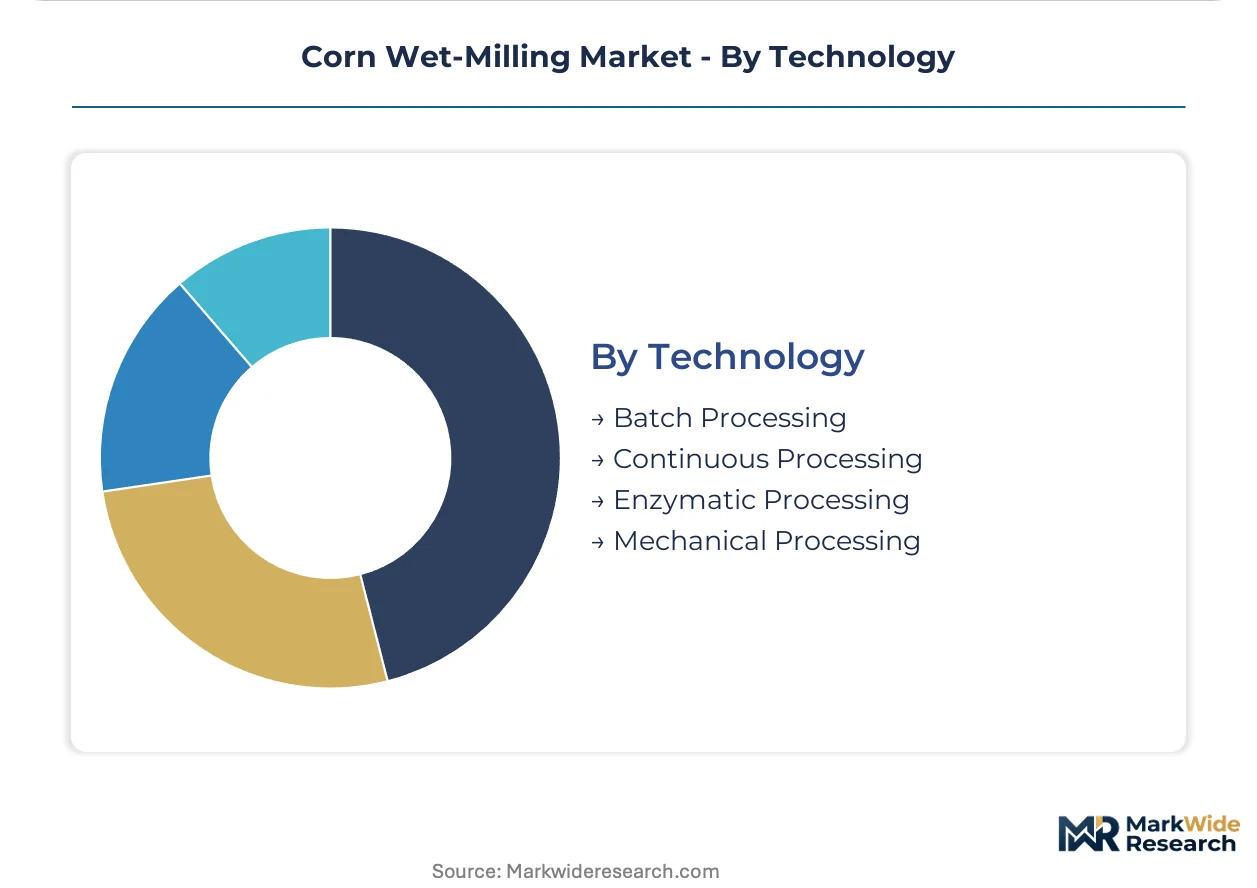
Technology:
Margin pools are concentrating in enzymatic systems as energy costs and extraction yields favor biocatalytic approaches over mechanical alternatives.
- Enzymatic Processing:Protein-engineered biocatalysts reduce thermal energy consumption while lifting starch yields toward the upper bound of kernel dry weight recovery. Talent scarcity in protein chemistry and fermentation science constrains adoption speed across Midwest processing clusters.
- Continuous Processing:Steady-state operation maximizes throughput for commodity sweetener and ethanol output, with front-end investment recouped through scale economies.
- Batch Processing:Smaller-scale units enable specialty grade production with frequent changeovers for organic or identity-preserved corn streams.
- Mechanical Processing:Legacy grinding and centrifugation assets face obsolescence as enzymatic alternatives compress energy margins, though some fiber and germ recovery stages retain mechanical elements.
Continuous processing holds the volume base. Enzymatic systems are expanding most quickly as processors retrofit for yield and energy efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Processing capacity clusters along the United States Corn Belt, where Iowa and Illinois facilities capture scale economies from farm-gate proximity. This geographic concentration creates vulnerability to localized weather disruptions and logistics bottlenecks.
United States
EPA Renewable Fuel Standard obligations lock in baseline ethanol demand from corn starch, while beverage manufacturers consolidate procurement through single-source agreements. FDA governs food-grade starch purity standards for human consumption. Iowa and Illinois processing clusters dominate capacity, with Nebraska and Indiana adopting membrane filtration miniaturization for distributed processing models.
China
Industrial fermentation feedstock demand from pharmaceutical and bioplastics manufacturers pulls refined dextrose volumes. NMPA and MIIT administer food contact material standards and industrial chemical registration. Shandong Province and the Yangtze River Delta concentrate wet-milling infrastructure near corn import terminals and downstream chemical plants.
Brazil
Animal nutrition exports to Southeast Asian poultry and aquaculture markets drive gluten meal and steep liquor volumes. ANVISA regulates food-grade starch specifications for domestic consumption. São Paulo state and Paraná host processing complexes integrated with port logistics for Atlantic shipping routes to European and Asian buyers.
Germany
REACH registration requirements and EFSA migration limits favor established wet-millers with compliance infrastructure for starch-based food contact materials. ECHA chemical registration demands documented purity chains for sulfurous acid residues. North Rhine-Westphalia and Lower Saxony anchor European processing capacity with technical application centers serving beverage texture formulation demand.
India
FSSAI food safety standards and BIS industrial specifications govern domestic starch quality tiers. Maharashtra and Gujarat concentrate processing capacity near port infrastructure for export-oriented corn oil and gluten meal shipments. Pharmaceutical-grade dextrose demand from domestic drug manufacturers creates premium fraction pull.
Corn Wet-Milling Market Vendor Landscape
Concentration sits with integrated agribusiness conglomerates controlling elevator-to-ingredient supply chains. Three structural tiers separate multinational processors with captive corn supply from regional specialists and commodity traders. Strategic moves center on enzymatic technology licensing and backward integration into farm-gate collection networks.
Within the integrated processor tier, Cargill, Archer Daniels Midland Company, and Ingredion exemplify scale-driven positioning through captive supply chain control. Cargill represents the Iowa-anchored elevator network archetype. Archer Daniels Midland Company occupies the commodity-to-specialty diversification position. Ingredion sits within the specialty starch formulation vector targeting beverage texture systems. Tate & Lyle anchors European demand coverage through London-based technical centers.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill |
| Tate & Lyle |
| Ingredion |
| Agrana Beteiligungs |
| Roquette Freres |
| Grain Processing Corporation |
| Global Bio-Chem Technology Group Company |
| Bunge Limited |
| Others |
Supply Flow & Price Mechanics
EPA Renewable Fuel Standard compliance gates both supply qualification and price differentiation simultaneously, as ethanol blenders demand documented dextrose purity chains while food manufacturers seek segregated organic and non-GMO handling certifications. This dual-gate structure concentrates pricing power with integrated processors who control elevator-to-ingredient supply chains across Iowa and Illinois.
Pricing Analysis
EPA Renewable Fuel Standard obligations dictate the pricing tier structure across the corn wet-milling sector, separating contract-based long-term offtake agreements for fuel-grade dextrose from spot-market transactions for specialty food starches. Price differentiation rests on certification level—EFSA-compliant food contact grades command premiums over standard sweetener fractions—and volume scale, with multinational beverage manufacturers extracting discounts through consolidated procurement. Cost compression in commodity sweetener channels is intensifying because beverage reformulators are substituting cane sugar and alternative sweeteners for high-fructose corn syrup. Animal nutrition companies exhibit the highest price sensitivity, indexing gluten meal purchases to soybean meal alternatives, while pharmaceutical-grade dextrose buyers show minimal sensitivity due to limited qualified suppliers.
Supply Chain Analysis
Inventory cycles run tight through harvest compression windows, with Iowa and Illinois processors holding minimal buffer stocks of identity-preserved corn ahead of seasonal intake surges. Geographic supply concentrates in the United States Corn Belt, with Brazil and China as secondary processing hubs serving export-oriented gluten meal and industrial fermentation feedstock channels respectively. Raw material dependencies center on natural gas for thermal drying, sulfur dioxide for steeping chemistry, and engineered enzymes for biocatalytic extraction stages. Single-source vulnerability pervades the enzyme supply chain, where specialized protein catalysts are sourced from limited biotech manufacturing networks. Distribution runs through captive elevator networks to integrated wet-mill complexes, with finished ingredients moving via rail and barge to downstream food, fuel, and materials manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Corn wet-milling is positioned for cyclical recovery as livestock cycle economics rebound and bioplastics capacity expansion pulls refined dextrose into non-food channels. The recovery trajectory hinges on normalized natural gas input costs and sustained EPA volume obligations.
For Market Incumbents: Secure backward integration into farm-gate collection networks to defend against membrane filtration miniaturization enabling distributed processing models in Nebraska and Indiana. Add segregated handling capacity for organic and identity-preserved corn streams to capture clean-label starch premiums. Talent scarcity in protein chemistry represents the critical capability gap; recruit fermentation scientists away from pharmaceutical and biotech sectors to accelerate enzymatic retrofit programs. For New Entrants and Emerging Players: EFSA compliance fast-track programs offer entry pathways into European bioplastics supply chains, where REACH registration requirements exclude commodity exporters. Target specialty beverage texture systems in premium carbonated and ready-to-drink coffee categories, where specific shear stability specifications reward formulation partnerships over commodity supply. Pursue joint development agreements with polylactic acid manufacturers seeking consistent dextrose purity above standard sweetener grades. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional processors in the U.S. Midwest lacking enzymatic refining capacity but holding valuable elevator infrastructure and EPA compliance registrations. Long-term viability favors processors with demonstrated carbon capture integration pathways and existing EFSA documentation systems. Watch enzyme engineering talent migration as the inflection signal—accelerated hiring by wet-millers indicates biocatalytic retrofit timelines compressing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farm-Gate Collection | Captive corn supply insulates margin structures from spot price volatility and logistics disruptions. |
| Enzymatic Refining Capacity Expansion | Biocatalytic extraction reduces natural gas consumption while lifting starch yields toward kernel dry weight limits. |
| EFSA Compliance Infrastructure Buildout | Documented purity chains for sulfurous acid residues unlock European bioplastics and food contact material premiums. |
| Carbon Capture Integration at Fermentation Sites | Monetization pathways under emerging emissions accounting frameworks create new revenue streams from ethanol production. |
| Specialty Starch Formulation Partnerships | Beverage texture system collaborations with carbonated and ready-to-drink coffee brands secure long-term offtake commitments. |
Methodological Framework
The analysis maps starch and sweetener output channels, bioplastics feedstock specifications, and enzymatic processing technology segments, each validated through plant managers at wet-milling facilities, procurement leads at downstream beverage and food manufacturers, and distribution channel partners handling corn oil and gluten meal exports. Primary interviews with fermentation scientists and protein chemists informed biocatalytic adoption timelines, while secondary validation drew from EPA Renewable Fuel Standard volume obligation filings, FDA food-grade starch purity standards, EFSA migration limit documentation, and SEC 10-K disclosures from integrated agribusiness conglomerates. Bottom-up capacity modeling across Iowa, Illinois, Nebraska, and Indiana facilities triangulated against top-down demand estimates from ethanol blenders and bioplastics manufacturers.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with modeled segmentation spanning product type, application, end user, and technology tiers plus regional production hub differentiation. CAGRs were derived from regression analysis of historical capacity utilization rates and forward-looking policy scenario modeling. Industry-specific forecast inputs included EPA biofuel mandate revision probabilities, European Union REACH registration requirement enforcement trajectories, and livestock cycle economics affecting gluten meal demand.
Decision-makers should treat outputs as directional under assumptions of sustained EPA Renewable Fuel Standard obligations and normalized natural gas pricing; material deviation in biofuel policy or energy input costs would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
Corn Thresher Market
Agricultural Processing Equipment
Feed Screw Barrel Market
Agricultural Processing Equipment
Solar Herbs Dryer Market
Agricultural Processing Equipment
Grain Handling Equipment Market
Agricultural Processing Equipment
Combine Harvesters Market
Agricultural Processing Equipment
Harvesting Machinery Market
Agricultural Processing Equipment
Harvesters Market
Agricultural Processing Equipment
Animal Feed Processing Equipment Market
Agricultural Processing Equipment
Shelling Machine Market
Agricultural Processing Equipment
Vegetable Dicing Machines Market
Agricultural Processing Equipment
Rice Polishing Machines Market
Agricultural Processing Equipment
Cashew Processing Machine Market
Agricultural Processing Equipment
Global Threshers Market
Agricultural Processing Equipment
Grain Processing Equipment Market
Agricultural Processing Equipment
Rice Milling Machinery Market
Agricultural Processing Equipment
Global Dry Milling Market