
 Canoe Paddles Market | 2026-2036
Canoe Paddles Market Size, Share, and Industry Trends Forecast 2026-2036
Canoe Paddles Market Insights
Recreational outfitters is collapsing as the dominant buyer archetype as competitive racing programs and expedition touring operators expand fleet purchases. Werner Paddles anchors its position through vertical integration into carbon fiber pre-preg manufacturing for shaft lamination. Bending Branches competes on geographic dominance across the upper Midwest paddle sports retail channel. Aqua-Bound specializes in adjustable-length systems targeting the crossover kayak-canoe rental market.
A canoe paddle is a handheld lever with a blade at one or both ends, typically constructed from laminated hardwood, aluminum alloy, fiberglass composite, or carbon fiber pre-preg, with shaft diameters ranging from 28 to 32 millimeters and blade surface areas between 120 and 180 square centimeters, designed to convert upper body torque into propulsive thrust for watercraft displacement. Carbon fiber material type commands premium positioning among competitive end users where stiffness-to-weight ratios determine stroke efficiency. Straight shaft paddle design retains volume leadership in rental fleets due to durability and maintenance simplicity, while bent shaft configurations capture margin pools in the touring segment through ergonomic load distribution. Adjustable paddle length categories are gaining fastest in the recreational channel as outfitters reduce SKU inventory across multi-user programs.
The US Forest Service administers wilderness area permits that cap group sizes and mandate non-motorized transport, directly shaping seasonal paddle demand in protected watersheds. EPA oversight of composite manufacturing emissions affects carbon fiber and fiberglass supply chain siting decisions for domestic producers. ISO 12217 small craft stability standards influence blade area and shaft geometry specifications for commercial tour operators. Stakeholders must monitor evolving wilderness access quotas and composite resin formulation rules to align production planning with constrained permit-growth environments.
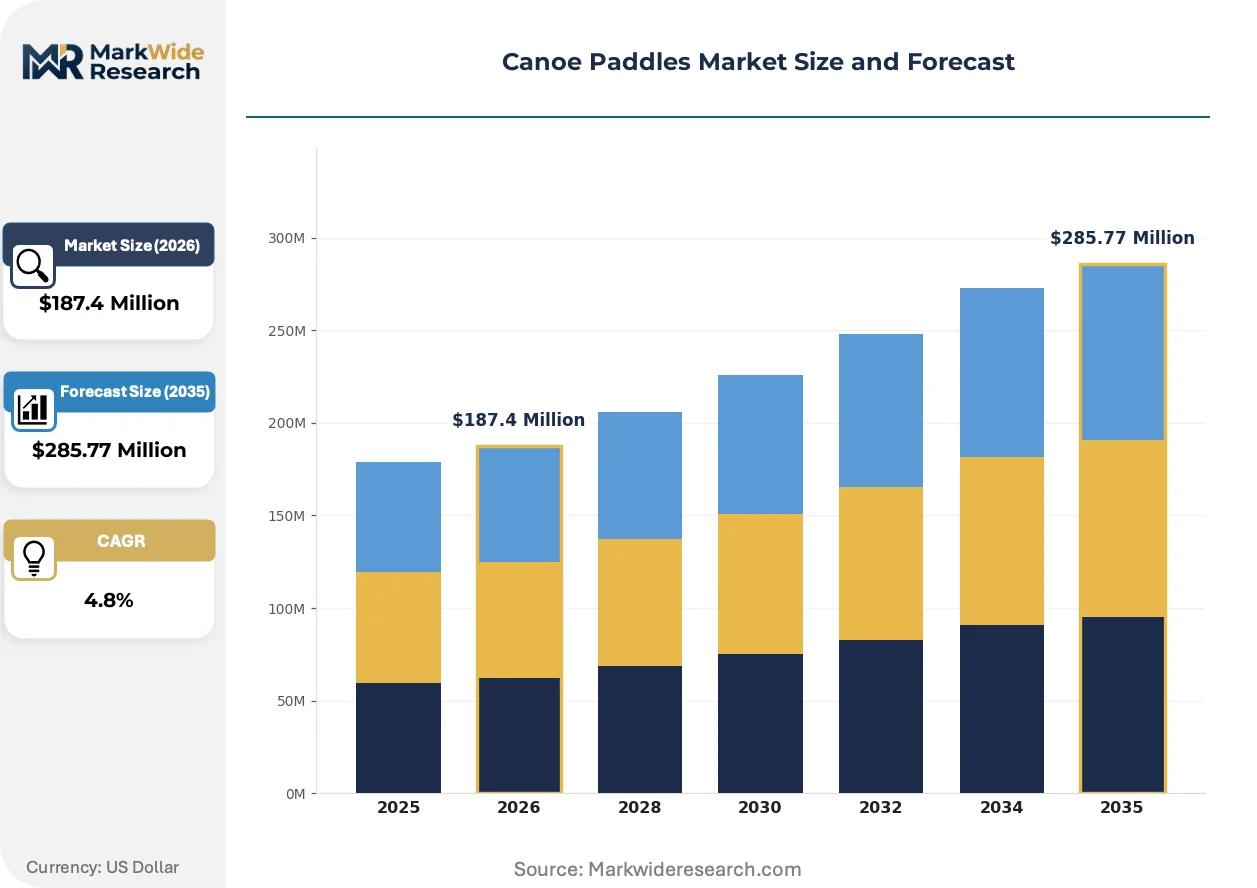
Market Dynamics
Carbon fiber pre-preg manufacturing is concentrating shaft production among vertically integrated suppliers, compressing margins for laminated hardwood processors and reshaping competitive positioning across performance segments.
Growth Catalysts
- US Forest Service permit caps:Wilderness area group size limits in Boundary Waters and other protected watersheds mandate non-motorized transport, directly expanding paddle procurement from commercial outfitters.
- Adjustable-length system adoption:Rental fleet operators are consolidating SKU inventories through telescoping shaft mechanisms that accommodate multi-user programs without dedicated sizing.
- Expedition touring operator expansion:Guided multi-day wilderness programs in Ontario's Algonquin corridor and Queensland's Noosa Everglades are driving fleet refresh cycles for durable carbon fiber inventory.
Market Restraints
- Carbon fiber supply concentration:Pre-preg resin formulation and layup capacity clusters among a limited set of North American and Asian suppliers, creating input bottlenecks for shaft manufacturers.
- EPA composite emissions oversight:Volatile organic compound regulations on fiberglass and carbon fiber curing operations constrain domestic production siting and expansion timelines.
- Aluminum alloy substitution in rental segments:Price-sensitive outfitters in high-theft or high-loss environments continue specifying metal shafts despite weight penalties.
Strategic Opportunities
- ISO 12217 stability standard alignment:Commercial tour operators seeking certification are specifying blade area and shaft geometry that meet small craft stability requirements, creating specification-driven demand pools.
- Crossover kayak-canoe rental channel:Paddle sports facilities serving dual craft types represent underpenetrated demand for adjustable systems that reduce inventory carrying costs.
- Queensland guided tourism infrastructure:Australia's ecotourism investment programs are expanding permit capacity in coastal everglades systems, building addressable demand for corrosion-resistant shaft materials.
Industry Challenges
- Composite technician skill scarcity:Carbon fiber layup and pre-preg handling require specialized training that outpaces vocational program output in manufacturing regions.
- Multi-material bonding complexity:Shaft-to-blade junctions combining carbon fiber, fiberglass, and thermoplastic inserts create quality control variability and warranty exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canoe Paddles Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Wood, Aluminum, Fiberglass, Carbon Fiber Paddle Length: Standard, Short, Long, Adjustable Paddle Design: Straight Shaft, Bent Shaft, Double-Bladed, Single-Bladed End User: Recreational, Professional, Touring, Competitive |
| Companies Covered | Bending Branches, Werner Paddles, Carlisle Paddles, Aqua-Bound, Grey Owl Paddles, Adventure Technology, ZRE, Sawyer Paddles and Oars, Mitchell Paddles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canoe Paddles Market Trends and Innovations
Material science advances and regulatory compliance requirements are fragmenting traditional supply relationships while creating new specification gateways for commercial buyers.
Carbon fiber pre-preg layup automation is fragmenting established procurement patterns between hand-laminated hardwood shops and precision manufacturing operations. Competitive racing programs and expedition operators are adopting automated shaft production for stiffness consistency. This technology is fragmenting the supplier base into high-volume precision manufacturers versus artisan craft producers serving heritage segments.
REACH chemical registration requirements in Europe are restricting certain epoxy resin formulations used in traditional fiberglass shaft construction. Manufacturers serving EU distribution channels are reformulating with compliant resin systems that alter cure times and material properties. Commercial tour operators in EU member states are now specifying REACH-compliant paddles to satisfy environmental audit requirements from tourism certification bodies.
Outcome-based fleet management contracts are displacing traditional capital purchase models among large recreational outfitters. Rental operators in Minnesota's lake country and Ontario's provincial park systems are contracting for paddle availability per season rather than owning depreciating inventory. This shift concentrates buying power among multi-location operators capable of negotiating service-level agreements with manufacturers.
Canoe Paddles Market Segmentation
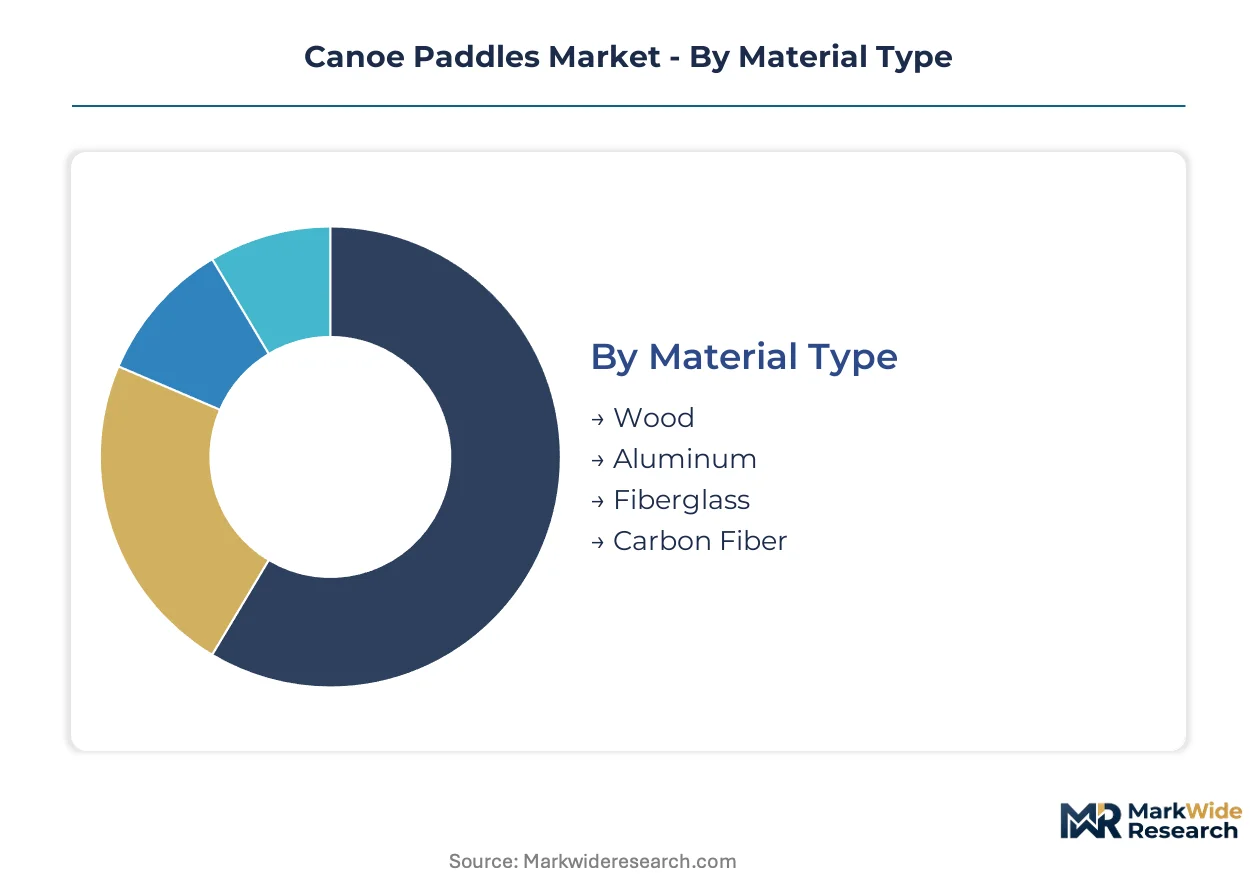
Material composition and shaft geometry determine pricing architecture and procurement channels across the canoe paddles market. Segmentation reveals how carbon fiber technology concentrates in performance tiers while aluminum and wood retain rental fleet dominance through durability economics.
Material Type:
Carbon fiber and fiberglass segments drive export demand from North American manufacturers to Australian and European guided tour operators, while wood and aluminum supply domestic rental markets through regional distributors.
- Carbon Fiber:Pre-preg layup construction delivers stiffness-to-weight ratios above 130 GPa/MPa, critical for competitive stroke efficiency. Expedition operators in Queensland's Noosa Everglades and Ontario's Algonquin corridor specify carbon fiber for multi-day fleet durability under load.
- Wood:Laminated hardwood shafts using maple, cherry, or ash laminates provide heritage aesthetics and impact absorption. Minnesota's Boundary Waters outfitters prioritize wood for repairability in remote watersheds where field maintenance determines trip completion rates.
- Aluminum:Extruded alloy shafts with thermoplastic grips dominate high-theft rental environments through cost replacement economics.
- Fiberglass:E-glass and S-glass composite layups occupy mid-tier positioning between wood heritage and carbon performance.
Wood holds the largest share; momentum sits with carbon fiber.
Paddle Length:
Length specification directly correlates with user anthropometrics and craft beam width, creating inventory complexity that rental operators address through standardization or adjustable systems.
- Adjustable:Telescoping shaft mechanisms spanning 220-260 centimeters accommodate multi-user programs without dedicated sizing. Outcome-based fleet contracts in Minnesota's lake country specify adjustable systems to reduce SKU carrying costs across seasonal demand fluctuations.
- Standard:Fixed 230-240 centimeter shafts match average adult torso proportions for general recreational use. Ontario provincial park rental facilities standardize on this length to simplify inventory management across mixed demographic user bases.
- Short:Sub-220 centimeter configurations suit smaller paddlers and narrow-beam solo canoes.
- Long:Extended 250+ centimeter shafts accommodate wide tandem craft and standing paddle techniques.
Standard length dominates current procurement; adjustable systems are climbing the fastest.
Paddle Design:
Shaft geometry determines ergonomic load distribution and manufacturing cost structure, with bent shaft configurations commanding margin premiums in touring segments.
- Straight Shaft:Linear shaft construction maximizes durability and maintenance simplicity for high-cycle rental applications. US Forest Service permit caps in Boundary Waters drive straight shaft procurement from commercial outfitters prioritizing field repairability over ergonomic optimization.
- Bent Shaft:11-14 degree elbow angles reduce wrist strain during extended touring strokes. Professional expedition guides in Queensland's guided tourism infrastructure specify bent shaft designs for client comfort across multi-day everglades programs.
- Double-Bladed:Kayak-style symmetrical blades adapted for canoe use in crossover rental markets.
- Single-Bladed:Traditional asymmetric blade configuration for J-stroke and Canadian stroke techniques.
Straight shaft retains volume leadership; bent shaft captures expanding margin pools.
End User:
Customer archetype determines specification intensity, with competitive and professional segments driving carbon fiber adoption while recreational demand concentrates in durable, cost-optimized configurations.
- Competitive:Racing programs specify FISA-compliant blade areas and shaft diameters optimized for stroke rate efficiency. ISO 12217 stability standard alignment creates specification-driven demand pools among sprint and marathon racing circuits.
- Touring:Multi-day wilderness operators prioritize weight reduction and durability tradeoffs. EPA composite emissions oversight constrains domestic carbon fiber supply for this segment, creating sourcing advantages for vertically integrated manufacturers with captive pre-preg capacity.
- Recreational:Casual users and day-trippers drive volume through aluminum and wood rental specifications.
- Professional:Guides and instructors require equipment meeting commercial liability and certification standards.
Recreational users represent the largest addressable base; competitive segments show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian manufacturers export carbon fiber shafts to Australian guided tour operators across the Queensland coastal corridor, establishing a trans-Pacific trade flow that bypasses traditional North American distribution channels.
United States
Minnesota's Boundary Waters Canoe Area Wilderness drives seasonal procurement spikes as US Forest Service permit caps mandate non-motorized transport for commercial outfitters. EPA oversight of composite manufacturing emissions constrains domestic carbon fiber curing operations, pushing some shaft production offshore. The upper Midwest paddle sports retail channel concentrates distribution through Minneapolis-St. Paul and Duluth logistics hubs serving lake country recreation demand.
Canada
Ontario's Algonquin Provincial Park corridor sustains fleet refresh cycles from multi-day wilderness tour operators prioritizing durability under load. The country's national environmental regulator monitors volatile organic compound releases from fiberglass resin formulation facilities in the Great Lakes manufacturing belt. Toronto and Ottawa serve as procurement centers linking domestic paddle fabricators with Quebec's laminated hardwood processing clusters.
Australia
Queensland's Noosa Everglades guided tour market imports corrosion-resistant carbon fiber inventory for saltwater everglades programs. The Therapeutic Goods Administration's sister environmental body oversees chemical registration for epoxy resin systems used in shaft construction. Brisbane anchors distribution for coastal ecotourism infrastructure investments expanding permit capacity across the state's northern wetlands.
Germany
REACH chemical registration requirements restrict traditional epoxy formulations, forcing reformulation of compliant resin systems for EU distribution channels. ECHA oversight alters cure times and material properties for manufacturers serving European commercial tour operators. Bavaria's precision manufacturing regions host pre-preg layup automation specialists supplying stiffness-consistent shafts to competitive racing circuits.
Japan
METI industrial standards influence blade area specifications for sprint and marathon racing programs adopting FISA-compliant geometries. JIS certification requirements create specification gateways for carbon fiber shaft imports from North American vertically integrated suppliers. The Kansai region around Osaka concentrates recreational paddle retail serving Lake Biwa and inland waterway tourism.
Canoe Paddles Market Competitive Landscape
Listed leaders compete with private specialists across material technology and geographic channel control, producing a tiered structure where scale-driven precision manufacturers face artisan craft producers in heritage segments. The vendor base splits between high-volume automated shaft production and hand-laminated hardwood shops serving repairability-focused wilderness operators. Three archetypes dominate: vertically integrated carbon fiber pre-preg specialists, regional hardwood fabricators with distribution depth, and adjustable-system innovators targeting rental fleet consolidation. Competitive moves concentrate on backward integration into resin formulation capacity and outcome-based fleet management contracting that displaces capital purchase models.
Among North American specialists, Werner Paddles exemplifies the vertically integrated archetype through captive carbon fiber pre-preg manufacturing, while Bending Branches anchors geographic dominance across upper Midwest retail channels. Aqua-Bound occupies a position within the adjustable-system tier, representing the crossover kayak-canoe rental market specialization. These three companies illustrate how competitive positioning fragments across material technology, channel control, and product architecture dimensions.
| Leading Market Players |
|---|
| Bending Branches |
| Werner Paddles |
| Carlisle Paddles |
| Aqua-Bound |
| Grey Owl Paddles |
| Adventure Technology |
| ZRE |
| Sawyer Paddles and Oars |
| Mitchell Paddles |
| Others |
Pricing and Supply Chain Analysis
Outcome-based fleet management contracts lock in multi-season paddle availability for Minnesota lake country outfitters while anchoring price visibility against carbon fiber pre-preg volatility. These arrangements concentrate buying power among operators capable of negotiating service-level agreements that bundle maintenance, rotation, and end-of-life replacement.
Pricing Analysis
Current-generation carbon fiber pre-preg paddles command substantial premiums over prior-generation fiberglass layups and legacy laminated hardwood, with next-generation automated layup systems threatening further stratification. Three-tier pricing structure across premium, standard, and economy levels separates competitive racing specifications from commercial tour operator durability tiers and rental fleet replacement economics. Price differentiation hinges on ISO 12217 stability certification and shaft stiffness-to-weight ratios. Cost compression in the aluminum alloy rental tier is intensifying because outfitters prioritize theft replacement economics over performance metrics. Recreational day-trippers exhibit highest price sensitivity; expedition operators show lowest.
Supply Chain Analysis
Inbound logistics costs from Asian pre-preg resin suppliers through West Coast ports create vulnerability for North American shaft manufacturers dependent on just-in-time curing schedules. Carbon fiber pre-preg production concentrates in the United States, Japan, and China, with shaft lamination capacity clustering in Minnesota and Ontario manufacturing belts. Domestic producers draw from epoxy resin systems, E-glass and S-glass fiber stock, and laminated hardwood billets from Quebec processing clusters. Single-source vulnerability sits with limited North American pre-preg formulation facilities subject to EPA volatile organic compound oversight. Distribution runs through Minneapolis-St. Paul and Toronto logistics hubs serving upper Midwest and provincial park retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where US Forest Service permit caps create regulatory entrenchment that locks commercial outfitters into established supply relationships. Switching costs compound through fleet standardization and guide training investments.
For Market Incumbents: Consolidate backward integration into captive carbon fiber pre-preg manufacturing to secure input access against EPA emissions constraints on curing operations. Deepen channel control through exclusive outcome-based fleet contracts with multi-location operators in Minnesota's Boundary Waters and Ontario's Algonquin corridor. Aluminum alloy substitution in high-theft rental environments represents a margin pressure point requiring tiered product architecture response. For New Entrants and Emerging Players: Differentiate on adjustable-length system architecture targeting the underpenetrated crossover kayak-canoe rental channel where SKU consolidation demand runs ahead of incumbent supply. Queensland's Noosa Everglades guided tourism infrastructure offers the most penetrable geography given corrosion-resistant shaft requirements and expanding permit capacity. A direct-to-outfitter go-to-market angle bypasses established retail channel gatekeepers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated manufacturers with captive resin formulation capacity over pure-play shaft fabricators. Long-term viability over the projection horizon rests on regulatory compliance infrastructure and multi-year fleet service contract portfolios. The acquisition target archetype combines automated pre-preg layup technology with established relationships among US Forest Service permit holders. Watch for EPA composite emissions rulemaking as the inflection indicator that would recalibrate domestic production economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pre-preg Manufacturing | Captive resin formulation capacity insulates against EPA volatile organic compound constraints on curing operations. |
| Outcome-Based Fleet Management Contracts | Service-level agreements with Minnesota lake country operators displace capital purchase models and concentrate buying power. |
| Adjustable-Length System R&D Investment | Telescoping shaft mechanisms reduce SKU carrying costs for rental fleet operators across seasonal demand fluctuations. |
| ISO 12217 Stability Certification Alignment | Commercial tour operators in EU member states specify compliant paddles to satisfy environmental audit requirements. |
| Queensland Distribution Partnership | Brisbane logistics hub access captures ecotourism infrastructure investment expanding permit capacity in coastal everglades systems. |
Research Methodology
Initial hypotheses were tested against primary input from carbon fiber composite engineers, wilderness area permit administrators, commercial outfitter procurement managers, and paddle sports retail channel buyers and refined through secondary validation. Primary fieldwork combined structured interviews with Minnesota and Ontario fleet operators, technical discussions with pre-preg manufacturing specialists, and regulatory consultations on EPA emissions oversight. Secondary sources included US Forest Service permit allocation data, ECHA REACH chemical registration databases, ISO 12217 small craft stability documentation, and customs trade records for carbon fiber shaft imports. Bottom-up triangulation across end-user demand segments was cross-checked against top-down supply-side capacity assessments.
Variance decomposition across material type, shaft geometry, paddle length, and end-user archetype segments shaped the analytical framework over the projection horizon. Modeled dimensions included carbon fiber versus wood versus aluminum material composition, straight versus bent shaft design, fixed versus adjustable length configurations, and competitive racing versus touring versus recreational user categories. CAGRs were derived from segment-level volume build-ups and price trajectory assumptions. Industry-specific forecast inputs incorporated Boundary Waters permit cap trajectories and Queensland ecotourism infrastructure investment pipelines.
Material uncertainties — US Forest Service permit allocation adjustments, EPA composite emissions rulemaking, and carbon fiber pre-preg supply concentration disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory stability and input supply continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
Bicycle Bags and Bag Packs Market
Outdoor Gear
Wheeled Insulated Cooler Market
Outdoor Gear
Spain Camping Equipment Market
Outdoor Gear
Europe Camping Equipment Market
Outdoor Gear
Camp Fire Tripod Market
Outdoor Gear
Rain Boots Market
Outdoor Gear
South Korea Camping Equipment Market
Outdoor Gear
UK Camping Equipment Market
Outdoor Gear
North America and Europe Leaf Blower Market
Outdoor Gear
Sleeping Bag Market
Outdoor Gear
China Camping Equipment Market
Outdoor Gear
Shared Umbrella Market
Outdoor Gear
Diving Equipment Market
Outdoor Gear
Fairway Mowers Market
Outdoor Gear
Camping Equipment Market
Outdoor Gear
North America Robotic Lawn Mower Market