
 Hunting Blinds Market | 2026-2036
Hunting Blinds Market Size, Share, and Industry Trends Forecast 2026-2036
Hunting Blinds Market Outlook
Premium weatherproofing certification is bifurcating the Hunting Blinds Market into performance-tier and value-tier supply lanes. Ameristep leverages proprietary fabric lamination to dominate mass retail channels. Redneck Blinds anchors its position through in-house rotational molding of polymer panels. Shadow Hunter Blinds specializes in scent-control integration for professional guide clientele.
Hunting blinds are enclosed or elevated concealment structures engineered with hydrostatic head ratings, UV-stabilized fabrics, and silent-entry zipper systems to eliminate visual and olfactory detection by game animals during wildlife observation or harvest activities. Ground blinds lead volume shipments due to lower price points and universal terrain compatibility, while tree stands command margin concentration among trophy hunters seeking elevated sight lines. Fabric materials capture the largest addressable base through lightweight packability, though metal-framed panel blinds sustain replacement demand among commercial outfitters operating fixed lease properties.
US hunters navigate FDA-adjacent scent-control chemical regulations and state wildlife agency blind placement restrictions on public lands. The EPA oversees treated fabric biocide claims under FIFRA guidelines affecting antimicrobial coating marketing. Stakeholders must monitor evolving state-level baiting and blind proximity rules that directly dictate product sizing and mobility requirements.
Market Dynamics
Fabric lamination chemistry and rotational molding capabilities are concentrating supply-side power among manufacturers controlling proprietary weatherproofing processes, while recreational hunters drive demand fragmentation through specialized scent-control and elevated-platform preferences.
Growth Catalysts
- Polymer coating breakthroughs:Hydrostatic head ratings exceeding 10,000mm are extending blind lifespans in extreme precipitation zones, triggering replacement cycles among commercial outfitters operating fixed lease properties.
- US public land access expansion:State wildlife agency programs increasing hunter opportunity days are expanding addressable user bases for portable ground blind configurations.
- Scent-control chemistry:EPA FIFRA-compliant antimicrobial fabric treatments are opening premium pricing tiers previously restricted by untreated material limitations.
Market Restraints
- Aluminum tariff volatility:Frame and panel blind manufacturers face input cost instability from trade policy fluctuations affecting extruded structural components.
- Polymer supply concentration:Rotational molding resin availability clusters among Gulf Coast petrochemical producers, creating geographic vulnerability for panel blind fabricators.
- Silent-entry engineering limits:Current zipper and magnetic closure systems impose acoustic detection thresholds that restrict adoption among professional guides serving pressure-hunted trophy properties.
Strategic Opportunities
- Canada backcountry penetration:Underdeveloped distribution infrastructure in Alberta and Saskatchewan outfitter corridors presents first-mover expansion potential for lightweight fabric configurations.
- Mobile-optimized channel convergence:Direct-to-consumer platforms integrating 3D terrain visualization are compressing traditional retail markup structures for recreational purchaser segments.
- US Inflation Reduction Act conservation funding:Federal habitat improvement allocations are expanding huntable acreage and associated blind placement permit volumes.
Industry Challenges
- Specialized sewing automation:Scent-control seam sealing and complex fabric lamination require skilled technician pipelines that remain underdeveloped in domestic manufacturing bases.
- State-by-state compliance fragmentation:Blind proximity restrictions, baiting prohibitions, and public land placement windows create SKU proliferation burdens for national distribution strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hunting Blinds Market |
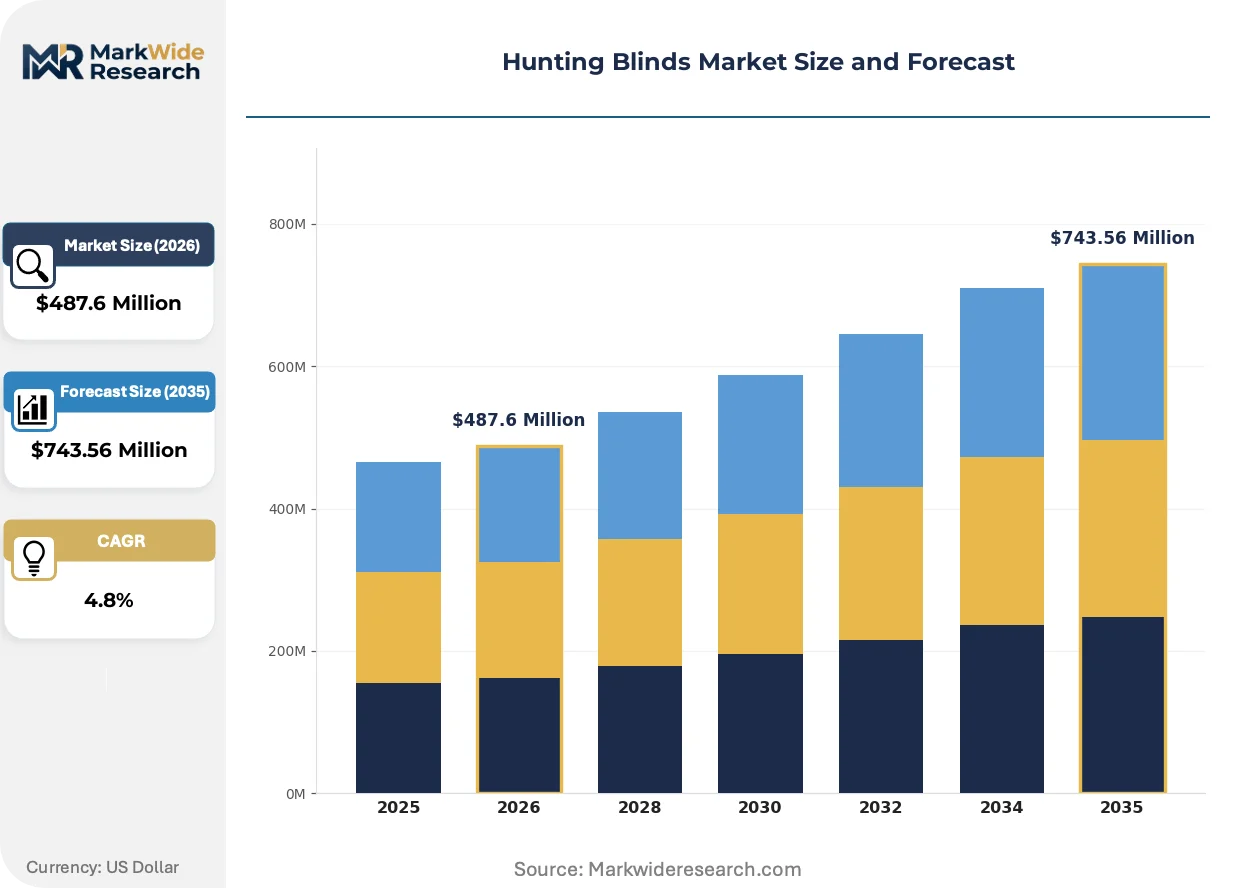
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $743.56 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground Blinds, Tree Stands, Portable Blinds, Panel Blinds Material: Fabric, Metal, Plastic, Camouflage Size: Small, Medium, Large, Extra Large End User: Recreational Hunters, Professional Guides, Wildlife Observers, Commercial Outfitters |
| Companies Covered | Slayer Blinds, Ameristep, Game Winner, Titan Hunting Blinds, Shadow Hunter Blinds, Redneck Blinds, Nukem Hunting, TideWe, Primos, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hunting Blinds Market Strategic Shifts
Active camouflage pattern development and connected hunting ecosystems are redefining how concealment performance is measured and monetized across recreational and commercial user segments.
Adaptive textile technology incorporating micro-climate ventilation and infrared signature suppression is fragmenting traditional static-blind categories into condition-responsive product tiers. Western big-game hunters are adopting these systems fastest, paying structural premiums for thermal regulation capabilities that extend effective hunt durations. This capability expansion is fragmenting the mid-market by forcing legacy manufacturers into accelerated R&D cycles or private-label partnerships.
EPA FIFRA enforcement tightening on biocide marketing claims is compressing antimicrobial coating label strategies across treated fabric suppliers. Manufacturers must now substantiate scent-neutralization efficacy through standardized testing protocols before interstate commerce. The professional guide segment bears primary compliance burden, as their clientele demands verifiable performance documentation for high-fee trophy operations.
Subscription-based blind access models are emerging among lease aggregators, replacing outright ownership for occasional hunters in Texas and Kansas corn-belt corridors. These platforms coordinate seasonal rotation logistics across multiple properties, unbundling storage and transport burdens from recreational users. The shift concentrates capital deployment among platform operators while compressing replacement demand for individual ownership configurations.
Hunting Blinds Market Segmentation
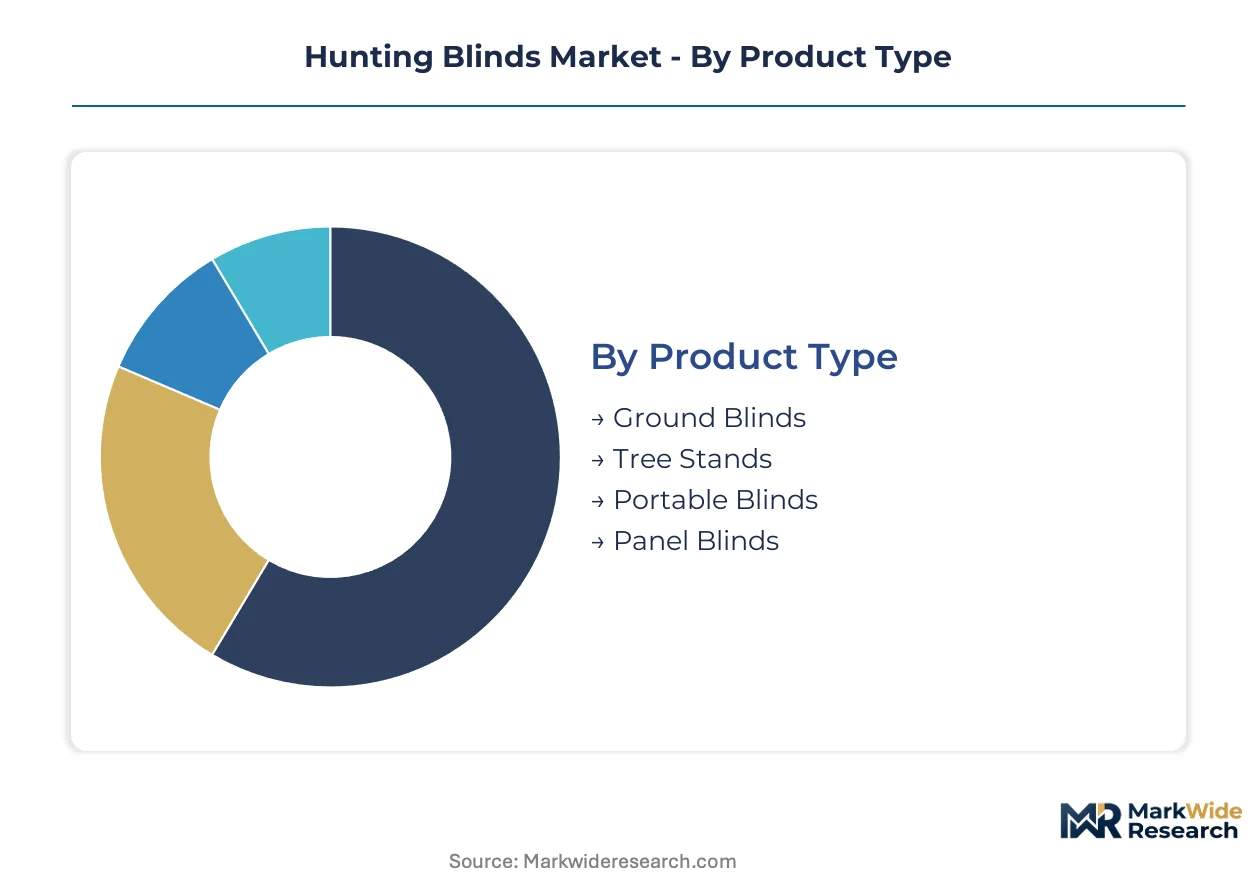
Hunting blind segmentation reveals how product specifications map to distinct regulatory environments and usage protocols. Material certifications and mobility requirements fragment supply chains across recreational and commercial channels.
Product Type:
Ground blinds face fewer placement restrictions on US public lands than elevated configurations, while tree stands trigger OSHA-adjacent fall-protection scrutiny in commercial lease operations.
- Ground Blinds:Enclosed fabric or panel structures with hydrostatic head ratings and silent-entry systems dominate volume shipments. Recreational hunters in Texas and Kansas corn-belt corridors drive replacement cycles through weather-related wear.
- Tree Stands:Elevated platforms with harness-compatible anchoring systems command margin concentration among trophy hunters seeking sight-line advantages. Professional guides operating pressure-hunted properties absorb premium pricing for acoustic-dampened entry mechanisms.
- Portable Blinds:Lightweight packable configurations under 15 pounds serve backcountry hunters in Alberta and Saskatchewan.
- Panel Blinds:Rigid polymer or metal-framed structures sustain multi-season deployment on fixed lease properties.
Ground blinds handle the majority of throughput; portable blinds are expanding most quickly on share.
Material:
Cost tiers separate premium weatherproofing certifications from value-oriented untreated fabrics, with rotational molding and lamination chemistry driving manufacturing concentration.
- Fabric:UV-stabilized textiles with polymer coatings and seam-sealed construction capture the largest addressable base through packability. Western big-game hunters in Montana and Colorado pay structural premiums for micro-climate ventilation integration.
- Metal:Extruded aluminum frames for panel blinds face tariff volatility affecting input cost stability. Commercial outfitters in fixed-lease Wisconsin and Michigan properties favor durability over transportability.
- Plastic:Rotational-molded polymer panels from Gulf Coast resin supply clusters serve permanent installations.
- Camouflage:Patterned surface treatments with infrared signature suppression command specialized pricing tiers.
Fabric commands the volume base; plastic configurations show the steepest expansion trajectory among commercial operators.
Size:
Application requirements dictate dimensional standards, with state wildlife agency proximity rules directly constraining footprint maximums on public lands.
- Small:Single-occupant configurations under 40 square feet satisfy solo hunters and dense-terrain constraints.
- Medium:Two-person capacity with gear storage dominates recreational purchase patterns.
- Large:Three-to-four person footprints serve guide-client operations and family hunting units.
- Extra Large:Specialized filming and observation platforms exceed standard mobility parameters.
Medium sizes carry the volume concentration; large configurations gain share fastest among outfitter procurement.
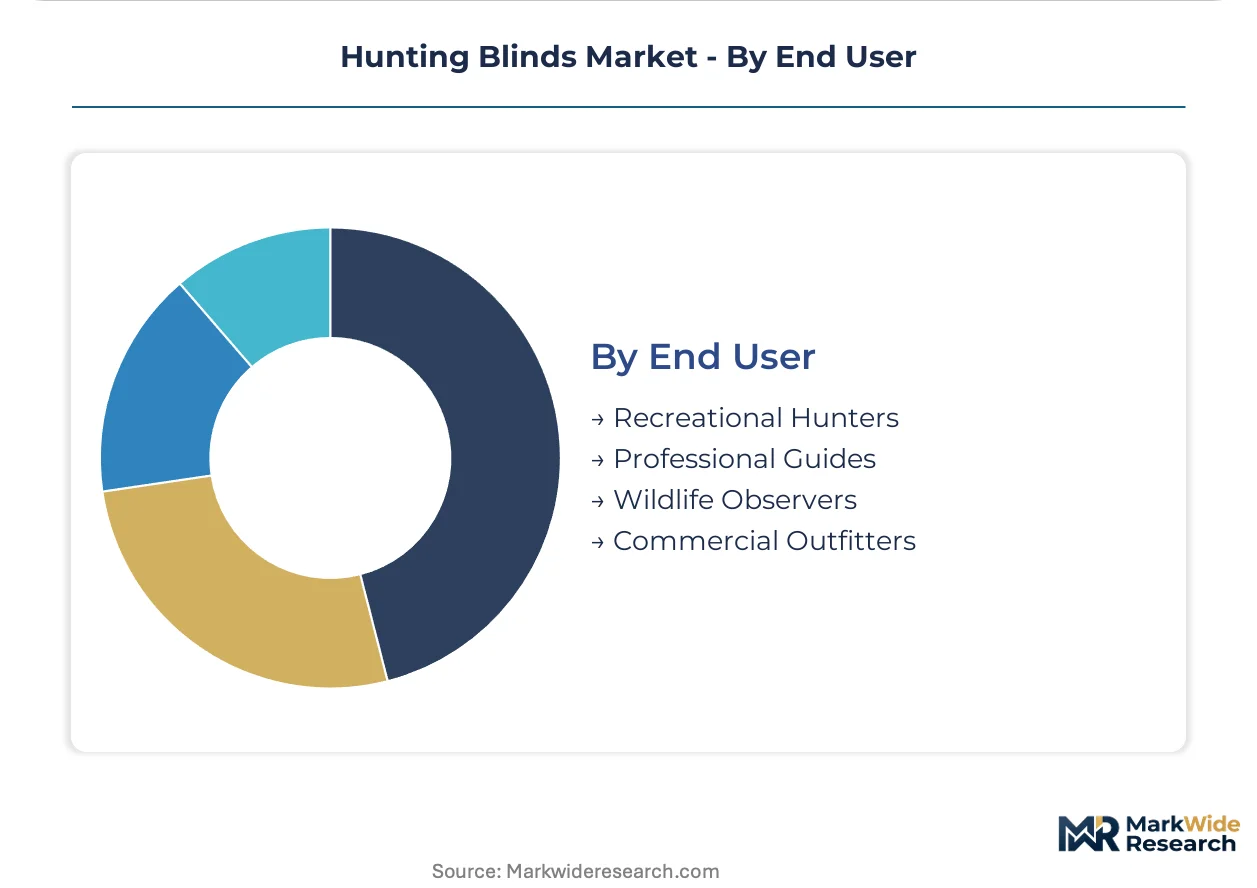
End User:
Customer type determines compliance burden intensity, with professional segments absorbing documentation requirements for EPA FIFRA-verified scent-control claims.
- Recreational Hunters:Individual purchasers driving seasonal replacement cycles through mass retail and direct-to-consumer channels. Subscription-based access models in Texas and Kansas are unbundling ownership from occasional use.
- Professional Guides:High-fee trophy operations demand verifiable antimicrobial efficacy documentation. EPA enforcement tightening compresses label strategies for this segment specifically.
- Wildlife Observers:Photography and research applications prioritize visual concealment over harvest functionality.
- Commercial Outfitters:Fixed-lease property operators sustain metal-framed panel blind demand through multi-year depreciation schedules.
Recreational hunters anchor the demand base; professional guides are climbing the fastest on premium tier penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows favor North American producers shipping rotational-molded polymer panels to Canadian outfitter markets, while fabric-based configurations from Asian manufacturing clusters face tariff headwinds entering US retail channels.
United States
Whitetail deer hunting culture in Texas and Kansas sustains consistent replacement cycles for ground blinds. EPA FIFRA guidelines govern antimicrobial coating marketing claims on treated fabrics. Wisconsin and Michigan commercial outfitters concentrate demand for metal-framed panel blinds on fixed lease properties.
Canada
Backcountry hunters in Alberta and Saskatchewan drive portable blind adoption under 15 pounds. Health Canada and PMRA regulate scent-control chemical treatments on imported fabrics. Distribution infrastructure gaps in prairie outfitter corridors create first-mover expansion opportunities for lightweight configurations.
Germany
Wild boar hunting associations in Bavaria and Lower Saxony sustain niche demand for elevated platforms. REACH compliance requirements restrict certain polymer coating chemistries in textile imports. Stuttgart-area fabricators specialize in precision-engineered frame components for European hunting blind assemblers.
Australia
Feral game management programs in New South Wales and Victoria expand addressable user bases for observation blinds. The Therapeutic Goods Administration (TGA) and state environmental agencies regulate chemical treatments on hunting equipment fabrics. Melbourne-based distributors channel Asian-manufactured fabric blinds into domestic retail networks.
United Kingdom
Deer stalking estates in Scotland and rural England absorb premium pricing for scent-control integrated systems. HSE guidelines and wildlife licensing frameworks constrain blind placement on public access lands. Birmingham metalworking clusters supply extruded aluminum frame components to domestic blind fabricators.
Hunting Blinds Market Competitive Environment
Concentration sits with rotational molding specialists and fabric lamination chemists controlling proprietary weatherproofing processes. Mid-tier assemblers fragment across regional distribution networks without captive supply of core materials. Two strategic archetypes dominate: polymer panel fabricators with Gulf Coast resin access, and textile specialists with EPA-compliant antimicrobial coating pipelines. Capacity expansion and direct-to-consumer platform development represent the dominant competitive vectors reshaping channel economics.
Within the polymer fabrication tier, Redneck Blinds exemplifies rotational molding capabilities, while Ameristep occupies a position bridging mass retail channel access with proprietary fabric lamination. Shadow Hunter Blinds anchors the professional guide segment through scent-control integration specialization. These three represent distinct archetype positions rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Slayer Blinds |
| Ameristep |
| Game Winner |
| Titan Hunting Blinds |
| Shadow Hunter Blinds |
| Redneck Blinds |
| Nukem Hunting |
| TideWe |
| Primos |
| Others |
Value Chain & Pricing Dynamics
Rotational molding capacity utilization above 85 percent at Gulf Coast resin clusters concentrates pricing power among polymer panel fabricators, while fabric lamination specialists in domestic textile corridors defend margin floors through proprietary weatherproofing chemistry that recreational hunters cannot replicate in-house.
Pricing Analysis
Recreational hunters anchor a three-tier pricing structure across premium, standard, and economy levels, with EPA FIFRA-compliant antimicrobial certification and hydrostatic head ratings above 10,000mm driving tier separation. Price differentiation rests on certification grade and after-sales service bundling for commercial outfitters. Cost compression in economy fabric tiers is intensifying because Asian manufacturing clusters face tariff headwinds entering US retail channels. Occasional hunters in subscription-based access models show highest price sensitivity; professional guides absorbing premium tiers for trophy operations show lowest.
Supply Chain Analysis
Container availability constraints on transpacific trade lanes from Vietnam and Bangladesh inflate landed costs for fabric-based configurations, while domestic rotational molding draws from Gulf Coast petrochemical producers. Raw material dependencies include UV-stabilized polyester textiles, extruded aluminum structural components, and rotational molding resins. Single-source vulnerability clusters among polymer resin suppliers concentrated in hurricane-exposed geographies. Distribution runs through mass retail channel partners, direct-to-consumer platforms with 3D terrain visualization, and lease aggregator subscription services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from seasonal rotation logistics and storage unbundling expands faster than hardware ownership, as Texas and Kansas lease aggregators capture capital deployment from occasional hunters seeking blind access without transport burdens.
For Market Incumbents: Compound defensive positioning through captive supply of rotational molding resins and proprietary fabric lamination chemistry that emerging assemblers cannot replicate without skilled technician pipelines. Add capacity in Alberta and Saskatchewan corridors to preempt first-mover expansion by lightweight portable specialists. EPA FIFRA enforcement tightening on antimicrobial claims presents certification investment leverage against mid-tier competitors lacking standardized testing protocols. For New Entrants and Emerging Players: EPA FIFRA fast-track certification for scent-control fabric treatments opens premium tier penetration among professional guide clientele demanding verifiable efficacy documentation. White-space targets include underdeveloped Canadian prairie outfitter corridors and mobile-optimized direct-to-consumer platforms compressing traditional retail markups. Go-to-market through 3D terrain visualization tools that recreational hunters use for blind placement planning. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors rotational molding specialists with Gulf Coast resin access and fabric lamination chemists controlling proprietary weatherproofing processes over pure-play assemblers lacking captive materials. Long-term viability hinges on consolidation of supply-side concentration among manufacturers with skilled sewing automation for scent-control seam sealing. Watch subscription-based access model penetration rates in Texas and Kansas corn-belt corridors as inflection indicator for hardware ownership displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Rotational Molding Capacity Expansion | Gulf Coast resin access secures supply continuity for polymer panel fabricators serving fixed-lease commercial outfitters. |
| EPA FIFRA Certification Investment | Antimicrobial coating validation opens premium pricing tiers previously restricted by untreated material limitations. |
| Direct-to-Consumer Platform Launch | 3D terrain visualization tools compress traditional retail markups for recreational hunter segments. |
| Canadian Distribution Infrastructure Buildout | Alberta and Saskatchewan corridor penetration captures first-mover advantage in backcountry portable blind demand. |
| Subscription-Based Access Model Development | Seasonal rotation logistics unbundle storage and transport burdens from occasional hunters in Texas and Kansas. |
Study Parameters
Desk research of customs and trade data, state wildlife agency permit databases, and EPA FIFRA registration records preceded structured interviews with rotational molding plant managers, commercial outfitter procurement leads, retail channel category buyers, and professional hunting guides. Primary fieldwork with fabric lamination specialists and polymer resin distributors combined with secondary validation through SEC filings of publicly traded outdoor equipment manufacturers and hunting lease aggregator platform disclosures. Bottom-up shipment estimates triangulated against top-down addressable hunter population analysis.
Variance decomposition across product type, material certification tier, end-user segment, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from replacement cycle modeling for ground blinds versus tree stands, with inputs including state-level public land access expansion programs and polymer coating durability test data. Forecast segmentation incorporated mobility requirements, scent-control integration levels, and commercial versus recreational usage patterns.
Underlying assumptions cover EPA FIFRA enforcement continuity, Gulf Coast resin supply stability, and state wildlife agency blind placement rule persistence, with deviation risk concentrated in aluminum tariff volatility and subscription model adoption rates among occasional hunters. Recalibration cycles align with material shifts in antimicrobial coating chemistry approvals and public land access program funding allocations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor & Sports
LED Fishing Light Market
Outdoor & Sports
Walkbehind Lawnmower Market
Outdoor & Sports
Riding Multi-Purpose Lawn Mower Market
Outdoor & Sports
Fishing Reels Market
Outdoor & Sports
Mexico Fishing Reels Market
Outdoor & Sports
Camping Utensils Market
Outdoor & Sports
Freshwater Fishing Rod Market
Outdoor & Sports
Camping Beds and Mats Market
Outdoor & Sports
Global Paintball Equipment Market
Outdoor & Sports
Global Slingshot Market
Outdoor & Sports
Swimming Pool Liner Market
Outdoor & Sports
Swimming Pool Equipment Market
Outdoor & Sports
Global Sailing Dinghy Masts Market
Outdoor & Sports
Garden Solar Lights Market
Outdoor & Sports
Autonomous Golf Caddy Market
Outdoor & Sports
Golf Trolley Market