
 Germany Camping Equipment Market | 2026-2036
Germany Camping Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Camping Equipment Market Insights
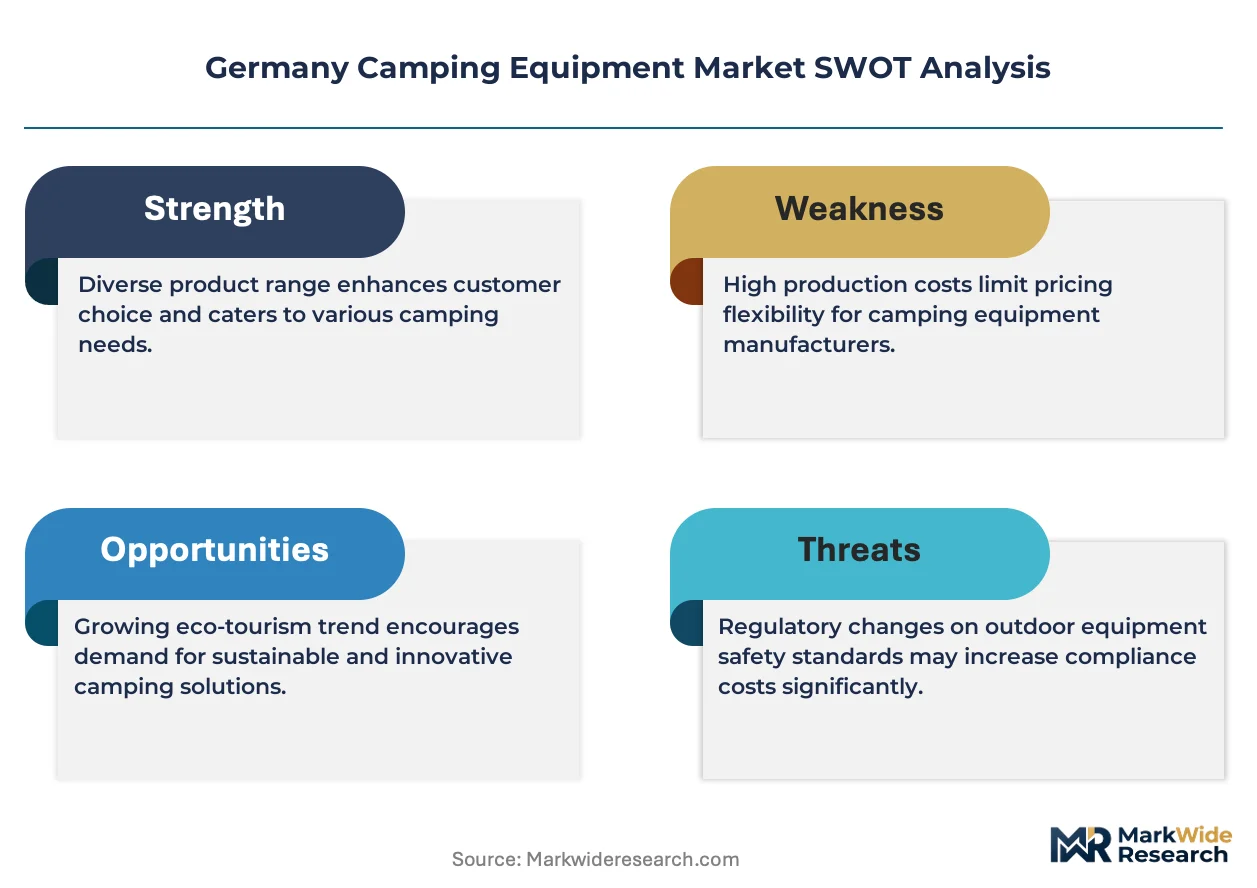
The price-performance boundary between premium and commodity camping equipment is hardening in Germany. Dometic Group AB leverages its thermal engineering heritage to dominate caravan and portable cooling systems. Hilleberg the Tentmaker anchors the expedition-grade segment with four-season tunnel tents engineered for Scandinavian conditions. Decathlon competes aggressively on value, sustaining market presence through vertical retail control and in-house design of mid-range trekking shelters.
Camping equipment encompasses portable shelters, sleep systems, cooking apparatus, and site furniture manufactured from technical textiles, aluminum alloys, and composite polymers for temporary outdoor habitation. Tents utilizing silicone-coated nylon ripstop with hydrostatic head ratings above 3,000 mm serve as primary weatherproof shelters for recreational and expedition use. The product type segment shows sleeping bags with down and synthetic insulation capturing margin pools at premium tiers, while outdoor furniture grows fastest as car camping expands. End user dynamics reveal adventure seekers driving technical product demand, whereas families sustain volume through seasonal recreational purchases.
KBA vehicle regulations influence trailer and caravan equipment standards, while REACH compliance governs chemical treatments in tent fabrics and sleeping bag fills. The EU Green Deal's circular economy requirements are pressuring manufacturers to eliminate perfluorinated compounds and adopt recycled polyester feedstocks. Stakeholders must monitor evolving Extended Producer Responsibility frameworks for textile waste and decide whether to invest in closed-loop recycling infrastructure or outsource compliance to specialized material suppliers.
Market Dynamics
The EU Green Deal's circular economy mandates are forcing German manufacturers to eliminate perfluorinated compounds from tent fabrics and sleeping bag fills, triggering a wholesale reconfiguration of material sourcing and supplier relationships across the camping equipment supply chain.
Growth Catalysts
- REACH Compliance Pressure:Chemical safety regulations under ECHA governance are accelerating adoption of recycled polyester feedstocks and bio-based alternatives in technical textiles, creating first-mover advantages for compliant suppliers.
- Adventure Seeker Segment Expansion:Experiential outdoor travel prioritization among German consumers is pulling demand toward four-season expedition-grade equipment with premium insulation and weatherproofing specifications.
- Black Forest Infrastructure Investment:Bavarian Alpine regions and southwestern forest corridors are receiving sustained public and private camping facility development, concentrating equipment demand in these geographic clusters.
Market Restraints
- Down Supply Volatility:Feather and down insulation costs fluctuate with avian influenza cycles and ethical sourcing certification requirements, compressing margin stability for sleeping bag manufacturers.
- Aluminum Alloy Concentration:Tent pole and frame production depends heavily on European smelter capacity, exposing the supply chain to energy price shocks and carbon border adjustment mechanisms.
- Technical Textile Limitation:Silicone-coated nylon ripstop with hydrostatic head ratings above 3,000 mm remains difficult to recycle within current mechanical reprocessing infrastructure.
Strategic Opportunities
- Extended Producer Responsibility Tailwinds:Germany's evolving textile waste frameworks incentivize closed-loop recycling infrastructure investment or specialized supplier partnerships for compliance outsourcing.
- Car Camping Application Expansion:Vehicle-based outdoor recreation is driving demand for outdoor furniture and portable cooling systems as distinct product categories with higher margin profiles.
- Retail Channel Convergence:Direct-to-consumer platforms and specialized outdoor retail networks are displacing general sporting goods distribution for technical equipment purchases.
Industry Challenges
- Material Science Talent Gap:Formulation expertise for PFAS-free durable water repellent chemistries remains scarce, slowing product development timelines for compliant tent and sleeping bag lines.
- Certification Timeline Friction:KBA vehicle regulations for trailer and caravan equipment require extended testing protocols that delay new product introductions by multiple quarters.
- Supply Chain Reconfiguration Costs:Transitioning to recycled polyester feedstocks demands capital expenditure for supplier qualification, quality assurance systems, and inventory buffer management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Camping Equipment Market |
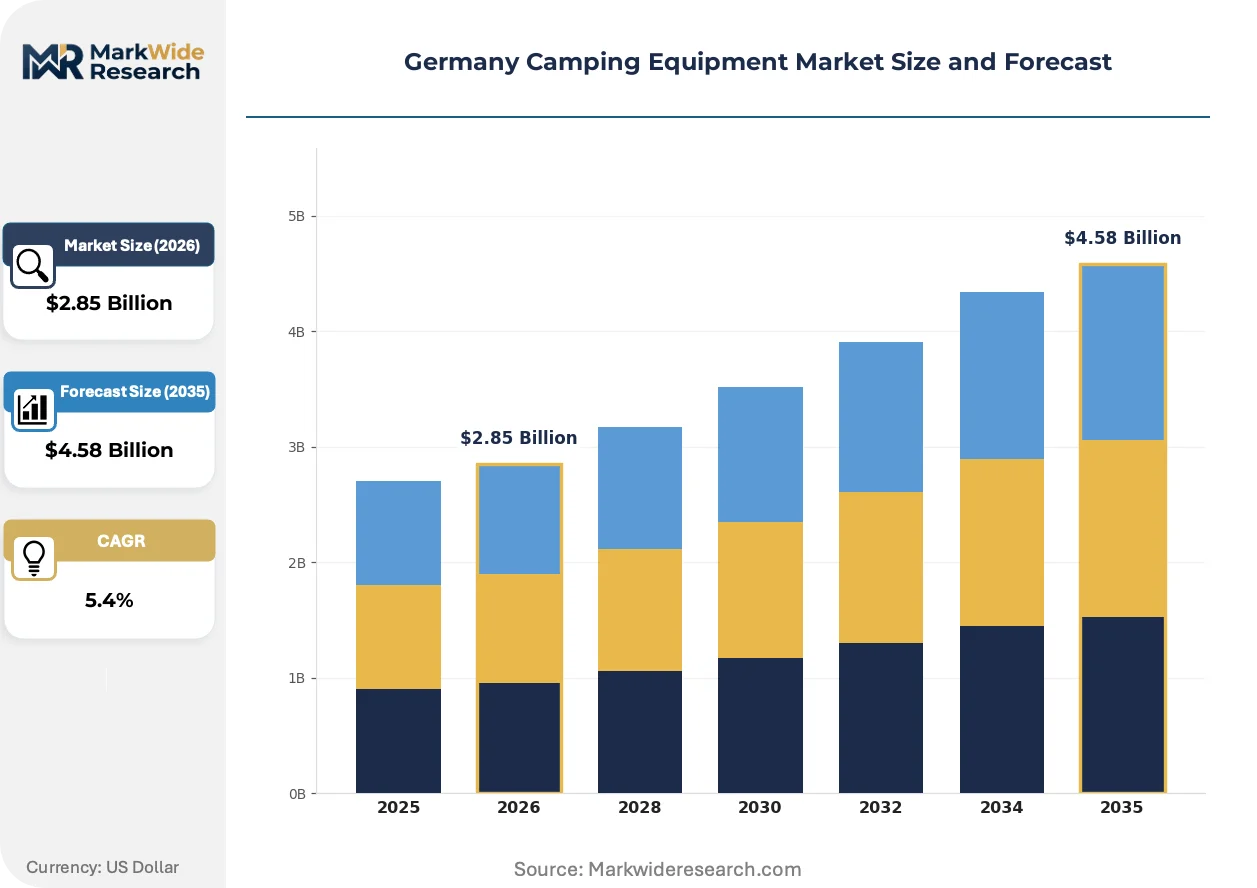
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $4.58 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tents, Sleeping Bags, Camping Stoves, Outdoor Furniture End User: Families, Adventure Seekers, Casual Campers, Youth Groups Distribution Channel: Retail Stores, Online Platforms, Specialty Shops, Camping Events Price Tier: Economy, Mid-range, Premium, Luxury |
| Companies Covered | Dometic Group AB, Hilleberg the Tentmaker, Johnson Outdoors, Newell Brands, Big Agnes, Oase Outdoors ApS, AMG Group Ltd., Exxel Outdoors, Decathlon, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Camping Equipment Market Trends and Innovations
Sustainability mandates and technical performance requirements are converging to reshape how German camping equipment is designed, manufactured, and sold. Material innovation and distribution transformation dominate competitive differentiation.
Silicone-coated nylon ripstop with hydrostatic head ratings above 3,000 mm is modularizing tent architecture across the German market. Adventure seekers and family recreational buyers are adopting component-based shelter systems at accelerating rates. This modularity is compressing replacement cycles while enabling customization that was previously cost-prohibitive at mass-market price points.
REACH compliance under ECHA governance is eliminating perfluorinated compounds from tent fabric treatments and sleeping bag fills. German manufacturers must reformulate durable water repellent chemistries or source alternative barrier technologies. The expedition-grade segment faces the steepest reformulation costs due to performance requirements that PFAS historically satisfied.
Vertical retail control is displacing wholesale distribution for mid-range trekking shelters in Germany. Decathlon's in-house design capabilities and direct store networks are capturing volume that independent outdoor retailers previously intermediated. This channel compression is most visible in Bavaria's Alpine regions where consumer proximity to specialized retail is highest.
Germany Camping Equipment Market Segmentation
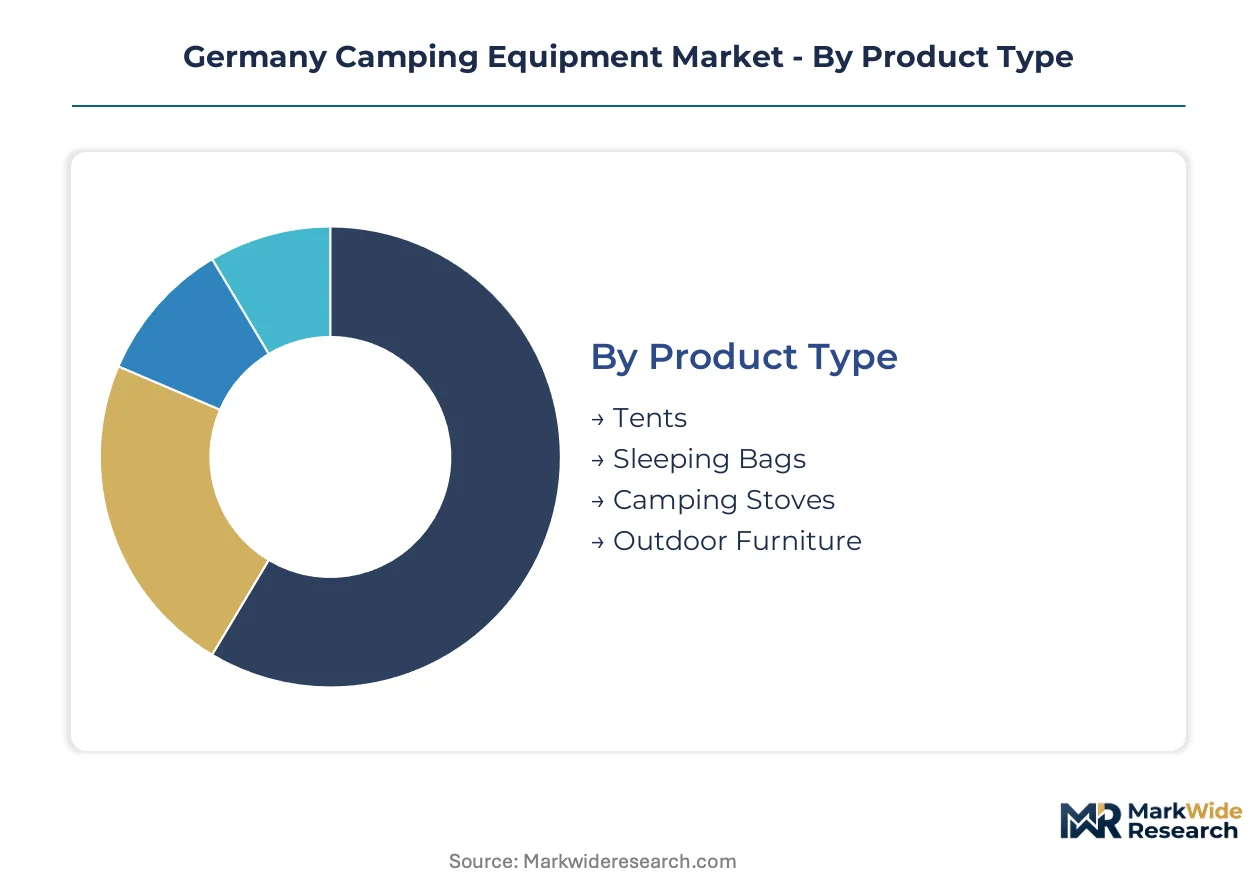
Equipment replacement cycles in Germany diverge sharply between recreational and technical use cases. Segmentation reveals where margin pools concentrate versus where volume scales fastest across the country's outdoor recreation economy.
Product Type:
Upgrade cycles compress where technical specifications advance most rapidly, forcing buyers toward replacement rather than repair.
- Tents:Silicone-coated nylon ripstop with hydrostatic head ratings above 3,000 mm dominates Bavarian Alpine and Black Forest deployments. Modular tunnel and geodesic architectures now displace legacy dome designs as adventure seekers prioritize weatherproofing over weight savings.
- Sleeping Bags:Down and synthetic insulation systems capture distinct buyer tiers—premium down lines face supply volatility from avian influenza cycles, while synthetic fills gain share among cost-conscious recreational users in southwestern forest corridors.
- Camping Stoves:Portable liquid fuel and canister systems serve vehicle-based camping growth.
- Outdoor Furniture:Collapsible chairs and tables expand fastest as car camping infrastructure investment concentrates demand in accessible sites.
Volume placements concentrate in Tents; the faster expansion belongs to Outdoor Furniture.
End User:
Customer archetypes stratify by technical sophistication and purchase frequency, with distinct channel preferences and price elasticity profiles.
- Families:Seasonal recreational purchases sustain baseline volume through mid-range equipment with durability emphasis over technical performance. Black Forest camping infrastructure investment directly serves this segment's accessibility requirements.
- Adventure Seekers:Four-season expedition-grade specifications drive premium tier demand; this cohort tolerates higher price points for weatherproofing and thermal efficiency in Alpine conditions.
- Casual Campers:Infrequent users favor rental and entry-level purchase options.
- Youth Groups:Institutional procurement emphasizes cost efficiency and bulk durability over individual technical features.
Volume placements concentrate in Families; the steepest expansion trajectory belongs to Adventure Seekers.
Distribution Channel:
Channel economics shift as direct-to-consumer platforms capture technical equipment purchases previously intermediated by general sporting goods retailers.
- Retail Stores:Mass-market sporting goods chains retain family recreational volume but lose technical equipment share to specialized competitors. Decathlon's vertical retail control exemplifies this compression in Bavaria's highest-density outdoor markets.
- Online Platforms:Direct-to-consumer sites displace wholesale distribution for mid-range trekking shelters, enabling manufacturers to capture margin previously allocated to independent outdoor retailers.
- Specialty Shops:Technical consultation and fitting services defend premium equipment placements.
- Camping Events:Seasonal expos and festival retail create concentrated demand spikes for impulse and upgrade purchases.
Volume placements concentrate in Retail Stores; the fastest channel expansion belongs to Online Platforms.
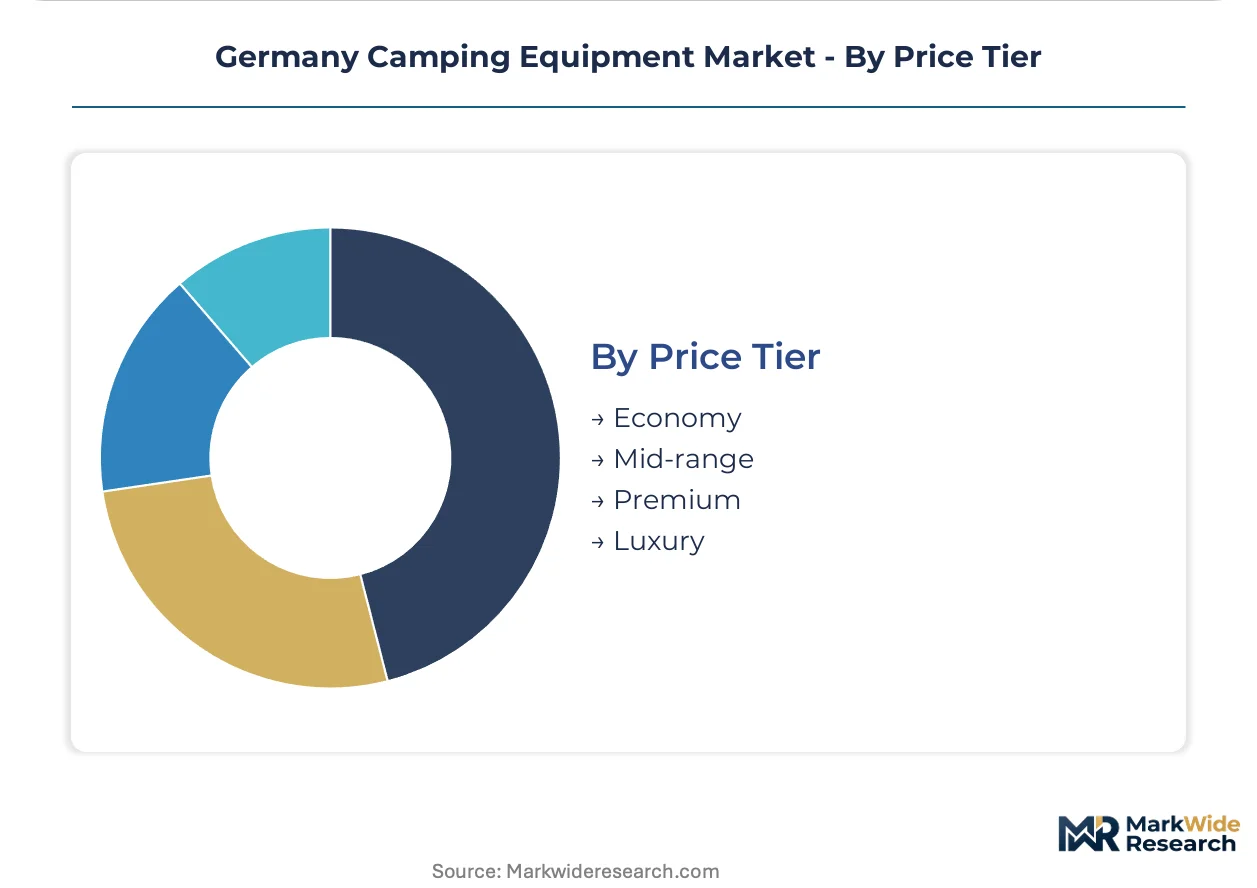
Price Tier:
Cost stratification hardens as material compliance costs under REACH and EU Green Deal mandates compress mid-tier margins.
- Economy:Entry-level synthetic sleeping bags and basic dome tents serve casual campers and youth groups with minimal technical requirements. REACH-compliant recycled polyester feedstocks penetrate this tier first due to lower performance barriers.
- Mid-range:Component-based shelter systems and mixed-fill sleeping bags balance cost with weatherproofing adequacy for Black Forest recreational use.
- Premium:Four-season tunnel tents and down insulation systems target adventure seekers with Alpine performance requirements.
- Luxury:Expedition-grade equipment with proprietary fabric technologies and extended warranties commands highest margins.
Volume placements concentrate in Mid-range; the fastest margin expansion belongs to Premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich anchors German camping equipment demand through its proximity to Alpine trailheads and the concentration of specialized outdoor retail in Bavaria's capital corridor.
Bavaria
Adventure seekers and family recreational users drive equipment purchases across the Alpine foothills and lakeside campgrounds. KBA vehicle regulations govern trailer and caravan equipment standards for the region's extensive motorhome culture. Garmisch-Partenkirchen and Berchtesgaden cluster four-season tent demand as base camps for mountaineering expeditions.
Baden-Württemberg
Black Forest infrastructure investment sustains seasonal recreational volume through upgraded campground facilities and accessible trail networks. REACH compliance under ECHA governance shapes chemical treatments in tent fabrics sourced by regional manufacturers. Freiburg im Breisgau concentrates mid-range equipment retail as the gateway to southwestern forest corridors.
North Rhine-Westphalia
Urban outdoor enthusiasts from Cologne and Düsseldorf generate weekend camping demand for accessible regional parks. The EU Green Deal's circular economy mandates pressure local distributors to stock REACH-compliant recycled polyester products. Sauerland's reservoir districts cluster car camping growth with expanded site amenities.
Lower Saxony
Coastal camping along the North Sea drives demand for weather-resistant shelters and portable cooking systems. Extended Producer Responsibility frameworks for textile waste influence regional retailer procurement policies. Lüneburg Heath nature reserves concentrate youth group and educational camping activity with institutional equipment requirements.
Hesse
Rhine-Main metropolitan campers favor compact, vehicle-compatible equipment for short-duration outdoor recreation. Energy price volatility affects aluminum alloy tent pole costs through European smelter supply chains. Taunus mountain campgrounds anchor premium sleeping bag demand among Frankfurt's adventure-oriented professionals.
Germany Camping Equipment Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Germany's camping equipment sector. The market structures around three tiers: integrated manufacturers with captive textile operations, specialized tent engineering houses, and vertically controlled retail platforms. Strategic moves concentrate on material compliance partnerships under REACH mandates and direct-to-consumer channel expansion that compresses wholesale margins.
Within the thermal systems tier, Dometic Group AB anchors caravan and portable cooling applications through its engineering heritage. Among expedition-grade specialists, Hilleberg the Tentmaker exemplifies tunnel tent architecture engineered for severe weather conditions. Decathlon occupies a position in value-tier distribution through retail network control and in-house design of mid-range trekking shelters.
| Leading Market Players |
|---|
| Dometic Group AB |
| Hilleberg the Tentmaker |
| Johnson Outdoors |
| Newell Brands |
| Big Agnes |
| Oase Outdoors ApS |
| AMG Group Ltd. |
| Exxel Outdoors |
| Decathlon |
| Others |
Pricing and Supply Chain Analysis
Captive textile operations at integrated manufacturers anchor both supply security and pricing power in German camping equipment, insulating premium producers from REACH-driven feedstock volatility that compresses margins for outsourced competitors.
Pricing Analysis
Performance-based pricing anchors German camping equipment tiers, with hydrostatic head ratings and thermal efficiency metrics commanding premiums in Alpine conditions. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and weatherproofing specifications. Cost compression in mid-range synthetic fills is intensifying because recycled polyester feedstock qualification demands capital expenditure. Families exhibit highest price sensitivity through seasonal recreational purchases, while adventure seekers tolerate premium tiers for four-season expedition-grade specifications.
Supply Chain Analysis
Technical textile formulation expertise concentrates in Germany's chemical corridor and select Vietnamese cut-and-sew operations, constraining capacity expansion for PFAS-free durable water repellent chemistries. European smelter output for aluminum alloy tent poles draws from German and Norwegian primary production, with energy price volatility threatening frame cost stability. Single-source vulnerability sits with silicone-coated nylon ripstop suppliers certified above 3,000 mm hydrostatic head. Distribution runs through Decathlon's vertical retail network and specialized outdoor shops displacing wholesale intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German camping equipment functions as a cost-of-compliance story where REACH mandates under ECHA governance erect barrier-to-entry moats favoring incumbents with capitalized reformulation infrastructure.
For Market Incumbents: Anchor market position through backward integration into recycled polyester feedstock production, securing qualified supply chains before Extended Producer Responsibility frameworks tighten. Defend against Decathlon's channel compression by deepening technical consultation services at specialty retail touchpoints in Bavaria's Alpine corridor. Certification investment in PFAS-free chemistries creates sustainable differentiation as regulatory timelines accelerate.
For New Entrants and Emerging Players: Modular tent architecture with component-based customization offers technology-first wedge into mid-range trekking shelters where independent retailers seek alternatives to Decathlon's vertical control. Target car camping outdoor furniture as the most penetrable segment, exploiting infrastructure investment gaps in Black Forest accessible sites. Direct-to-consumer platforms enable margin capture without wholesale distribution overhead.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated outdoor conglomerates seeking REACH-compliant manufacturing assets. Five-to-ten year viability favors producers with captive textile operations and established ECHA regulatory relationships over asset-light designers. Monitor avian influenza cycles as inflection indicator for down insulation supply stability and synthetic fill substitution rates.
| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Chemistry Reformulation | REACH compliance under ECHA governance eliminates perfluorinated compounds, forcing material science investment. |
| Closed-Loop Recycling Infrastructure | Extended Producer Responsibility frameworks incentivize captive recovery systems for technical textiles. |
| Direct-to-Consumer Channel Expansion | Online platforms displace wholesale margins previously allocated to independent outdoor retailers. |
| Modular Shelter System Development | Component-based architectures compress replacement cycles while enabling mass-market customization. |
| Car Camping Application Diversification | Vehicle-based recreation drives demand for outdoor furniture and portable cooling with higher margin profiles. |
Research Methodology
Document review covered ECHA regulatory filings, KBA vehicle equipment standards, EU Green Deal circular economy mandates, and customs trade data, complemented by interviews with technical textile procurement directors, camping equipment brand managers, specialty retail buyers, and outdoor industry association executives. Secondary validation drew from SEC filings of listed outdoor conglomerates, German Federal Statistical Office production data, and Bavarian tourism infrastructure investment disclosures. Bottom-up equipment unit economics and top-down regional demand aggregation enabled triangulation across primary and secondary sources.
Segmentation outputs across product type, end user archetype, distribution channel, and price tier informed volume and value projections over the analysis window. CAGRs derived from historical replacement cycle analysis, infrastructure investment pipelines, and regulatory compliance timeline modeling. Forecast inputs incorporated KBA certification protocol durations, REACH chemical restriction phase-in schedules, and Black Forest campground development permits.
Several conditions sit outside the modeled scope, including abrupt avian influenza mutations disrupting down supply, unilateral tariff impositions on aluminum alloy imports, and accelerated EU Green Deal timelines beyond current ECHA guidance. Forecasts reflect documented assumptions regarding regulatory stability and feedstock qualification trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
Canoe Paddles Market
Outdoor Gear
Japan Camping Equipment Market
Outdoor Gear
Beach Umbrella Market
Outdoor Gear
Japan Camping Tent Market
Outdoor Gear
Inflatable Tents Market
Outdoor Gear
Crash Pads Market
Outdoor Gear
Camp Fire Tripod Market
Outdoor Gear
Shoulder Strap Insulated Cooler Market
Outdoor Gear
Campsite Cooking Gears Market
Outdoor Gear
Wheeled Insulated Cooler Market
Outdoor Gear
Diving Equipment Market
Outdoor Gear
China Camping Equipment Market
Outdoor Gear
Fairway Mowers Market
Outdoor Gear
Camping Equipment Market
Outdoor Gear
Ice Axe Market
Outdoor Gear
China Camping Tent Market