
 MES Software Market | 2026-2036
MES Software Market Size, Share, and Industry Trends Forecast 2026-2036
MES Software Market Outlook
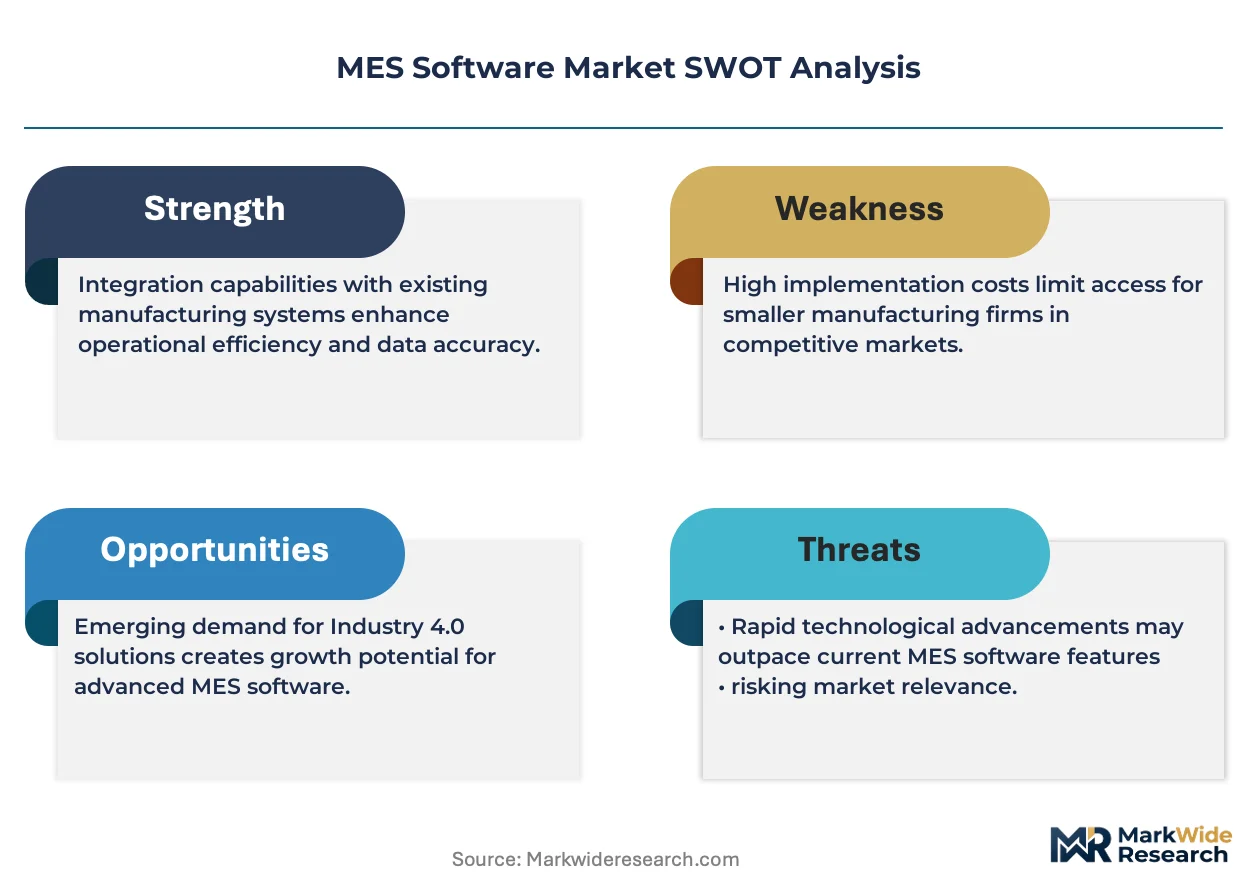
Modular subscription packaging is broadening buyer choice in MES procurement, letting mid-sized manufacturers acquire quality management or inventory control modules without full-suite commitments. GE Proficy leverages its industrial software heritage to anchor complex process manufacturing deployments. Rockwell FactoryTalk competes through tight integration with its automation hardware ecosystem. AVEVA MES differentiates via deep asset performance management capabilities tied to energy and infrastructure verticals.
Manufacturing execution system software orchestrates shop-floor operations by interfacing directly with PLCs, SCADA networks, and enterprise ERP layers to enforce production schedules, capture lot genealogy, and trigger quality holds in real time. Cloud-based deployment is outpacing on-premises installations as factories seek elastic compute for IoT data ingestion without capital-heavy server farms. Production Management solutions occupy the largest solution share given their role as the core scheduling and dispatching engine, while Data Analytics modules are expanding fastest as manufacturers pursue predictive quality models. Automotive end users sustain the deepest integration investments due to just-in-sequence assembly complexity and supplier traceability mandates.
FDA 21 CFR Part 11 compliance requirements in pharmaceuticals and the EU MDR traceability framework in medical devices are hardening demand for validated MES platforms with immutable audit trails. ISO 22400 standards for key performance indicators in manufacturing operations are shaping how vendors structure their analytics dashboards and benchmarking modules. Buyers must weigh vendor roadmaps for AI-driven anomaly detection against the interoperability risks of proprietary data architectures.
Market Dynamics
Cloud-native architectures are compressing deployment cycles from months to weeks, forcing incumbent vendors to modularize monolithic suites while pharmaceutical serialization mandates under the EU Falsified Medicines Directive harden compliance requirements.
Growth Catalysts
- EU Falsified Medicines Directive:Serialization mandates compel pharmaceutical manufacturers to deploy validated MES platforms with immutable audit trails for end-to-end lot traceability.
- Automotive just-in-sequence assembly:Tier-1 suppliers deepen MES integration to manage supplier traceability and real-time production sequencing for electric vehicle platforms.
- Edge computing architectures:Distributed processing nodes at the PLC layer reduce latency for quality holds and predictive maintenance triggers.
Market Restraints
- Legacy ERP entrenchment:Proprietary data architectures in incumbent systems create interoperability friction and elevate switching costs for brownfield facilities.
- Validated system recertification:FDA 21 CFR Part 11 compliance timelines extend 18-24 months for software updates, freezing vendor release cycles.
- OT-IT skill scarcity:Shortage of engineers proficient in both shop-floor protocols and cloud infrastructure constrains implementation velocity.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for electronics and pharmaceutical manufacturing are accelerating greenfield MES deployments in contract manufacturing clusters.
- AI-driven anomaly detection:Convergence of machine learning models with historian databases enables predictive quality models that reduce scrap rates.
- Subscription module unbundling:Quality management and inventory control modules sold separately lower entry barriers for mid-sized manufacturers.
Industry Challenges
- Multi-protocol integration complexity:Harmonizing OPC-UA, MQTT, and proprietary PLC protocols demands specialized system integrators and extends project timelines.
- Cybersecurity certification lag:IEC 62443 compliance for industrial control systems requires vendor investment that smaller players cannot absorb.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MES Software Market |
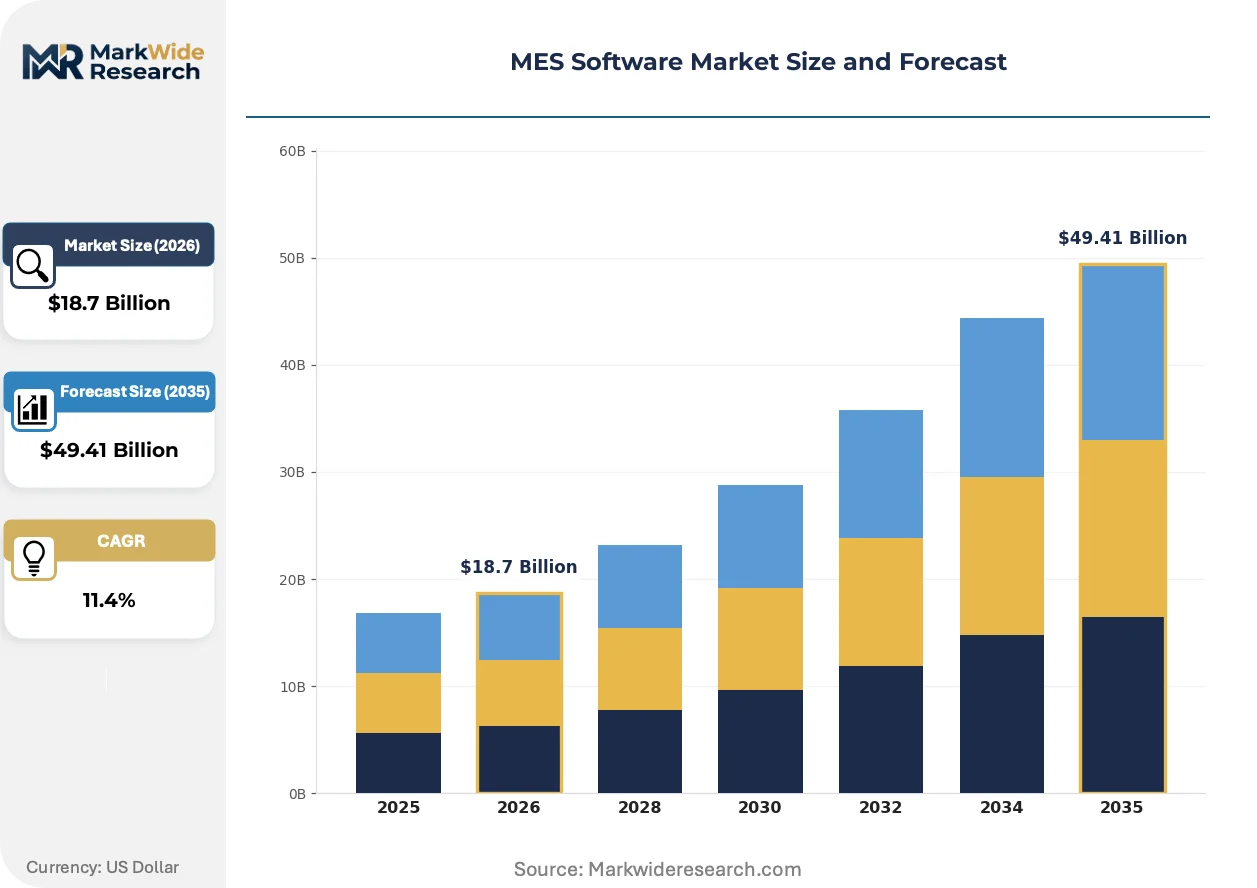
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-premises, Cloud-based, Hybrid, SaaS End User: Manufacturing, Automotive, Pharmaceuticals, Aerospace Solution: Production Management, Quality Management, Inventory Control, Data Analytics Integration Level: ERP Integration, IoT Integration, API Integration, Legacy Systems |
| Companies Covered | GE Proficy, DELMIA Apriso, Honeywell Forge, iProd, Matta, Rockwell FactoryTalk, Plex, TruMES, AVEVA MES, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MES Software Market Strategic Shifts
Digital thread architectures are dissolving boundaries between product lifecycle management and shop-floor execution, enabling closed-loop feedback from field performance back to process parameters.
Edge-native MES platforms are converging with containerized microservices to push compute closer to PLCs and SCADA nodes. Automotive manufacturers in Germany and Japan are piloting these architectures to reduce cloud dependency for sub-10-millisecond quality holds. The structural result is converging with a hybrid deployment model where sensitive process data remains on-premise while analytics workloads burst to cloud infrastructure.
EMA's intensified scrutiny of computer system validation is extending audit requirements to cloud-hosted MES environments. Pharmaceutical contract manufacturers must now demonstrate physical and logical separation of tenant data alongside 21 CFR Part 11 compliance. European facilities are responding by demanding vendor-provided validation documentation packages that accelerate regulatory submissions.
Mid-sized manufacturers are abandoning perpetual licenses for consumption-based pricing tied to production volume or active user seats. This shift compresses vendor revenue recognition cycles while transferring capital expenditure risk to software providers. The pattern is most pronounced in Germany, where factory networks prioritize scalable connectivity without heavy infrastructure overhaul.
MES Software Market Segmentation
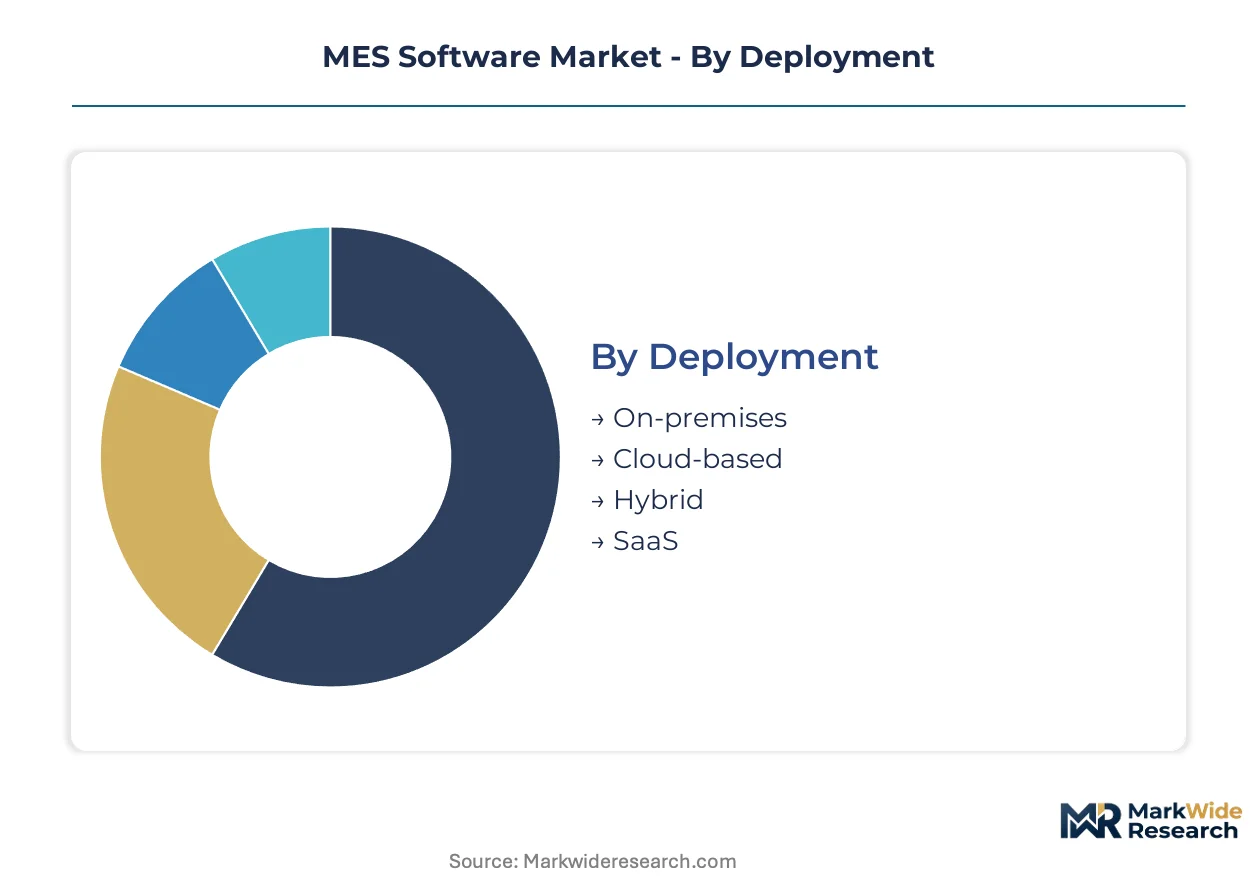
MES software procurement patterns diverge sharply by deployment philosophy, operational maturity, and integration complexity. Buyers select architectures based on regulatory exposure, legacy asset bases, and cloud-readiness of shop-floor networks.
Deployment:
Standardization pressure intensifies at the infrastructure layer as vendors push cloud-native stacks against entrenched on-premises preferences in regulated industries.
- On-premises:Installed within factory data centers with direct PLC connectivity and air-gapped security architectures. Pharmaceutical manufacturers in Germany and Switzerland favor this model for validated environments under EMA and Swissmedic scrutiny where physical data sovereignty is non-negotiable.
- Cloud-based:Delivered via multi-tenant platforms with elastic compute for IoT data lakes and predictive analytics workloads. German automotive suppliers are migrating fastest to this model to avoid capital-intensive server refreshes while scaling connectivity across supplier networks.
- Hybrid:Sensitive process data remains on-premise while analytics and reporting burst to cloud infrastructure. This architecture dominates brownfield facilities in Japan balancing METI cybersecurity guidelines against Industry 4.0 modernization mandates.
- SaaS:Consumption-based pricing tied to production volume or active user seats with rapid deployment cycles. Mid-sized contract manufacturers in India's PLI-backed electronics clusters are adopting this to compress implementation timelines.
Most installed capacity flows through On-premises deployments. Expansion is steepest in Cloud-based configurations.
End User:
Demand concentration maps to traceability burden and assembly complexity rather than pure production scale.
- Manufacturing:General discrete and process manufacturers with mixed-mode production lines and moderate regulatory exposure. Food and beverage processors under FSSAI and FDA jurisdiction deploy validated MES for lot genealogy and allergen control.
- Automotive:Just-in-sequence assembly operations with supplier traceability mandates and electric vehicle platform complexity. Tier-1 suppliers in Germany and Japan sustain the deepest integration investments due to real-time production sequencing requirements.
- Pharmaceuticals:Batch process manufacturers subject to FDA 21 CFR Part 11 and EU Falsified Medicines Directive serialization mandates. These buyers demand immutable audit trails and validated system documentation packages.
- Aerospace:Defense and commercial aviation with AS9100 quality standards and long-tail component traceability across multi-tier supply chains. Boeing and Airbus supplier networks in the US and France drive specialized MES configurations.
Automotive commands the largest integration budgets per facility. Pharmaceuticals is climbing the fastest as serialization deadlines harden.
Solution:
Module selection reflects where manufacturers perceive the greatest operational leverage versus compliance risk.
- Production Management:Core scheduling, dispatching, and work-order execution engines interfacing directly with PLCs and SCADA layers. This remains the default entry point for first-time MES adopters in automotive and industrial machinery.
- Quality Management:Electronic batch records, statistical process control, and non-conformance tracking with closed-loop corrective action. Pharmaceutical and medical device manufacturers under EU MDR and FDA jurisdiction treat this as mandatory infrastructure.
- Inventory Control:WIP tracking, material genealogy, and warehouse synchronization with ERP systems. Electronics manufacturers in South Korea and Taiwan deploy these modules to manage high-velocity component flows.
- Data Analytics:Historian databases, predictive quality models, and AI-driven anomaly detection converging with machine learning pipelines. This module is expanding most quickly as manufacturers pursue scrap reduction and predictive maintenance triggers.
Production Management retains the largest installed base. Data Analytics is gaining share fastest as edge computing architectures mature.
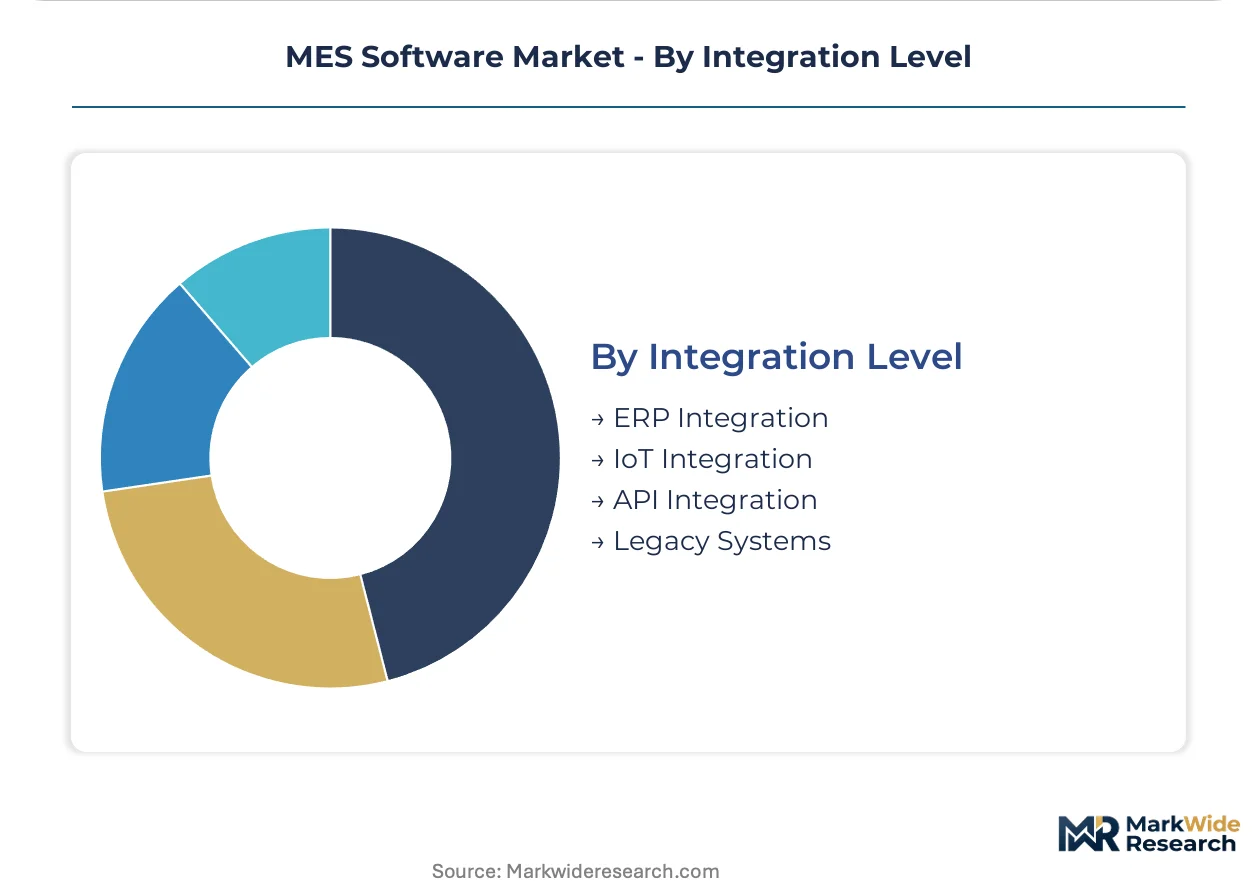
Integration Level:
Interoperability requirements harden as brownfield complexity meets cloud-native vendor roadmaps.
- ERP Integration:Bi-directional data exchange with SAP, Oracle, and Microsoft Dynamics for financial reconciliation and demand planning. This remains the baseline expectation across all end-user categories.
- IoT Integration:OPC-UA and MQTT protocol handlers ingesting sensor streams from smart devices and edge gateways. German automotive manufacturers prioritize this for real-time quality holds and predictive maintenance.
- API Integration:RESTful interfaces enabling low-code connectivity with specialized manufacturing applications and supplier portals. Contract manufacturers in India's pharmaceutical clusters leverage this for rapid ecosystem integration.
- Legacy Systems:Adapter layers for proprietary PLC protocols and decades-old SCADA installations in brownfield facilities. This integration tier consumes disproportionate implementation resources in US and European heavy industry.
ERP Integration anchors the majority of active deployments. IoT Integration is expanding most steeply as digital thread architectures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MES software originated in American and German automotive plants during the 1980s, where shop-floor data collection first merged with enterprise planning systems. Today deployment patterns reflect divergent regulatory regimes and manufacturing maturity across industrial economies.
United States
FDA 21 CFR Part 11 compliance requirements drive pharmaceutical manufacturers toward validated platforms with immutable audit trails. The FDA intensifies computer system validation scrutiny for cloud-hosted environments. Boston and Research Triangle Park clusters host contract manufacturers demanding rapid-deployment SaaS architectures.
Germany
Automotive just-in-sequence assembly complexity sustains the deepest integration investments globally. KBA traceability mandates intersect with Industry 4.0 modernization programs under BMWi funding. Stuttgart and Wolfsburg supplier networks prioritize hybrid deployments balancing METI-aligned cybersecurity with elastic cloud analytics.
China
Electronics contract manufacturers under MIIT guidelines accelerate greenfield MES adoption for high-velocity component tracking. NMPA serialization requirements for pharmaceuticals harden demand for validated batch records. Shenzhen and Suzhou industrial zones deploy edge-native architectures to reduce latency for quality holds.
India
PLI scheme incentives for electronics and pharmaceutical manufacturing compress implementation timelines in contract manufacturing clusters. CDSCO traceability mandates converge with FSSAI lot genealogy requirements for food processors. Bangalore and Hyderabad pharma corridors adopt modular subscription packaging to avoid full-suite capital commitments.
Japan
METI cybersecurity guidelines shape hybrid deployment preferences among automotive and precision machinery manufacturers. PMDA quality system regulations extend validation requirements to medical device production. Nagoya and Toyota City manufacturing networks pilot edge computing nodes for sub-10-millisecond predictive maintenance triggers.
MES Software Market Competitive Environment
The competitive structure tilts toward industrial automation heritage players with entrenched PLC integration capabilities. Incumbent vendors with decades of shop-floor protocol experience command premium positioning in regulated verticals. Three archetypes dominate: automation-hardware-anchored suites, cloud-native challengers with consumption pricing, and vertical specialists with pre-validated pharmaceutical modules. Strategic moves concentrate on modular unbundling of monolithic suites and rapid certification partnerships for IEC 62443 cybersecurity compliance.
Among automation-heritage providers, GE Proficy and Rockwell FactoryTalk exemplify the hardware-anchored archetype, while AVEVA MES occupies a position within the asset-performance-focused tier. These three represent divergent responses to cloud-native pressure: GE Proficy leverages industrial software lineage for complex process manufacturing, Rockwell FactoryTalk competes through tight integration with its automation ecosystem, and AVEVA MES differentiates via energy and infrastructure vertical depth.
| Leading Market Players |
|---|
| GE Proficy |
| DELMIA Apriso |
| Honeywell Forge |
| iProd |
| Matta |
| Rockwell FactoryTalk |
| Plex |
| TruMES |
| AVEVA MES |
| Others |
Value Chain & Pricing Dynamics
OT-IT engineering talent concentration in Germany's Stuttgart and Munich corridors widens pricing-tier spreads between validated pharmaceutical deployments and mid-market SaaS configurations, as labor-cost differentials compound with compliance documentation burdens.
Pricing Analysis
Consumption-based subscription tiers tied to production volume or active user seats now dominate procurement conversations. Three-tier pricing structure across premium, standard, and economy levels separates validated pharmaceutical suites with FDA 21 CFR Part 11 documentation from rapid-deployment SaaS offerings for contract manufacturers. Price differentiation hinges on certification grade and customization depth. Pricing pressure stems from modular unbundling as vendors compete for mid-sized manufacturers. Tier-1 automotive suppliers exhibit lowest price sensitivity due to integration complexity lock-in, while India's PLI-backed electronics clusters drive hardest bargain on per-seat economics.
Supply Chain Analysis
Edge computing hardware supply rests on Taiwanese semiconductor foundries and German industrial automation component specialists. Cloud infrastructure draws from hyperscaler data centers in Ireland, Singapore, and Virginia. Software development talent clusters in India's Bangalore and Hyderabad corridors. Single-source vulnerability concentrates in legacy PLC protocol adapter layers where decades-old documentation creates switching friction. Distribution runs through direct vendor sales organizations for enterprise accounts and regional system integrators for mid-market deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The MES software market functions as a stable compounder, with regulatory serialization mandates across pharmaceuticals and automotive traceability requirements generating recurring replacement cycles that sustain vendor revenue predictability.
For Market Incumbents: Anticipate cloud-native challengers compressing deployment timelines from months to weeks by accelerating modular unbundling of monolithic suites. Defensive investments should concentrate on IEC 62443 cybersecurity certification partnerships and pre-validated documentation packages that shorten pharmaceutical customer regulatory submissions. Threat intensity peaks among SaaS entrants targeting India's PLI electronics clusters with consumption pricing. For New Entrants and Emerging Players: System integrators with brownfield legacy system expertise represent the most accessible channel partnership archetype for market penetration. White-space targets concentrate on mid-sized contract manufacturers in India's pharmaceutical corridors seeking modular quality management without full-suite capital commitments. Automotive Tier-2 suppliers in Japan's Nagoya manufacturing network present secondary opportunity given METI cybersecurity guideline compliance gaps. For Investors and Strategic Acquirers: Industrial automation conglomerates with captive PLC hardware ecosystems are the most active acquirer in this space, seeking software capabilities that tighten customer switching costs. Acquisition target archetypes include vertical specialists with pre-validated pharmaceutical modules and edge-native platform developers with containerized microservice architectures. Long-term viability over a five-to-ten year window depends on AI-driven anomaly detection integration depth. The signal to watch is FDA guidance evolution on cloud-hosted computer system validation requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Unbundling | Quality management modules sold separately lower entry barriers for India's PLI electronics manufacturers. |
| Edge-Native Platform Development | Containerized microservices at PLC layer reduce latency for German automotive sub-10-millisecond quality holds. |
| Cybersecurity Certification Partnership | IEC 62443 compliance investments address European pharmaceutical contract manufacturer procurement requirements. |
| Pre-Validated Documentation Packaging | FDA 21 CFR Part 11 documentation accelerates EMA scrutiny timelines for cloud-hosted MES deployments. |
| AI-Driven Anomaly Detection Integration | Machine learning convergence with historian databases enables predictive quality models for scrap reduction. |
Study Parameters
Direct dialogue with MES implementation specialists, pharmaceutical validation officers, automotive Tier-1 procurement directors, and cloud infrastructure architects grounded qualitative insights. Secondary validation drew from FDA 21 CFR Part 11 guidance documents, EMA computer system validation inspection reports, IEC 62443 industrial cybersecurity standards, and vendor SEC filings. Bottom-up deployment sizing across deployment models, end-user verticals, and solution modules triangulated against top-down industrial software market assessments.
Segmented outputs across the analysis window reflect modeled deployment trajectories by cloud-native, hybrid, and on-premises architectures, disaggregated further by pharmaceutical, automotive, aerospace, and general manufacturing end-user categories. CAGRs derived from installation base growth rates, replacement cycle compression, and module attachment rate evolution. Forecast inputs incorporated PLI scheme incentive timelines, EU Falsified Medicines Directive serialization deadlines, and edge computing hardware cost curves.
Revisions become necessary when regulatory validation timelines compress or extend, cloud security guidance from FDA or EMA shifts substantively, or OT-IT skill scarcity intensifies beyond current absorption capacity. A small set of named triggers warrants ongoing watch: EMA cloud-hosting scrutiny intensity, India PLI scheme renewal structure, and German automotive just-in-sequence complexity migration to electric platforms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
House Cleaning App Market
Software & Services
Nonconformance Management Software Market
Software & Services
Global Decision Support Software Market
Software & Services
Tag Management Software Market
Software & Services
Game Development Software Market
Software & Services
Global Core Human Resource Software Market
Software & Services
3PL Software Market
Software & Services
Coaching Management Software Market
Software & Services
Global Healthcare Contract Management Software Market
Software & Services
United States IT Services Market
Software & Services
Italy HR Payroll Software Market
Software & Services
Document-Centric Collaboration Software Market
Software & Services
Animation Design Software Market
Software & Services
Global Dance Studio Software Market
Software & Services
Attendance Management Software Market
Software & Services
Preschool Education Software Market