
 Commerce As a Service (Caas) Market | 2026-2036
Commerce As a Service (Caas) Market Size, Share, and Industry Trends Forecast 2026-2036
Commerce As a Service (Caas) Market Analysis
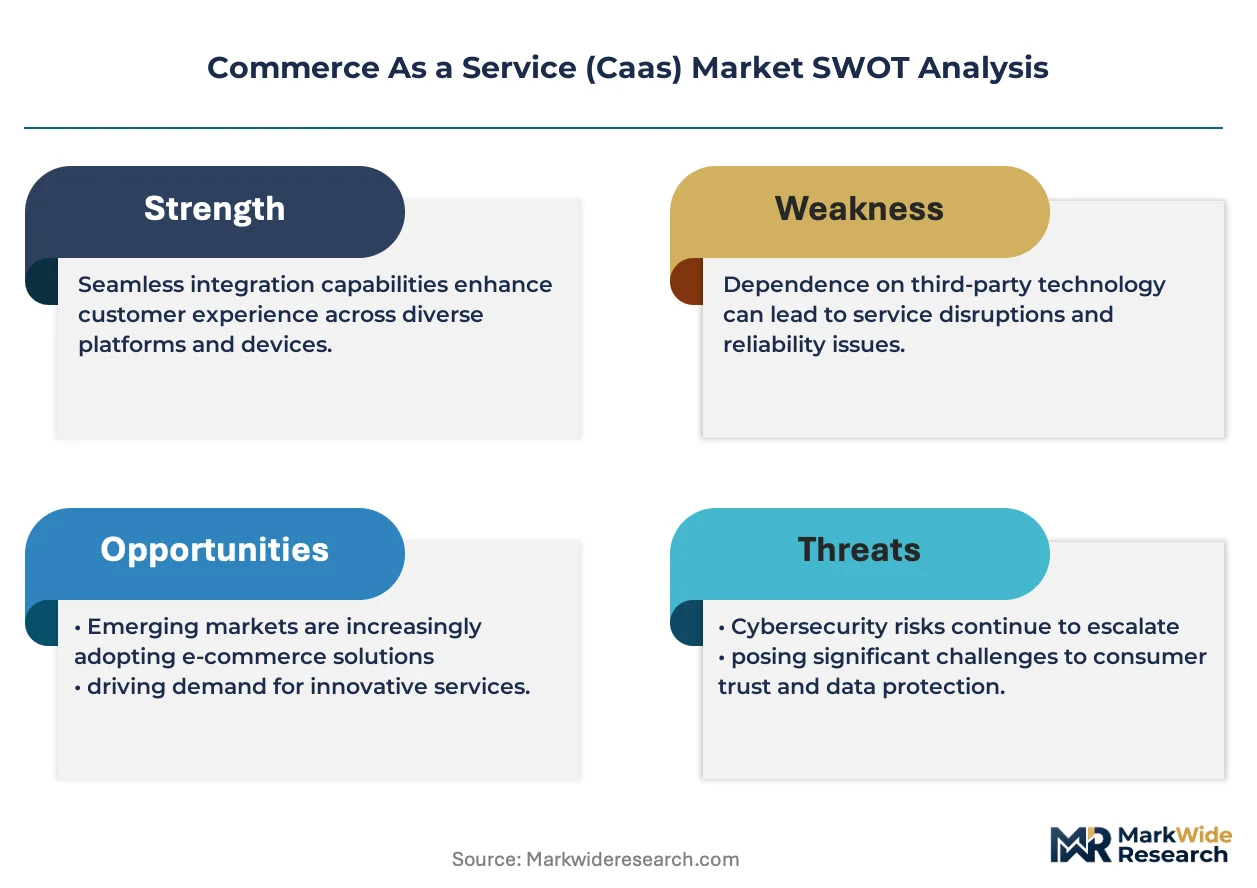
The gap between premium managed commerce stacks and commodity API bundles is recalibrating competitive dynamics across the sector. Oracle Corporation leverages its database heritage to anchor high-availability enterprise deployments. Microsoft Corporation competes through Azure-native integration that extends into ERP and CRM workflows. Amazon Web Services, Inc. dominates infrastructure-layer provisioning, controlling cost curves that shape downstream pricing.
Commerce as a Service denotes the outsourcing of retail technology infrastructure—spanning checkout orchestration, inventory synchronization, and payment tokenization—to third-party platforms accessible via RESTful APIs and microservice meshes. Its primary commercial purpose is to decouple front-end merchandising from back-end transactional complexity, enabling brands to deploy commerce capabilities without maintaining proprietary data centers. Payment Processing and Order Fulfillment command the deepest margin pools, reflecting their operational criticality and switching costs. API Integration leads technology adoption, while Hybrid Cloud deployment is gaining traction among enterprises balancing latency requirements with regulatory data-sovereignty constraints.
The EU AI Act, GDPR, and PCI DSS collectively tighten compliance obligations for cross-border transaction processing and automated decision-making in customer engagement workflows. The EU AI Act specifically imposes risk-tiered obligations on AI-driven product recommendations and dynamic pricing engines, forcing vendors to re-architect analytics pipelines. Stakeholders must monitor how divergent regulatory timelines between Europe and the United States reshape vendor roadmaps and client procurement criteria.
Market Dynamics
Mid-market retailers are abandoning monolithic legacy stacks for modular API-first architectures, compressing vendor selection cycles and redefining implementation risk profiles across the sector.
Growth Catalysts
- PCI DSS 4.0 mandates:The updated standard's enhanced authentication requirements are forcing retailers to outsource tokenization infrastructure rather than build in-house compliance layers.
- Headless commerce adoption:Direct-to-consumer brands are decoupling front-end presentation from back-end transaction processing to accelerate omnichannel deployment.
- Micro-fulfillment networks:Urban warehouse densification in the United States is creating demand for real-time inventory APIs that synchronize stock across distributed nodes.
Market Restraints
- Cloud egress cost volatility:Cross-border data transfer fees from hyperscale providers erode margin predictability for multi-region deployments.
- API dependency concentration:Critical checkout infrastructure relies on a narrow tier of infrastructure providers, creating single-point-of-failure exposure.
- GDPR territorial scope:The regulation's extraterritorial application imposes compliance overhead on non-EU vendors serving European consumers.
Strategic Opportunities
- Embedded finance convergence:The intersection of banking-as-a-service APIs and commerce infrastructure enables checkout-native lending and insurance products.
- India's ONDC protocol:The country's open network for digital commerce mandates interoperable APIs, creating standardized entry points for foreign platform providers.
- Carbon accounting integration:The EU CSRD's scope 3 disclosure requirements position emissions-tracking APIs as a value-added layer for enterprise clients.
Industry Challenges
- Observability tooling gaps:Distributed microservice architectures generate fragmented telemetry that complicates root-cause analysis during checkout failures.
- OAuth scope creep:Expanding permission requirements across integrated third-party services multiply attack surfaces and audit complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commerce As a Service (Caas) Market |
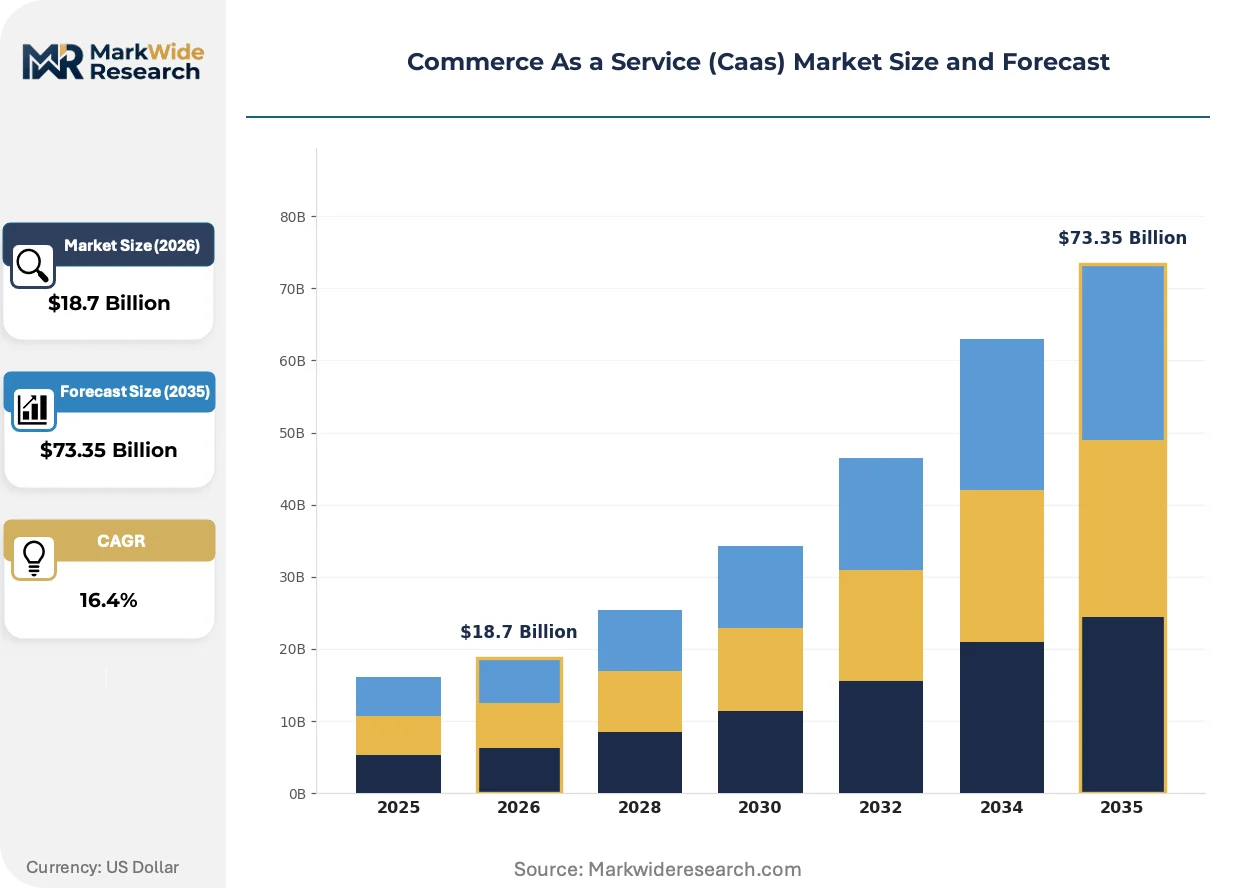
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Payment Processing, Inventory Management, Order Fulfillment, Customer Engagement Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premise End User: Retailers, E-commerce Platforms, Brands, Startups Technology: API Integration, Microservices, SaaS Solutions, AI Analytics |
| Companies Covered | Oracle Corporation, Hewlett Packard Enterprise Development LP, Alibaba Cloud, Rackspace Hosting, Inc., International Business Machines Corporation, Dell Technologies Inc., Google LLC, Microsoft Corporation, Amazon Web Services, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commerce As a Service (Caas) Market Emerging Trajectories
Real-time inventory graph technology is collapsing the latency between stock-level visibility and customer-facing availability signals, eliminating oversell risk in high-velocity categories.
Edge-deployed machine learning inference is rewriting how product recommendation engines operate, shifting computation from centralized cloud regions to points-of-presence within 50 milliseconds of end users. Fast-fashion retailers are piloting these architectures to serve personalized ranking without exposing raw behavioral data to cross-border transit. The shift compresses infrastructure costs while complicating model governance under divergent national AI regulations.
The EU AI Act's risk-tiered obligations for automated decision-making are forcing vendors to re-architect pricing and recommendation pipelines around human-in-the-loop checkpoints. High-risk system classifications now apply to dynamic discount engines that profile consumers based on behavioral data. Compliance investments are diverting R&D resources from feature velocity toward documentation and audit trail infrastructure.
Subscription-native checkout flows are displacing traditional cart-and-checkout patterns among digitally native vertical brands. Merchants are unbundling one-time purchase infrastructure in favor of recurring billing primitives that handle dunning, pause mechanics, and upgrade orchestration. This behavioral pivot is most pronounced in United States wellness and pet categories, where customer lifetime value metrics now dominate acquisition cost optimization.
Commerce As a Service (Caas) Market Segmentation
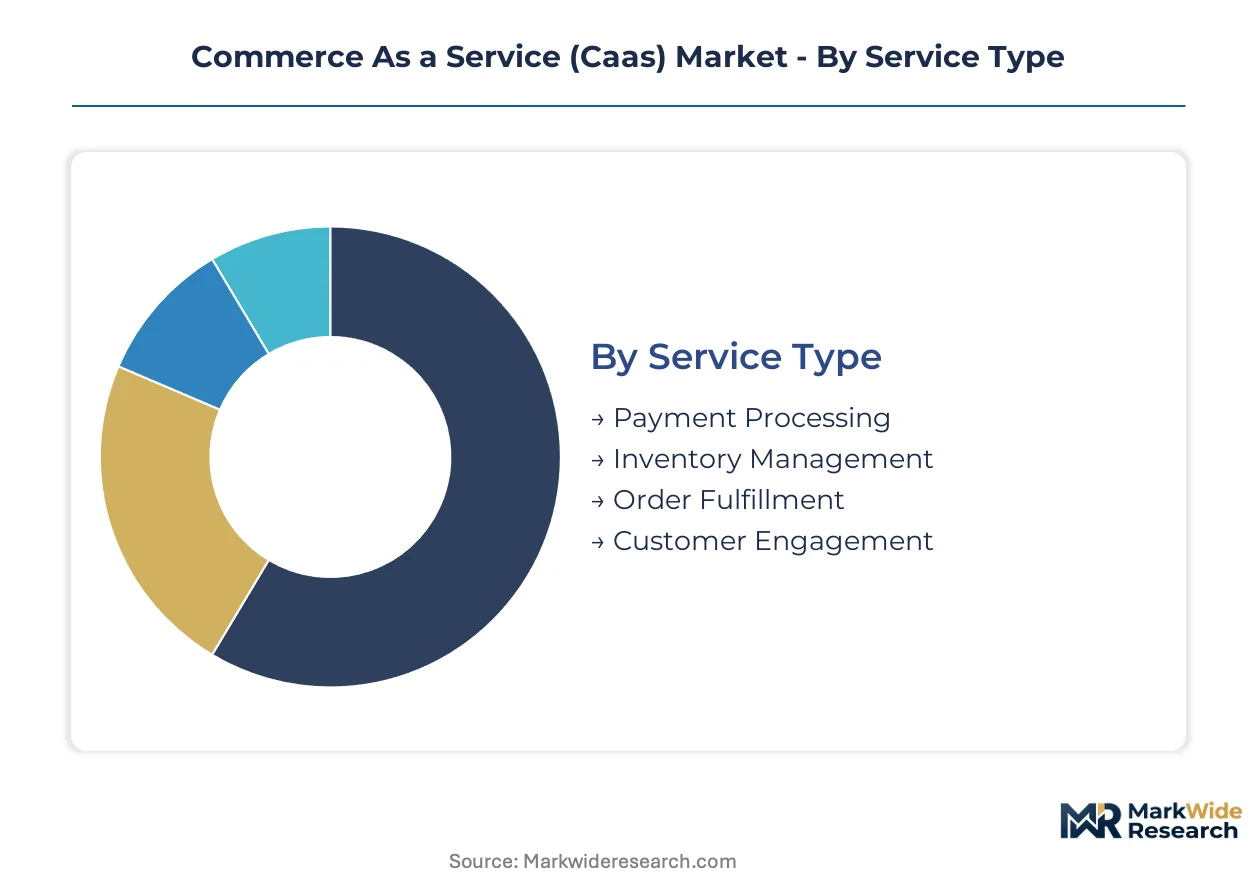
Commerce As a Service architectures fragment across service layers, deployment topologies, and integration technologies that determine implementation complexity and total cost of ownership. Understanding segment boundaries clarifies where vendors compete on performance versus where standardization erodes pricing power.
Service Type:
Payment Processing and Order Fulfillment operate as embedded infrastructure requiring deep system integration, while Inventory Management and Customer Engagement function more readily as standalone modules.
- Payment Processing:Tokenization engines and checkout orchestration layers that handle PCI DSS compliance, fraud scoring, and multi-processor routing. Demand concentrates among United States direct-to-consumer brands seeking to decouple front-end merchandising from back-end transaction complexity, driven by PCI DSS 4.0 mandates that raise in-house compliance costs.
- Order Fulfillment:Micro-fulfillment network coordination, real-time inventory synchronization, and last-mile delivery API management. Urban warehouse densification across United States metropolitan clusters creates demand for stock-level visibility across distributed nodes, constrained by cloud egress cost volatility in multi-region deployments.
- Inventory Management:SKU-level tracking, demand forecasting, and supplier integration platforms.
- Customer Engagement:Recommendation engines, loyalty program orchestration, and behavioral analytics pipelines.
Payment Processing leads volumes today; Order Fulfillment is gaining share fastest.
Deployment Model:
Cost tiering separates hyperscale public deployments from captive infrastructure, with hybrid configurations commanding premium positioning for latency-sensitive workloads.
- Public Cloud:Multi-tenant infrastructure provisioning via AWS, Azure, or Google Cloud with consumption-based pricing. Mid-market retailers in the United States favor this model for rapid scaling without capital expenditure, though cross-border data transfer fees erode margin predictability.
- Hybrid Cloud:Workload splitting between on-premise transaction processing and cloud-based analytics, balancing latency requirements against regulatory data-sovereignty constraints. European retailers under GDPR territorial scope obligations drive adoption here, forced by EU AI Act compliance timelines to maintain local inference capabilities.
- Private Cloud:Single-tenant infrastructure with dedicated compute and storage resources.
- On-Premise:Fully captive data center deployments retaining direct hardware control.
Public Cloud dominates transaction volumes; Hybrid Cloud shows the steepest expansion trajectory.
End User:
Customer maturity and technical sophistication determine procurement patterns, from legacy-dependent retailers to API-native startups.
- Retailers:Brick-and-mortar chains and multi-channel operators modernizing from monolithic legacy stacks. Mid-market United States retailers represent the core migration wave, compressing vendor selection cycles as they abandon in-house commerce infrastructure.
- E-commerce Platforms:Marketplace operators and SaaS storefront providers requiring white-label commerce primitives. These buyers in the United States prioritize modular checkout infrastructure that accelerates omnichannel deployment for their merchant bases.
- Brands:Digitally native vertical brands and established consumer goods companies.
- Startups:Early-stage companies prioritizing speed-to-market over customization depth.
Retailers anchor current demand; E-commerce Platforms are climbing the fastest.
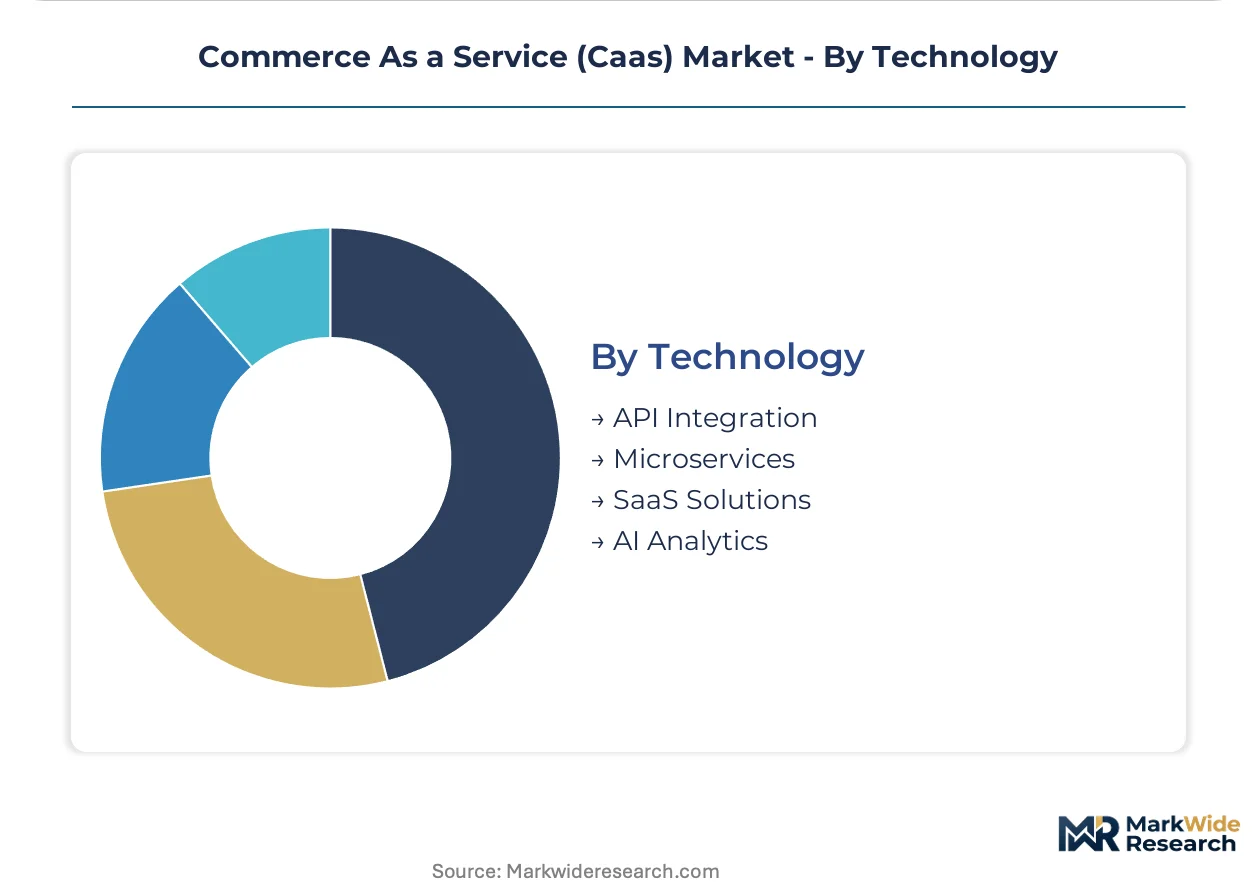
Technology:
Integration architecture maturity separates established API standards from emerging inference capabilities that trigger new compliance obligations.
- API Integration:RESTful and GraphQL interfaces enabling modular service composition. This layer leads technology adoption across all geographies, with India's ONDC protocol mandating interoperable entry points that reshape vendor certification priorities for foreign platform providers.
- AI Analytics:Machine learning pipelines for dynamic pricing, product recommendations, and demand forecasting. EU AI Act risk-tiered obligations for automated decision-making force vendors to re-architect these systems around human-in-the-loop checkpoints, diverting R&D resources toward audit infrastructure.
- Microservices:Containerized service meshes enabling independent deployment and scaling.
- SaaS Solutions:Pre-configured commerce applications with limited customization flexibility.
API Integration commands the largest installed base; AI Analytics faces the most rapid regulatory-forced restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates direct-to-consumer checkout infrastructure investment, while Germany anchors European compliance-driven procurement for hybrid cloud deployments. Divergent regulatory timelines between these jurisdictions reshape vendor certification priorities and client selection criteria.
United States
Direct-to-consumer brands in wellness and pet categories drive subscription-native checkout adoption. PCI DSS 4.0 mandates from the Federal Trade Commission's enforcement framework push retailers toward outsourced tokenization. Urban micro-fulfillment networks in Los Angeles and New York Metro densify real-time inventory API demand.
Germany
Mid-market retailers prioritize GDPR-compliant hybrid architectures balancing latency against data sovereignty. The EU AI Act's risk-tiered obligations force re-architecting of dynamic pricing engines around human-in-the-loop checkpoints. Industrial commerce clusters in Bavaria and North Rhine-Westphalia pilot carbon accounting integration for CSRD scope 3 disclosures.
India
The ONDC protocol mandates interoperable APIs, creating standardized entry points for foreign platform providers. RBI guidelines on payment tokenization accelerate outsourcing of compliance infrastructure. Bangalore and Mumbai technology corridors concentrate startup adoption of modular checkout primitives.
United Kingdom
Post-Brexit regulatory divergence complicates cross-border transaction processing for retailers serving EU consumers. The Financial Conduct Authority's open banking standards enable embedded finance convergence at checkout. London's fintech density supports banking-as-a-service API integration with commerce infrastructure.
Japan
Consumer goods companies modernize from legacy monolithic stacks toward microservice meshes. METI guidelines on data free flow with trust shape cross-border deployment architectures. Tokyo-Osaka industrial corridors concentrate demand for real-time inventory synchronization across distributed fulfillment nodes.
Commerce As a Service (Caas) Market Vendor Landscape
Top-tier vendors anchor hyperscale infrastructure provisioning, while specialized platform providers occupy modular service niches. The market structure concentrates around database heritage players, cloud-native integrators, and API-first commerce specialists. Three archetypes dominate: enterprise legacy extenders, hyperscale infrastructure controllers, and modular checkout orchestrators. Competitive dynamics center on Azure-native ERP workflow integration and edge-deployed inference capabilities.
Within the enterprise legacy extender tier, Oracle Corporation and International Business Machines Corporation occupy positions anchored by high-availability database deployments. Microsoft Corporation exemplifies the cloud-native integrator archetype through Azure-native extension into ERP and CRM workflows. Amazon Web Services, Inc. represents the hyperscale infrastructure controller, shaping downstream pricing through cost curve control.
| Leading Market Players |
|---|
| Oracle Corporation |
| Hewlett Packard Enterprise Development LP |
| Alibaba Cloud |
| Rackspace Hosting, Inc. |
| International Business Machines Corporation |
| Dell Technologies Inc. |
| Google LLC |
| Microsoft Corporation |
| Amazon Web Services, Inc. |
| Others |
Supply Flow & Price Mechanics
Mid-market retailers' migration from legacy monolithic stacks to modular API-first architectures is compressing vendor selection cycles and forcing hyperscale infrastructure providers to recalibrate service bundling. This procurement shift concentrates buying power among direct-to-consumer brands seeking consumption-based pricing, eroding margin buffers for providers lacking Azure-native ERP integration or edge-deployed inference capabilities.
Pricing Analysis
Capacity additions in the United States are reshaping price floors for public cloud deployments as AWS, Azure, and Google Cloud expand data center footprints. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation hinging on PCI DSS 4.0 certification tier and latency guarantees for real-time inventory APIs. Cost compression in the standard tier is intensifying because hyperscale providers are cross-subsidizing compute to capture downstream payment processing volumes. Direct-to-consumer brands in wellness and pet categories show the highest price sensitivity, while enterprise retailers with GDPR obligations accept premium hybrid cloud rates.
Supply Chain Analysis
Cloud infrastructure talent scarcity in India and Ireland is constraining delivery timelines for API gateway deployments and edge node provisioning. The supply chain draws from the United States, Germany, and India for hyperscale data center equipment, specialized tokenization hardware, and micro-fulfillment robotics. Raw material dependencies span advanced semiconductors for inference accelerators, lithium-ion cells for edge server backup power, and rare earth elements for networking components. Single-source vulnerability concentrates in AWS's infrastructure-layer provisioning, which shapes downstream pricing for multi-region deployments. Distribution runs through direct enterprise sales teams and hyperscale marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where procurement committees now prioritize EU AI Act-compliant architectures over feature velocity, rewarding vendors with pre-certified human-in-the-loop pipelines.
For Market Incumbents: Cement hybrid cloud positioning by acquiring regional data center operators in Germany to satisfy GDPR territorial scope requirements. Deepen API integration moats through exclusive partnerships with India's ONDC protocol implementers before foreign platform providers standardize entry points. The threat of embedded finance convergence at checkout demands defensive moves into banking-as-a-service licensing. For New Entrants and Emerging Players: Capture carbon accounting integration modules for EU CSRD scope 3 disclosure workflows, the most penetrable white-space as industrial commerce clusters in Bavaria pilot emissions-tracking APIs. Target mid-market United States retailers abandoning Oracle and IBM legacy extenders with subscription-native checkout primitives that handle dunning and pause mechanics. A vertical go-to-market through pet and wellness direct-to-consumer brands minimizes competitive head-to-head with hyperscale infrastructure controllers. For Investors and Strategic Acquirers: Asymmetric upside sits with modular checkout orchestrators possessing pre-built EU AI Act documentation infrastructure and audit trail capabilities. The five-to-ten-year viability window favors acquisition targets with captive edge-deployed machine learning inference rather than centralized cloud dependencies. Watch for PCI DSS 4.0 enforcement acceleration by the FTC as the inflection signal that triggers consolidation among tokenization specialists lacking outsourced compliance scale.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure-native ERP workflow extension captures mid-market retailers abandoning monolithic stacks. |
| Acquisition of Specialist Firm | Carbon accounting API providers gain enterprise relevance under EU CSRD scope 3 mandates. |
| Geographic Expansion | German hybrid cloud deployments satisfy GDPR data-sovereignty constraints for European retailers. |
| Product Launch | Subscription-native checkout flows displace cart-and-checkout patterns in United States wellness categories. |
| Strategic Partnership | ONDC protocol alignment creates standardized entry points for foreign providers in India. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with CTOs at direct-to-consumer brands, IT procurement officers at mid-market retailers, platform engineers at e-commerce SaaS providers, and integration specialists at systems integrators with secondary validation against SEC filings from hyperscale providers, RBI guidelines on payment tokenization, EU AI Act regulatory texts, and ONDC protocol documentation. Bottom-up service-type demand modeling and top-down macroeconomic anchoring were triangulated for consistency.
Historical reference periods spanning pre-pandemic baselines through post-PCI DSS 4.0 announcement windows anchored the projection horizon across service type, deployment model, end user, and technology segmentation dimensions. CAGRs were derived from fitted growth curves calibrated to documented vendor revenue disclosures and procurement cycle compression patterns observed in United States mid-market retail. Forecast inputs incorporated urban micro-fulfillment network densification rates and EU AI Act compliance investment diversion from R&D to audit infrastructure.
Regulatory timeline divergence, hyperscale capacity expansion delays, and mid-market retailer bankruptcy waves are the dominant revision risks to modeled trajectories. Forecasts reflect documented assumptions about procurement committee behavior and compliance cost pass-through elasticity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Catalog Management Systems Market
Software & Services
Global API Management Software Market
Software & Services
Global Online Expense Management Software Market
Software & Services
Global CMDB Software Market
Software & Services
Global Cloud Testing Market
Software & Services
Global Pharmaceutical Manufacturing Software Market
Software & Services
Sports Production Software Market
Software & Services
Home Fitness App Market
Software & Services
Smartphone Applications Market
Software & Services
Global Building Information Modeling (BIM) Software Market
Software & Services
Europe Integration Platform As a Service Market
Software & Services
Global Appointment Reminder Software Market
Software & Services
Asia-Pacific Text to Speech (TTS) Software Market
Software & Services
Enterprise Search Software Market
Software & Services
Global Restaurant POS Software Market
Software & Services
Hadoop Market