
 Digital Rights Management (DRM) Market | 2026-2036
Digital Rights Management (DRM) Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Rights Management (DRM) Market Outlook
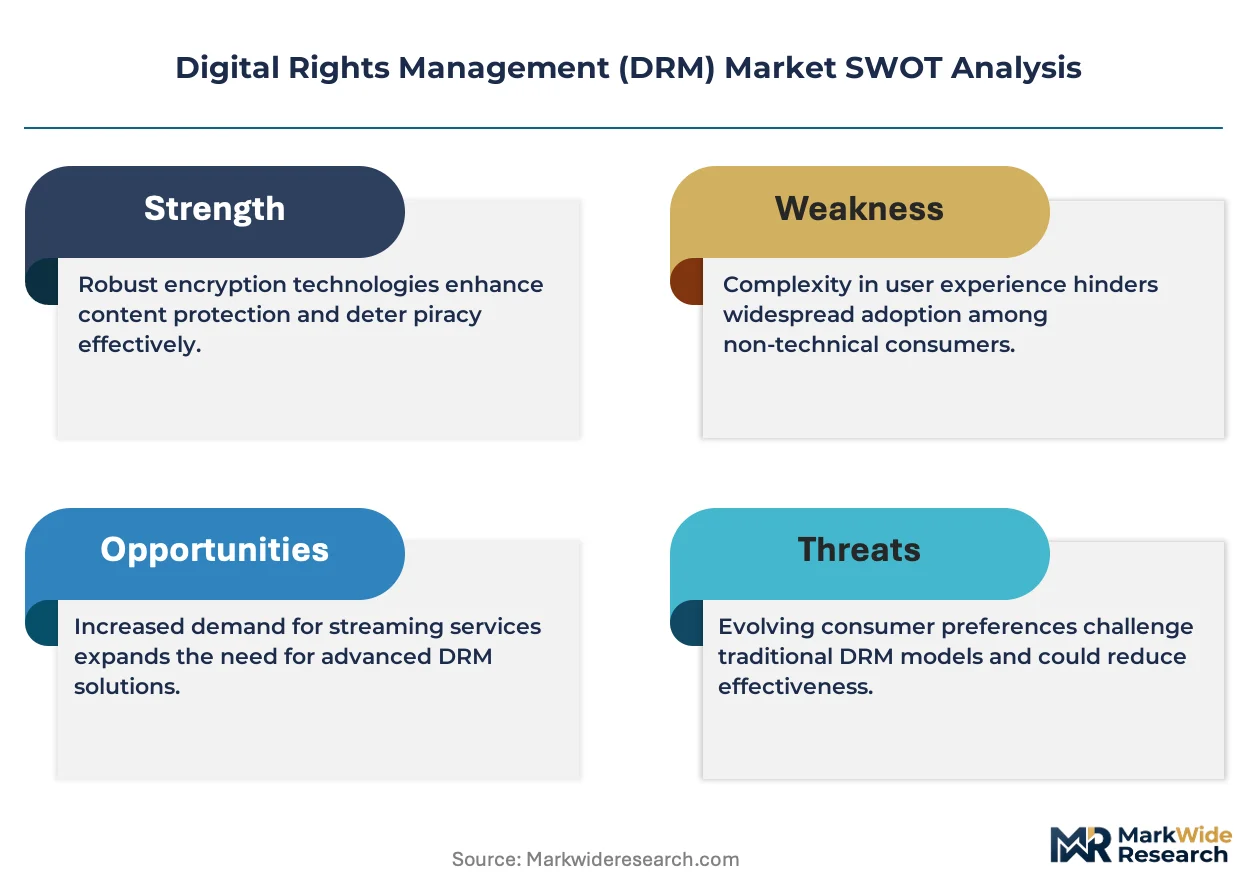
The EU AI Act is realigning how content platforms authenticate and track intellectual property across automated distribution pipelines. Microsoft Corporation leverages its Azure Purview architecture to embed compliance-ready governance layers for European media clients. Adobe anchors its competitive stance through deep Creative Cloud integration with document security protocols. Intertrust Technologies Corporation specializes in hardware-agnostic trust frameworks that span connected television and automotive infotainment ecosystems.
Digital Rights Management encompasses cryptographic access control, persistent content identification, and policy enforcement mechanisms that govern the reproduction, modification, and distribution of digital assets across authorized endpoints. Encryption modules within DRM stacks typically employ AES-128 or AES-256 cipher suites with key rotation intervals calibrated to content sensitivity tiers, while watermarking overlays forensic identifiers imperceptible to consumers but extractable by forensic tools for leak tracing. Cloud-based deployment commands the largest revenue share as studios and publishers migrate license servers away from capital-intensive on-premise data centers toward elastic infrastructure that scales with release-window traffic spikes. Media application verticals generate the densest margin pools, with live sports and day-and-date film releases commanding premium authentication tiers that dwarf standard software licensing economics.
The U.S. Digital Millennium Copyright Act, the EU's Copyright Directive Article 17 upload-filter mandates, and China's GB/T standards for digital publication security collectively shape product roadmaps and market access conditions for DRM vendors seeking cross-border deployment. Japan's METI guidelines for content protection in 4K and 8K broadcasting further tighten technical specifications for hardware-software trust boundaries. Stakeholders must monitor how fragmented national anti-circumvention statutes interact with platform liability regimes when architecting multi-territory license orchestration systems.
Market Dynamics
Streaming platforms and cloud-native distribution pipelines are compressing authentication cycles from weeks to hours, forcing DRM vendors to abandon static license servers in favor of elastic, API-first architectures that synchronize with release-window traffic spikes.
Growth Catalysts
- EU AI Act compliance mandates:Content platforms serving European audiences must embed automated provenance tracking for AI-generated media, expanding demand for forensic watermarking and cryptographic audit trails.
- Live sports streaming surge:Broadcasters in the United States, Germany, and Japan are deploying premium authentication tiers for 4K and 8K real-time distribution, creating dense margin pools beyond standard software licensing.
- Automotive infotainment expansion:Connected vehicle ecosystems require hardware-agnostic trust frameworks that span dashboard displays, rear-seat entertainment, and over-the-air content updates.
Market Restraints
- Encryption key management costs:AES-256 cipher suites with rotating key intervals demand specialized cryptographic hardware that inflates operational expenditure for mid-tier publishers.
- Fragmented anti-circumvention statutes:The U.S. Digital Millennium Copyright Act, EU Copyright Directive Article 17, and China's GB/T standards create conflicting compliance obligations that slow multi-territory deployments.
- Open-source codec substitution:AV1 and other royalty-free video standards reduce reliance on proprietary DRM-encrypted pipelines for non-premium content tiers.
Strategic Opportunities
- India's OTT regulatory maturation:TRAI content protection guidelines for streaming platforms create first-mover advantages for vendors establishing localized license orchestration infrastructure.
- Blockchain-anchored provenance:Distributed ledger integration with forensic watermarking is automating royalty attribution across fragmented distribution chains.
- Medical imaging DRM:HIPAA-compliant access control for DICOM files represents an underpenetrated vertical with strict audit requirements and premium pricing tolerance.
Industry Challenges
- Legacy on-premise migration friction:Studios with capital-intensive data center investments face integration complexity when transitioning license servers to elastic cloud infrastructure.
- Forensic analyst talent scarcity:Specialized skills combining steganography, signal processing, and legal evidence handling command premium compensation that strains vendor margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Rights Management (DRM) Market |
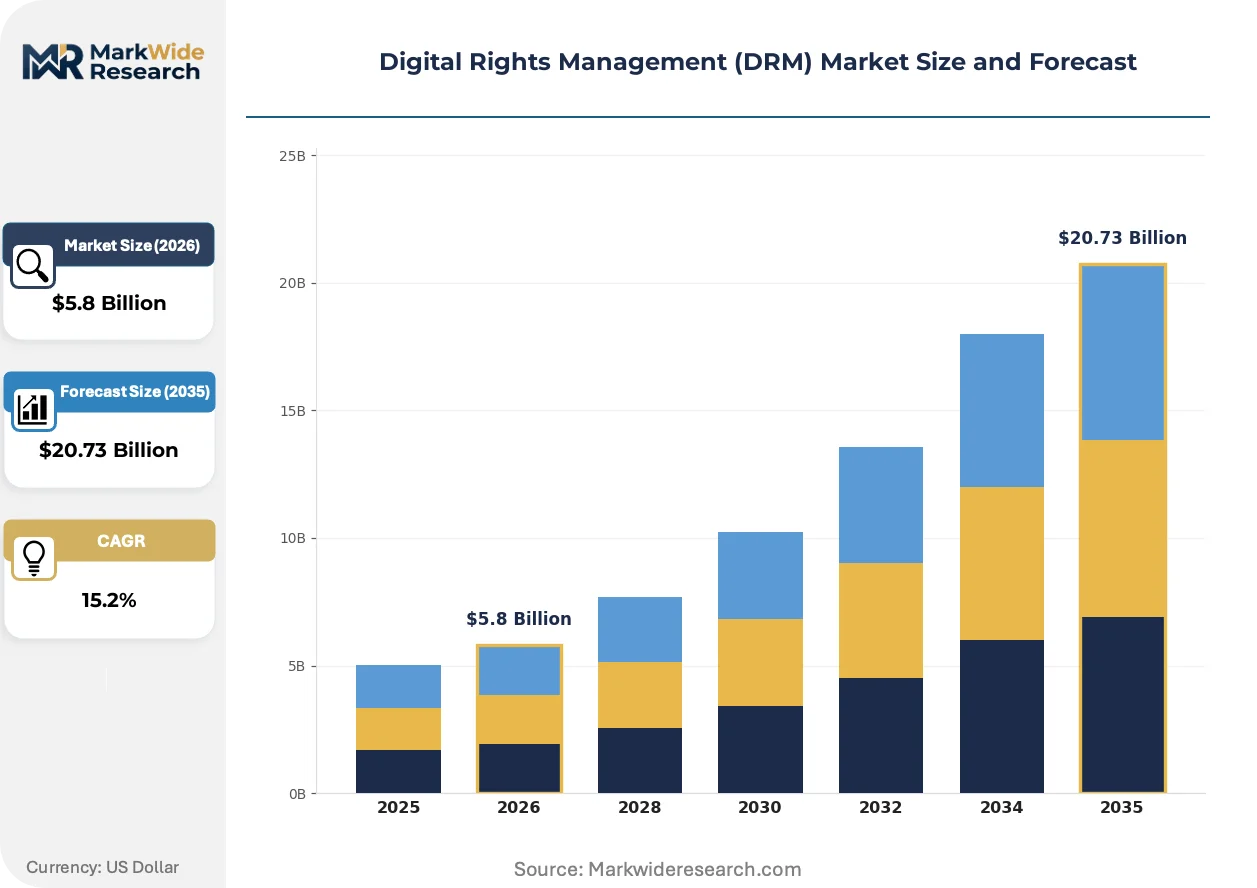
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $20.73 Billion |
| CAGR (2026 – 2036) | 15.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Encryption, Watermarking, Tokenization, Licencing Management Application: Consumer Electronics, Software, Media, E-Books Deployment: Cloud-Based, On-Premise, Hybrid, Open Source End User: Media Companies, Software Developers, Educational Institutions, Content Creators |
| Companies Covered | Oracle Corporation, IBM, Adobe, Seclore, Intertrust Technologies Corporation, Microsoft Corporation, Apple, Fortra, LLC, Google LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Rights Management (DRM) Market Strategic Shifts
Machine learning is compressing the gap between content ingestion and authenticated distribution, enabling real-time policy enforcement that adapts to viewer location, device trust level, and subscription tier without human intervention.
Perceptual hashing combined with neural fingerprinting is automating content identification across re-encoded, cropped, and filtered variants that evade traditional cryptographic detection. Major studios in Los Angeles and London are deploying these systems for pre-release leak tracing. The technology is automating forensic workflows that previously required manual analyst review of suspected infringement.
Japan's METI guidelines for 4K and 8K broadcasting are mandating hardware-software trust boundaries that exceed baseline international standards. Domestic electronics manufacturers must embed tamper-resistant secure elements in television chipsets. Premium content licensors in Tokyo are now requiring METI-compliant certification as a condition for day-and-date theatrical windowing.
Subscription fatigue among streaming consumers is fragmenting demand across ad-supported tiers, transactional rentals, and bundled aggregator platforms. Studios in Burbank are unbundling DRM authentication from all-you-can-eat subscriptions, selling discrete access credits through retail channels. This behavioral shift is most visible in the United States, where churn rates exceed twenty percent annually for standalone services.
Digital Rights Management (DRM) Market Segmentation
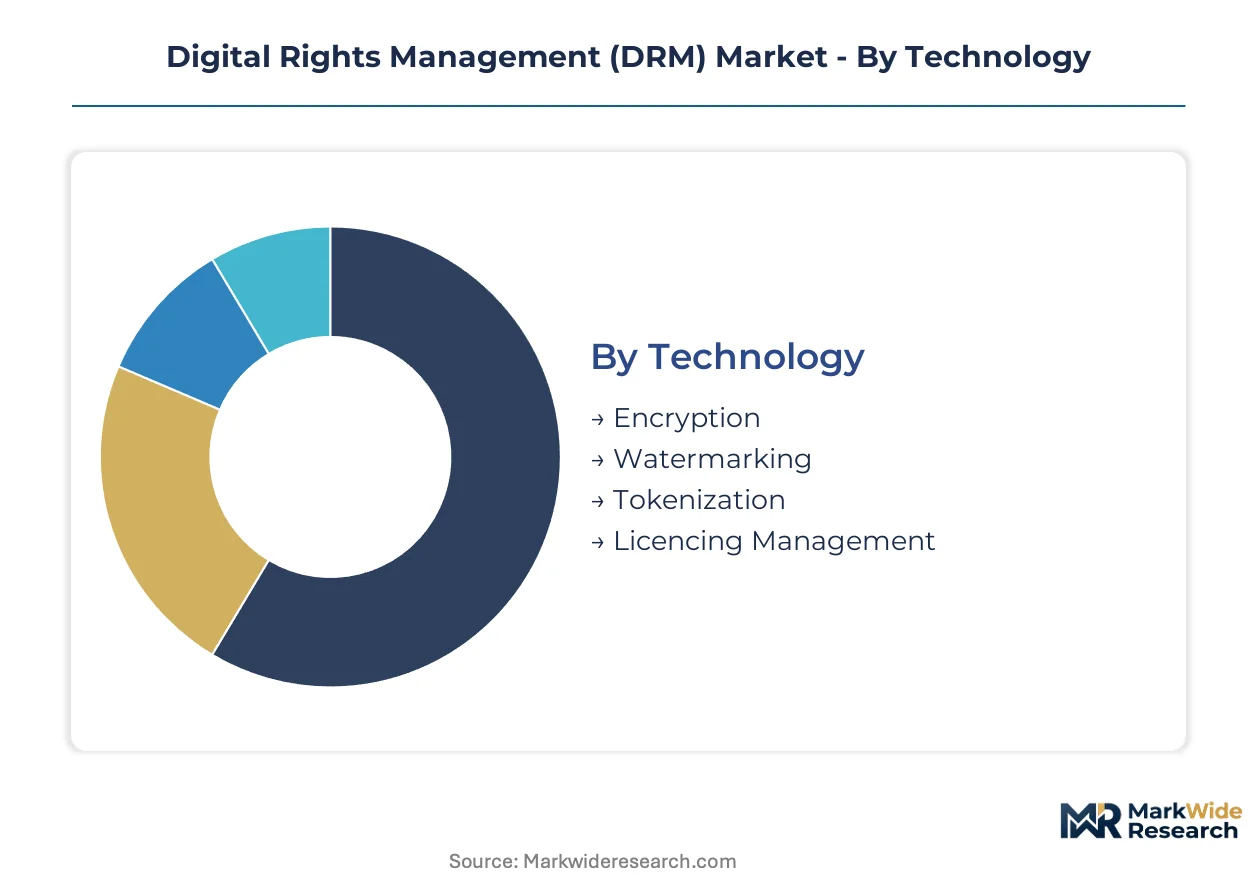
DRM architectures fragment across integration depths, from standalone license servers to embedded silicon trust zones. Each segmentation axis reveals distinct margin structures and vendor specialization patterns that determine competitive positioning.
Technology:
Encryption modules operate as either standalone security layers or deeply embedded chipset functions, with integration depth determining operational overhead and forensic granularity.
- Encryption:AES-128 and AES-256 cipher suites form the cryptographic backbone, with key rotation intervals calibrated to content sensitivity tiers. Studios in Los Angeles and London demand hardware-security-module integration for pre-release theatrical windows, where breach consequences carry nine-figure revenue exposure.
- Watermarking:Forensic steganography overlays imperceptible identifiers extractable by specialized tools for leak tracing. Broadcasters in Japan and Germany deploy these systems for live sports distribution, where real-time piracy response windows compress to minutes.
- Tokenization:Session-based access credentials decouple authentication from persistent identity storage.
- Licencing Management:Policy orchestration engines govern entitlement enforcement across fragmented device ecosystems.
Volume placements concentrate in Encryption; the faster expansion belongs to Watermarking.
Application:
End-use contexts span consumer-facing hardware to enterprise software ecosystems, with each vertical imposing distinct latency and certification requirements.
- Media:Video streaming platforms and broadcast distribution pipelines command premium authentication economics. Day-and-date theatrical releases and live sports in the United States, Germany, and Japan drive dense margin pools that dwarf standard software licensing.
- Consumer Electronics:Television chipsets, automotive infotainment systems, and mobile devices embed hardware-agnostic trust frameworks. METI guidelines in Japan mandate tamper-resistant secure elements for 4K and 8K broadcasting certification.
- Software:Application code protection and API access control for enterprise deployments.
- E-Books:Document encryption with device-specific rendering restrictions for educational and trade publishing.
Revenue concentration sits with Media; Consumer Electronics climbs fastest on connected vehicle and smart display proliferation.
Deployment:
Infrastructure choices reflect capital intensity tolerance and traffic predictability, with migration patterns revealing studio risk appetites.
- Cloud-Based:Elastic license servers scale with release-window traffic spikes, replacing capital-intensive data center investments. Major studios in Burbank and London have accelerated migration post-pandemic, driven by variable cost structures and geographic redundancy requirements.
- Hybrid:Split architectures retain sensitive key material on-premise while offloading authentication traffic to elastic infrastructure. Publishers in Frankfurt and Tokyo favor this model for GDPR and domestic data sovereignty compliance.
- On-Premise:Dedicated hardware for maximum control over cryptographic material.
- Open Source:Community-maintained alternatives reducing licensing overhead for non-premium content tiers.
Customer migrations favor Cloud-Based; Hybrid deployments gain share fastest among compliance-sensitive European and Japanese licensors.
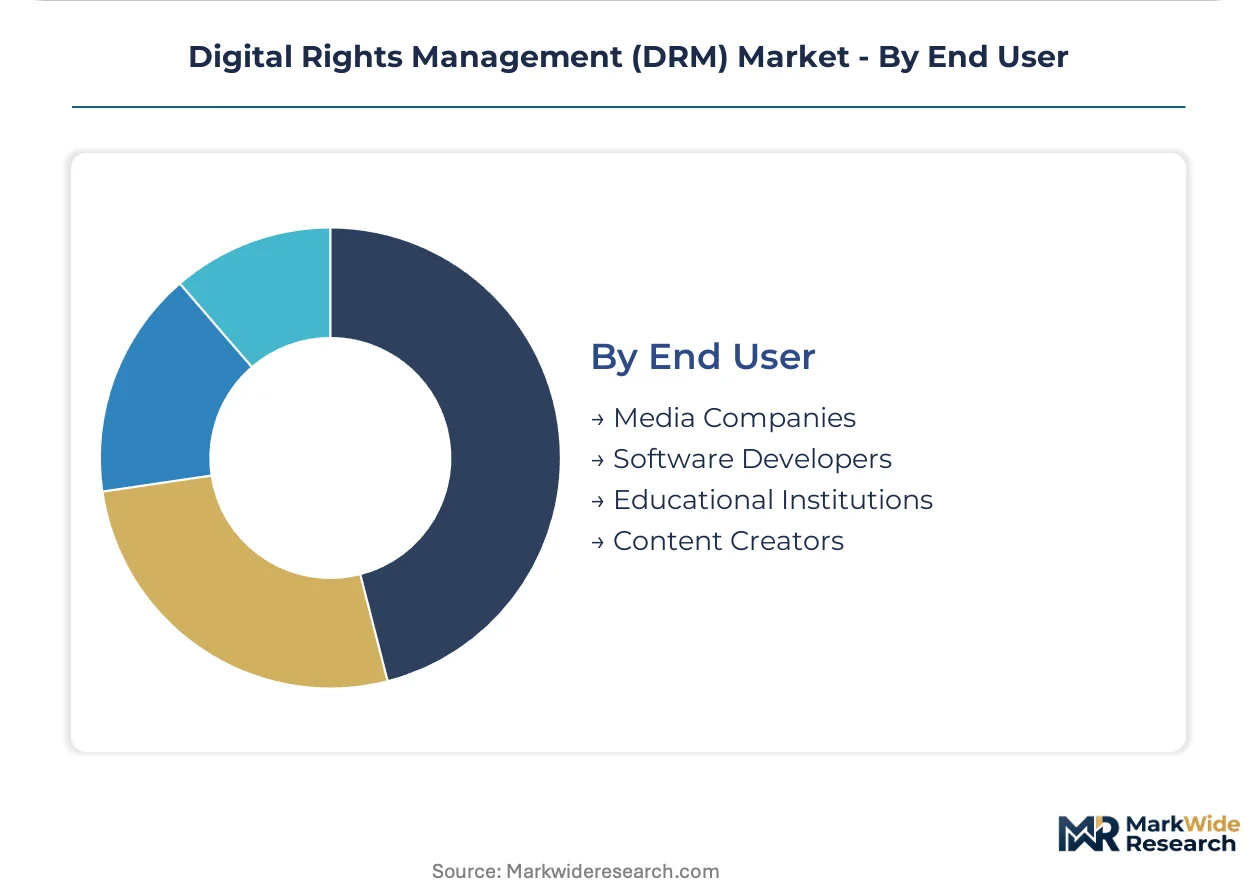
End User:
Organizational scale and content velocity dictate solution complexity, from individual creator tools to enterprise orchestration platforms.
- Media Companies:Studios, broadcasters, and streaming platforms operate the most demanding authentication pipelines. Live sports distributors in the United States and Germany deploy premium tiers with sub-second failover and forensic watermarking for 4K real-time distribution.
- Content Creators:Individual producers and independent studios require lightweight, API-first protection without enterprise overhead. YouTube and TikTok creators in Los Angeles and Mumbai drive demand for automated, self-service licensing tools.
- Software Developers:Application publishers protecting code integrity and subscription entitlements.
- Educational Institutions:Campus-wide access control for digital course materials and research repositories.
Contract value concentrates with Media Companies; Content Creators expand most quickly on creator-economy platform growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates the largest consumption base for DRM solutions, while production gravity centers on cloud infrastructure clusters in Virginia, Washington state, and Ireland. European regulatory pressure from GDPR and the EU AI Act accelerates compliance investment faster than organic demand growth alone would predict.
United States
Hollywood studios in Burbank and Los Angeles deploy premium authentication tiers for day-and-date theatrical releases, compressing license orchestration cycles to hours. The Digital Millennium Copyright Act shapes vendor product roadmaps through strict anti-circumvention enforcement. Seattle-based cloud providers anchor elastic license server infrastructure that scales with release-window traffic spikes.
Germany
Frankfurt broadcasters and Munich automotive OEMs drive demand for hardware-agnostic trust frameworks spanning infotainment and connected vehicle ecosystems. The EU Copyright Directive Article 17 upload-filter mandates force platform liability recalibration. Berlin studios favor hybrid deployments retaining sensitive key material on-premise while offloading authentication traffic to elastic infrastructure.
Japan
Tokyo-based premium content licensors require METI-compliant certification for 4K and 8K broadcasting day-and-date theatrical windowing. METI guidelines mandate tamper-resistant secure elements in television chipsets that exceed baseline international standards. Osaka electronics manufacturers embed these hardware-software trust boundaries across connected television and automotive display ecosystems.
India
Mumbai streaming platforms and Bengaluru OTT infrastructure providers respond to TRAI content protection guidelines for maturing regulatory frameworks. The TRAI guidelines create first-mover advantages for vendors establishing localized license orchestration infrastructure. Hyderabad cloud data centers host elastic authentication pipelines serving South Asian content distributors.
United Kingdom
London broadcasters and post-production houses in Soho deploy forensic watermarking for live sports distribution with real-time piracy response windows compressing to minutes. The UK Information Commissioner's Office enforces GDPR-aligned data sovereignty requirements for cross-border license orchestration. Manchester media technology clusters specialize in API-first architectures for mid-tier publishers migrating from capital-intensive data centers.
Digital Rights Management (DRM) Market Competitive Environment
The competitive structure tilts toward cloud-native platform providers with embedded security stacks. Consolidation pressure concentrates around vendors offering elastic, API-first architectures that synchronize with release-window traffic spikes. Three archetypes dominate: hyperscale cloud platforms with native DRM modules, specialized trust framework vendors with hardware-agnostic positioning, and creative software suites with deep document security integration. Competitive moves center on strategic partnerships with streaming platforms and portfolio diversification into automotive infotainment and medical imaging verticals.
Within the cloud-platform tier, Microsoft Corporation and Google LLC represent the scale-driven integration model, anchoring elastic infrastructure that replaces on-premise license servers. Adobe occupies a position exemplifying creative-suite embedding, while Intertrust Technologies Corporation sits within the specialized trust framework archetype for hardware-agnostic deployment across connected television and automotive ecosystems. Oracle Corporation and IBM represent enterprise software incumbents extending security portfolios into content protection, with Apple anchoring the vertically integrated device-and-service stack model.
| Leading Market Players |
|---|
| Oracle Corporation |
| IBM |
| Adobe |
| Seclore |
| Intertrust Technologies Corporation |
| Microsoft Corporation |
| Apple |
| Fortra, LLC |
| Google LLC |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up trust framework specialists anchor supply-side discipline through serial consolidation of cryptographic hardware vendors, translating fragmented component sourcing into centralized pricing power over AES-256 module procurement for Hollywood studios and Tokyo broadcasters.
Pricing Analysis
Margin tightening in premium authentication tiers reflects hardware-security-module integration mandates from Japan's METI and the EU AI Act, forcing studios to absorb specialized cryptographic silicon costs. Three-tier pricing structure across premium, standard, and economy levels separates day-and-date theatrical releases with forensic watermarking from mid-tier streaming catalogs and basic software licensing. Cost compression in economy tiers accelerates because open-source codec substitution erodes proprietary pipeline dependence. Mid-tier publishers exhibit acute price sensitivity, while live sports distributors in the United States and Germany tolerate premium pricing for sub-second failover guarantees.
Supply Chain Analysis
Refurbishment flows for cryptographic hardware security modules cycle through certified facilities in Taiwan and South Korea before re-entry into European and Japanese broadcast infrastructure. Taiwan, South Korea, and the United States concentrate fabrication of tamper-resistant secure elements. AES-256 cipher cores, forensic watermarking ASICs, and cloud GPU clusters for real-time authentication draw from these manufacturing hubs. Single-source vulnerability in advanced node semiconductor fabrication concentrates risk. Distribution runs through hyperscale cloud provider marketplaces and direct enterprise licensing agreements with major studios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act erects a cost-of-compliance barrier that favors incumbent vendors with pre-existing forensic watermarking and cryptographic audit trail infrastructure, locking out undercapitalized entrants lacking automated provenance tracking capabilities.
For Market Incumbents:Acquire specialized forensic watermarking boutiques in London and Los Angeles to consolidate leak-tracing capabilities before open-source neural fingerprinting matures. Expand hardware-agnostic trust framework coverage into automotive infotainment through backward integration with Tier 1 display suppliers. Patent thickets around perceptual hashing algorithms provide defensive moats against codec substitution threats.
For New Entrants and Emerging Players:Enter via India's TRAI-mandated content protection guidelines, where localized license orchestration infrastructure remains underdeveloped and first-mover advantages persist. Target medical imaging verticals with HIPAA-compliant DICOM access control, an underpenetrated segment with premium pricing tolerance and strict audit requirements. Partner with Hyderabad cloud data centers for South Asian market entry rather than competing directly with hyperscale incumbents.
For Investors and Strategic Acquirers:Distressed-cycle entries favor specialized trust framework vendors with hardware-agnostic positioning in Japan and Germany, where METI and GDPR compliance investments create sticky customer relationships. Long-term viability hinges on automotive infotainment and medical imaging diversification beyond media verticals. Monitor AV1 codec adoption rates in non-premium content tiers as an inflection indicator for proprietary DRM pipeline displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding Azure Purview governance layers secures European media clients against EU AI Act penalties. |
| Acquisition of Specialist Firm | Consolidating forensic watermarking boutiques concentrates leak-tracing capabilities in Los Angeles and London. |
| Geographic Expansion | Establishing Hyderabad license orchestration infrastructure captures India's TRAI-mandated content protection demand. |
| Product Launch | Releasing HIPAA-compliant DICOM access control penetrates medical imaging's premium-priced audit requirements. |
| Strategic Partnership | Aligning with Tier 1 automotive display suppliers extends hardware-agnostic trust frameworks into infotainment. |
Study Parameters
SEC filings from hyperscale cloud providers, EMA regulatory submissions, and Japan's METI certification databases formed the secondary backbone, cross-referenced against primary interviews with DRM platform engineers, streaming service CTOs, Hollywood studio security architects, and automotive infotainment procurement leads. Bottom-up and top-down triangulation validated segment-level assumptions through hyperscaler capex disclosures and customs records for cryptographic hardware imports.
Bottom-up modeling anchored volume projections to individual license server deployments and authentication transaction volumes, while top-down constraints drew from aggregate cloud infrastructure spending patterns across the analysis window. Segmentation dimensions spanned deployment model, content sensitivity tier, integration depth, and regional regulatory cluster. CAGRs derived from license orchestration cycle compression rates and migration patterns from on-premise to elastic infrastructure.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated AV1 codec substitution or fragmented anti-circumvention statute harmonization failures. Practitioners should monitor open-source neural fingerprinting maturity and India's TRAI enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Revops Platform Market
Digital Solutions
Green IT Services Market
Digital Solutions
Data Pipeline Market
Digital Solutions
Container Management Software Market
Digital Solutions
Car Wash Management System Market
Digital Solutions
Human Resource (HR) Technology Market
Digital Solutions
India Engineering Research and Development (ER&D) Services Market
Digital Solutions
Thin Client Market
Digital Solutions
Supply Chain Digital Twin Market
Digital Solutions
Big Data and Data Engineering Services Market
Digital Solutions
Work From Home Setup Market
Digital Solutions
IT Asset Management Market
Digital Solutions
Global Mobile Workforce Management Market
Digital Solutions
Remote Integration Solutions Market
Digital Solutions
Hiking Apps Market
Digital Solutions
Europe Warranty Management System Market