
 Community Forum Market | 2026-2036
Community Forum Market Size, Share, and Industry Trends Forecast 2026-2036
Community Forum Market Outlook
Enterprise customer support is pivoting toward self-service community models as first-line resolution channels. Discourse leverages open-source architecture to sustain developer loyalty across technical user bases. Mighty Networks anchors its position through native course and event layering for creator-led communities.
Community forums are digital platforms enabling structured discussion, content archiving, and member interaction through threaded conversations, moderation tools, and searchable knowledge repositories. These systems operate on cloud or on-premise infrastructure with API extensibility, real-time notifications, and role-based access controls to serve support, education, and affinity group objectives. Hybrid deployments are capturing margin pools as organizations demand both web accessibility and native mobile performance without full SaaS dependency. Subscription monetization leads revenue generation while advertising-supported models face pressure from privacy-compliant targeting constraints across Technology and Education topic areas.
FCC guidelines on digital platform transparency, GDPR data portability mandates, and emerging EU AI Act content classification requirements are tightening accountability for algorithmic moderation and cross-border data flows. Compliance investments are redirecting vendor R&D toward auditable moderation pipelines and regional data residency options. Stakeholders must weigh build-versus-buy decisions against the accelerating specialization of vertical-specific community stacks.
Market Dynamics
Enterprise migration toward self-service resolution channels is compressing traditional ticketing workflows and redirecting platform R&D toward AI-augmented moderation pipelines. Vendors face simultaneous pressure from GDPR portability mandates and emerging algorithmic transparency requirements across multiple jurisdictions.
Growth Catalysts
- SaaS Subscription Models:Recurring revenue structures enable vendors to fund continuous platform development. Enterprise IT budgets are reallocating capital from on-premise licenses to cloud-native community infrastructure.
- GDPR Article 20 Portability:European data portability rules compel organizations to maintain auditable member data exports. Compliance investments are accelerating procurement of platforms with native data residency controls.
- Creator Economy Platforms:Course creators and membership operators require integrated community layers for retention. Native monetization tools are capturing margin pools previously fragmented across separate LMS and forum stacks.
Market Restraints
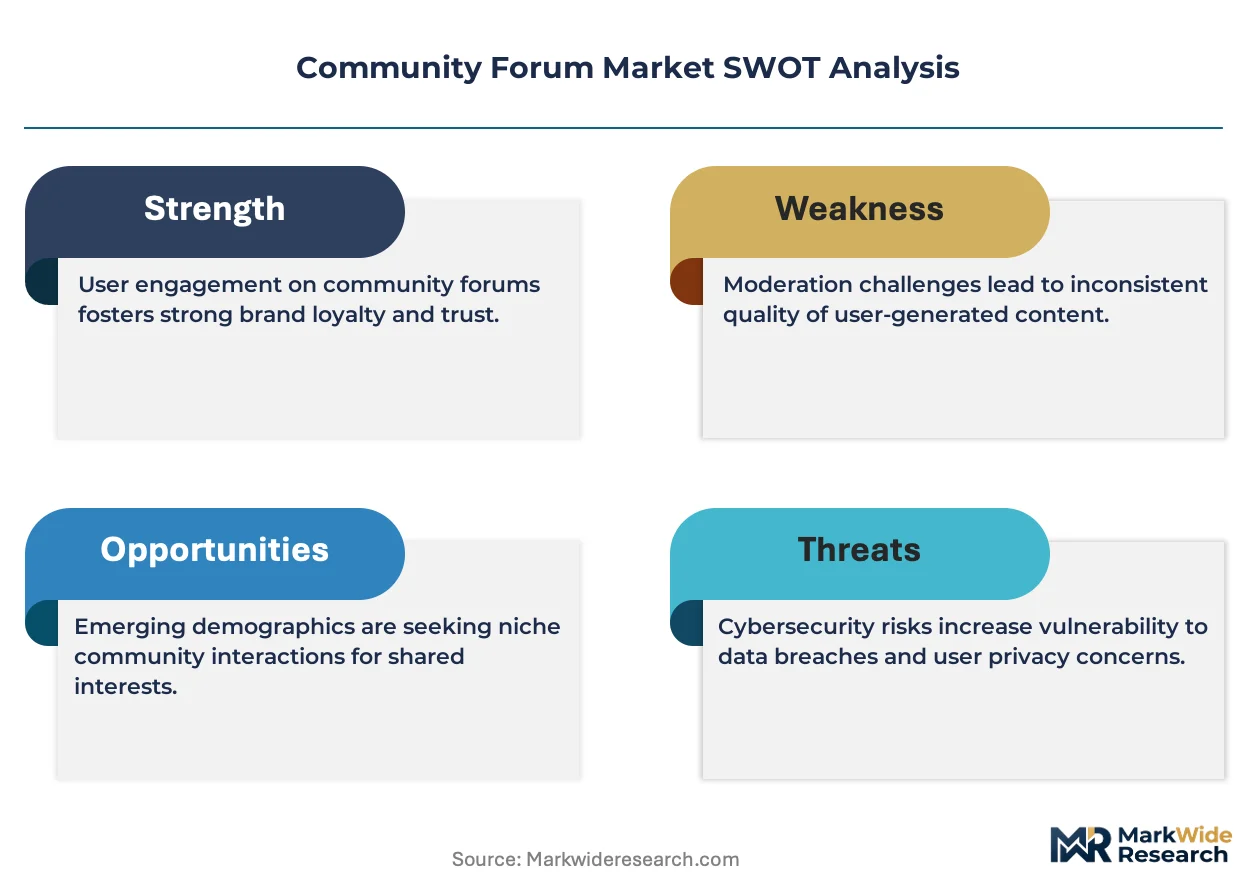
- Cloud Infrastructure Concentration:AWS, Azure, and Google Cloud dominate hosting costs for SaaS community vendors. Regional outages or pricing adjustments transmit directly to platform operating margins.
- Open-Source Substitution:Discourse and Flarum offer self-hosted alternatives with zero licensing fees. Price-sensitive organizations with internal DevOps capacity are diverting procurement toward these options.
- EU AI Act Moderation Requirements:Content classification obligations for algorithmic systems impose compliance overhead. Smaller vendors face disproportionate legal and engineering costs relative to revenue base.
Strategic Opportunities
- India's Digital Public Infrastructure:The country's expanding SaaS ecosystem and English-language creator base present underpenetrated demand. Localization for regional languages unlocks tier-2 city adoption.
- Healthcare Patient Communities:HIPAA-compliant forum architectures address chronic disease management and clinical trial recruitment. Pharmaceutical sponsors are funding branded community deployments for real-world evidence collection.
- Edge-Cloud Hybrid Architectures:Converging CDN distribution with on-premise data residency satisfies financial services compliance. Regional banks are piloting architectures that cache content locally while maintaining centralized moderation.
Industry Challenges
- Trust and Safety Engineering Talent:Scarce expertise in scalable content moderation and adversarial abuse detection constrains platform differentiation. Vendors compete for personnel with major social media operators.
- API Integration Complexity:Legacy CRM and ticketing systems require custom middleware for real-time synchronization. Implementation timelines extend 6-18 months for enterprise deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Community Forum Market |
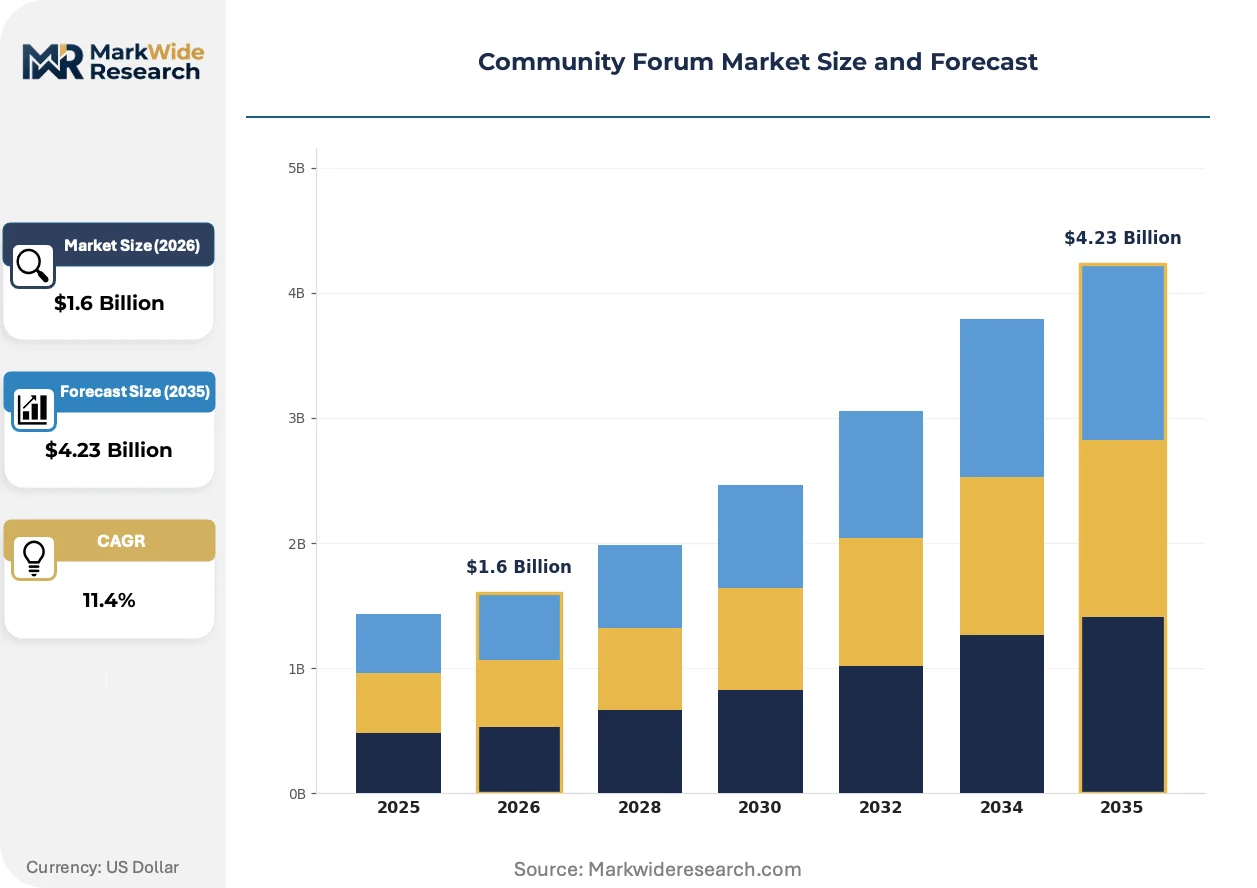
| Market Size in 2026 | $1.6 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Web-based, Mobile Application, Hybrid, Desktop Client User Type: General Users, Experts, Moderators, Administrators Topic Area: Technology, Health, Lifestyle, Education Monetization Model: Subscription, Advertising, Donations, Membership |
| Companies Covered | Discourse, Bettermode, Mighty Networks, EzyCourse, Hivebrite, Circle, Higher Logic Vanilla, Skool, Discord, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Community Forum Market Strategic Shifts
Generative AI capabilities are embedding directly into community workflows, reshaping both member experience architectures and backend operational economics. Three converging developments are determining competitive positioning.
Large language model-powered response drafting is overtaking manual first-line support in technical communities. Developer-focused platforms are deploying these tools to reduce moderator burnout and accelerate resolution times. The structural consequence is compression of traditional tiered support staffing models, with headcount reallocating toward escalation engineering rather than routine query handling.
The EU AI Act's risk-based classification system is mandating algorithmic impact assessments for automated moderation systems. Community platforms deploying AI-driven content filtering must document decision logic and maintain human oversight protocols. North American vendors with European subscriber bases are establishing Dublin and Frankfurt data centers to satisfy regional processing requirements.
Enterprise procurement teams are consolidating vendor relationships by demanding community functionality within existing collaboration suites. Microsoft Teams and Slack integrations are displacing standalone forum subscriptions in mid-market IT budgets. This pattern is most visible in United States technology sector deployments, where platform fatigue is driving preference for unified workspace contracts over specialized point solutions.
Community Forum Market Segmentation
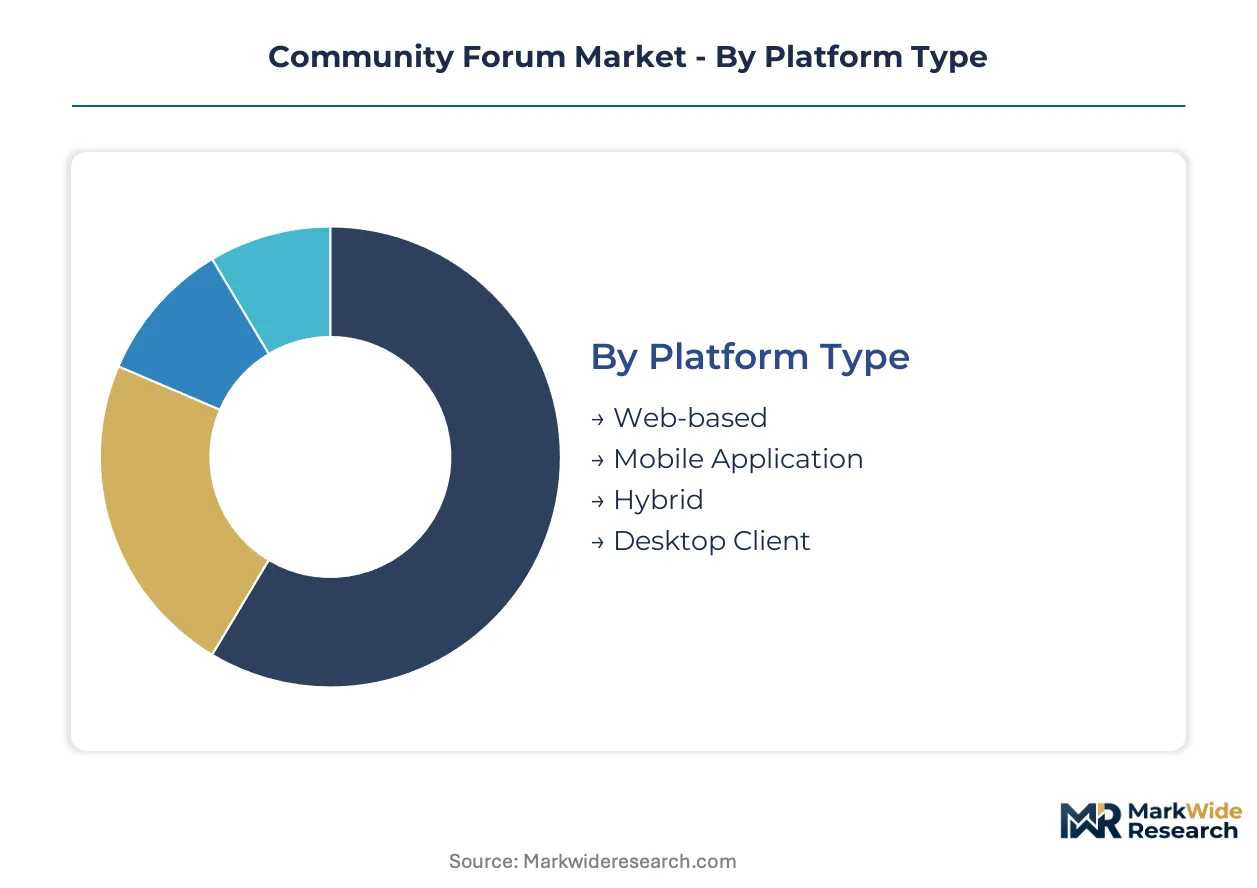
Community forum architectures diverge sharply across deployment modes, user roles, topical focus, and revenue mechanics. Each segmentation axis shapes procurement patterns, compliance obligations, and platform engineering priorities for vendors and enterprise buyers.
Platform Type:
Deployment architecture determines infrastructure costs, mobile performance benchmarks, and data residency compliance pathways for organizations.
- Web-based:Browser-rendered interfaces dominate enterprise support deployments where IT security policies restrict native application installations. United States SaaS vendors prioritize responsive design frameworks to capture mid-market procurement budgets without dedicated mobile development.
- Mobile Application:Native iOS and Android clients command premium subscription tiers from creator economy operators requiring push notification engagement. Course creators and membership communities in the United States drive disproportionate revenue concentration here due to retention-sensitive business models.
- Hybrid:Progressive web applications with offline caching satisfy financial services compliance requirements for local data processing while maintaining centralized moderation pipelines. Regional banks pilot these architectures to cache content locally.
- Desktop Client:Electron-based or native desktop applications persist in developer communities requiring deep IDE integrations and local file system access for technical documentation workflows.
Mature deployment sits with Web-based platforms. Newer deployment is concentrated in Hybrid architectures.
User Type:
Role differentiation shapes permission architectures, moderation tooling investments, and platform pricing tiers across customer segments.
- General Users:Registered members with posting, reaction, and search privileges constitute the volume base for advertising-supported and freemium subscription models. Health topic communities in the United States monetize this segment through pharmaceutical sponsor-funded access.
- Experts:Verified credential holders with elevated visibility algorithms drive knowledge base quality in technical and medical communities. Platform R&D concentrates here to reduce moderator burnout through AI-augmented response drafting.
- Moderators:Community-appointed or platform-employed content curators operate trust and safety workflows including escalation triage and sanction enforcement. GDPR Article 20 portability mandates compel audit trails for moderator decisions affecting member data.
- Administrators:Technical operators with configuration access to theming, integrations, and data export functions represent the procurement decision node for enterprise contracts.
Administrators control procurement budgets. Experts represent the fastest-growing investment priority for platform differentiation.
Topic Area:
Content domain determines regulatory exposure, moderation sensitivity, and monetization viability for community operators.
- Technology:Developer communities around programming languages, DevOps tooling, and open-source projects sustain Discourse and Flarum adoption through technical user loyalty. FCC transparency guidelines and EU AI Act classification requirements reshape algorithmic moderation investments here.
- Health:Patient communities for chronic disease management and clinical trial recruitment require HIPAA-compliant architectures. Pharmaceutical sponsors fund branded deployments for real-world evidence collection in the United States.
- Lifestyle:Hobby, fitness, and interest-based communities monetize through membership subscriptions and affiliate commerce integrations with lower regulatory overhead than health or technology verticals.
- Education:Course cohort discussions and institutional learning communities integrate with LMS stacks. Creator economy platforms capture margin pools previously fragmented across separate forum and courseware systems.
Technology communities anchor open-source platform adoption. Health communities are climbing the fastest due to HIPAA-compliant infrastructure investments.
Monetization Model:
Revenue architecture determines customer acquisition costs, lifetime value calculations, and platform feature roadmaps for vendors.
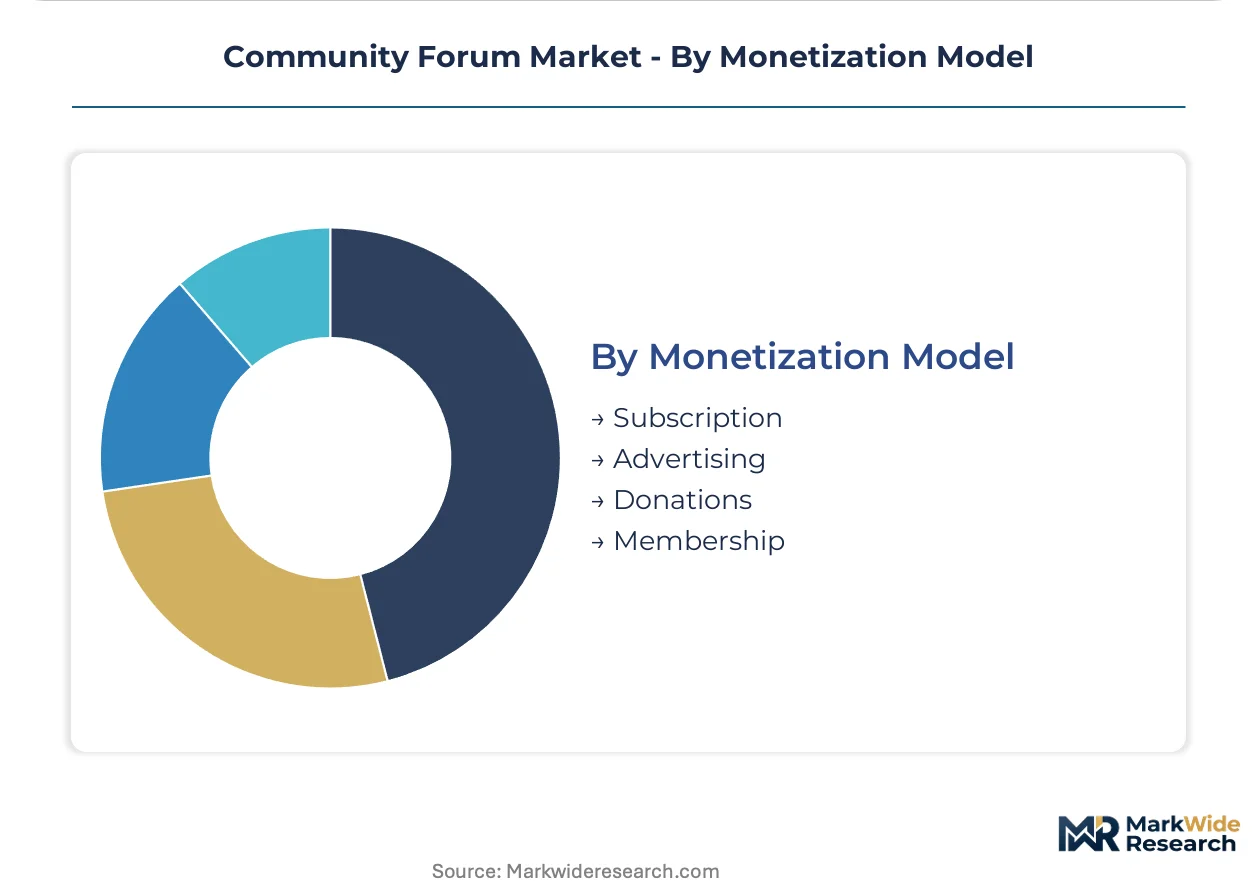
- Subscription:Recurring SaaS fees from community operators fund continuous platform development and enterprise support tiers. United States technology sector procurement teams consolidate vendor relationships around subscription bundles.
- Advertising:Impression and click-based revenue faces compression from privacy-compliant targeting constraints across GDPR jurisdictions and emerging state-level regulations in the United States.
- Donations:Voluntary contribution models sustain niche communities with strong ideological or affinity alignment, particularly in open-source software and advocacy contexts.
- Membership:Tiered access gates with exclusive content, direct creator interaction, and event privileges capture premium pricing from creator economy operators.
Subscription models dominate vendor revenue. Membership tiers are gaining share fastest among creator economy platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Community forum platform production concentrates among SaaS vendors headquartered in the United States, while consumption spreads across enterprise IT budgets in Germany, India, and Japan. This geographic divide shapes data residency investments and localization roadmaps for vendors seeking expansion beyond North American subscriber bases.
United States
Enterprise IT procurement teams in San Francisco and New York Metro drive subscription revenue for cloud-native community platforms. FCC transparency guidelines on digital platform accountability reshape vendor disclosure obligations for algorithmic moderation systems. Austin and Seattle host the densest concentration of SaaS engineering talent developing real-time notification architectures.
Germany
GDPR Article 20 portability mandates compel Munich and Frankfurt-based enterprises to audit member data export capabilities. The country's national data protection authority enforces strict cross-border processing limitations that redirect vendor R&D toward regional data center investments. Berlin's startup ecosystem sustains adoption of open-source alternatives among price-sensitive mid-market buyers.
India
Bangalore and Hyderabad's expanding SaaS workforce generates demand for English-language community platforms serving technical user bases. The country's digital public infrastructure investments unlock tier-2 city adoption through regional language localization. Mumbai's creator economy operators pilot membership-tier monetization for course cohort discussions.
Japan
Tokyo-based enterprises prioritize hybrid deployment architectures satisfying local data processing requirements. METI guidelines on AI system transparency impose documentation standards for automated content classification. Osaka's manufacturing sector sustains niche adoption of desktop-integrated forum clients for technical documentation workflows.
United Kingdom
London's fintech cluster demands edge-cloud hybrid architectures caching content locally while maintaining centralized moderation. The country's data protection framework extends GDPR-equivalent portability requirements to post-Brexit operations. Manchester and Birmingham health systems pilot HIPAA-compliant patient community deployments for chronic disease management.
Community Forum Market Competitive Environment
Top-tier vendors anchor enterprise SaaS subscriptions, while open-source alternatives and creator-economy specialists fragment the mid-market. The vendor base separates into three strategic archetypes: cloud-native incumbents funding continuous platform development, open-source projects capturing DevOps-fluent organizations, and vertical specialists layering native monetization tools for course creators. Dominant competitive moves include geographic expansion through regional data center establishment and portfolio diversification into adjacent collaboration suite integrations.
Within the open-source tier, Discourse exemplifies developer-loyalty strategies sustaining technical user adoption without licensing revenue. Mighty Networks occupies a position among creator-economy specialists, anchoring native course and event functionality for membership operators. Circle represents the SaaS-native archetype, sitting within the premium subscription segment serving branded community deployments.
| Leading Market Players |
|---|
| Discourse |
| Bettermode |
| Mighty Networks |
| EzyCourse |
| Hivebrite |
| Circle |
| Higher Logic Vanilla |
| Skool |
| Discord |
| Others |
Value Chain & Pricing Dynamics
Enterprise procurement consolidation around unified collaboration suites is compressing standalone forum vendor pricing power and forcing infrastructure cost absorption into SaaS margins. Cloud hyperscaler dependency concentrates supply-side leverage among AWS, Azure, and Google Cloud, transmitting hosting cost volatility directly to platform operating economics.
Pricing Analysis
Short lead-time deployment premiums distinguish SaaS-native vendors from self-hosted alternatives requiring DevOps provisioning cycles. Three-tier pricing structure across premium, standard, and economy levels segments by data residency controls, API rate limits, and white-label customization depth. Pricing pressure stems from open-source substitution by Discourse and Flarum among technical user bases with internal infrastructure capacity. Price-sensitive mid-market buyers in Germany and India gravitate toward self-hosted options, while least-sensitive creator economy operators in the United States absorb premium tiers for native monetization tooling.
Supply Chain Analysis
Regional distribution centers for content delivery networks anchor downstream performance, with edge nodes in Frankfurt, Singapore, and Mumbai serving latency-sensitive mobile deployments. Supply concentrates among United States hyperscalers for primary compute, while India and Ireland provide secondary data residency options for GDPR and emerging AI Act compliance. Raw material dependencies include open-source software libraries, LLM inference APIs, and telecommunications bandwidth. Single-source vulnerability sits with AWS dominance in enterprise hosting contracts. Distribution runs through direct vendor sales for enterprise accounts and self-service provisioning for mid-market subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generative AI integration is displacing legacy tiered support staffing models, compressing resolution timelines and redirecting platform R&D toward algorithmic moderation pipelines. Vendors must navigate this transition while satisfying tightening transparency mandates across multiple jurisdictions.
For Market Incumbents: Hedge against open-source erosion by deepening proprietary AI differentiation in automated response drafting and trust-and-safety workflows. Acquire specialized moderation technology teams to defend against talent scarcity constraining platform differentiation. Fortify data residency footprints in Frankfurt and Dublin to preempt EU AI Act compliance displacement. For New Entrants and Emerging Players: Begin with India's tier-2 city creator economy, where English-language platform demand exceeds localized supply and digital public infrastructure unlocks regional language expansion. Target healthcare patient communities in the United Kingdom and United States, where HIPAA-compliant architectures command procurement premiums from pharmaceutical sponsors. Pursue white-label embedding partnerships with existing LMS vendors to bypass direct sales friction. For Investors and Strategic Acquirers: The window for entry favors vertical specialists with native monetization tooling and established creator economy retention metrics. Long-term viability hinges on regulatory compliance automation rather than feature breadth expansion. Watch for EU AI Act enforcement patterns as the inflection signal determining which moderation infrastructure investments translate to sustainable competitive position.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding community functionality within Microsoft Teams and Slack captures mid-market procurement consolidation in United States technology sector. |
| Geographic Expansion | Establishing Frankfurt and Dublin data centers satisfies GDPR Article 20 portability and EU AI Act processing requirements for European subscriber bases. |
| Acquisition of Specialist Firm | Absorbing trust-and-safety engineering teams addresses scarce expertise in scalable content moderation and adversarial abuse detection. |
| Product Launch | Deploying LLM-powered response drafting tools compresses traditional tiered support models and accelerates resolution times in technical communities. |
| Strategic Partnership | Aligning with pharmaceutical sponsors funds HIPAA-compliant patient community deployments for real-world evidence collection in chronic disease management. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with CTOs, IT procurement officers, platform engineers, and integration specialists across SaaS vendor and enterprise buyer organizations. SEC filings, hyperscaler capex disclosures, App Annie mobile engagement metrics, and FCC transparency guideline documentation provided quantitative validation. Bottom-up deployment volume estimates triangulated against top-down subscription revenue analysis across the analysis window.
Data-stream reconciliation across vendor-reported ARR, enterprise IT budget allocations, and mobile application download trends informed the analytical framework. Segmentation dimensions modeled include deployment architecture, user role tier, topical vertical, and monetization mechanism, with regional adoption patterns capturing jurisdiction-specific compliance investments. CAGRs derived from fitted growth curves incorporating SaaS expansion rates, creator economy platform penetration, and healthcare vertical funding cycles.
Underlying measurement precision varies by segment; web-based and hybrid deployment estimates carry tighter precision than emerging edge-cloud architectures. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and hyperscaler pricing stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Voice Remote Control Market
Digital Solutions
Boat Navigation Software Market
Digital Solutions
Supplier Contract Management Market
Digital Solutions
Product Life Cycle Management (PLM) Market
Digital Solutions
Premium Messaging Market
Digital Solutions
Global Correspondence Management System Market
Digital Solutions
Control Room Solutions Market
Digital Solutions
Digital String Encoder Market
Digital Solutions
Global B2B Buyer Intent Data Tools Market
Digital Solutions
Legaltech Market
Digital Solutions
Global Digital Asset Management Software Market
Digital Solutions
End-User Computing (EUC) Market
Digital Solutions
Asia-Pacific API Management Market
Digital Solutions
Asia-Pacific Desktop Virtualization Market
Digital Solutions
US Supply Chain Management Software Market
Digital Solutions
Global Commerce Cloud Solution Market