
 Global Digital Signature Software Market | 2026-2036
Global Digital Signature Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Signature Software Market Foresight
The EU eIDAS regulation is realigning procurement standards for cross-border contract execution across member states. DocuSign leverages its early certification under eIDAS Qualified standards to anchor trust-sensitive European financial workflows. Adobe Sign competes through deep integration with enterprise document management stacks, while airSlate SignNow specializes in mid-market workflow automation with competitive per-seat economics.
Digital signature software comprises cryptographic protocols that bind signatory identity to electronic documents using public-key infrastructure, hash functions, and timestamping services to ensure non-repudiation and integrity verification. Cloud-based deployment leads volume adoption as organizations eliminate on-premises certificate management overhead, while biometric verification within the solution-type layer captures premium pricing from healthcare records and high-value real estate transaction applications where identity assurance thresholds are most stringent.
The EU eIDAS framework, the US ESIGN Act, and India's IT Act collectively establish enforceability standards that determine which platform architectures qualify for government and regulated-industry procurement. FDA 21 CFR Part 11 in the United States imposes additional audit-trail requirements on digital signatures used in pharmaceutical quality systems, narrowing vendor eligibility. Stakeholders must monitor evolving qualified trust-service provider lists and national digital identity interoperability mandates to anticipate which platform certifications will unlock public-sector contract opportunities.
Market Dynamics
Cloud migration is compressing certificate management costs while biometric verification layers are commanding premium pricing in healthcare and real estate workflows where identity assurance thresholds are most stringent.
Growth Catalysts
- EU eIDAS Qualified Standards:Legally binding cross-border contract execution mandates are forcing financial institutions across Germany, France, and the Netherlands to replace paper-based notarization with certified digital platforms.
- Biometric Verification Integration:Fingerprint and facial recognition protocols embedded within signing workflows are unlocking high-value pharmaceutical and clinical trial applications governed by FDA 21 CFR Part 11 audit-trail requirements.
- India's Digital Infrastructure Buildout:The country's national digital identity stack and IT Act enforcement are accelerating procurement modernization across state governments and public-sector banks.
Market Restraints
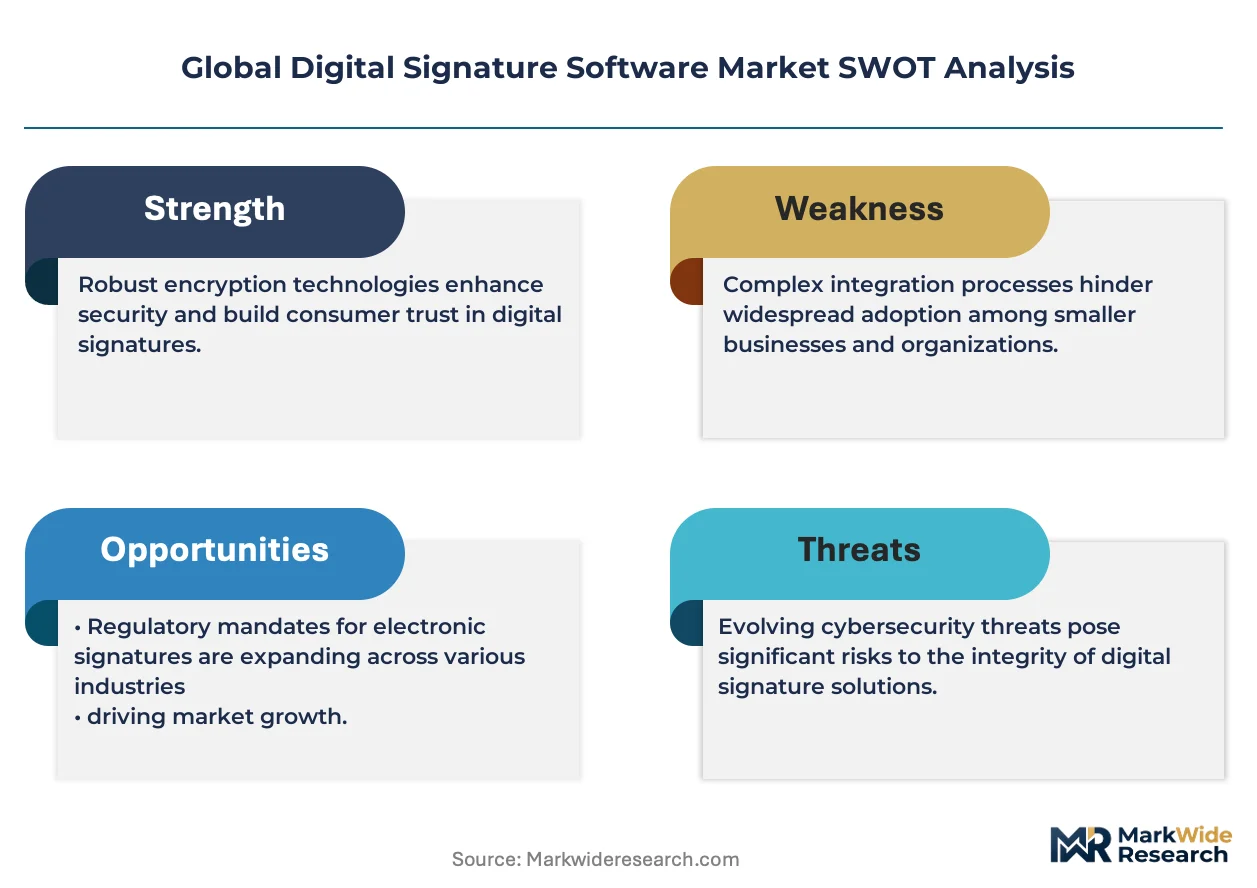
- Certificate Authority Concentration:Trust-service provider accreditation remains concentrated among a handful of EU-recognized entities, creating single-point-of-failure risk for cross-border transaction validity.
- Cryptographic Key Management Costs:Hardware security module requirements for qualified signatures impose capital intensity that excludes smaller professional services firms from premium-tier compliance.
- Interoperability Friction:Divergent national digital identity schemas between EU member states and India's Aadhaar-linked systems prevent seamless signature portability across jurisdictions.
Strategic Opportunities
- Brazil's Underpenetrated Enterprise Segment:ANVISA's advancing electronic submission requirements for pharmaceutical registrations are creating first-mover advantage for platforms achieving local qualified trust-service status.
- Convergence with Blockchain Timestamping:Immutable ledger anchoring of signature events is attracting litigation-prone sectors including construction contracting and intellectual property licensing.
- Saudi Arabia's Government Digitization Mandate:SFDA and central bank directives requiring electronic execution for trade finance and regulatory filings are opening public-sector procurement channels.
Industry Challenges
- Qualified Trust-Service Certification Timelines:ETSI and national supervisory body audits for eIDAS compliance extend 18-24 months, delaying market entry for new platform entrants.
- Legacy Document Management Integration:Enterprise content repositories built on 1990s-era architectures require costly API middleware development to support modern cryptographic signing protocols.
- Cross-Jurisdictional Legal Uncertainty:Courts in common-law jurisdictions including England and Singapore continue developing case precedent on electronic signature enforceability in contested commercial disputes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Signature Software Market |
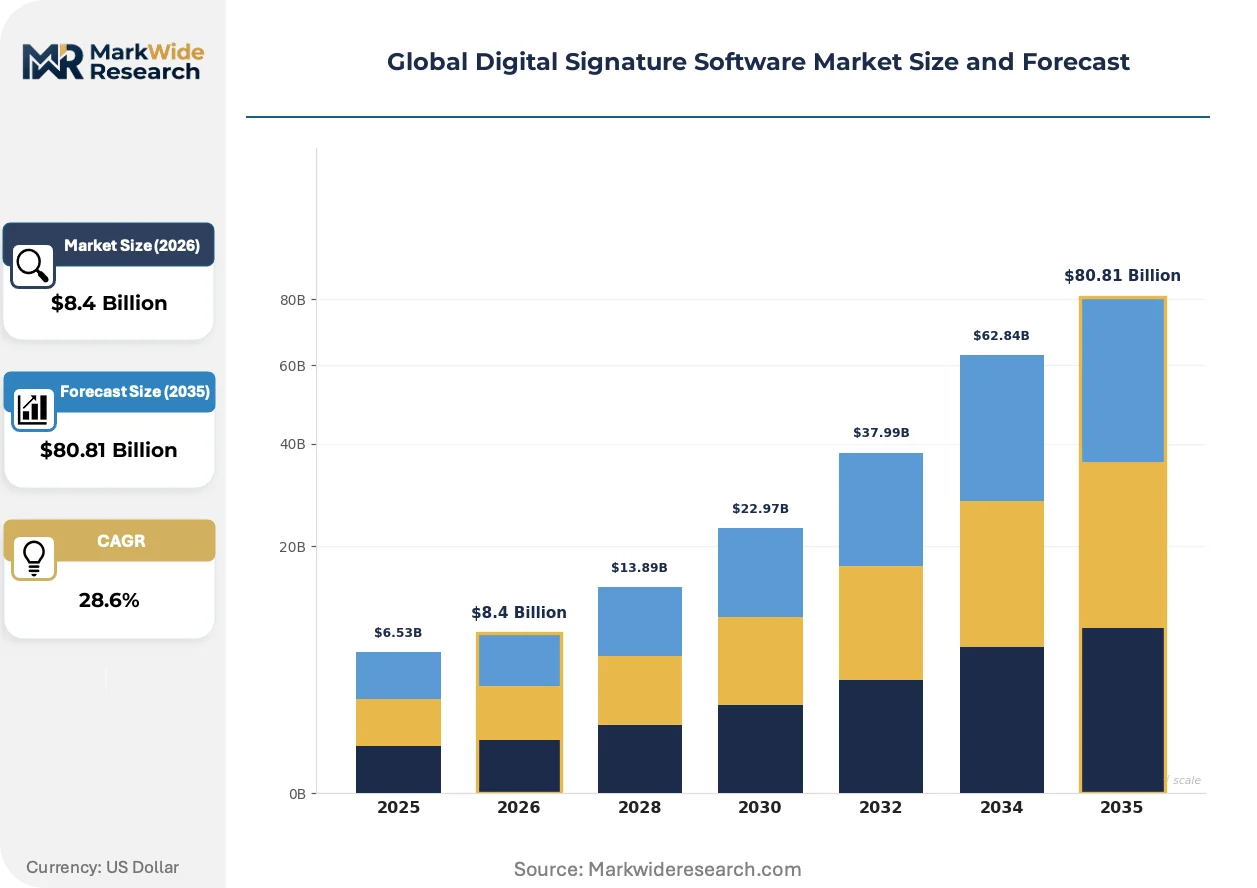
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $80.81 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Hosted, Virtual Appliance Solution Type: Single-Sign-On, Multi-Factor Authentication, Biometric Verification, Document Encryption, Timestamping End User Segment: Financial Institutions, Government Agencies, Software Developers, Legal Firms, Educational Institutions Application: Contract Management, Healthcare Records, Supply Chain Verification, E-Governance, Real Estate Transactions |
| Companies Covered | Dropbox Sign, Zoho Sign, DocuSign, Wesignature, airSlate SignNow, Adobe Sign, Signeasy, Xodo Sign, PandaDoc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Signature Software Market Shifts & Advancements
Decentralized identity architectures and zero-knowledge proof verification are redrawing competitive boundaries between incumbent cloud platforms and emerging cryptographic infrastructure providers.
Blockchain-based timestamping is decentralizing audit-trail custody away from platform operators toward distributed ledger networks. Pharmaceutical manufacturers subject to FDA 21 CFR Part 11 are piloting these architectures to eliminate vendor lock-in risk. The structural consequence is fragmenting what had been consolidated platform control over signature evidentiary chains.
REACH-aligned supply chain due diligence requirements in the European Union are extending signature accountability into raw material sourcing documentation. Chemical manufacturers must now attach qualified electronic signatures to substance safety data sheets crossing member state borders. German industrial conglomerates are deploying eIDAS-compliant workflows to satisfy ECHA submission deadlines without manual notarization bottlenecks.
Enterprise buyers are unbundling signature functionality from monolithic document platforms and procuring best-of-breed cryptographic modules through API-first contracts. Financial services procurement teams in New York and London are negotiating direct trust-service provider relationships, bypassing traditional platform intermediaries. This disintermediation is most visible in investment banking and insurance underwriting verticals where transaction volumes justify dedicated infrastructure investment.
Global Digital Signature Software Market Segmentation
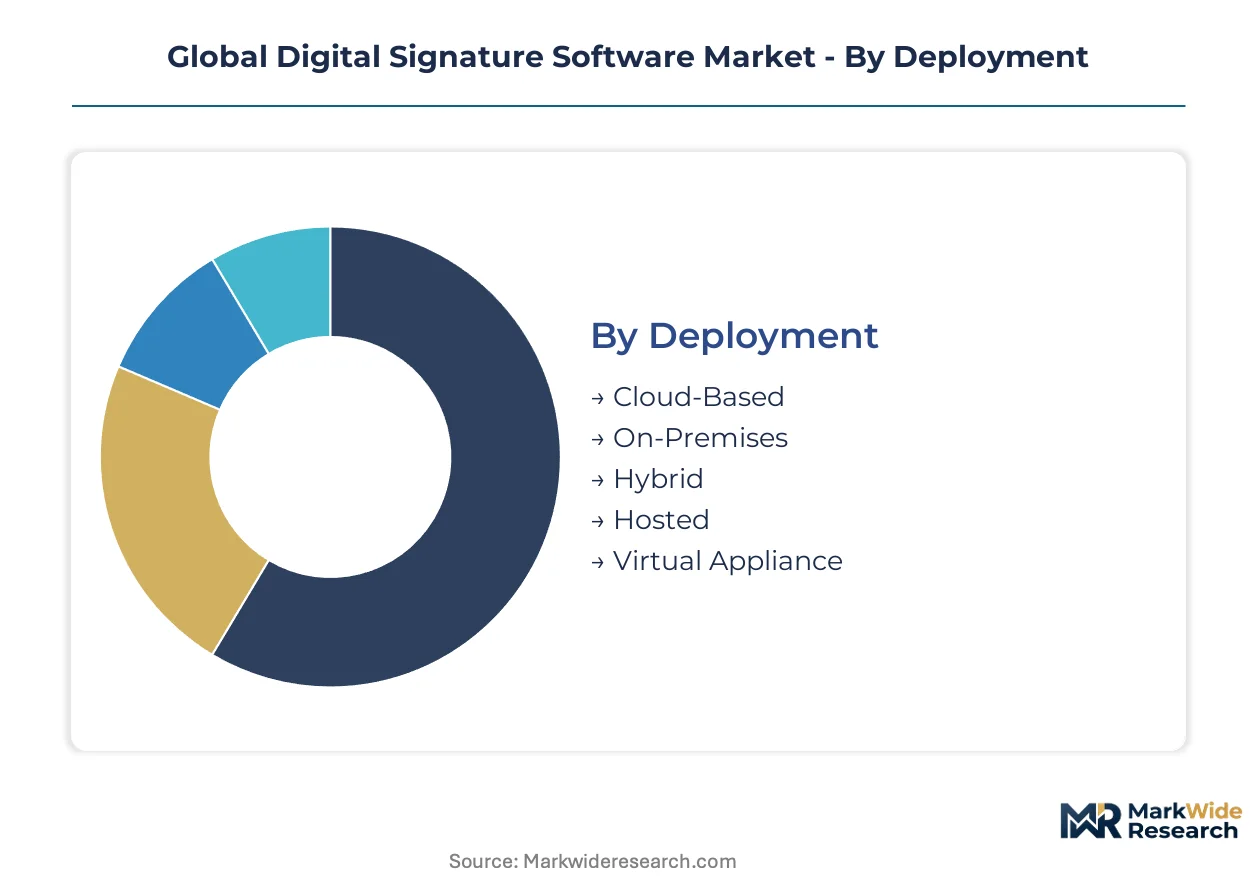
Deployment architecture determines total cost of ownership and compliance eligibility across regulated industries. Solution type selection maps directly to identity assurance thresholds required by sector-specific regulators. End-user procurement patterns reveal which verticals prioritize standalone platforms versus embedded modules.
Deployment:
Standalone cloud deployments dominate procurement where IT teams lack cryptographic expertise, while embedded on-premises systems persist in defense and intelligence workflows requiring air-gapped certificate management.
- Cloud-Based:Public-key infrastructure management shifts entirely to vendor-operated data centers, eliminating hardware security module capital expenditure. Financial institutions in Germany and the Netherlands are standardizing on cloud-based platforms to satisfy eIDAS Qualified trust-service mandates without building captive certificate authority infrastructure.
- On-Premises:Private certificate authority deployment retains full control over signing key custody within organizational boundaries. India's public-sector banks favor on-premises architectures to maintain sovereign data residency under RBI guidelines while integrating with the national digital identity stack.
- Hybrid:Split architectures route routine signatures through cloud infrastructure while reserving on-premises HSMs for qualified signatures requiring maximum legal enforceability.
- Hosted:Dedicated single-tenant cloud instances address data sovereignty requirements without full infrastructure ownership.
- Virtual Appliance:Containerized certificate authority software deploys across private cloud environments with standardized hardware abstraction.
Cloud-Based leads volumes today; Hybrid is gaining share fastest.
Solution Type:
Authentication intensity correlates with transaction value and regulatory scrutiny, creating tiered pricing architecture across verification modalities.
- Biometric Verification:Fingerprint and facial recognition protocols bind physiological identifiers to signing events through liveness detection algorithms. FDA 21 CFR Part 11 compliance in pharmaceutical quality systems drives premium pricing for biometric layers in United States manufacturing operations.
- Multi-Factor Authentication:Knowledge-based and possession-based factors combine with cryptographic credentials to satisfy NIST 800-63 assurance levels. Government agencies across France and Germany mandate multi-factor workflows for classified procurement documentation.
- Single-Sign-On:Identity federation reduces authentication friction for high-volume internal workflows with lower external enforceability requirements.
- Document Encryption:Post-signature content protection prevents unauthorized access to executed agreements during archival retention periods.
- Timestamping:RFC 3161-compliant time attestation establishes signature existence at specific moments without full identity verification.
Multi-Factor Authentication anchors enterprise procurement; Biometric Verification commands the steepest expansion trajectory.
End User Segment:
Procurement sophistication varies sharply across verticals, with regulated industries demanding qualified trust-service certification while professional services prioritize per-seat economics.
- Financial Institutions:Investment banks and insurance underwriters deploy API-first signature modules integrated directly with core banking systems. Loan origination workflows in the United States and India are displacing wet-ink notarization with eIDAS-equivalent qualified signatures for cross-border trade finance.
- Government Agencies:National digital identity infrastructure programs in India and Saudi Arabia mandate electronic execution for public procurement and regulatory filings. SFDA directives require qualified signatures for pharmaceutical import licensing documentation.
- Software Developers:Embedded signing functionality integrates through REST APIs into vertical SaaS applications without standalone platform procurement.
- Legal Firms:Contract execution automation reduces manual notarization bottlenecks for high-volume commercial practice groups.
- Educational Institutions:Credential issuance and transcript authentication represent emerging use cases with lower compliance intensity.
Financial Institutions dominate current spending; Government Agencies show the most rapid budget acceleration.
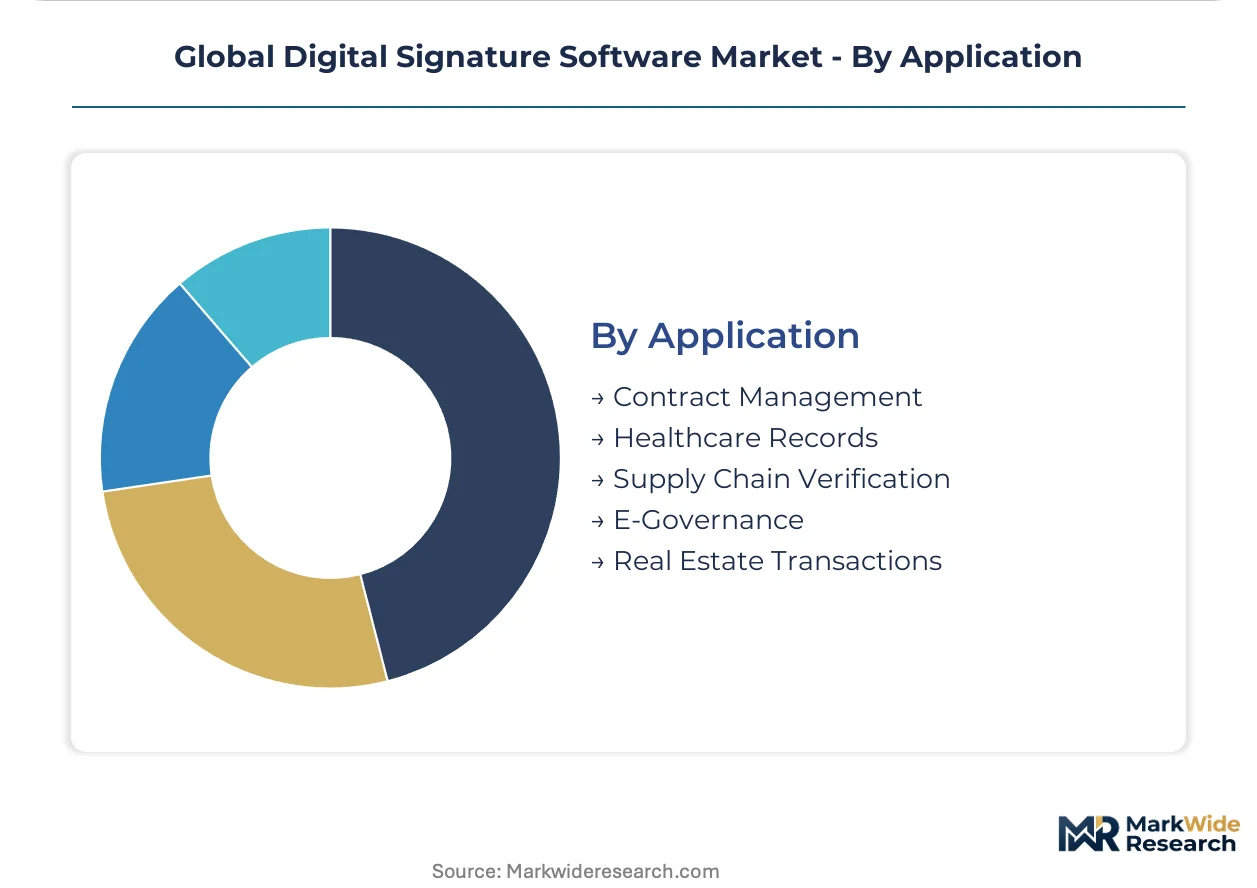
Application:
Use case specificity determines integration complexity, with document-centric workflows requiring less customization than transaction systems needing real-time verification.
- Contract Management:Enterprise legal departments automate signature collection across procurement, employment, and commercial agreements with clause-level routing logic. REACH-aligned supply chain due diligence in the European Union extends signature requirements to substance safety data sheets crossing member state borders.
- Healthcare Records:Clinical trial documentation and patient consent forms require FDA 21 CFR Part 11 audit trails with biometric identity binding. Pharmaceutical manufacturers pilot blockchain-anchored timestamping to eliminate vendor lock-in risk for long-term evidentiary chains.
- Supply Chain Verification:Bills of lading and customs documentation execute across multi-party logistics networks with jurisdiction-specific validity requirements.
- E-Governance:Citizen-facing service delivery platforms integrate qualified signatures for tax filing, permit applications, and property registration.
- Real Estate Transactions:High-value property transfers command maximum identity assurance tiers with notarial supervision requirements varying by jurisdiction.
Contract Management leads deployment scale; Healthcare Records is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The digital signature software industry traces its commercial origins to Silicon Valley's enterprise SaaS ecosystem, where early cloud-based signing platforms achieved scale before regulatory frameworks formalized electronic execution standards across jurisdictions.
United States
Financial institutions in New York and Chicago are displacing wet-ink notarization with API-first signing modules integrated into loan origination workflows. The FDA's 21 CFR Part 11 imposes audit-trail requirements that narrow vendor eligibility for pharmaceutical quality systems. Silicon Valley and Boston anchor the highest concentration of platform development and enterprise procurement decision-making.
Germany
Industrial conglomerates in the Rhine-Ruhr and Bavaria regions deploy eIDAS-compliant workflows to satisfy ECHA submission deadlines for REACH-aligned supply chain documentation. The national digital identity infrastructure program mandates qualified electronic signatures for public procurement above threshold values. Frankfurt's financial services cluster drives cross-border trade finance digitization.
India
Public-sector banks favor on-premises architectures to maintain sovereign data residency under RBI guidelines while integrating with the Aadhaar-linked national digital identity stack. State governments in Maharashtra and Karnataka are modernizing procurement systems to accept electronically executed contracts. Mumbai and Bangalore concentrate fintech platform development and enterprise adoption.
Saudi Arabia
SFDA directives require qualified signatures for pharmaceutical import licensing documentation, opening procurement channels for certified platform providers. The central bank mandates electronic execution for trade finance and regulatory filings across Riyadh and Jeddah financial centers. Government digitization mandates are accelerating citizen-facing service delivery platform deployment.
Brazil
ANVISA's advancing electronic submission requirements for pharmaceutical registrations create first-mover advantage for platforms achieving local qualified trust-service status. São Paulo's enterprise software procurement market concentrates demand from manufacturing and professional services verticals. The regulatory framework remains less mature than European or North American equivalents, leaving pricing power with early certified entrants.
Global Digital Signature Software Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade differentiation, with eIDAS Qualified and FDA 21 CFR Part 11 compliance separating high-assurance tiers from basic electronic signature functionality. The vendor base organizes into three strategic archetypes: incumbent document platforms with embedded signing modules, standalone cloud-native specialists, and API-first infrastructure providers serving embedded use cases. Dominant competitive moves include direct trust-service provider partnerships that bypass platform intermediaries, and biometric verification layer acquisitions to satisfy healthcare and pharmaceutical identity assurance thresholds.
Within the enterprise platform tier, DocuSign and Adobe Sign occupy positions anchored by early eIDAS certification and deep document management integration respectively, while airSlate SignNow exemplifies mid-market workflow automation with competitive per-seat economics. Dropbox Sign represents the cloud storage platform extension archetype, leveraging existing enterprise file collaboration relationships to capture signing workflow adjacency. Zoho Sign and PandaDoc sit within the business productivity suite extension category, embedding signature functionality into broader software procurement relationships rather than standalone platform sales.
| Leading Market Players |
|---|
| Dropbox Sign |
| Zoho Sign |
| DocuSign |
| Wesignature |
| airSlate SignNow |
| Adobe Sign |
| Signeasy |
| Xodo Sign |
| PandaDoc |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up cloud infrastructure specialists anchor supply-side consolidation across certificate authority provisioning and biometric verification module sourcing, translating capital discipline into tiered SaaS pricing that segments procurement by compliance intensity rather than raw transaction volume.
Pricing Analysis
Subscription-based tiering anchored to certification grade separates eIDAS Qualified workflows from basic electronic signatures, with FDA 21 CFR Part 11 compliance commanding premium multiples over standard ESIGN-tier offerings. Price differentiation rests on audit-trail immutability guarantees and biometric identity binding depth. Cost compression in mid-market SaaS tiers is intensifying as API-first infrastructure providers disintermediate platform intermediaries in financial services procurement. Government agencies exhibit lowest price sensitivity due to mandated compliance thresholds, while professional services firms drive standard-tier commoditization through per-seat procurement.
Supply Chain Analysis
Cryptographic engineering talent scarcity in Germany, the Netherlands, and Estonia constrains qualified trust-service provider accreditation velocity and extends ETSI audit timelines. Hardware security module fabrication draws from Taiwan semiconductor foundries and specialized European security chip fabricators. Single-source vulnerability concentrates in EU-recognized certificate authority infrastructure, where supervisory body concentration creates validity risk for cross-border transactions. Distribution runs through direct API contracts with enterprise procurement teams and hyperscaler marketplace integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Digital Signature Software Market compounds steadily as regulatory digitization mandates across financial services and government procurement create irreversible workflow substitution.
For Market Incumbents: Deploy biometric verification layer acquisitions to defend healthcare and pharmaceutical margins against API-first infrastructure entrants. Prioritize direct trust-service provider partnerships in Saudi Arabia and Brazil to preempt regulatory certification bottlenecks. Consolidation of mid-market workflow automation platforms addresses pricing pressure from productivity-suite embedded alternatives. For New Entrants and Emerging Players: Capture Brazil's underpenetrated enterprise segment ahead of ANVISA's advancing electronic submission deadlines. Target India's state government procurement modernization as Aadhaar-linked identity infrastructure matures. A compliance-first go-to-market emphasizing local qualified trust-service status unlocks public-sector contract channels faster than feature differentiation. For Investors and Strategic Acquirers: Valuations sit cheapest among regional trust-service providers with pending eIDAS accreditation rather than scaled cloud platforms with mature multiples. The five-to-ten year viability window favors infrastructure providers with cryptographic key custody control over document-centric workflow layers. Watch for ETSI audit timeline compression as the inflection signal for accreditation capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep embedding into SAP and Oracle document management stacks anchors enterprise retention. |
| Acquisition of Specialist Firm | Biometric verification module purchases satisfy FDA 21 CFR Part 11 identity assurance thresholds. |
| Strategic Partnership | Direct trust-service provider alliances bypass platform intermediaries in investment banking procurement. |
| Geographic Expansion | Local qualified status in Saudi Arabia and Brazil unlocks government digitization contract flows. |
| Product Launch | Blockchain-anchored timestamping pilots attract pharmaceutical manufacturers seeking vendor independence. |
Research Methodology
Bottom-up financial institution and government agency deployment modeling reconciled against top-down trust-service provider capacity tracking forms the analytical core. Primary interviews with CTOs, IT procurement officers, regulatory compliance leads, and integration specialists combined with secondary validation against SEC filings, eIDAS supervisory body accreditation registers, FDA 21 CFR Part 11 guidance documents, and national digital identity program disclosures. Triangulation across these sources ensures segmentation integrity.
Input-output matrices map deployment architecture adoption curves to solution-type pricing trajectories across the projection horizon. Segmentation dimensions modeled include cloud versus on-premises infrastructure, biometric versus multi-factor authentication intensity, financial institution versus government agency end-use, and contract management versus healthcare records application. CAGRs derive from installed base expansion rates and average revenue per account movements. Forecast inputs incorporate ETSI audit pipeline data and national digital identity interoperability milestone schedules.
Regulatory accreditation delays, cryptographic standard migrations, and cross-jurisdictional enforcement friction are the dominant revision risks. Forecasts reflect assumptions about trust-service provider list stability and government procurement digitization commitment. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Europe Smart Doorbell Market
Security Software
North America Secure Access Service Edge Market
Security Software
Digital Risk Protection Software Market
Security Software
Battery-Powered Doorbell Camera Market
Security Software
Network Camera Market
Security Software
Consumer Endpoint Security Market
Security Software
Security Software Market
Security Software
Global Password Management Software Market
Security Software
Global Dynamic Application Security Testing Market
Security Software
Europe Enterprise Firewall Market
Security Software
Social Media Security Market
Security Software
Communication Encryption Software Market
Security Software
Identity Verification Software Market
Security Software
United States Consumer Identity and Access Management Market
Security Software
Global Background Check Software Market
Security Software
Decentralized Identity Software Market