
 Global Data Discovery Software Market | 2026-2036
Global Data Discovery Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Data Discovery Software Market Foresight
Multi-source procurement of analytics infrastructure is shifting toward integrated cloud-native platforms. Microsoft Corporation leverages its Azure ecosystem to anchor enterprise deployments across hybrid environments. IBM Corporation competes through specialized AI-powered data catalog offerings that sustain R&D intensity in governed data access. Oracle Corporation dominates database-native discovery tools, extending its control over structured enterprise workloads.
Data discovery software encompasses platforms that automatically profile, catalog, and visualize distributed datasets through metadata harvesting, machine learning-based relationship mapping, and natural language query interfaces; these systems enable organizations to locate, understand, and trust data assets for operational decision-making. Cloud-based deployment leads in new installations as enterprises prioritize elastic scalability, while self-service analytics and data catalog solutions capture expanding margin pools through subscription pricing. Predictive analytics remains a faster-growing segment as manufacturers and energy utilities apply discovery-layer outputs to forecast maintenance and demand patterns.
The EU AI Act and GDPR impose strict provenance and explainability requirements that shape product roadmaps for metadata management and automated lineage documentation. The US SEC climate disclosure rules and HIPAA data handling standards create parallel compliance demand across BFSI and healthcare-adjacent government sectors. Stakeholders must monitor how fragmented national AI governance frameworks reshape cross-border data residency requirements and platform certification thresholds.
Market Dynamics
The EU AI Act and GDPR are compressing vendor timelines for automated lineage documentation, forcing platform providers to embed compliance capabilities into core architectures rather than bolt-on modules. Financial services and healthcare enterprises now treat data provenance as a procurement prerequisite, not a post-sale configuration.
Growth Catalysts
- GDPR Article 30 mandates:European enterprises must maintain records of processing activities, driving automated metadata harvesting deployments across Frankfurt, Paris, and Amsterdam data centers.
- Self-service analytics proliferation:Manufacturing and energy utilities demand natural language query interfaces that reduce dependency on specialized data engineering teams.
- Cloud-native elasticity:Hybrid workload portability requirements push enterprises toward Kubernetes-orchestrated discovery platforms that span AWS, Azure, and private infrastructure.
Market Restraints
- Specialized talent scarcity:Data catalog architects and metadata engineers command premium compensation in London, New York, and Bangalore, inflating implementation costs.
- Input concentration risk:GPU-dependent machine learning pipelines for relationship mapping face supply constraints from Taiwan Semiconductor Manufacturing capacity allocation.
- Cross-border data friction:China's data localization requirements and India's draft Digital Personal Data Protection Act fragment unified discovery architectures.
Strategic Opportunities
- Indian enterprise modernization:RBI-mandated data governance frameworks for scheduled commercial banks create greenfield demand in Mumbai, Hyderabad, and Bengaluru.
- AI model explainability convergence:Integration of data lineage with MLOps pipelines enables end-to-end provenance tracking for generative AI deployments.
- Utility sector predictive maintenance:German energy distributors apply discovery-layer outputs to forecast transformer failures and optimize grid asset replacement cycles.
Industry Challenges
- Legacy system integration complexity:Mainframe-resident structured data requires specialized connectors that extend deployment timelines for Fortune 500 enterprises.
- Certification timeline compression:ISO 27001 and SOC 2 Type II audits for cloud-native discovery platforms demand six-to-nine month preparation cycles that delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Data Discovery Software Market |
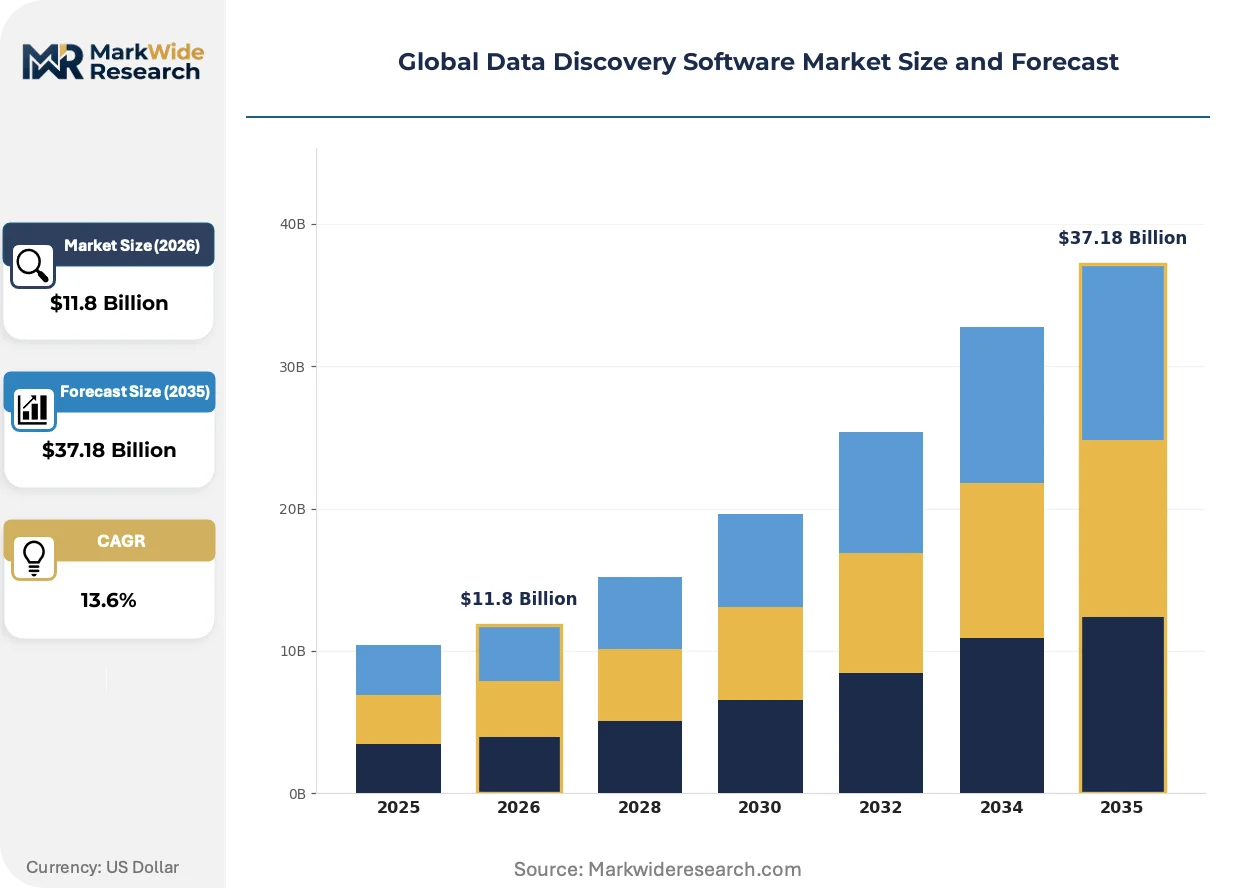
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $37.18 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Private Cloud, Public Cloud Solution/Offering: Data Visualization, Self-Service Analytics, Metadata Management, Data Catalog, Predictive Analytics, Data Preparation Application: Customer Analytics, Risk Management, Fraud Detection, Supply Chain Optimization, Market Research, Product Development End User/Industry Vertical: BFSI, Telecommunications, Government, Manufacturing, Education, Energy & Utilities |
| Companies Covered | Microsoft Corporation, IBM Corporation, Oracle Corporation, SAP SE, Tableau Software LLC, QlikTech International AB, SAS Institute Inc., TIBCO Software Inc., Google LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Data Discovery Software Market Shifts & Advancements
Automated relationship mapping and natural language interfaces are compressing the distance between raw data assets and business decision-makers. Platform providers now compete on time-to-insight rather than catalog breadth alone.
Graph-based metadata engines is electrifying enterprise data architecture by exposing hidden relationships across siloed systems. Pharmaceutical manufacturers in Basel and Boston deploy these engines to trace compound provenance from laboratory notebooks through regulatory submissions. The technology is electrifying competitive positioning by enabling real-time impact analysis for schema changes that previously required weeks of manual documentation.
The EU AI Act's risk classification framework imposes documentation burdens on high-risk AI systems that cascade into data discovery requirements. Financial institutions in Frankfurt and healthcare AI developers in Paris must now maintain immutable audit trails linking training data to model outputs. European regulators are inspecting these lineage records during authorization processes, creating procurement preference for platforms with built-in compliance templates.
Buyer procurement committees now unbundle data discovery from broader analytics suites, evaluating standalone catalog vendors against cloud-native alternatives. Large German manufacturers conduct proof-of-concept trials with three to four providers simultaneously, compressing traditional eighteen-month sales cycles. This pattern concentrates in regulated industries where procurement autonomy has shifted from IT departments to data governance officers with direct board reporting lines.
Global Data Discovery Software Market Segmentation
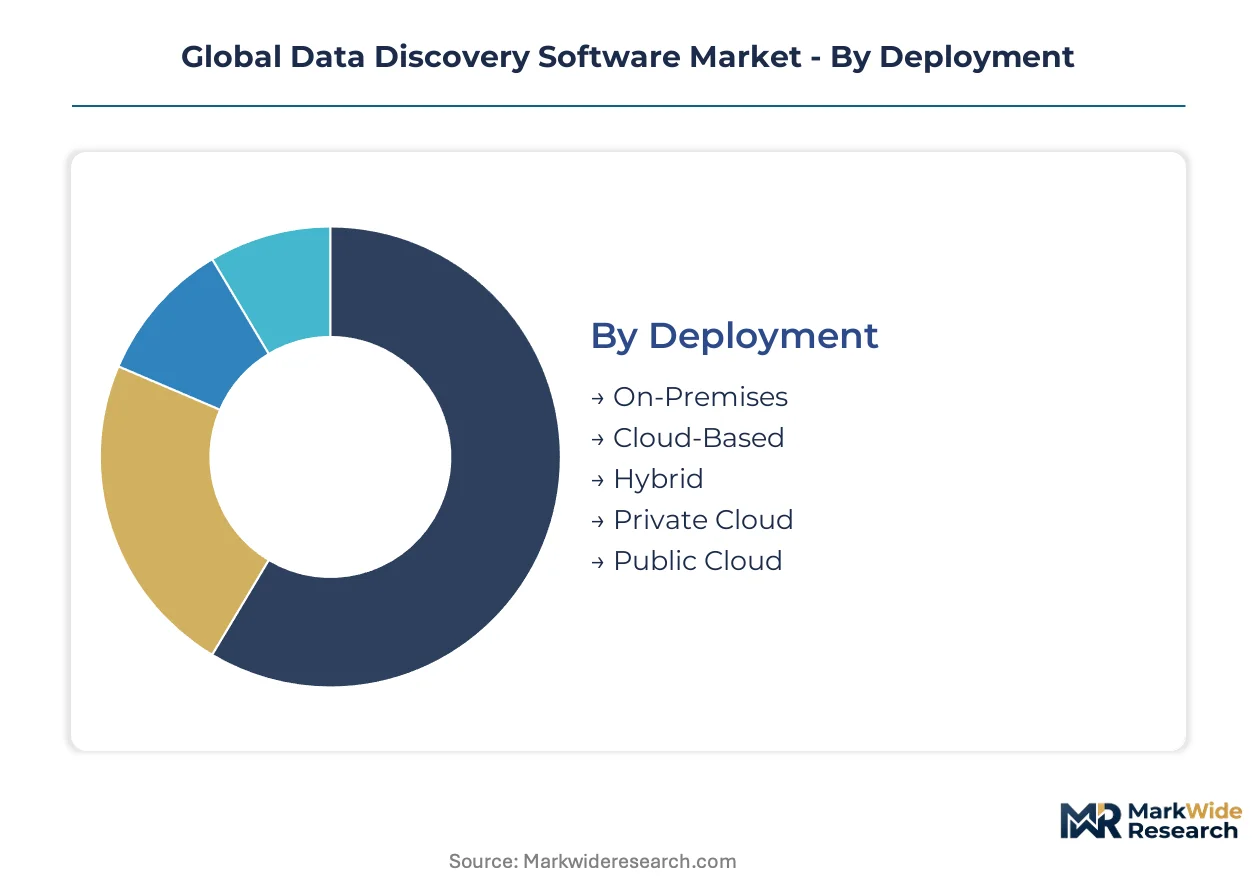
Data discovery software segments along four intersecting dimensions that determine integration architecture and procurement patterns. Deployment mode shapes infrastructure decisions, while solution type dictates whether buyers seek standalone platforms or embedded capabilities within broader analytics ecosystems.
Deployment:
Integration depth varies sharply by deployment mode, with cloud-native architectures embedding discovery layers directly into data pipelines while on-premises installations maintain standalone governance hubs.
- Cloud-Based:Elastic scalability through containerized microservices enables real-time metadata harvesting across distributed AWS, Azure, and GCP environments. Financial services firms in New York and London prioritize this mode for MLOps integration and automated lineage documentation demanded by the EU AI Act.
- Hybrid:Kubernetes-orchestrated platforms span private data centers and public cloud instances, preserving sensitive workloads on-premises while leveraging cloud compute for relationship mapping. German automotive manufacturers and US healthcare systems favor this architecture for HIPAA and GDPR compliance segmentation.
- On-Premises:Air-gapped installations serve defense contractors and classified government facilities with complete physical data sovereignty.
- Private Cloud:Single-tenant dedicated infrastructure addresses RBI-mandated data localization for Indian scheduled commercial banks.
- Public Cloud:Multi-tenant SaaS offerings reduce total cost of ownership for mid-market enterprises in Brazil and Southeast Asia.
Cloud-based deployments lead volumes today; hybrid architectures are gaining share fastest as regulated industries pursue workload portability.
Solution/Offering:
Margin concentration follows solution complexity, with predictive analytics and automated data preparation commanding premium pricing against commoditized visualization modules.
- Data Catalog:Centralized inventory systems with AI-powered tagging and automated stewardship workflows. BFSI procurement committees in Frankfurt and Singapore treat catalog breadth as a primary evaluation criterion for vendor selection.
- Predictive Analytics:Discovery-layer outputs feed directly into forecasting models for demand planning and asset maintenance. German energy distributors apply these capabilities to transformer failure prediction, while US manufacturers optimize inventory positioning.
- Self-Service Analytics:Natural language interfaces reduce dependency on specialized data engineering teams.
- Metadata Management:Automated lineage harvesting satisfies GDPR Article 30 and EU AI Act documentation requirements.
- Data Visualization:Dashboard and reporting layers with embedded discovery capabilities.
- Data Preparation:Cleansing, transformation, and enrichment tools integrated with catalog functions.
Data catalog solutions anchor current revenue; predictive analytics is climbing the fastest as industrial users operationalize discovery outputs.
Application:
Use case maturity determines whether discovery platforms serve exploratory analysis or operational system integration.
- Risk Management:Real-time exposure monitoring across trading books and insurance portfolios requires sub-second metadata refresh rates. Basel III and Solvency II compliance drives adoption among European banks and reinsurers.
- Fraud Detection:Relationship mapping exposes anomalous transaction patterns and synthetic identity networks. Indian payment processors and Brazilian fintechs deploy these capabilities to meet central bank transaction monitoring mandates.
- Customer Analytics:Unified consumer profiles spanning CRM, web, and mobile touchpoints.
- Supply Chain Optimization:Multi-tier supplier visibility and disruption risk assessment.
- Market Research:Survey data integration with external demographic and behavioral datasets.
- Product Development:R&D pipeline tracking from concept through regulatory submission.
Risk management applications dominate current deployment value; fraud detection is expanding most quickly as real-time payment systems proliferate.
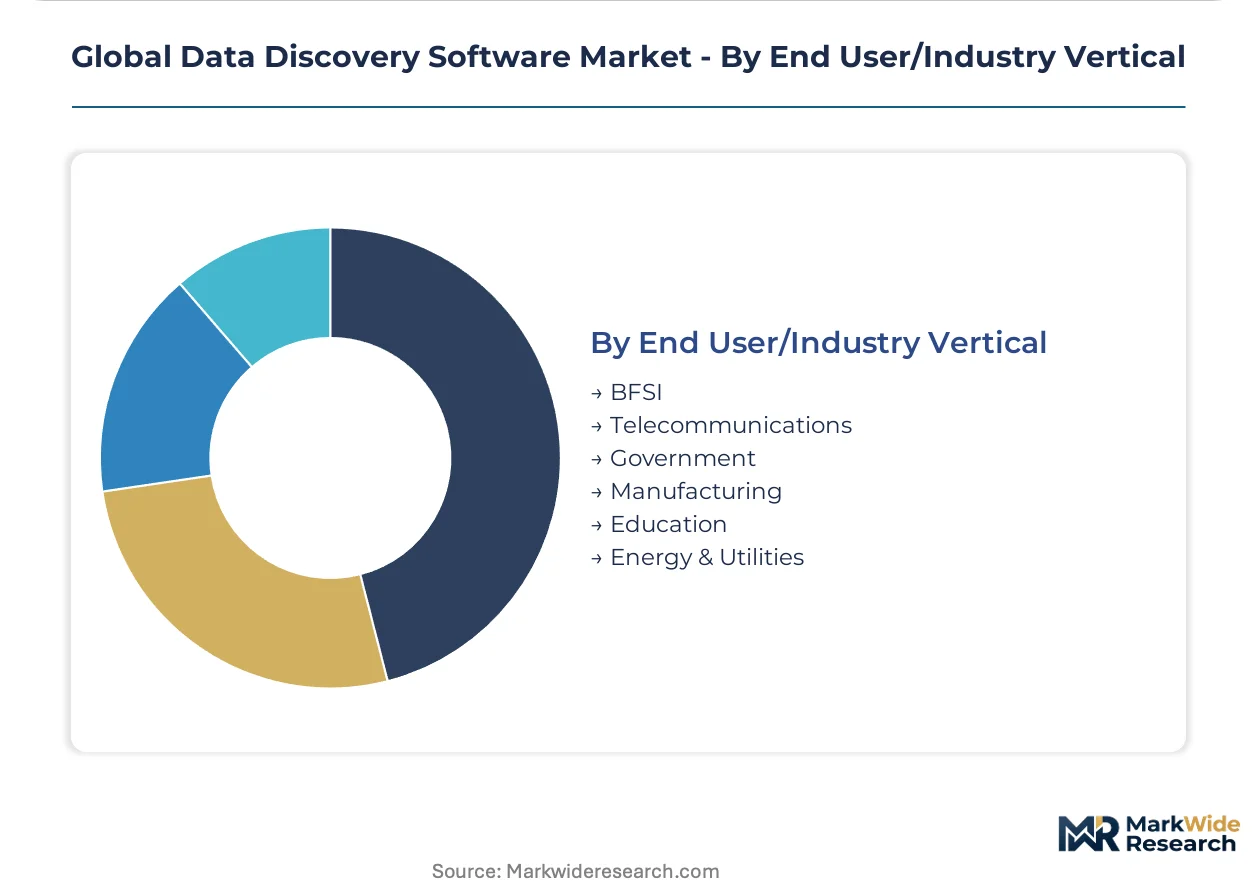
End User/Industry Vertical:
Vertical specialization intensity separates generic platforms from sector-certified offerings with pre-built connectors and compliance templates.
- BFSI:Trading, lending, and insurance operations demand immutable audit trails linking data assets to model outputs. SEC climate disclosure rules and Basel IV data aggregation standards shape procurement specifications for US and European institutions.
- Energy & Utilities:Grid asset management and renewable generation forecasting require time-series discovery capabilities. German distributors and US independent system operators invest heavily in predictive maintenance integration.
- Telecommunications:Network performance data and subscriber analytics at massive scale.
- Government:Citizen service delivery and inter-agency data sharing with classified handling protocols.
- Manufacturing:IoT sensor streams and quality management system integration.
- Education:Student lifecycle analytics and research data management.
BFSI verticals command the largest share of current spending; energy and utilities is seeing the steepest expansion trajectory as grid modernization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between jurisdictions creates compliance-cost arbitrage that shapes where enterprises deploy data discovery infrastructure. The EU AI Act and GDPR impose documentation burdens that accelerate platform investment in European data centers, while US and Asian markets pursue differentiated governance frameworks.
United States
SEC climate disclosure rules and HIPAA data handling standards drive procurement across financial services and healthcare-adjacent government sectors. The SEC mandates granular emissions data tracking that requires automated lineage capabilities. New York and Boston financial institutions dominate early adoption of MLOps-integrated discovery platforms for trading book provenance.
Germany
Industrial manufacturers and energy utilities demand predictive analytics integration for asset maintenance forecasting. The EU AI Act risk classification framework imposes immutable audit trail requirements on high-risk AI systems. Frankfurt banking clusters and Munich automotive headquarters anchor continental deployment of graph-based metadata engines.
India
RBI-mandated data governance frameworks for scheduled commercial banks create greenfield demand in Mumbai, Hyderabad, and Bengaluru. The draft Digital Personal Data Protection Act fragments unified discovery architectures with localization requirements. Domestic fintechs and payment processors deploy relationship mapping for central bank transaction monitoring compliance.
United Kingdom
Post-Brexit regulatory autonomy produces parallel but divergent data protection standards from EU frameworks. The Information Commissioner's Office enforces UK GDPR with sector-specific guidance on automated decision-making. London financial services firms maintain dual-compliance discovery stacks for EU and UK market access.
Japan
METI industrial data governance guidelines shape enterprise platform selection for manufacturing IoT integration. Pharmaceutical manufacturers in Kanto and Kansai regions deploy discovery layers for regulatory submission traceability. Domestic cloud providers compete with hyperscalers through data residency guarantees.
Global Data Discovery Software Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized AI-powered catalog capabilities and vertical-specific compliance templates. The vendor base stratifies across three maturity tiers: hyperscale cloud platforms with integrated discovery layers, standalone catalog specialists with governed data access features, and database-native tool providers extending structured workload control. Strategic differentiation concentrates on automated lineage documentation speed, MLOps pipeline integration depth, and pre-built regulatory compliance templates. Dominant competitive moves include strategic partnerships with cloud infrastructure providers and portfolio diversification into adjacent data governance modules.
Within the hyperscale platform tier, Microsoft Corporation, IBM Corporation, and Oracle Corporation exemplify divergent architectural approaches. Microsoft leverages Azure ecosystem anchoring across hybrid deployment environments. IBM occupies a position emphasizing AI-powered catalog specialization with sustained R&D intensity in governed access protocols. Oracle anchors database-native discovery tool dominance with extension into structured enterprise workload management. These three entities collectively represent the competitive tension between integrated cloud suites and specialized best-of-breed alternatives.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| Oracle Corporation |
| SAP SE |
| Tableau Software LLC |
| QlikTech International AB |
| SAS Institute Inc. |
| TIBCO Software Inc. |
| Google LLC |
| Others |
Supply & Pricing Matrix
Captive cloud infrastructure integration anchors supply position and pricing power for hyperscale platform providers, enabling Microsoft and Oracle to bundle discovery layers with compute commitments while standalone catalog vendors absorb margin compression from GPU-dependent ML pipeline costs.
Pricing Analysis
Direct-to-enterprise subscription discounts dominate the channel structure, with three-tier pricing stratification across enterprise, mid-market, and developer tiers. Certification-grade differentiation separates FedRAMP-authorized deployments from standard SaaS offerings, while volume scale commitments unlock hybrid portability rights. Cost compression in the mid-market tier intensifies as Indian fintechs and Brazilian payment processors demand consumption-based alternatives to annual contracts. Developer-tier buyers exhibit highest price sensitivity, whereas Frankfurt banking clusters accept premium positioning for immutable EU AI Act audit trails.
Supply Chain Analysis
Refurbishment and remanufacturing flows for GPU clusters extend hardware lifecycles as Taiwan Semiconductor Manufacturing capacity allocation constrains new silicon availability. Supply concentrates in the United States, Ireland, and Singapore for hyperscaler data center infrastructure, while specialized metadata engine development draws from Israel, Canada, and Germany. Single-source vulnerability in TSMC's advanced node production threatens ML-based relationship mapping pipelines. Distribution runs through direct enterprise sales organizations with embedded solutions architects, supplemented by hyperscaler marketplace listings for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Data Discovery Software Market represents a late-cycle quality story as procurement autonomy shifts from IT departments to data governance officers demanding premium compliance specifications under the EU AI Act and SEC climate disclosure rules.
For Market Incumbents: Anticipate margin pressure from open-source metadata engines by embedding automated lineage documentation as a core architectural primitive rather than bolt-on module. Defend position through backward integration into MLOps pipeline providers and capacity addition in Mumbai and Frankfurt data centers to satisfy RBI and GDPR localization mandates.
For New Entrants and Emerging Players: The premium-to-economy pricing gap in the Indian scheduled commercial bank segment offers white-space entry for catalog vendors with pre-built RBI compliance templates. Target German energy utilities with predictive maintenance integration capabilities as the most penetrable vertical, leveraging proof-of-concept trial structures that compress traditional eighteen-month procurement cycles.
For Investors and Strategic Acquirers: Roll-up economics work for standalone catalog specialists with governed data access IP because hyperscalers face antitrust scrutiny on vertical platform extension. Long-term viability favors vendors with ISO 27001 and SOC 2 Type II pre-certification. Monitor EU AI Act authorization timelines as the inflection signal for procurement preference shifts toward built-in compliance templates.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding discovery layers into Azure and AWS marketplaces captures mid-market procurement workflows. |
| Acquisition of Specialist Firm | Absorbing graph-based metadata engine providers accelerates time-to-insight for pharmaceutical provenance tracking. |
| Geographic Expansion | Establishing Mumbai and Hyderabad delivery centers addresses RBI-mandated data localization for scheduled commercial banks. |
| Strategic Partnership | Aligning with Kubernetes orchestration vendors enables hybrid workload portability across regulated industries. |
| Product Launch | Introducing natural language query interfaces reduces manufacturing and energy utility dependency on data engineering teams. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with CTOs, IT procurement officers, data governance officers, and platform engineers alongside secondary validation from SEC filings, hyperscaler capex disclosures, App Annie enterprise mobility data, and EU regulatory authorization databases. Bottom-up deployment counts triangulate against top-down software spend estimates.
Granularity-level modeling addresses deployment mode, organization size, vertical specialization, and integration complexity dimensions across the projection horizon. CAGRs derive from segment-level adoption curves weighted by regulatory enforcement timelines and cloud infrastructure penetration rates. Forecast inputs incorporate RBI data governance framework implementation pace and EU AI Act risk classification rollout schedules.
Caveats apply where TSMC capacity reallocation or fragmented national AI governance framework proliferation could materially shift the outlook. Practitioners should monitor ISO 27001 certification timeline compression and GPU supply allocation announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Saas-Based Expense Management Market
Software & Services
Human Capital Management (HCM) Saas Market
Software & Services
Global Intranet Software Market
Software & Services
Global Online Assessment Software Market
Software & Services
Global Managed File Transfer (MFT) Software and Service Market
Software & Services
Indonesia Big Data Analytics Software Market
Software & Services
Home Design Software Market
Software & Services
Instant Messaging Software Market
Software & Services
Voice to Text on Mobile Devices Market
Software & Services
Projector Software Market
Software & Services
Global Accounts Receivable Software Market
Software & Services
Automotive Dealership Software Market
Software & Services
Warranty Management Software Market
Software & Services
Global HVAC Software Market
Software & Services
Global Document Control Software Market
Software & Services
Global Thermal Analysis Software Market