
 Temperature Loggers Market | 2026-2036
Temperature Loggers Market Size, Share, and Industry Trends Forecast 2026-2036
Temperature Loggers Market Analytics
The capital-intensity divergence between in-house sensor fabrication and outsourced assembly is redrawing competitive tiers in temperature logging. Testo SE & Co. KGaA leverages captive manufacturing of calibration-grade thermistors to sustain margin structures unavailable to modular competitors. OMEGA Engineering Inc. anchors its position through deep channel control across North American industrial distribution, while Onset Computer Corporation differentiates via specialized wireless mesh architectures for environmental monitoring networks.
Temperature loggers are electronic instruments that record thermal data at programmed intervals using thermocouple, thermistor, or RTD sensors, typically achieving accuracy within ±0.5°C and storing thousands of readings in onboard memory for later retrieval and compliance documentation. Their primary commercial purpose centers on documenting chain-of-custody conditions for temperature-sensitive goods and processes, creating audit trails that satisfy regulatory evidentiary requirements. Wireless product types are capturing disproportionate growth as Bluetooth and cloud-based technology segments enable real-time alerting without physical retrieval, though USB-based multi-use devices still dominate margin pools in laboratory end-user settings where calibration traceability commands premium pricing. Single-use loggers face commoditization pressure in pharmaceutical cold chain applications despite expanding volume, as food and beverage buyers prioritize cost-per-shipment over instrument reusability.
FDA 21 CFR Part 11 electronic records requirements and EU Good Distribution Practice guidelines enforced by EMA national competent authorities are elevating validation documentation burdens for temperature logger deployments in pharmaceutical logistics. The EPA's Clean Air Act refrigeration management rules and evolving F-Gas Regulation phase-down schedules in Europe are indirectly stimulating replacement demand as HVAC end-users retrofit monitoring systems to track alternative refrigerant performance. Stakeholders must weigh calibration infrastructure investments against the compliance risk of distributed, unvalidated sensor networks as regulatory scrutiny intensifies across jurisdictions.
Market Dynamics
Cold chain logistics operators are deploying sensor networks at unprecedented density as pharmaceutical traceability mandates harden and perishable cargo values climb. The shift from spot-check monitoring to continuous digital documentation is restructuring procurement priorities across temperature-sensitive supply chains.
Growth Catalysts
- FDA Drug Supply Chain Security Act:Pharmaceutical distributors in the United States must maintain electronic records of temperature conditions, forcing upgrade cycles in legacy logging infrastructure.
- Precision fermentation:Biotechnology firms producing cultivated proteins and alternative dairy require sub-degree accuracy across multi-stage bioreactor processes, creating specialized demand for calibration-grade instruments.
- Germany's Bundesamt für Sicherheit im Gesundheitswesen:Stringent federal health security oversight drives premium instrument procurement from precision manufacturing clusters in Baden-Württemberg and Bavaria.
Market Restraints
- Thermistor supply concentration:High-precision bead thermistors rely on Japanese and German component suppliers, creating vulnerability to export control disruptions.
- Calibration infrastructure gaps:Distributed sensor networks in emerging markets lack accredited calibration laboratories, forcing redundant hardware deployment or compliance risk acceptance.
- Single-use logger commoditization:Pharmaceutical cold chain buyers treat disposable loggers as cost-per-shipment commodities, compressing margins despite expanding shipment volumes.
Strategic Opportunities
- EU F-Gas Regulation phase-down:HVAC retrofit cycles to monitor alternative refrigerant performance create replacement demand for industrial-grade temperature monitoring systems.
- India's cold chain expansion:Agricultural export growth and vaccine distribution networks drive demand for cost-optimized wireless loggers with cloud connectivity.
- Bluetooth Low Energy convergence with NFC:Hybrid connectivity architectures enable tap-to-retrieve data workflows that bridge laboratory traceability requirements with field deployment convenience.
Industry Challenges
- 21 CFR Part 11 validation timelines:Pharmaceutical logistics operators face 12-18 month software qualification cycles that delay deployment of firmware-upgradable logger platforms.
- Metrology technician scarcity:Accredited calibration laboratories struggle to hire personnel qualified in IEC 17025 procedures, extending turnaround times for sensor recertification.
- Legacy system protocol fragmentation:Industrial facilities operate mixed fleets of Modbus, BACnet, and proprietary sensor networks that resist unified data aggregation without middleware investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Temperature Loggers Market |
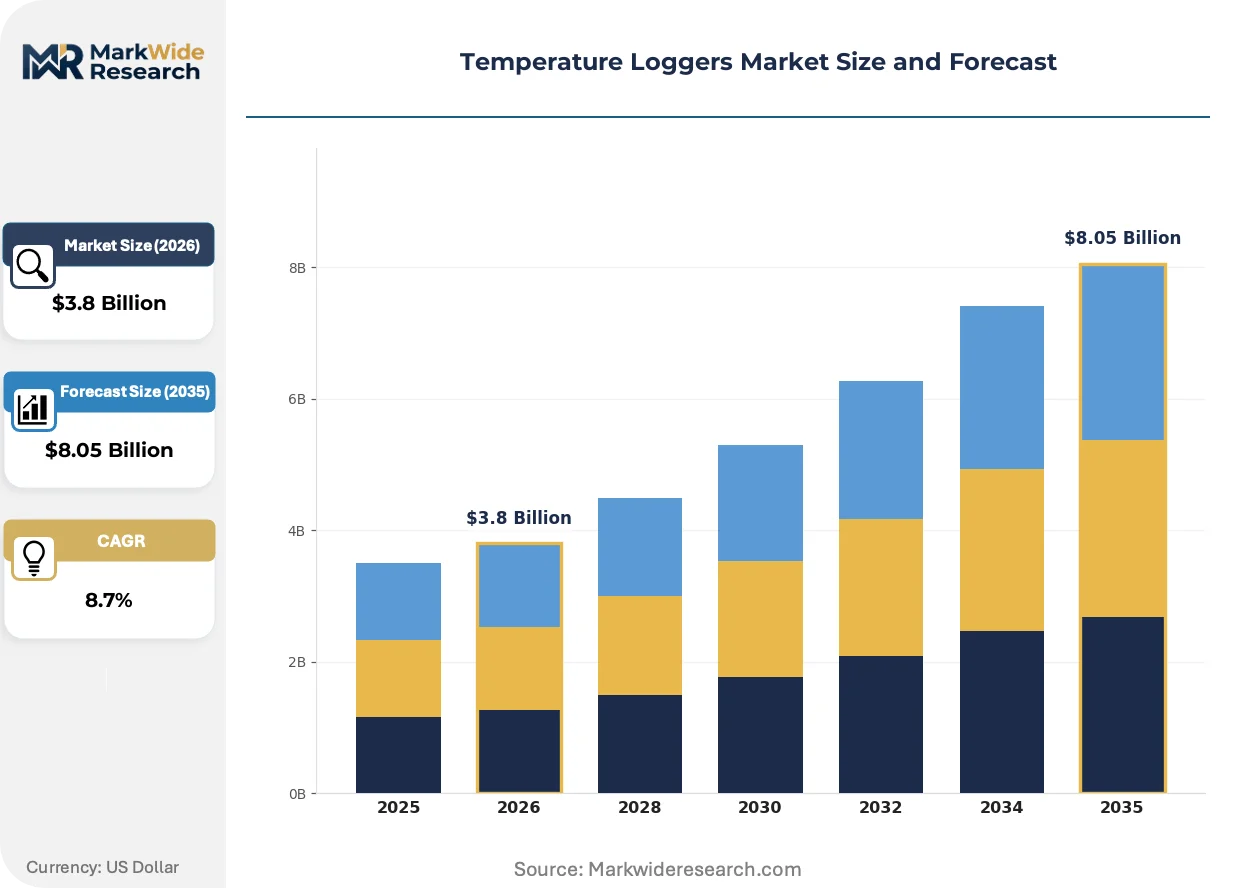
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use, Multi-Use, Wireless, USB End User: Pharmaceuticals, Food & Beverage, HVAC, Laboratories Installation: Permanent, Portable, Fixed, Removable Technology: Cloud-Based, Bluetooth, Infrared, Data Logger |
| Companies Covered | Testo SE & Co. KGaA, OMEGA Engineering Inc., Onset Computer Corporation, HIOKI E.E. Corporation, ELPRO-BUCHS AG, Rotronic AG, MadgeTech Inc., Lascar Electronics Limited, Dickson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Temperature Loggers Market Evolving Landscape
Sensor miniaturization and edge computing capabilities are dissolving the boundary between standalone loggers and distributed IoT architectures. Three developments are restructuring competitive positioning and buyer expectations.
Multi-sensor fusion platforms integrating temperature, humidity, shock, and light exposure into single devices are fragmenting the historical separation between environmental monitoring categories. Cold chain operators in pharmaceutical and fresh produce logistics now demand consolidated data streams that eliminate hardware redundancy. This convergence is compressing addressable market boundaries for single-function instrument specialists while expanding total solution contract values.
The European Union's F-Gas Regulation and its scheduled hydrofluorocarbon phase-down are compelling industrial refrigeration operators to retrofit monitoring systems for alternative refrigerant tracking. Equipment manufacturers must validate sensor accuracy across ammonia, CO2, and hydrofluoro-olefin thermal profiles that differ materially from legacy refrigerant characteristics. German chemical processing facilities and Dutch cold storage operators are currently absorbing the highest compliance-driven replacement volumes.
Subscription-based hardware provisioning is displacing capital purchase models among mid-sized food distributors seeking to convert fixed monitoring costs to variable per-shipment economics. Third-party logistics providers now bundle logger rental, calibration, and data analytics into unified service tiers. This shift is most visible in North American perishable produce distribution, where seasonal volume volatility makes ownership economics unfavorable.
Temperature Loggers Market Segmentation
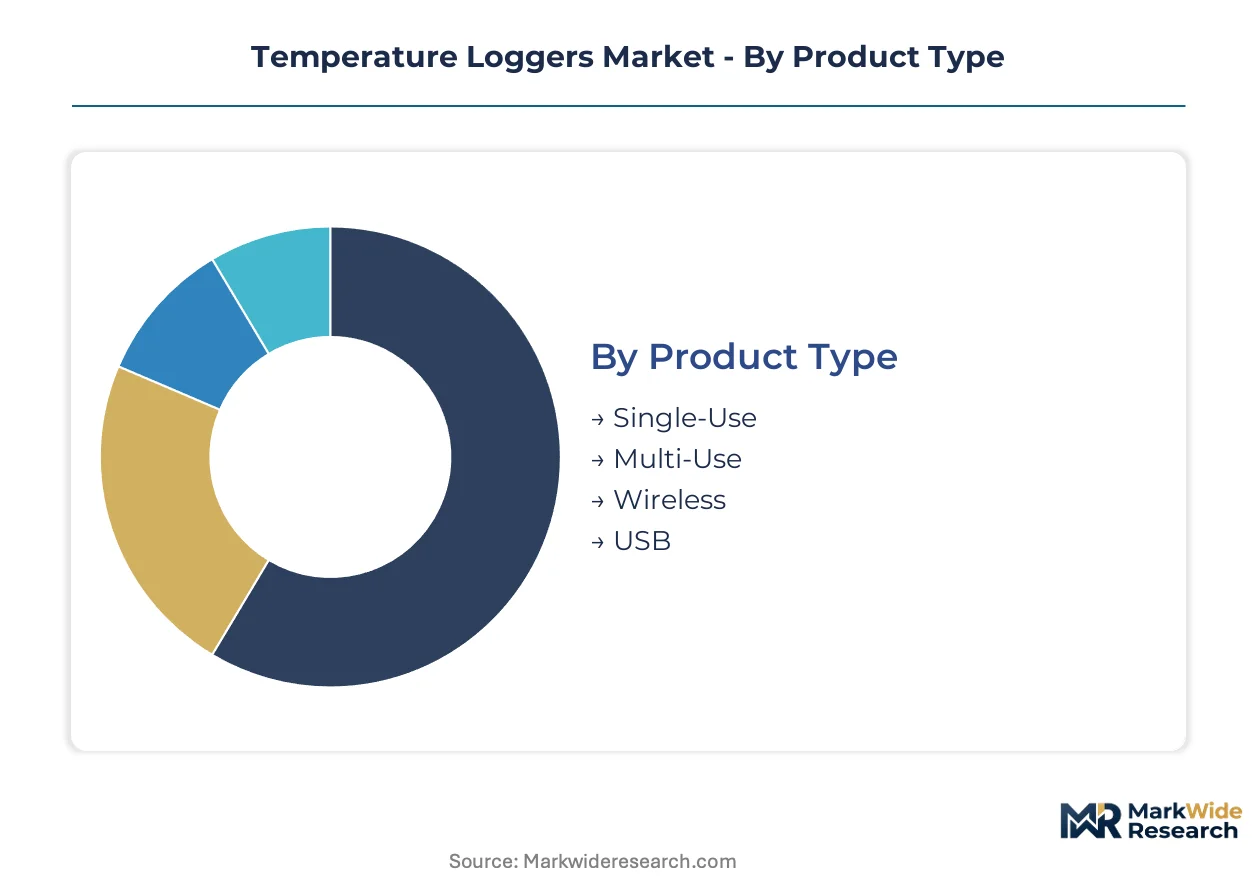
Temperature logger procurement splits sharply between compliance-driven pharmaceutical buyers prioritizing calibration traceability and cost-sensitive food distributors optimizing per-shipment economics. Understanding these segment boundaries reveals where pricing power concentrates and which technology trajectories command R&D investment.
Product Type:
Margin pools concentrate in reusable instruments with embedded calibration certificates, while single-use devices compete on unit cost.
- Single-Use:Disposable loggers with pre-programmed temperature thresholds and irreversible visual alarms. Pharmaceutical cold chain buyers in Germany treat these as cost-per-shipment commodities, compressing manufacturer margins despite expanding vaccine distribution volumes.
- Multi-Use:Battery-powered instruments with downloadable memory and recalibration capability. Laboratory end-users in Baden-Württemberg precision manufacturing clusters pay premiums for NIST-traceable documentation that satisfies FDA 21 CFR Part 11 requirements.
- Wireless:Real-time alerting via cellular or mesh networks eliminates physical retrieval.
- USB:Direct computer interface dominates budget-conscious food distributor procurement.
The dominant share belongs to Multi-Use, while Wireless is closing the gap fastest.
End User:
Application requirements diverge between sub-degree bioprocess monitoring and broad-range HVAC surveillance.
- Pharmaceuticals:EMA national competent authorities enforce continuous documentation for investigational drug shipments. EU Good Distribution Practice mandates drive replacement cycles toward firmware-validated platforms with encrypted data integrity.
- Food & Beverage:Perishable produce distributors prioritize logger rental models that convert fixed costs to variable per-shipment economics. Seasonal volume volatility in North American distribution networks makes ownership structures unfavorable.
- HVAC:EPA Clean Air Act refrigeration management rules stimulate retrofit demand.
- Laboratories:IEC 17025-accredited calibration requirements sustain premium pricing tiers.
Pharmaceuticals commands the largest revenue pool, though Food & Beverage shows the steepest expansion trajectory.
Installation:
Deployment flexibility determines total cost of ownership across facility types.
- Permanent:Hardwired sensors integrated into building management systems. Dutch cold storage operators favor these for ammonia refrigeration monitoring under EU F-Gas Regulation compliance timelines.
- Portable:Handheld units with interchangeable probes serve field audit applications. Indian agricultural export inspectors deploy these for spot-check verification of mango and grape shipments.
- Fixed:Stationary mounting without permanent electrical connection.
- Removable:Magnetic or adhesive attachment for temporary monitoring.
Permanent installations retain the largest installed base, while Portable configurations gain share fastest.
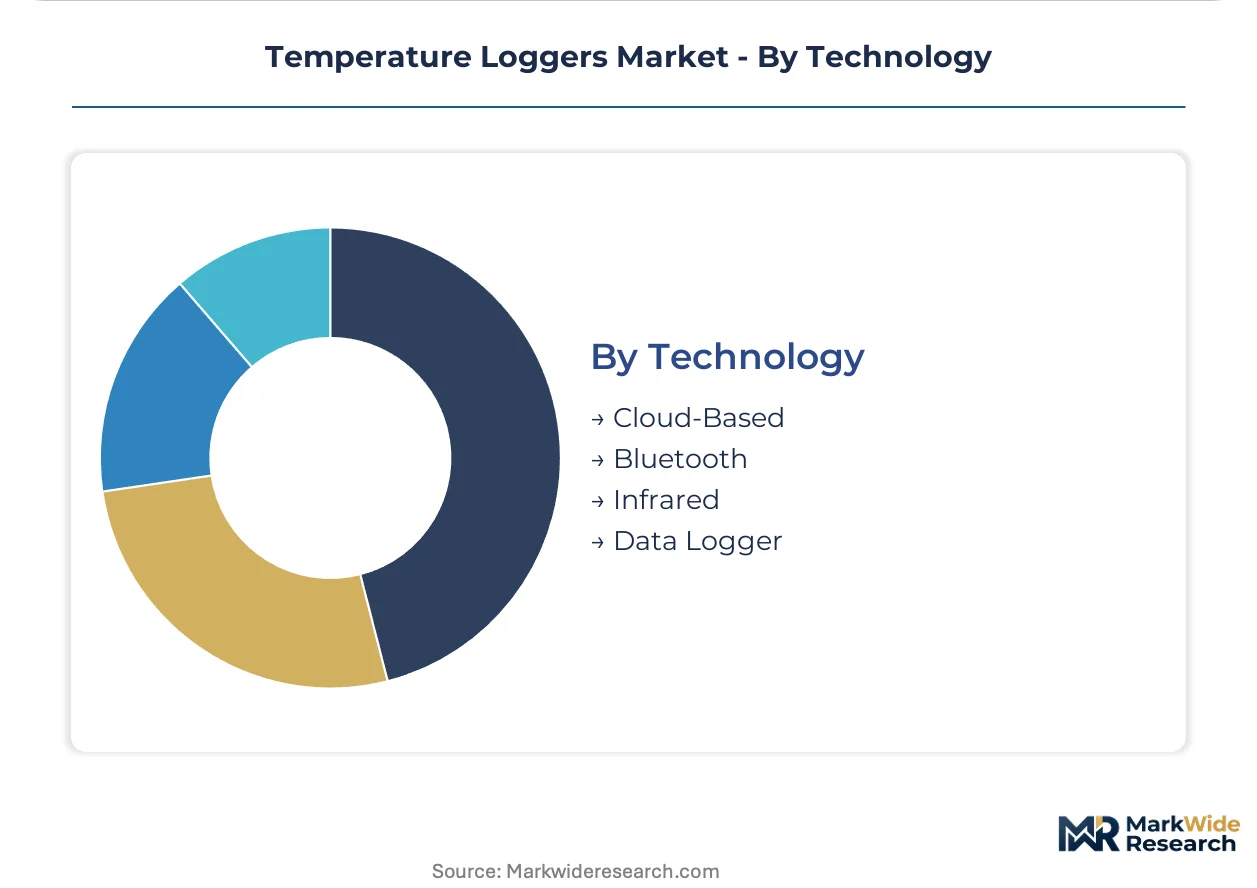
Technology:
Connectivity architecture shapes data retrieval workflows and validation burden.
- Cloud-Based:Continuous data streaming to hosted platforms with automated compliance reporting. Biotechnology firms operating precision fermentation bioreactors require these architectures for multi-stage process documentation.
- Bluetooth:Short-range wireless enabling smartphone retrieval without cloud dependency. Hybrid Bluetooth-NFC architectures bridge laboratory traceability requirements with field deployment convenience.
- Infrared:Non-contact surface temperature measurement for hazardous environments.
- Data Logger:Standalone memory storage without external connectivity.
Data Logger maintains the dominant position, though Cloud-Based is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns split sharply between precision-calibrated pharmaceutical procurement in Germany and cost-optimized per-shipment deployment in India. German buyers prioritize NIST-traceable documentation for FDA compliance, while Indian agricultural exporters favor disposable loggers with cloud connectivity. The United States anchors replacement demand from legacy infrastructure upgrades, Japan concentrates high-accuracy bioprocess instrumentation, and the Netherlands leads industrial refrigeration retrofit cycles.
United States
Pharmaceutical distributors drive replacement cycles as FDA 21 CFR Part 11 mandates force upgrades from paper-based temperature records to encrypted digital systems. The Drug Supply Chain Security Act compels electronic documentation of investigational drug shipments. Cold chain logistics operators in New Jersey and Pennsylvania absorb the highest compliance-driven procurement volumes.
Germany
Precision manufacturing clusters in Baden-Württemberg and Bavaria sustain premium instrument demand for calibration-grade bioreactor monitoring. Bundesamt für Sicherheit im Gesundheitswesen oversight enforces stringent validation requirements for pharmaceutical traceability. Stuttgart-based industrial automation firms integrate temperature logging into multi-parameter process control systems.
India
Agricultural export growth and vaccine distribution networks fuel demand for cost-optimized wireless loggers with smartphone retrieval capability. FSSAI cold chain regulations for mango and grape shipments mandate continuous monitoring documentation. Maharashtra and Gujarat processing facilities deploy the highest sensor densities for perishable cargo integrity.
Japan
Precision fermentation biotechnology firms require sub-degree accuracy across multi-stage bioreactor processes. METI industrial standards for pharmaceutical manufacturing equipment elevate calibration certificate requirements. Osaka and Tokyo metropolitan areas concentrate cultivated protein production facilities driving specialized instrument procurement.
Netherlands
Industrial refrigeration operators retrofit monitoring systems to track alternative refrigerant performance under EU F-Gas Regulation phase-down timelines. Dutch cold storage facilities absorb the highest compliance-driven replacement volumes for ammonia and CO2 thermal profile validation. Rotterdam port logistics hubs deploy dense sensor networks for pharmaceutical transshipment documentation.
Temperature Loggers Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in temperature logger supply. Captive thermistor fabrication and calibration infrastructure distinguish the upper tier from modular assemblers dependent on outsourced components. Three archetypes dominate: vertically integrated instrument manufacturers with in-house sensor production, channel-anchored industrial distributors with deep North American coverage, and wireless architecture specialists focused on environmental monitoring networks. Consolidation pressure favors acquisition of calibration laboratories and cloud platform capabilities over capacity expansion.
Among European precision instrument fabricators, Testo SE & Co. KGaA exemplifies the integrated manufacturing archetype through captive thermistor production. OMEGA Engineering Inc. represents channel-anchored positioning across industrial distribution networks. Onset Computer Corporation occupies the wireless specialization tier with mesh architecture capabilities. These three anchors illustrate how competitive differentiation concentrates in upstream component control, downstream access, or connectivity innovation rather than assembly scale.
| Leading Market Players |
|---|
| Testo SE & Co. KGaA |
| OMEGA Engineering Inc. |
| Onset Computer Corporation |
| HIOKI E.E. Corporation |
| ELPRO-BUCHS AG |
| Rotronic AG |
| MadgeTech Inc. |
| Lascar Electronics Limited |
| Dickson |
| Others |
Value Network & Pricing Analysis
Bluetooth Low Energy module substitution for proprietary radio stacks is redrawing component sourcing maps and compressing hardware margins as pharmaceutical buyers demand encrypted firmware validation. This technology migration simultaneously loosens Japanese component chokeholds while intensifying pricing pressure on modular assemblers lacking calibration infrastructure.
Pricing Analysis
Long-term calibration service contracts dominate pharmaceutical procurement, insulating integrated manufacturers from spot-market volatility in single-use logger segments. Pricing stratifies across NIST-traceable premium tiers, FDA-validated standard tiers, and unvalidated economy tiers. Cost compression in disposable pharmaceutical loggers is intensifying because Indian agricultural exporters treat units as per-shipment commodities. Food and beverage distributors exhibit highest price sensitivity, while German precision manufacturing clusters pay calibration premiums without negotiation.
Supply Chain Analysis
Bead thermistor fabrication concentrates in Japan and Germany, creating single-source vulnerability for sub-degree accuracy instruments. High-precision sensing elements draw from specialty ceramics and platinum thin-film substrates. Tariff exposure on Japanese electronic components threatens margin structures for modular competitors. Distribution runs through industrial instrumentation distributors with deep channel control across North American pharmaceutical logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat arena where FDA 21 CFR Part 11 validation timelines create switching costs that entrench incumbent calibration laboratories. Network effects concentrate in cloud-platform data aggregation as pharmaceutical logistics operators resist fragmented sensor fleets.
For Market Incumbents: Fortify captive thermistor production through backward integration into Japanese and German component suppliers, neutralizing supply disruption risks from export control tightening. Deepen channel control across North American industrial distribution to block modular competitors from laboratory end-user access. Calibration infrastructure scarcity in emerging markets threatens premium pricing tiers.
For New Entrants and Emerging Players: Differentiate on hybrid Bluetooth-NFC architectures that bridge laboratory traceability requirements with Indian agricultural field deployment convenience. Target India's cost-optimized wireless logger segment where FSSAI cold chain regulations mandate documentation but price sensitivity excludes premium incumbents. Pursue cloud-platform partnerships rather than hardware manufacturing scale.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors acquisition of IEC 17025-accredited calibration laboratories over capacity expansion. Long-term viability rests on regulatory entrenchment rather than technology disruption. Watch EU F-Gas Regulation enforcement intensity as inflection indicator for industrial refrigeration retrofit demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Laboratory Acquisition | Captures FDA 21 CFR Part 11 validation capabilities that pharmaceutical distributors cannot replicate internally. |
| Bluetooth-NFC Hybrid Platform Launch | Bridges German laboratory traceability requirements with Indian agricultural field deployment economics. |
| Cloud Data Analytics Partnership | Aggregates fragmented sensor networks for biotechnology firms operating precision fermentation bioreactors. |
| EU F-Gas Compliance Service Tier | Captures Dutch cold storage retrofit cycles for ammonia and CO2 refrigerant monitoring validation. |
| Subscription Hardware Provisioning | Converts fixed monitoring costs to variable per-shipment economics for North American produce distributors. |
Research Methodology
Cross-validation between primary interviews with cold chain logistics operators and secondary regulatory filing analysis anchors the qualitative findings. Stakeholder consultations included pharmaceutical distribution compliance officers, bioreactor process engineers, industrial refrigeration maintenance directors, and agricultural export inspectors. Secondary sources encompassed FDA 21 CFR Part 11 guidance documents, EMA Good Distribution Practice updates, EU F-Gas Regulation implementation notices, and customs trade data on thermistor component flows. Bottom-up sensor deployment estimates triangulate against top-down pharmaceutical logistics spending patterns.
Sensitivity analysis around regulatory enforcement timelines and thermistor supply disruption scenarios shapes the projection framework. Segmentation dimensions span product type, end-user industry, installation configuration, and connectivity architecture. CAGRs derive from modeled replacement cycles in pharmaceutical cold chain infrastructure and HVAC retrofit demand under F-Gas phase-down schedules. Precision fermentation bioreactor instrumentation and Indian vaccine distribution networks provide industry-specific demand inputs.
The analysis sits within stated boundaries; outcomes outside sustained FDA enforcement intensity or accelerated EU refrigerant phase-down would require recalibration. Forecasts reflect documented assumptions on calibration laboratory capacity expansion and Bluetooth module cost trajectories. Practitioners should keep alternative scenarios live as Bundesamt für Sicherheit im Gesundheitswesen oversight stringency and Japanese component export policies evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Measuring Instruments
Temperature Calibrator Market
Measuring Instruments
Base Station Analyzer Market
Measuring Instruments
Global Dimensional Metrology Software Market
Measuring Instruments
India Hydrological and Meteorological Equipment Market
Measuring Instruments
Global Laser Measuring Instrument Market
Measuring Instruments
Global Dissolved Oxygen Meters and Controllers Market
Measuring Instruments
North America Scientific Instruments Market
Measuring Instruments
Air Velocity Meter Market
Measuring Instruments
Global Container Weighing Systems Market
Measuring Instruments
Global Instrument Calibrator Market
Measuring Instruments
Ultraviolet Data Logger Market
Measuring Instruments
Data Acquisition Market
Measuring Instruments
Communication Test and Measurement (Ctandm) Market
Measuring Instruments
Moisture Meter Market
Measuring Instruments
TDS Meter Market
Measuring Instruments
Monitoring Tools Market