
 India Hydrological and Meteorological Equipment Market | 2026-2036
India Hydrological and Meteorological Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
India Hydrological and Meteorological Equipment Market Foresight
IS 9000-grade sensor certification is bifurcating the competitive landscape into precision-tier suppliers and commodity assemblers. Vaisala Oyj leverages its Finnish calibration heritage to dominate high-altitude meteorological deployments across the Western Ghats. Encardio Rite anchors geotechnical-hydrological hybrid instrumentation for dam safety monitoring in the Himalayan region.
India hydrological and meteorological equipment encompasses instruments that measure precipitation, temperature, atmospheric pressure, wind velocity, and water flow parameters using piezoelectric, capacitive, or ultrasonic sensing principles, typically housed in IP65-rated enclosures with data loggers sampling at 1–10 minute intervals for real-time telemetry. The primary purpose spans flood early warning, irrigation scheduling, and climate resilience planning for monsoon-dependent agriculture. Wireless Sensors and Remote Sensing are capturing disproportionate investment as the India Meteorological Department replaces manual observatories with automatic weather station grids. Agricultural Monitoring and Flood Forecasting applications command the largest procurement budgets, though Climate Research instrumentation carries superior margin profiles due to stringent accuracy tolerances.
The Bureau of Indian Standards mandates IS 9000 compliance for meteorological sensor accuracy, while the Central Water Commission enforces hydrological data protocols under the National Hydrology Project. The Ministry of Jal Shakti's directive for real-time reservoir inflow monitoring is accelerating telemetry-equipped gauge adoption. Stakeholders must weigh Make-in-India localization requirements against the performance gap in indigenously manufactured ultrasonic anemometers.
Market Dynamics
The National Hydrology Project is compressing procurement cycles for automatic weather stations while BIS calibration mandates are fragmenting supplier tiers into precision-certified and commodity-grade camps.
Growth Catalysts
- State disaster management expansion:Automated weather station networks are proliferating across Maharashtra's agricultural belt and Bihar's flood-prone districts under centralized disaster preparedness frameworks.
- Ministry of Jal Shakti telemetry mandates:Real-time reservoir inflow monitoring directives are forcing hydrological gauge upgrades with cellular and satellite telemetry modules.
- Monsoon-dependent irrigation scheduling:Micro-irrigation adopters in the Gangetic plains are procuring soil moisture sensors and rain gauges to optimize water application timing.
Market Restraints
- IS 9000 certification bottlenecks:BIS laboratory capacity constraints are stretching sensor validation timelines to 14-18 months for domestic manufacturers.
- Ultrasonic anemometer import dependency:Indigenously manufactured wind sensors exhibit accuracy drift beyond 2% at velocities above 15 m/s, forcing reliance on Finnish and German suppliers.
- High-altitude deployment costs:Western Ghats and Himalayan installations require heated enclosures and anti-icing systems that triple unit economics versus plains deployments.
Strategic Opportunities
- Dam safety instrumentation convergence:Geotechnical-hydrological hybrid monitoring systems for Himalayan reservoir structures represent an underserved specification niche.
- Climate research instrumentation premiumization:Stringent accuracy tolerances for academic and meteorological department procurement carry 40-60% margin premiums over operational-grade equipment.
- Wireless sensor network integration:LoRaWAN and NB-IoT protocol adoption in Andhra Pradesh and Telangana smart village programs is opening retrofit demand for legacy gauge estates.
Industry Challenges
- Field calibration skill scarcity:Certified hydrometeorological technicians are concentrated in IMD and CWC establishments, leaving private operators dependent on annual manufacturer service visits.
- Legacy manual observatory integration:Automatic weather station grids must coexist with 19th-century rainfall and evaporation measurement protocols, creating data reconciliation overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Hydrological and Meteorological Equipment Market |
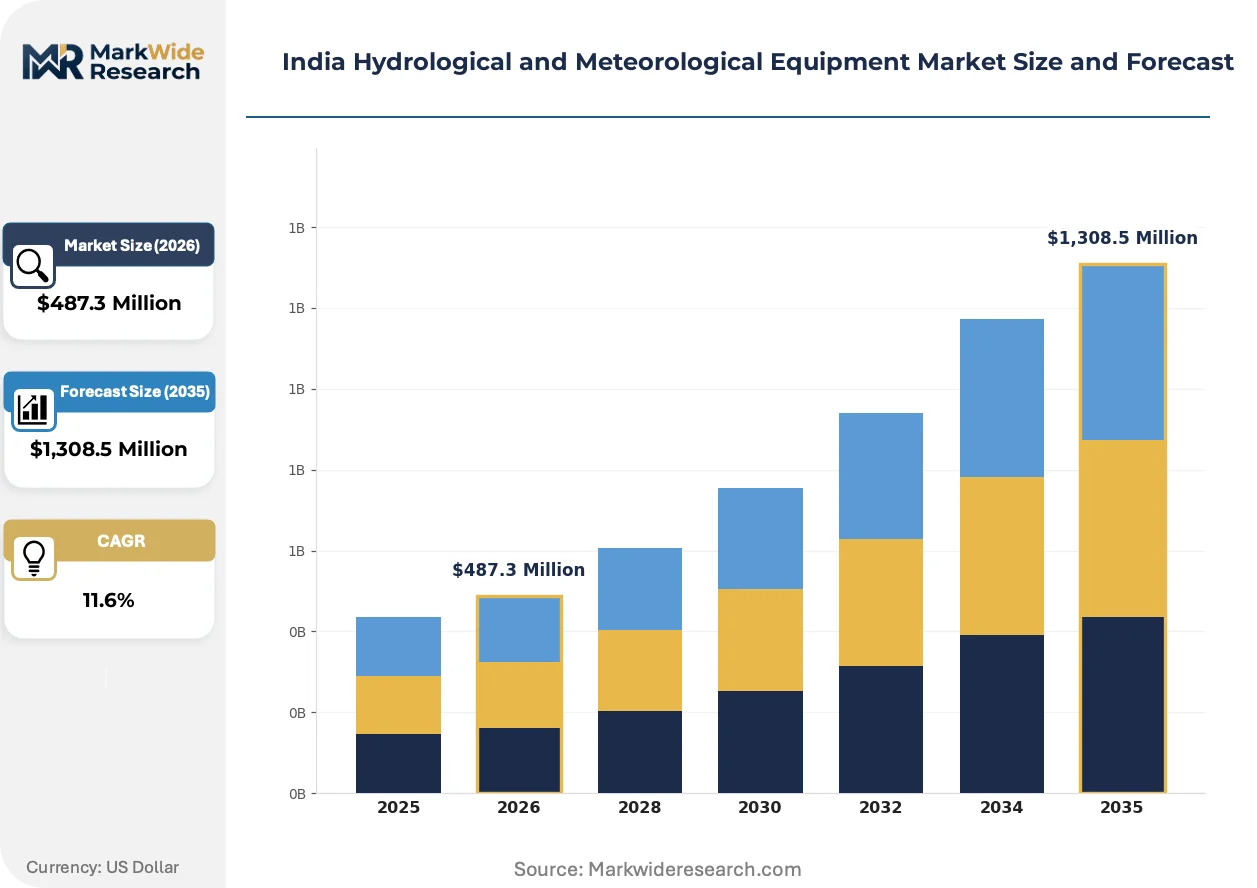
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,308.5 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rain Gauges, Thermometers, Barometers, Anemometers Application: Agricultural Monitoring, Flood Forecasting, Climate Research, Water Resource Management Technology: Wireless Sensors, Satellite Imagery, Remote Sensing, In-Situ Monitoring End User: Government Agencies, Research Institutes, Water Utilities, Environmental Consultants |
| Companies Covered | Hach Company, Vaisala Oyj, Gill Instruments Limited, Astra Microwave Products Limited, Geomax AG, In-Situ Inc., Encardio Rite, SEBA Hydrometrie GmbH & Co. KG, K. R. Instruments, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Hydrological and Meteorological Equipment Market Shifts & Advancements
Sensor fusion architectures and edge computing modules are displacing centralized data logger architectures across India's hydrometeorological infrastructure procurement.
Multi-parameter sensor nodes integrating piezoelectric precipitation detection, capacitive humidity sensing, and ultrasonic wind measurement into single IP65 enclosures are bifurcating procurement specifications. State agricultural departments favor these consolidated units for cost efficiency, while IMD climate research divisions maintain discrete sensor requirements for traceability. The divergence is compressing commodity assembler margins while elevating precision-tier supplier valuations.
Bureau of Indian Standards tightened IS 9000:2022 meteorological sensor accuracy protocols in alignment with WMO CIMO guidelines. Domestic manufacturers face recertification costs exceeding INR 8-15 lakh per sensor variant, accelerating exit of unorganized assemblers. Maharashtra and Gujarat state tenders now mandate BIS-licensed suppliers exclusively, reshaping competitive access to India's largest procurement pools.
Agricultural cooperatives and sugar mill federations are consolidating sensor procurement through state-level rate contracts, displacing individual farmer purchases. Maharashtra's Krishi Udyog federations now negotiate 500-unit automatic weather station lots directly with system integrators. This concentration is visible across western India's cash crop belts, where irrigation advisory services bundle hardware subscriptions with crop insurance products.
India Hydrological and Meteorological Equipment Market Segmentation
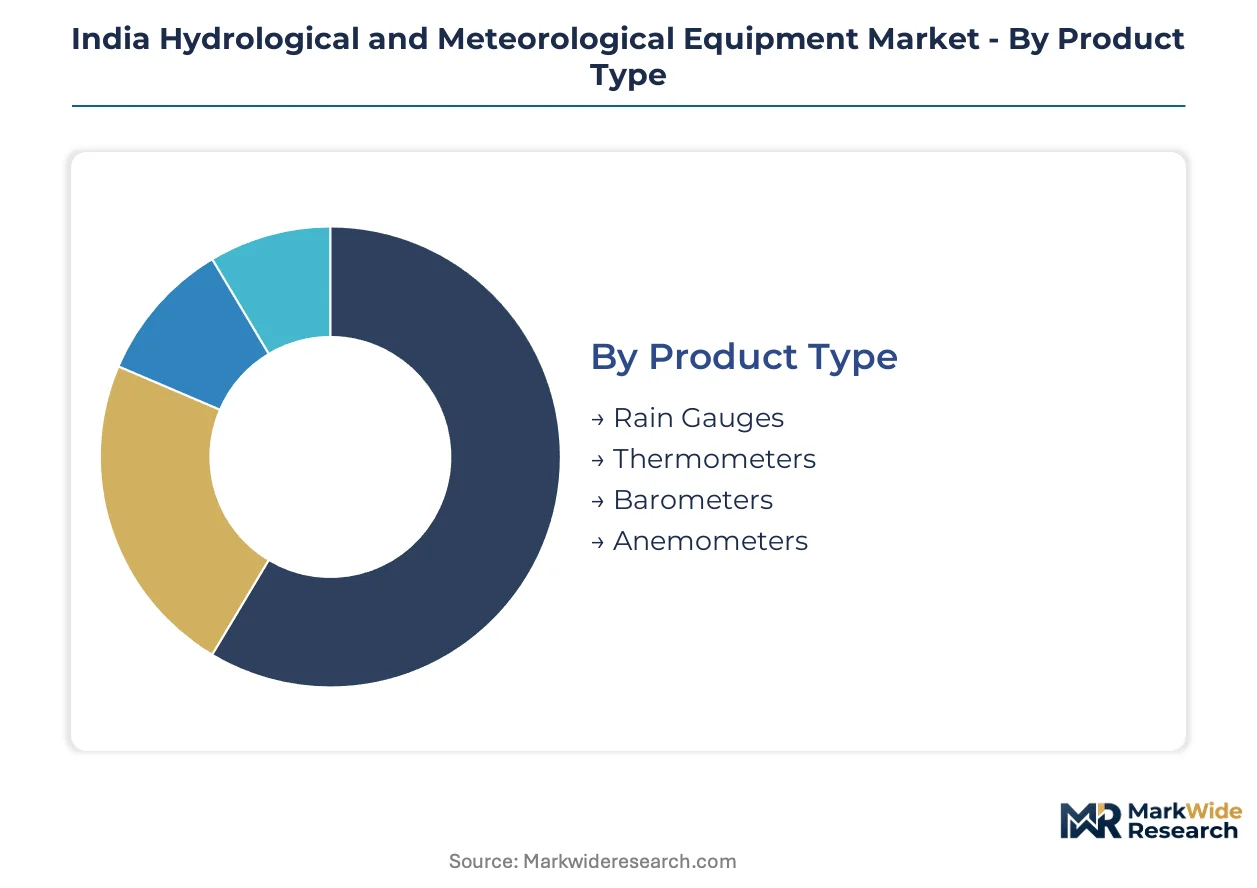
Segmentation in India's hydrometeorological equipment market reveals how procurement authority, technical complexity, and geographic risk concentration shape vendor access. Understanding these divides exposes where BIS certification barriers and telemetry mandates create margin differentiation.
Product Type:
Rain gauges and anemometers dominate domestic manufacturing, while precision barometers remain import-dependent due to calibration infrastructure gaps.
- Rain Gauges:Tipping-bucket mechanisms with 0.1mm resolution dominate Maharashtra sugar belt and Bihar flood zone deployments. Krishi Udyog federations consolidate 500-unit tenders for these units, compressing assembler margins while elevating BIS-certified suppliers.
- Anemometers:Ultrasonic variants with heated enclosures command triple unit economics for Western Ghats installations. Finnish calibration heritage separates precision-tier suppliers from commodity assemblers facing 2% accuracy drift above 15 m/s.
- Thermometers:Platinum resistance sensors with IP65 housings serve IMD automatic weather station grids.
- Barometers:Silicon capacitive pressure transducers require imported calibration standards unavailable in domestic BIS laboratories.
Rain gauges hold the largest share; momentum sits with ultrasonic anemometers as high-altitude telemetry mandates expand.
Application:
Cost tier stratification separates operational-grade flood warning systems from premium climate research instrumentation carrying 40-60% margin premiums.
- Agricultural Monitoring:Soil moisture sensors and micro-irrigation schedulers concentrate in the Gangetic plains. Sugar mill federations bundle hardware subscriptions with crop insurance, shifting procurement from individual farmers to state-level rate contracts.
- Flood Forecasting:Real-time reservoir inflow gauges with cellular telemetry anchor Bihar and Uttar Pradesh disaster management budgets. Ministry of Jal Shakti directives force upgrades across legacy manual observatory networks.
- Climate Research:WMO CIMO-grade traceability requirements restrict supplier pools to precision-tier vendors.
- Water Resource Management:Dam safety instrumentation converges geotechnical and hydrological monitoring for Himalayan reservoir structures.
Agricultural monitoring commands procurement volume; climate research delivers the steepest expansion trajectory in margin terms.
Technology:
Volume concentration favors wireless retrofit demand as Andhra Pradesh and Telangana smart village programs displace centralized data logger architectures.
- Wireless Sensors:LoRaWAN and NB-IoT multi-parameter nodes integrate precipitation, humidity, and wind measurement into single enclosures. State agricultural departments favor these for cost efficiency while IMD maintains discrete sensor requirements for traceability.
- Remote Sensing:Satellite telemetry modules serve Himalayan installations where cellular coverage fails, tripling unit economics versus plains deployments.
- Satellite Imagery:Downscaled precipitation products supplement ground gauge networks in data-sparse regions.
- In-Situ Monitoring:Legacy piezoelectric and capacitive sensors persist where real-time telemetry remains uneconomical.
Wireless sensors capture procurement volume; remote sensing is climbing the fastest as high-altitude mandates harden.
End User:
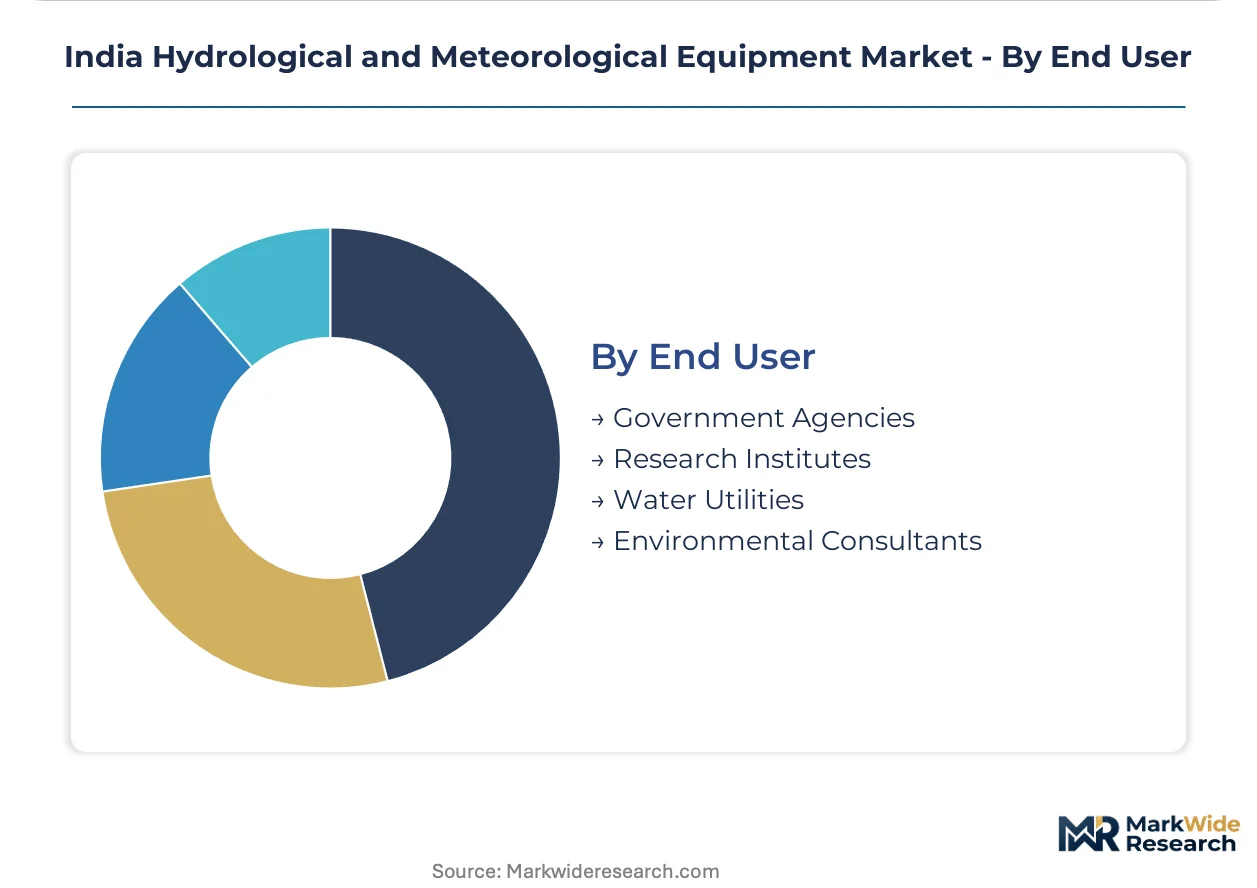
Customer type determines certification burden, with government tenders mandating BIS licensure while research institutes prioritize WMO traceability over cost.
- Government Agencies:State disaster management authorities and the India Meteorological Department drive automatic weather station network expansion. Maharashtra and Gujarat tenders now exclude unlicensed suppliers, reshaping competitive access.
- Water Utilities:Real-time reservoir monitoring directives from the Ministry of Jal Shakti accelerate telemetry-equipped gauge procurement for inflow forecasting.
- Research Institutes:Academic climate programs specify WMO CIMO-grade accuracy tolerances, restricting vendor pools to precision-tier suppliers with Finnish or German calibration heritage.
- Environmental Consultants:Project-based procurement for EIA compliance favors cost-optimized sensor packages without BIS certification requirements.
Government agencies hold the largest share; momentum sits with water utilities as telemetry mandates broaden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision calibration infrastructure concentrates in Maharashtra and Gujarat, where BIS-licensed laboratories serve the largest state procurement pools. The Western Ghats and Himalayan belts command premium deployment economics due to anti-icing and telemetry requirements.
Maharashtra
Sugar mill federations and Krishi Udyog cooperatives drive automatic weather station consolidation through 500-unit rate contracts. State tenders now mandate exclusive BIS licensure, filtering out unorganized assemblers from India's largest procurement volume. Pune and Nashik anchor system integrator clusters serving the agricultural belt.
Bihar
Flood-prone districts along the Gangetic plains anchor disaster management authority spending on real-time reservoir inflow gauges. National Hydrology Project directives from the Central Water Commission compress procurement cycles for cellular telemetry modules. Patna and Muzaffarpur concentrate deployment activity for early warning networks.
Uttar Pradesh
Micro-irrigation adopters in the western sugarcane belt procure soil moisture sensors and tipping-bucket rain gauges for water application optimization. Ministry of Jal Shakti mandates force upgrades across legacy manual observatory estates. Lucknow and Meerut host regional calibration facilities serving the Gangetic corridor.
Karnataka
High-altitude meteorological deployments across the Western Ghats require heated enclosures and Finnish-calibrated ultrasonic anemometers. State disaster management expansion targets coffee and spice belt agro-climatic zones with wireless sensor grids. Bengaluru anchors precision-tier supplier representation and technical service capacity.
Uttarakhand
Himalayan dam safety instrumentation converges geotechnical and hydrological monitoring for reservoir structures. Encardio Rite anchors hybrid system deployment for slope stability and seepage measurement. Dehradun and Rishikesh concentrate Central Water Commission field calibration operations.
India Hydrological and Meteorological Equipment Market Competitive Landscape
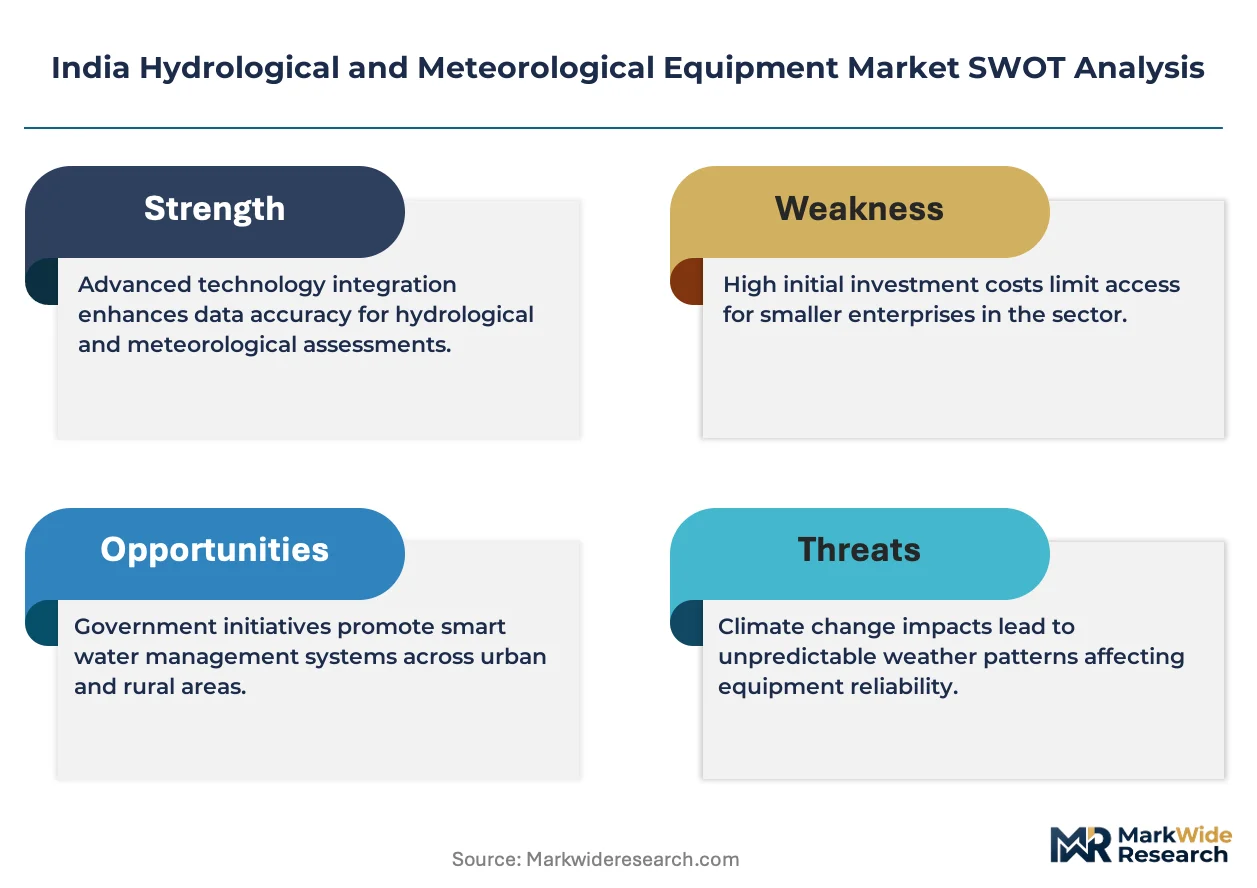
Technology leadership and cost leadership are held by different player archetypes across the supplier base. Finnish and German calibration heritage separates precision-tier vendors serving IMD climate research divisions from domestic assemblers competing on Maharashtra agricultural tenders. The market structures around three strategic archetypes: precision-certified instrumentation specialists, commodity-grade system integrators, and geotechnical-hydrological hybrid providers. Competitive moves concentrate on BIS licensure acquisition and telemetry module partnerships rather than manufacturing scale expansion.
Among precision-tier suppliers, Vaisala Oyj exemplifies the calibration-heritage archetype dominating high-altitude meteorological deployments. Encardio Rite occupies a position within the geotechnical-hydrological convergence segment for Himalayan infrastructure. Gill Instruments Limited represents the mid-tier instrumentation specialist serving state agricultural department wireless sensor requirements.
| Leading Market Players |
|---|
| Hach Company |
| Vaisala Oyj |
| Gill Instruments Limited |
| Astra Microwave Products Limited |
| Geomax AG |
| In-Situ Inc. |
| Encardio Rite |
| SEBA Hydrometrie GmbH & Co. KG |
| K. R. Instruments |
| Others |
Supply & Pricing Matrix
State-level rate contracts for automatic weather station procurement lock in multi-year supply commitments while capping unit price escalation for Maharashtra's Krishi Udyog federations. This contract structure binds BIS-certified manufacturers to volume obligations that stabilize input forecasting for precision sensor components.
Pricing Analysis
BIS IS 9000:2022 dictates the pricing tier structure across the India hydrological and meteorological equipment landscape. Certification-grade stratification separates precision-tier suppliers commanding 40-60% premiums for WMO CIMO-grade traceability from commodity assemblers competing on Maharashtra agricultural tenders. Price compression runs through the unlicensed assembler segment as state disaster management authorities mandate exclusive BIS licensure. Agricultural cooperatives exhibit acute price sensitivity, while research institutes prioritize calibration heritage over cost optimization.
Supply Chain Analysis
Container availability constraints on the Nhava Sheva-Helsinki trade lane elevate landed costs for Finnish-calibrated ultrasonic anemometers. Manufacturing concentration centers on Finland, Germany, and domestic Indian assembly for tipping-bucket rain gauges. Silicon capacitive pressure transducers and platinum resistance sensors draw from specialized foundries in Germany and Japan. Single-source vulnerability persists for heated enclosure subsystems required in Western Ghats deployments. Distribution runs through system integrator clusters in Pune and Bengaluru serving state procurement authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India hydrological and meteorological equipment market represents a high-growth disruption as BIS certification mandates compress supplier tiers and telemetry directives from the Ministry of Jal Shakti force infrastructure replacement cycles.
For Market Incumbents: Consolidate BIS laboratory partnerships to compress 14-18 month recertification timelines threatening market access. Acquire cellular telemetry module capabilities to capture Ministry of Jal Shakti mandates for real-time reservoir monitoring. Vertical integration into heated enclosure manufacturing defends margin position against high-altitude deployment cost escalation. For New Entrants and Emerging Players: Anchor in dam safety instrumentation convergence for Himalayan reservoir structures where geotechnical-hydrological hybrid specifications remain underserved. Target climate research instrumentation premiums through WMO CIMO-grade accuracy investments. Pursue LoRaWAN protocol integration partnerships with Andhra Pradesh and Telangana smart village programs as a go-to-market wedge. For Investors and Strategic Acquirers: Precision-tier instrumentation specialists with Finnish calibration heritage represent the most defensible acquisition archetype for climate research exposure. Long-term viability hinges on BIS licensure moats deepening across state procurement consolidation. Monitor Maharashtra tender exclusivity clauses as the signal for competitive access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| BIS Licensure Acquisition | Maharashtra and Gujarat state tenders now exclude unlicensed suppliers entirely. |
| Telemetry Module Integration | Cellular and satellite modules anchor Ministry of Jal Shakti compliance mandates. |
| Calibration Infrastructure Investment | Domestic BIS laboratory capacity constraints stretch validation timelines to 18 months. |
| Wireless Sensor Protocol Adoption | LoRaWAN and NB-IoT deployments accelerate across Andhra Pradesh smart village grids. |
| Dam Safety Hybrid Systems Development | Himalayan reservoir structures require converged geotechnical-hydrological monitoring specifications. |
Research Methodology
Cross-validation between primary interviews with India Meteorological Department procurement officers, Central Water Commission hydrologists, state disaster management authorities, and BIS certification engineers anchors the qualitative findings. Secondary validation draws from Bureau of Indian Standards calibration protocols, National Hydrology Project directive documents, state tender archives from Maharashtra and Gujarat, and WMO CIMO technical guidelines. Bottom-up unit economics modeling triangulates against top-down state budget allocation analysis.
Sensitivity analysis frames volume projections across product type, application tier, technology protocol, and end-user certification requirements. Segmentation dimensions span precision-grade versus operational-grade equipment, wireless versus wired telemetry architectures, and government agency versus research institute procurement authority. CAGRs derive from historical state budget trajectories and infrastructure replacement cycle analysis. Forecast inputs incorporate BIS laboratory capacity expansion timelines and Ministry of Jal Shakti mandate rollout schedules.
Underlying assumptions cover monsoon variability continuity, BIS certification enforcement consistency, and state fiscal capacity for disaster management expansion, with deviation risk concentrated in calibration infrastructure bottlenecks and import dependency for ultrasonic sensor components. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Measuring Instruments
Temperature Loggers Market
Measuring Instruments
North America Scientific Instruments Market
Measuring Instruments
Global Dimensional Metrology Software Market
Measuring Instruments
Multifunction Calibrators Market
Measuring Instruments
TDS Meter Market
Measuring Instruments
Air Velocity Meter Market
Measuring Instruments
Ultraviolet Data Logger Market
Measuring Instruments
Data Acquisition Market
Measuring Instruments
3D Laser Scanner Market
Measuring Instruments
Network Diagnostic Tools Market
Measuring Instruments
Handheld Wind Anemometer Market
Measuring Instruments
Base Station Analyzer Market
Measuring Instruments
Global Data Acquisition (DAQ) System Market
Measuring Instruments
3D Metrology Market
Measuring Instruments
Americas 3D Metrology Market
Measuring Instruments
Global Reference Thermometer Market