
 Multifunction Calibrators Market | 2026-2036
Multifunction Calibrators Market Size, Share, and Industry Trends Forecast 2026-2036
Multifunction Calibrators Market Foresight
Process manufacturing buyers are gaining share against traditional calibration lab procurement as in-house metrology programs expand, and the demand landscape is bifurcating between centralized service providers and captive shop-floor operations. Fluke Corporation leverages its handheld portfolio to dominate field-service channels where technicians perform loop verification without removing instruments. Yokogawa Electric Corporation anchors its position in Asia-Pacific process industries through tight integration with distributed control system installed bases. Beamex competes by specializing in documenting calibrators that automate paperless compliance workflows for regulated facilities.
A multifunction calibrator is a precision instrument that generates and measures multiple electrical signals—typically voltage, current, resistance, frequency, and thermocouple or RTD simulation—within a single unit, often achieving uncertainties of 0.002% or better for laboratory-grade models. Its primary purpose is to verify and adjust the accuracy of industrial process instrumentation, test equipment, and control loops against traceable standards. Portable units command the largest volume pool as maintenance technicians perform field verification across distributed plant assets, while rack-mount systems capture premium margins in automated test equipment lines where throughput and repeatability determine cost per test. Wireless-enabled models represent the fastest-expanding technology segment as facilities integrate calibrators into plant asset management systems for predictive maintenance scheduling.
The US OSHA process safety management standard mandates documented calibration of safety-critical instrumentation, while the EU Measuring Instruments Directive establishes harmonized conformity requirements for devices used in custody transfer and environmental monitoring. Germany's national metrology institute, PTB, maintains type approval requirements that shape product design priorities for European-market entrants. Buyers should monitor evolving cybersecurity requirements for connected calibrators as industrial IoT adoption blurs the boundary between metrology equipment and networked plant infrastructure.
Market Dynamics
Wireless-enabled calibrators are bifurcating the installed base as facilities retrofit legacy verification workflows with connected asset management architectures, forcing vendors to maintain parallel analog and digital product lines.
Growth Catalysts
- OSHA Process Safety Management:US refineries and chemical plants must document calibration of safety-critical pressure transmitters and temperature loops, sustaining replacement demand for field-portable units.
- Automotive electrification:Battery cell gigafactories in Germany and South Korea require high-throughput verification of thermal management sensors, expanding rack-mount calibrator deployment in metrology labs.
- Predictive maintenance integration:Industrial IoT platforms now ingest calibration drift data to schedule interventions before control loop degradation triggers process excursions.
Market Restraints
- Reference standard volatility:Platinum resistance thermometer elements and precision metal-film resistors face supply concentration from Japanese specialty component manufacturers.
- Metrology-grade silicon scarcity:Discrete voltage references and ADCs achieving sub-ppm stability depend on captive foundry capacity with 26-week lead times.
- EU Measuring Instruments Directive friction:Type approval timelines for custody-transfer-capable calibrators extend 14-18 months, delaying product launches for European process industries.
Strategic Opportunities
- India PLI scheme for precision instruments:Domestic production incentives could localize calibrator assembly for South Asian chemical and pharmaceutical markets currently served by imports.
- Cloud-native calibration software:SaaS platforms automating certificate generation and audit trails create recurring revenue attachments to hardware sales.
- Hydrogen economy instrumentation:High-pressure hydrogen refueling stations require specialized pressure and temperature verification protocols not addressed by general-purpose units.
Industry Challenges
- Deadweight tester obsolescence:Experienced technicians familiar with piston-cylinder primary standards are retiring faster than training programs replace them.
- ISO 17025 accreditation timelines:In-house metrology labs face 12-24 month certification cycles that delay captive calibration program launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multifunction Calibrators Market |
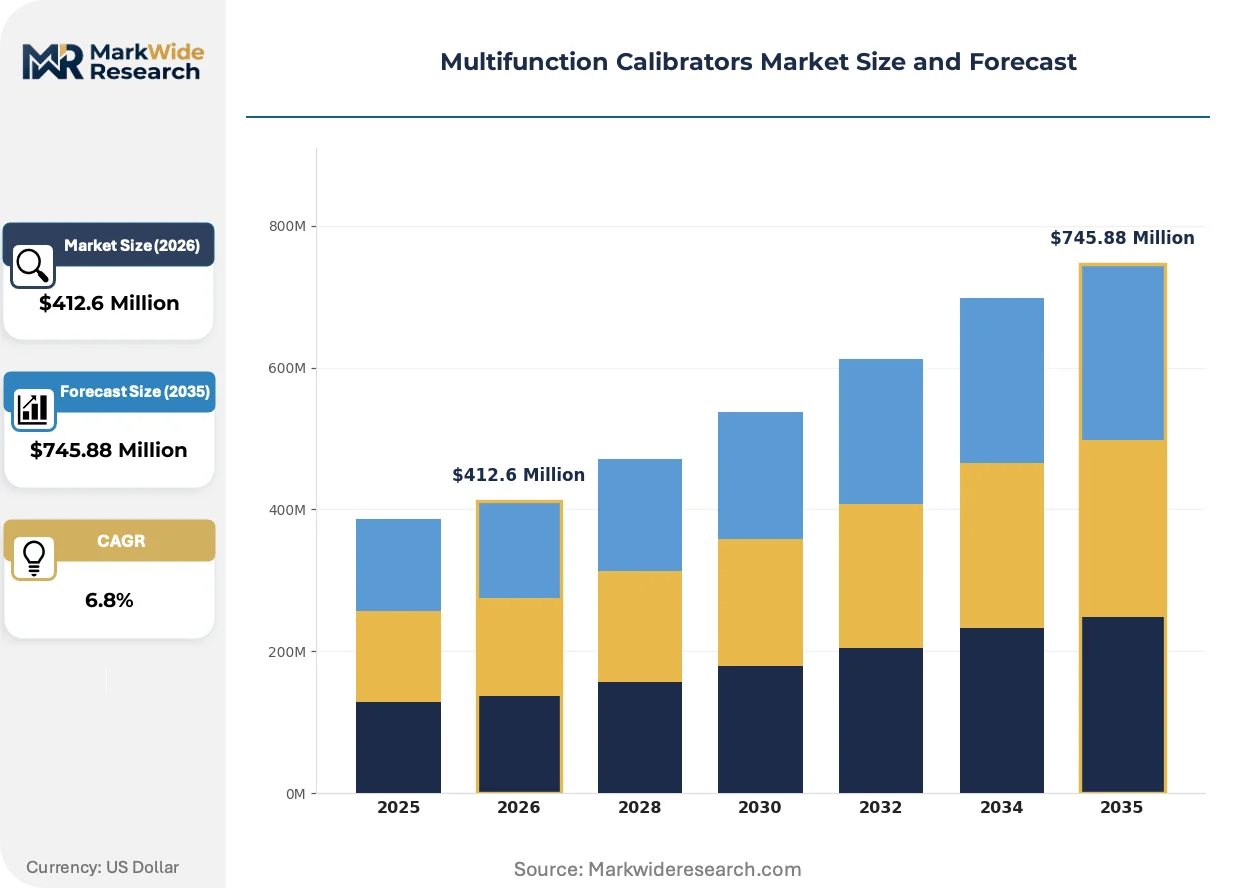
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone, Portable, Rack-Mount, Bench-Top Technology: Digital, Analog, Hybrid, Wireless End User: Manufacturing, Calibration Labs, Educational Institutions, Research Facilities Application: Testing, Measurement, Quality Assurance, Calibration |
| Companies Covered | Fluke Corporation, Yokogawa Electric Corporation, WIKA, Additel Corporation, Beamex, AMETEK, Transmille Ltd, Fortive Corporation, Keysight Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multifunction Calibrators Market Shifts & Advancements
Digital thread architectures are collapsing the boundary between calibration execution and quality system documentation, eliminating transcription errors while exposing instrument fleets to cybersecurity scrutiny previously reserved for control systems.
Automated documenting calibrators are bifurcating the technician workflow by capturing as-found and as-left data directly to tamper-evident databases. Pharmaceutical and food processing facilities in Ireland and Switzerland adopt these units aggressively to satisfy FDA and EMA audit requirements. The technology is compressing demand for standalone data loggers and manual certificate generation services.
REACH restrictions on lead-based solder and cadmium-plated connectors are forcing redesigns of thermocouple simulation modules. European manufacturers now specify tin-silver-copper alloys and nickel-palladium-gold contact finishes, adding material cost but ensuring market access. The F-Gas Regulation's phase-down of refrigerants used in precision temperature baths is simultaneously accelerating adoption of dry-block calibrators for field thermometry.
Buyer consolidation among multinational process operators is concentrating procurement authority at regional headquarters. Instrumentation managers at BASF, Dow, and SABIC now negotiate enterprise calibration service contracts covering multiple sites, displacing plant-level purchasing autonomy. This pattern is most visible in the Rhine-Ruhr industrial corridor and US Gulf Coast petrochemical clusters.
Multifunction Calibrators Market Segmentation
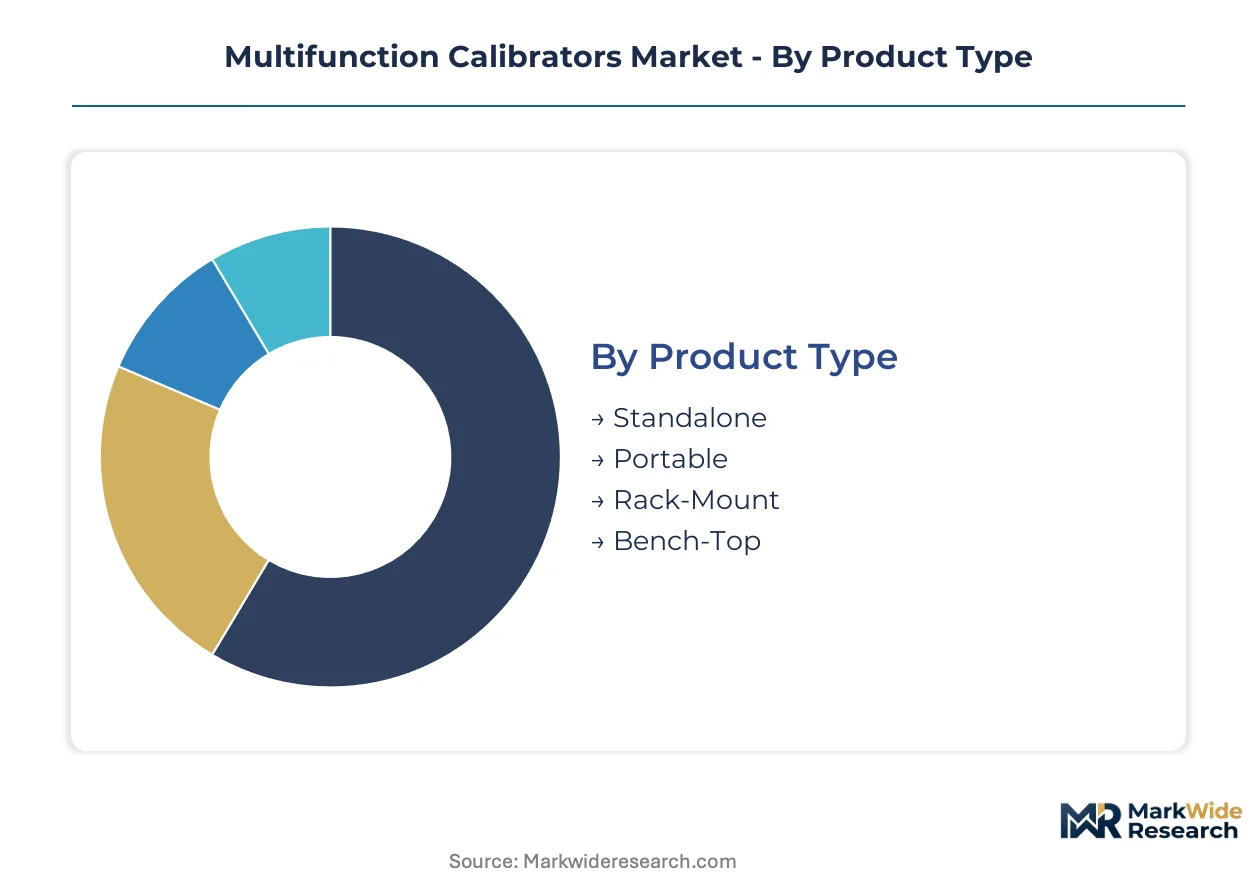
Multifunction calibrator procurement patterns diverge sharply across deployment contexts. Field technicians prioritize portability and battery autonomy, while metrology laboratories demand traceable uncertainty budgets and automated documentation workflows.
Product Type:
Portable units face intensifying substitution pressure from smartphone-connected sensor modules in low-accuracy applications, forcing vendors to defend laboratory-grade specifications as the differentiation anchor.
- Standalone:Self-contained units integrate source and measurement functions without external controller dependency. Demand concentrates in North American oil and gas field operations where technicians perform loop verification in hazardous locations without network connectivity.
- Portable:Battery-powered designs achieve 0.01% accuracy in packages under 3 kilograms. German automotive suppliers deploy these units across distributed stamping and paint shops to reduce instrument removal downtime.
- Rack-Mount:19-inch chassis configurations serve automated test equipment lines with IEEE-488 or LAN-based remote operation.
- Bench-Top:Laboratory-grade systems with touchscreen interfaces and internal reference standards for temperature-controlled environments.
Portable units anchor the volume base while rack-mount systems gain share at the steepest rate in battery manufacturing metrology labs.
Technology:
Cost tier stratification separates premium digital architectures from legacy analog preservation in budget-constrained educational markets.
- Digital:Microprocessor-controlled architectures with 24-bit sigma-delta ADCs and software-defined function generation. South Korean semiconductor fabs specify these units for wafer-level temperature sensor verification.
- Analog:Discrete component designs using precision resistor networks and zener reference diodes. Indian vocational training institutes maintain procurement of these units for fundamental instrumentation instruction.
- Hybrid:Combines analog signal conditioning with digital control and storage.
- Wireless:Bluetooth and Wi-Fi enabled models stream calibration data to plant asset management systems. Pharmaceutical facilities in Ireland adopt these aggressively for paperless FDA compliance workflows.
Digital architectures dominate current procurement volumes while wireless-enabled models are expanding most quickly through predictive maintenance integration.
End User:
Application maturity varies dramatically, with manufacturing's captive calibration programs displacing third-party service providers in process industries.
- Manufacturing:In-house metrology departments at chemical and food processing plants perform scheduled verification of pressure transmitters and temperature loops. US OSHA process safety management mandates sustain replacement demand across Gulf Coast refineries.
- Calibration Labs:ISO 17025 accredited facilities provide traceable calibration services to external clients. Germany's industrial automation corridor maintains dense networks of these service providers.
- Educational Institutions:University engineering programs and technical colleges.
- Research Facilities:National metrology institutes and corporate R&D centers developing next-generation sensor technologies.
Manufacturing end users command the largest revenue pool while calibration labs face margin compression from in-house program expansion.
Application:
Volume concentration in calibration services reflects regulatory documentation requirements that resist automation.
- Testing:Verification of instrument functionality against manufacturer specifications without formal adjustment. Automotive tier-one suppliers in Japan perform incoming inspection of sensor batches using portable calibrators.
- Measurement:Precise quantification of process variables for experimental or diagnostic purposes. Research facilities employ bench-top systems for uncertainty analysis studies.
- Quality Assurance:Production-line verification that instruments remain within tolerance bands.
- Calibration:Formal adjustment of instrument output to match traceable standards with documented before-and-after values. Regulated industries in Switzerland and Ireland prioritize this application for audit readiness.
Calibration applications generate the highest unit margins while testing applications show the steepest volume expansion in incoming inspection protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German calibrator manufacturers export precision instruments to process industries across the Rhine-Ruhr corridor and into Swiss pharmaceutical facilities. The trade flow reflects Europe's dense calibration service network serving automotive and chemical producers.
United States
OSHA process safety management mandates sustain replacement demand for field-portable units across Gulf Coast refineries. EPA compliance documentation requirements extend calibration obligations to environmental monitoring instrumentation. Houston petrochemical clusters deploy wireless-enabled calibrators for predictive maintenance integration.
Germany
Automotive electrification drives high-throughput verification demand at battery cell gigafactories. PTB type approval requirements shape product design priorities for European-market entrants. The industrial automation corridor between Cologne and Dortmund maintains dense third-party calibration service networks.
Japan
Semiconductor fabs specify digital architectures for wafer-level temperature sensor verification. METI industrial standards enforcement maintains rigorous traceability requirements for custody transfer applications. Nagoya automotive suppliers perform incoming inspection protocols using portable units.
South Korea
Battery manufacturing metrology labs deploy rack-mount systems for thermal management sensor verification. MFDS pharmaceutical manufacturing guidelines mandate documented calibration of critical control loops. Seoul-Incheon industrial zones concentrate demand for automated documenting calibrators.
Switzerland
Swissmedic audit requirements drive adoption of paperless compliance workflows in pharmaceutical facilities. REACH restrictions on lead-based solder force redesigns of thermocouple simulation modules. Basel pharmaceutical clusters prioritize calibration applications for FDA and EMA audit readiness.
Multifunction Calibrators Market Competitive Landscape
Listed leaders compete with private specialists across documentation and connectivity capabilities. The vendor base spans three tiers: diversified instrumentation conglomerates, focused metrology specialists, and regional service-integrated providers. Strategic archetypes include field-service dominant handheld portfolios, DCS-integrated system vendors, and documenting compliance specialists. Competitive moves concentrate on cloud-native software attachments and predictive maintenance platform integration.
Within the field-service archetype, Fluke Corporation exemplifies handheld portfolio dominance. Yokogawa Electric Corporation anchors the DCS-integrated tier through Asia-Pacific process industry presence. Beamex occupies the documenting compliance specialist position for regulated facilities.
| Leading Market Players |
|---|
| Fluke Corporation |
| Yokogawa Electric Corporation |
| WIKA |
| Additel Corporation |
| Beamex |
| AMETEK |
| Transmille Ltd |
| Fortive Corporation |
| Keysight Technologies |
| Others |
Supply & Pricing Matrix
OSHA process safety management documentation requirements gate both supplier qualification and price differentiation simultaneously, as vendors must demonstrate traceable calibration capabilities to serve US refineries while ISO 17025 accreditation tiers separate premium laboratory-grade units from economy field-portable alternatives. This regulatory architecture compresses margins at the mid-market tier while concentrating pricing power among established metrology specialists.
Pricing Analysis
Next-generation wireless-enabled calibrators command substantial premiums over legacy analog designs and current-generation digital units without connectivity. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and documentation automation capabilities. Cost compression in economy portable units is intensifying because smartphone-connected sensor modules encroach on low-accuracy applications. Small educational institutions and Indian vocational training programs exhibit highest price sensitivity, while pharmaceutical facilities in Switzerland and Ireland demonstrate lowest sensitivity due to audit-readiness requirements.
Supply Chain Analysis
Inventory buffers for platinum resistance thermometer elements and precision metal-film resistors have thinned to critical levels, with Japanese specialty component manufacturers quoting 26-week lead times for metrology-grade silicon. Supply concentrates in Japan, Germany, and the United States for discrete voltage references and ADCs achieving sub-ppm stability. Raw material dependencies span platinum group metals, high-purity copper alloys, and temperature-stable substrate materials. Single-source vulnerability in Japanese precision resistor networks exposes vendors to allocation risk. Distribution runs through authorized metrology distributors and direct OEM channels serving process industries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as predictive maintenance integration splits demand between connected asset management architectures and legacy analog preservation, creating distinct competitive arenas with divergent capability requirements.
For Market Incumbents: Shield laboratory-grade specification leadership from smartphone-connected sensor module encroachment by accelerating wireless platform integration and deepening backward integration into precision reference component supply. Threat substitution from low-cost Asian digital entrants intensifies in economy portable segments. Certification investment in EU Measuring Instruments Directive type approval preserves European market access against regulatory friction. For New Entrants and Emerging Players: Differentiate on cloud-native calibration software as a recurring revenue attachment to commodity hardware sales. White-space targets include India PLI scheme localization for South Asian chemical markets and hydrogen economy instrumentation protocols for high-pressure refueling stations. Most penetrable segment: automated documenting calibrators for mid-sized pharmaceutical facilities seeking paperless FDA compliance without enterprise-scale procurement authority. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native software tiers as SaaS delivery models reduce hardware-dependent working capital requirements. Long-term viability favors vendors with hybrid hardware-software revenue streams over pure equipment plays. Acquisition target archetype: documenting compliance specialists with established pharmaceutical customer relationships and embedded calibration management platforms. Signal to watch: MFDS and Swissmedic audit requirement harmonization accelerating consolidation among regional service providers.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Calibration Software Launch | SaaS platforms automating certificate generation create recurring revenue attachments at pharmaceutical facilities. |
| Wireless Platform Integration | Bluetooth-enabled models stream drift data to plant asset management systems for predictive maintenance scheduling. |
| Backward Integration into Precision Components | In-house production of voltage references and ADCs insulates margins from Japanese foundry allocation constraints. |
| EU Type Approval Acceleration | Compressed 14-18 month Measuring Instruments Directive timelines prevent competitive displacement in European process industries. |
| Hydrogen Economy Protocol Development | Specialized pressure and temperature verification for high-pressure refueling stations addresses unmet instrumentation requirements. |
Research Methodology
A standing panel of plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads provided ongoing calibration against secondary data from customs records, SEC filings, PTB type approval databases, and industrial automation trade association reports. Primary interviews with instrumentation managers at multinational process operators combined with bottom-up and top-down triangulation across product type, technology generation, end-use industry, and regional regulatory cluster segmentation.
Consistency checks validated volume and value outputs against external benchmarks from national metrology institute procurement disclosures and process industry capital expenditure patterns across the analysis window. The analytical framework modeled deployment context, accuracy tier, connectivity architecture, and documentation automation level as core segmentation dimensions. CAGRs were derived from instrument replacement cycle analysis and regulatory mandate expansion trajectories, with specific inputs including OSHA enforcement activity indices and battery manufacturing capacity buildout announcements.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of process safety documentation or accelerated semiconductor fab construction timelines would require recalibration. Forecasts reflect documented assumptions regarding wireless adoption curves and reference component supply normalization. Specific risk factors include REACH restriction expansion affecting thermocouple module materials and F-Gas Regulation phase-down impacts on temperature bath alternatives. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Measuring Instruments
3D Laser Scanner Market
Measuring Instruments
Network Diagnostic Tools Market
Measuring Instruments
Global Instrument Calibrator Market
Measuring Instruments
Digital Refrigeration Gauge Market
Measuring Instruments
Moisture Meter Market
Measuring Instruments
Air Velocity Meter Market
Measuring Instruments
Base Station Analyzer Market
Measuring Instruments
Ultraviolet Data Logger Market
Measuring Instruments
Handheld Wind Anemometer Market
Measuring Instruments
Data Acquisition Market
Measuring Instruments
Temperature Loggers Market
Measuring Instruments
Communication Test Equipment (CTE) Market
Measuring Instruments
Global Reference Thermometer Market
Measuring Instruments
Borescope Inspection Camera Market
Measuring Instruments
Laser Distance Meter Market
Measuring Instruments
Global Laser Measuring Instrument Market