
 3D Metrology Market | 2026-2036
3D Metrology Market Size, Share, and Industry Trends Forecast 2026-2036
3D Metrology Market Intelligence
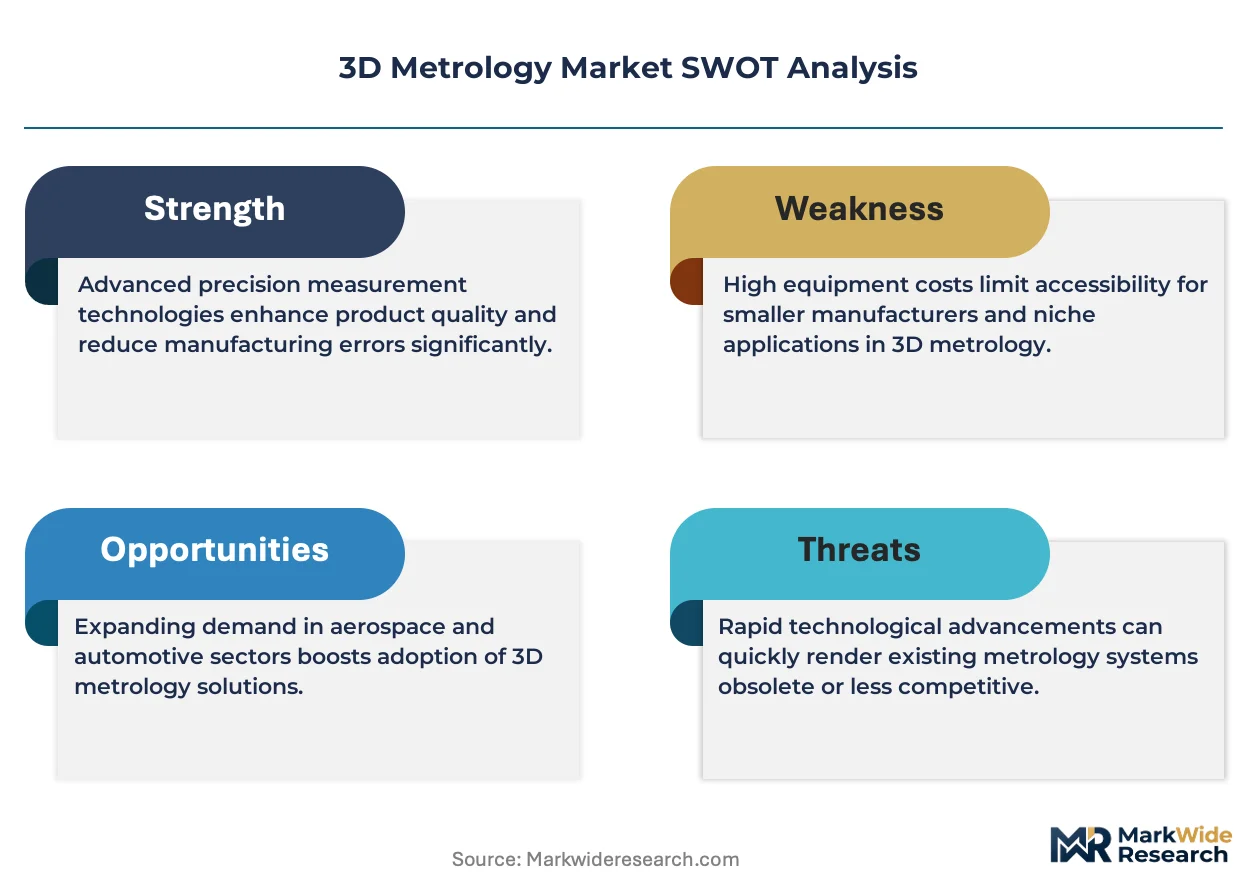
Sub-micron accuracy tiers is redrawing competitive boundaries in 3D metrology. Hexagon AB leverages its probe-to-software integration to dominate large-scale coordinate measuring machine deployments across automotive stamping plants. ZEISS Group anchors its position through captive optical component manufacturing and in-house lens grinding for white light interferometry systems. Renishaw plc differentiates via encoder and probe head backward integration, sustaining margin pools that pure hardware resellers cannot match.
3D metrology encompasses non-contact and contact-based dimensional measurement systems that capture spatial coordinates, surface topology, and geometric deviations against CAD nominal geometries, typically achieving resolutions from nanometer-scale confocal microscopy to millimeter-range photogrammetry for industrial quality assurance and process control. Coordinate measuring machines retain the largest installed base but face margin compression as laser scanner adoption accelerates in automotive body-in-white inspection workflows. Optical comparators occupy a mature niche in precision tooling firms while structured light scanners capture the fastest expansion in electronics manufacturers validating miniaturized connector geometries.
FDA 21 CFR Part 820 quality system regulations and EU MDR traceability requirements compel medical device OEMs to maintain calibrated 3D inspection records with documented measurement uncertainty budgets. ISO 10360 and VDI/VDE 2617 standards govern CMM performance verification, creating compliance-driven replacement cycles that benefit vendors with accredited service networks. Stakeholders must monitor how NIST advancements in computed tomography reference artifacts reshape acceptance testing protocols for additive-manufactured aerospace components.
Market Dynamics
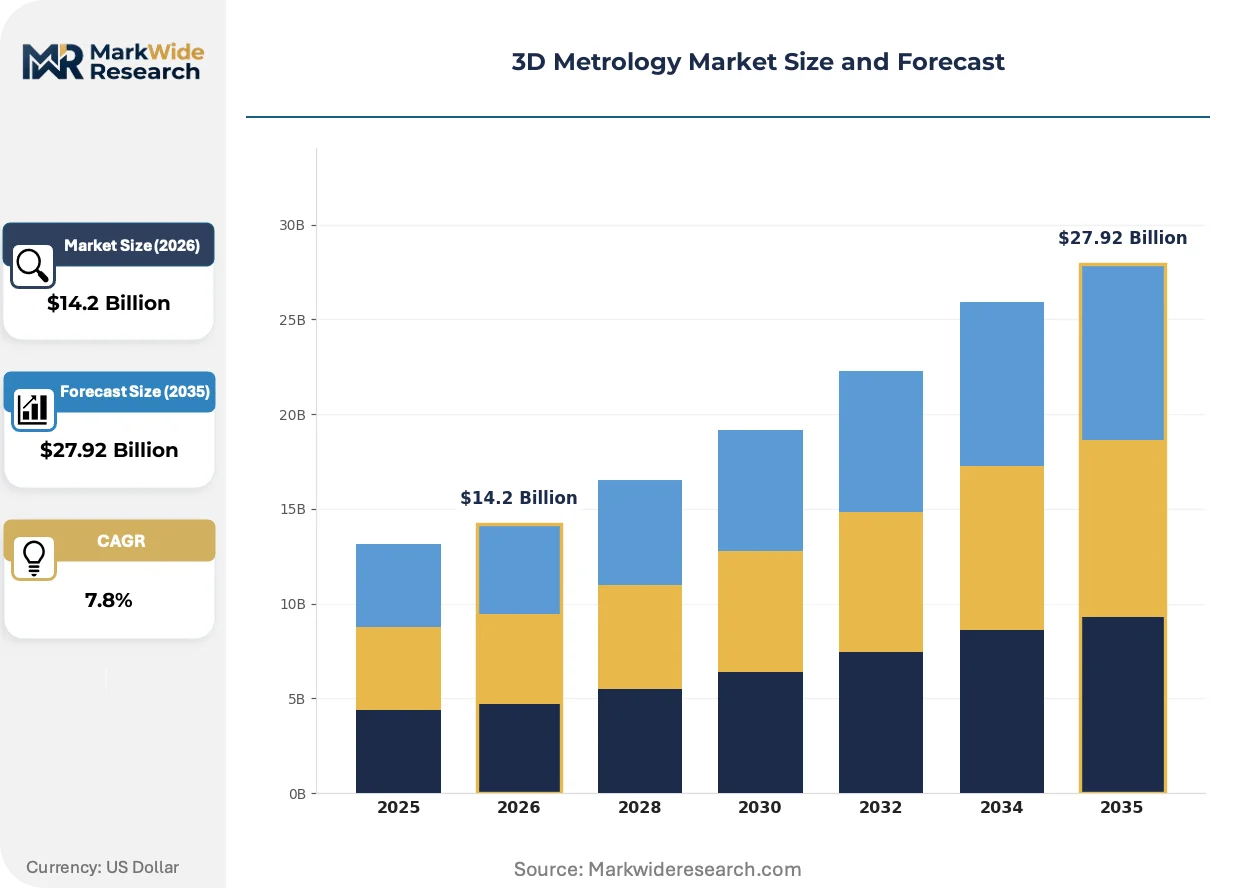
Structured light scanning is displacing tactile probe methods in aerospace and automotive quality assurance, compressing inspection cycle times while tightening traceability requirements under revised ISO 10360 and EU MDR mandates force equipment refresh decisions.
Growth Catalysts
- EU MDR traceability mandates:Medical device manufacturers in Germany and France must maintain calibrated 3D inspection records with documented measurement uncertainty budgets, accelerating replacement of legacy coordinate measuring equipment.
- Miniaturized electronics validation:Structured light scanners capture connector geometries below 50 microns in Bavaria and Baden-Württemberg precision tooling corridors.
- Rhône-Alpes aerospace cluster:Turbine blade verification workflows drive adoption of non-contact optical systems across Safran and Airbus supplier networks.
Market Restraints
- Optical component supply concentration:High-precision lens grinding capabilities concentrate in Jena and Oberkochen, creating single-source dependencies for white light interferometry systems.
- Technical limitation in reflective surfaces:Laser triangulation struggles with polished turbine alloys and chrome-plated medical instruments, requiring secondary tactile verification.
- ISO 10360 accreditation timelines:Performance verification protocols demand 12-18 month calibration cycles that delay new equipment deployment.
Strategic Opportunities
- Computed tomography convergence:X-ray metrology integration with additive manufacturing quality assurance opens acceptance testing for porous aerospace lattice structures.
- Service network unbundling:Independent calibration providers in Stuttgart and Lyon challenge vendor-captive service models through accredited mobile verification units.
- NIST reference artifact advancement:New CT calibration standards enable first-principles measurement traceability for internal geometries in printed medical implants.
Industry Challenges
- Multi-sensor integration complexity:Combining tactile probe, optical, and CT modalities within single coordinate frames demands specialized application engineering scarce in precision tooling firms.
- Measurement uncertainty budgeting:ISO 14253-1 compliance requires documented temperature compensation and probe qualification protocols that extend commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Metrology Market |
| Market Size in 2026 | $14.2 Billion |
| Market Size in 2035 | $27.92 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coordinate Measuring Machines, Laser Scanners, Structured Light Scanners, Optical Comparators, Stylus Probes Technology: Photogrammetry, White Light Interferometry, Confocal Microscopy, Time-of-Flight, Triangulation Application: Quality Control, Reverse Engineering, Prototype Inspection, Dimensional Analysis, Surface Finish Measurement End User: OEMs, Aerospace Suppliers, Precision Tooling Firms, Electronics Manufacturers, Consumer Goods Developers |
| Companies Covered | Hexagon AB, ZEISS Group, FARO Technologies, Mitutoyo Corporation, KEYENCE Corporation, KLA Corporation, Nikon Corporation, Renishaw plc, Jenoptik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Metrology Market Strategic Shifts & Innovations
Sensor fusion architectures and cloud-native inspection software are compressing the traditional hardware-software boundary in dimensional metrology, enabling real-time process correction loops that bypass offline quality departments.
Blue laser scanning is displacing red laser systems in automotive body-in-white inspection. BMW and Volkswagen stamping plants in Munich and Wolfsburg deploy 450nm wavelength scanners that reduce speckle noise on polished steel surfaces. The technology is displacing structured light setups in high-volume production lines where ambient vibration exceeds optical stability thresholds.
EU MDR Article 10 traceability requirements now mandate Unique Device Identification linkage to measurement records for Class IIa and above implants. TÜV SÜD and DEKRA notified bodies enforce documented calibration intervals that compress equipment replacement cycles. German orthopedic manufacturers in Tuttlingen and French spinal implant firms in Bordeaux accelerate optical comparator retirement to meet audit readiness standards.
After-sales service unbundling disrupts traditional vendor lock-in. Tier-1 automotive suppliers in Ingolstadt and aerospace contractors in Toulouse now procure calibration and software maintenance from independent metrology service bureaus. This procurement fragmentation concentrates in precision-dependent sectors where ISO 17025 accreditation outweighs brand loyalty in sourcing decisions.
3D Metrology Market Segmentation
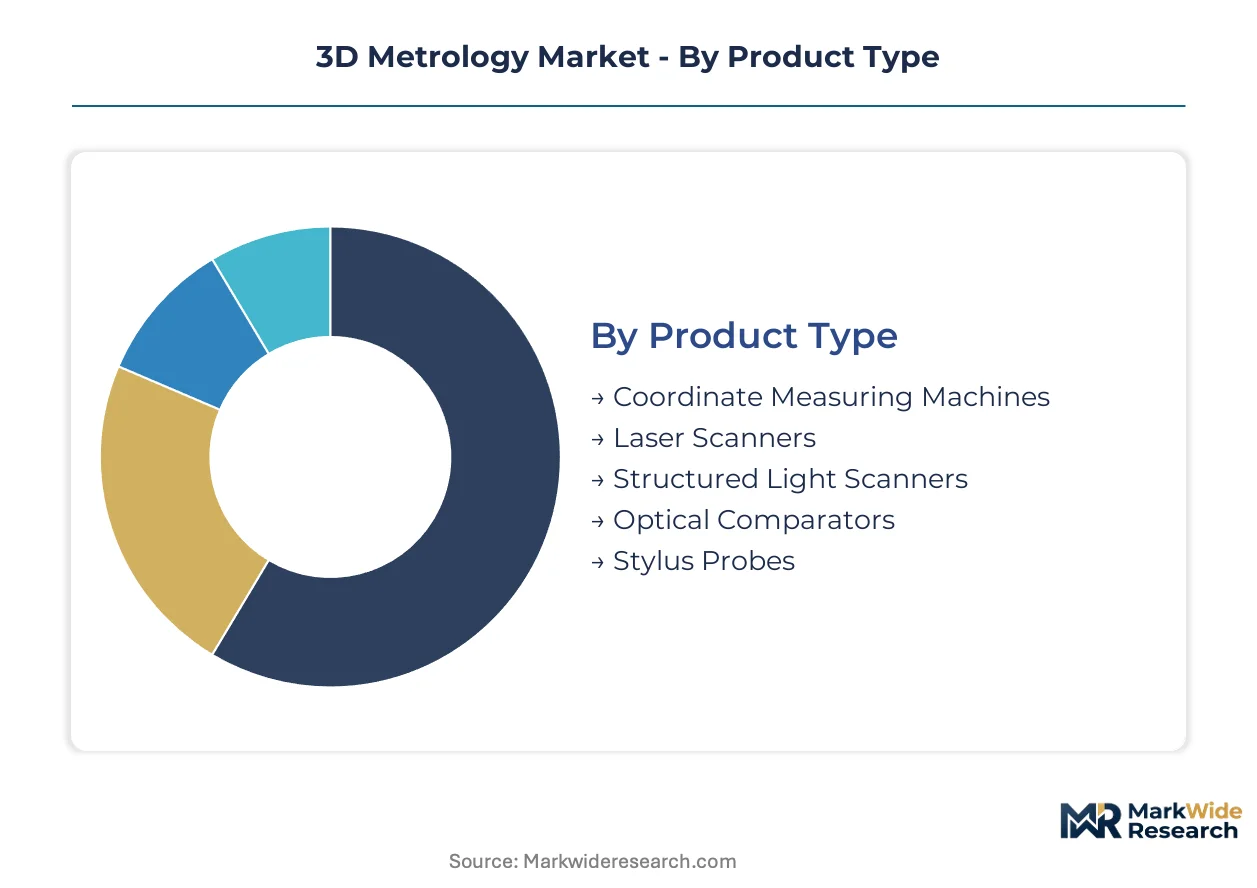
Segmentation in 3D metrology reveals how equipment specifications map to distinct procurement patterns across automotive stamping plants, aerospace supplier networks, and medical device cleanrooms. Technology-product pairings determine whether deployments concentrate in domestic precision tooling corridors or export-led electronics manufacturing hubs.
Product Type:
Coordinate measuring machines and laser scanners anchor domestic demand in German automotive clusters, while structured light systems serve export-driven electronics validation in Asian contract manufacturing.
- Coordinate Measuring Machines:Bridge and gantry configurations dominate large-scale dimensional verification in BMW and Volkswagen stamping operations across Munich and Wolfsburg. Tactile probe systems retain installed base leadership despite margin pressure from non-contact alternatives in body-in-white inspection workflows.
- Laser Scanners:Blue-wavelength 450nm systems reduce speckle interference on polished steel surfaces, displacing structured light in high-vibration production environments. Deployment concentrates in automotive OEM captive metrology labs where throughput requirements exceed optical stability thresholds.
- Structured Light Scanners:Bavarian precision tooling firms deploy these for connector geometries below 50 microns.
- Optical Comparators:Mature installed base in French spinal implant manufacturing around Bordeaux faces EU MDR-driven replacement cycles.
- Stylus Probes:Renishaw encoder-integrated heads sustain margin pools through backward integration into probe head manufacturing.
Coordinate measuring machines hold the largest share; momentum sits with structured light scanners.
Technology:
Cost tiers separate research-grade confocal systems from production-floor triangulation, with white light interferometry occupying premium metrology service bureau pricing.
- Photogrammetry:Millimeter-range accuracy suits large-structure verification in aerospace assembly jigs across Toulouse and Hamburg supplier networks. Portable systems enable field deployment for wind turbine blade inspection where CMM access proves impractical.
- White Light Interferometry:Sub-nanometer resolution demands captive lens grinding capabilities concentrated in Jena and Oberkochen, creating supply-side bottlenecks for surface finish measurement in medical implant manufacturing.
- Confocal Microscopy:Research-grade systems command premium pricing in semiconductor wafer metrology.
- Time-of-Flight:Long-range industrial applications include warehouse automation and construction surveying.
- Triangulation:Laser-based systems struggle with reflective turbine alloys, requiring secondary tactile verification in Safran supplier networks.
White light interferometry commands premium pricing; photogrammetry is expanding most quickly in portable applications.
Application:
Volume concentration in quality control reflects automotive and aerospace compliance mandates, while reverse engineering serves shorter-run medical device prototyping.
- Quality Control:FDA 21 CFR Part 820 and EU MDR traceability requirements compel calibrated 3D inspection records with documented uncertainty budgets. German orthopedic manufacturers in Tuttlingen accelerate equipment refresh cycles to maintain audit readiness under notified body enforcement.
- Reverse Engineering:Legacy part digitization for aftermarket aerospace components drives adoption across MRO facilities in France and Germany. Scan-to-CAD workflows compress redesign timelines for obsolete turbine blade geometries no longer supported by original drawings.
- Prototype Inspection:First-article validation in additive manufacturing requires CT-metrology convergence for internal lattice structures.
- Dimensional Analysis:GD&T verification remains standard across automotive tier-1 suppliers.
- Surface Finish Measurement:ISO 10360 and VDI/VDE 2617 compliance drives replacement of legacy optical comparators.
Quality control dominates volume; reverse engineering shows steepest expansion trajectory.
End User:
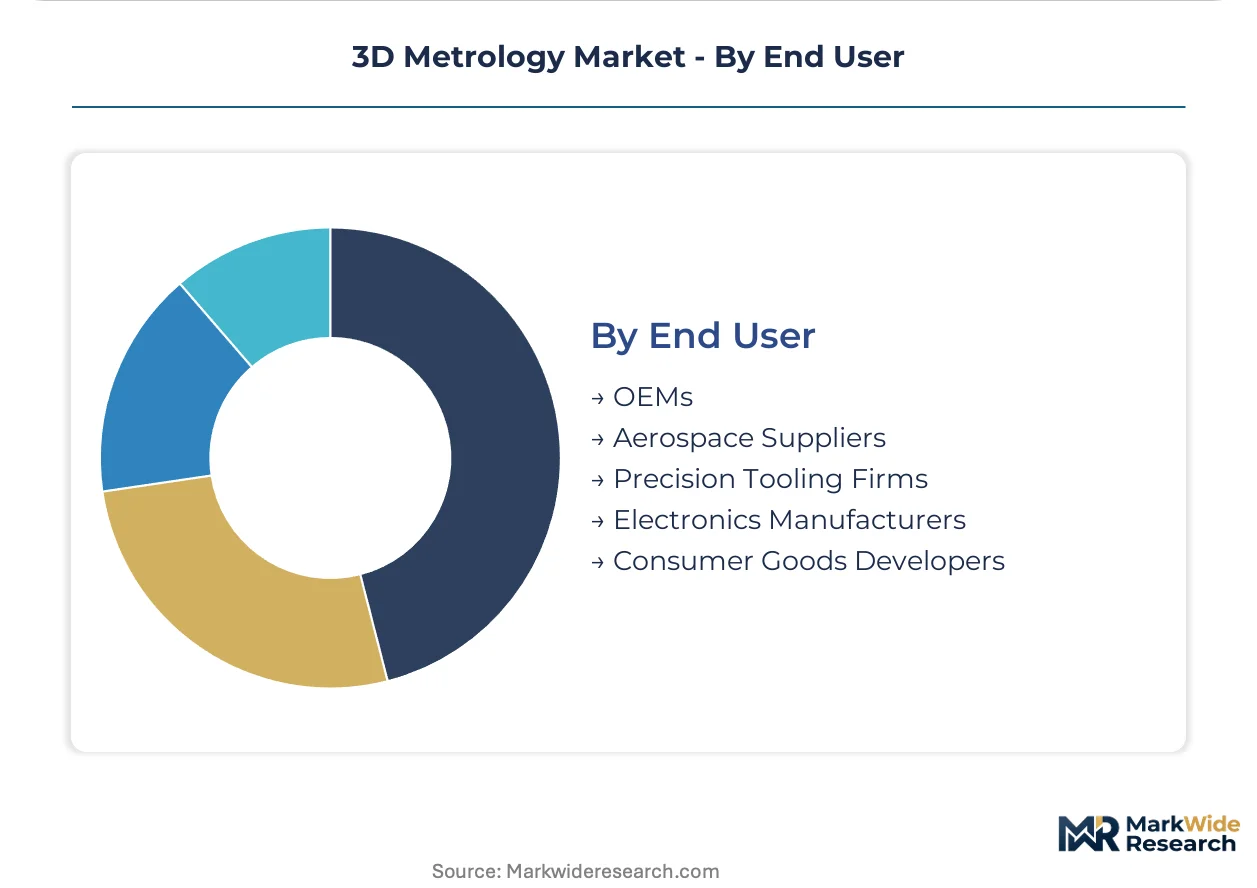
Customer type determines procurement authority concentration, with aerospace suppliers demanding accredited service networks while electronics manufacturers prioritize throughput over brand loyalty.
- OEMs:Captive metrology departments in BMW and Volkswagen maintain ISO 17025-accredited calibration intervals that compress replacement cycles. Vertical integration into probe and software development distinguishes preferred vendor relationships from transactional equipment purchases.
- Aerospace Suppliers:Safran and Airbus supplier networks in Rhône-Alpes mandate structured light scanning for turbine blade verification under NADCAP accreditation requirements. Tier-2 contractors face traceability documentation burdens that favor vendors with European service footprints.
- Precision Tooling Firms:Bavaria and Baden-Württemberg corridors concentrate demand for sub-micron accuracy tiers.
- Electronics Manufacturers:Miniaturized connector validation drives structured light adoption in contract manufacturing.
- Consumer Goods Developers:Packaging and appliance prototyping utilizes mid-range photogrammetry systems.
OEMs command largest procurement volumes; aerospace suppliers are gaining share fastest on NADCAP compliance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-precision lens grinding capabilities concentrate in Jena and Oberkochen, creating supply-side dependencies that ripple through equipment procurement across multiple manufacturing corridors. Equipment vendors with captive optical component production command pricing power in surface finish measurement tiers.
Germany
Bavaria and Baden-Württemberg precision tooling corridors drive structured light scanner adoption for connector geometries below 50 microns. KBA vehicle type approval requirements and EU MDR traceability mandates compress replacement cycles for legacy coordinate measuring equipment. Stuttgart and Munich automotive stamping plants deploy blue-wavelength laser systems for body-in-white inspection workflows.
France
Rhône-Alpes aerospace suppliers mandate non-contact optical verification for turbine blade geometries across Safran and Airbus networks. ANSM medical device regulations enforce documented calibration intervals that accelerate optical comparator retirement. Bordeaux spinal implant manufacturers face TÜV SÜD audit requirements that drive equipment refresh decisions.
United States
FDA 21 CFR Part 820 quality system regulations compel medical device OEMs to maintain calibrated 3D inspection records with measurement uncertainty budgets. NIST advancements in computed tomography reference artifacts reshape acceptance testing protocols for additive-manufactured components. Aerospace clusters in Connecticut and California drive demand for multi-sensor coordinate measuring machines.
Japan
METI industrial standards and JIS certification requirements govern CMM performance verification, creating compliance-driven procurement patterns. Semiconductor wafer metrology commands premium pricing for research-grade confocal microscopy systems. Nagoya automotive suppliers and Tokyo precision electronics manufacturers anchor domestic equipment demand.
China
MIIT equipment quality standards and GB metrology certification requirements structure procurement decisions for domestic manufacturing upgrading. Yangtze River Delta electronics contract manufacturers validate miniaturized connector geometries through structured light deployment. Shenzhen and Shanghai automotive stamping operations expand non-contact inspection capacity.
3D Metrology Market Key Industry Players
Concentration sits with diversified measurement technology conglomerates that span probe hardware through inspection software integration. The vendor base stratifies across three tiers: integrated metrology platforms with captive optical manufacturing, specialized encoder and probe head producers with backward integration into precision components, and regional equipment assemblers dependent on imported subsystems. Dominant competitive moves include M&A to acquire optical component capabilities and strategic partnerships to embed cloud-native inspection software within automotive quality workflows.
Among European-integrated measurement specialists, Hexagon AB, ZEISS Group, and Renishaw plc exemplify distinct archetype positions. Hexagon represents the platform-integrated model spanning probe hardware through software ecosystems. ZEISS occupies a position anchored in captive optical component manufacturing and in-house lens grinding capabilities. Renishaw sits within the precision component specialist tier, with backward integration into encoder and probe head production sustaining margin structures that pure hardware resellers cannot match.
| Leading Market Players |
|---|
| Hexagon AB |
| ZEISS Group |
| FARO Technologies |
| Mitutoyo Corporation |
| KEYENCE Corporation |
| KLA Corporation |
| Nikon Corporation |
| Renishaw plc |
| Jenoptik |
| Others |
Cost & Logistics Intelligence
Eighteen-month calibration cycles for ISO 10360 accreditation create inventory absorption patterns that concentrate pricing power with vendors maintaining captive service networks across German and French precision tooling corridors.
Pricing Analysis
EU MDR Article 10 dictates the pricing tier structure across 3D metrology equipment procurement. Three-tier pricing structure across premium, standard, and economy levels separates NADCAP-accredited multi-sensor systems from production-floor laser scanners and entry-level optical comparators. Price differentiation rests on ISO 17025 certification status and after-sales service bundling. Margins are tightening due to independent calibration providers in Stuttgart and Lyon unbundling vendor-captive maintenance contracts. Electronics manufacturers in contract manufacturing hubs exhibit highest price sensitivity; aerospace suppliers under NADCAP mandates show lowest.
Supply Chain Analysis
Germany and Japan anchor high-precision lens grinding and encoder manufacturing for 3D metrology subsystems. Optical component production draws from specialized glass substrates and rare-earth doped laser sources. Supply chain risk centers on single-source dependencies for white light interferometry optics concentrated in Jena and Oberkochen. Distribution runs through OEM captive metrology departments, tier-1 automotive supplier labs, and accredited service bureaus.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward tier-1 automotive suppliers and aerospace contractors consolidating procurement authority through multi-site framework agreements.
For Market Incumbents: Consolidate backward integration into probe head and encoder manufacturing to defend margin pools against pure hardware resellers. Lock in NADCAP-accredited service network density across Rhône-Alpes and Bavaria before independent calibration providers capture ISO 17025 market share. Prioritize sensor fusion R&D to maintain platform integration advantages over modular competitors. For New Entrants and Emerging Players: DEKRA and TÜV SÜD fast-track certification for optical comparator replacement cycles offers entry into French spinal implant and German orthopedic manufacturing corridors. Target EU MDR-driven equipment refresh in Tuttlingen and Bordeaux where audit readiness demands compress replacement timelines. Lead with cloud-native inspection software partnerships to bypass hardware development barriers. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-locked replacement cycle play because regulatory traceability mandates create non-discretionary demand independent of industrial capex cycles. Acquisition focus: mid-cap specialists with captive optical component production and existing ISO 17025 accreditation footprints. Signal to monitor: NIST CT reference artifact adoption rates reshaping acceptance testing protocols for additive-manufactured aerospace components.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Components | Captive lens grinding capabilities in Jena and Oberkochen insulate margin pools from supply concentration risk. |
| ISO 17025 Accreditation Expansion | Mobile verification units in Stuttgart and Lyon challenge vendor-captive service lock-in across precision tooling corridors. |
| Sensor Fusion Platform Development | Multi-sensor CMM architectures address NADCAP turbine blade verification demands from Safran and Airbus supplier networks. |
| Cloud-Native Inspection Software Partnership | Real-time process correction loops bypass offline quality departments in BMW and Volkswagen stamping plants. |
| CT-Metrology Convergence Investment | X-ray metrology integration opens acceptance testing for porous aerospace lattice structures under evolving NIST standards. |
Research Approach
Two parallel data streams informed the analysis: primary field engagement with metrology equipment vendors, automotive quality directors, aerospace supplier quality engineers, and independent calibration service operators; and secondary validation against ISO 10360 performance verification protocols, EU MDR regulatory filings, FDA 21 CFR Part 820 quality system records, and NIST measurement science publications. Bottom-up equipment shipment analysis triangulated against top-down industrial capex tracking across German automotive clusters and French aerospace networks.
Across the analysis window, the quantitative framework modeled demand across product type, technology tier, application workflow, and end-user procurement authority dimensions. CAGRs were derived from segmented unit economics and replacement cycle timing under regulatory compliance mandates. Forecast inputs incorporated EU MDR enforcement trajectories, NIST CT reference artifact development timelines, and NADCAP accreditation expansion patterns.
Decision-makers should treat outputs as directional under stable regulatory enforcement and continued aerospace production growth assumptions; material deviation in MDR audit intensity or additive manufacturing adoption would warrant model refresh. Recalibration cycles align with material shifts in notified body enforcement patterns and NIST measurement standard releases.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Measuring Instruments
Multifunction Calibrators Market
Measuring Instruments
Temperature Loggers Market
Measuring Instruments
3D Laser Scanner Market
Measuring Instruments
Global Data Acquisition (DAQ) System Market
Measuring Instruments
Data Acquisition Market
Measuring Instruments
Air Velocity Meter Market
Measuring Instruments
Monitoring Tools Market
Measuring Instruments
Borescope Inspection Camera Market
Measuring Instruments
India Hydrological and Meteorological Equipment Market
Measuring Instruments
Global Dissolved Oxygen Meters and Controllers Market
Measuring Instruments
Base Station Analyzer Market
Measuring Instruments
Global Reference Thermometer Market
Measuring Instruments
Global Process Instrumentation Market
Measuring Instruments
Communication Test and Measurement (Ctandm) Market
Measuring Instruments
Ultraviolet Data Logger Market
Measuring Instruments
Moisture Meter Market