
 North America Scientific Instruments Market | 2026-2036
North America Scientific Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
North America Scientific Instruments Market Intelligence
The EPA's enhanced environmental monitoring mandates under the Clean Air Act is rebalancing procurement priorities toward detection instruments with real-time data capabilities. Thermo Fisher Scientific leverages its chromatography portfolio to anchor demand from pharmaceutical quality control labs. Agilent Technologies specializes in mass spectrometry platforms that sustain its position in clinical testing workflows. Danaher Corporation controls the life sciences instrumentation channel through integrated workflow solutions spanning sample preparation to analysis.
Scientific instruments encompass precision-engineered devices designed to measure, analyze, detect, or visualize physical, chemical, or biological properties, typically achieving detection thresholds in parts per billion and operating under controlled environmental conditions to ensure reproducibility. These instruments serve critical functions in verifying product quality, advancing research discoveries, and ensuring regulatory compliance across industrial and academic settings. Analytical instruments command the largest share of product type revenue due to recurring consumables attachment and service contracts. Mass spectrometry technology segments are expanding fastest within pharmaceutical applications where molecular specificity requirements intensify. Research labs represent the most mature end user category, while environmental agencies present emerging demand as climate monitoring budgets expand.
The FDA enforces Current Good Manufacturing Practice regulations that dictate calibration protocols and data integrity standards for instruments used in pharmaceutical production. The EPA administers testing method certifications under the Clean Water Act and Safe Drinking Water Act that directly specify instrument performance criteria. OSHA laboratory safety standards further shape equipment specifications through exposure monitoring requirements. Stakeholders must monitor how evolving EPA method updates and FDA guidance on analytical procedure validation will reshape instrument replacement cycles and qualification documentation burdens.
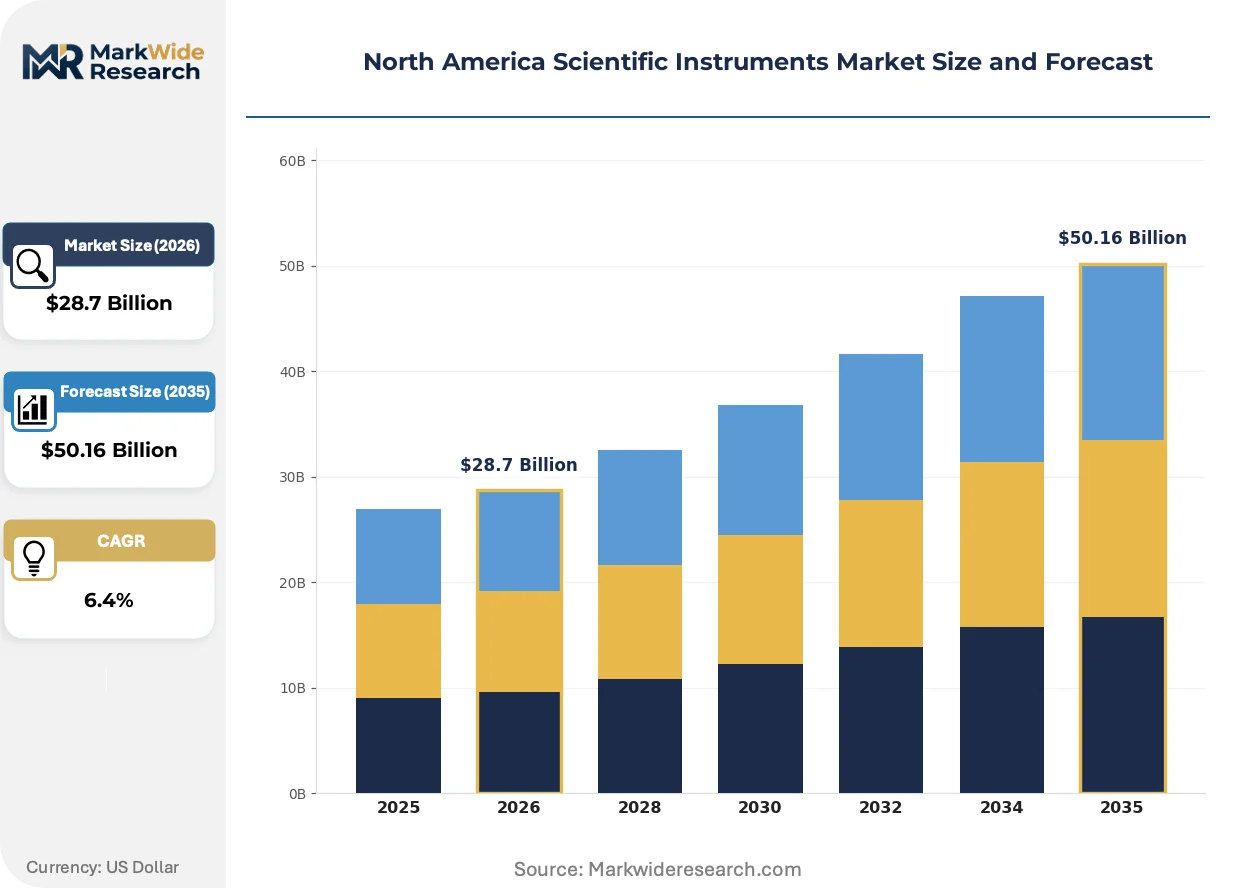
Market Dynamics
The EPA's real-time emissions monitoring mandates are compressing replacement cycles for legacy detection equipment, forcing laboratories to prioritize connected instrument platforms over standalone analyzers.
Growth Catalysts
- Clean Air Act enforcement:The EPA's updated continuous emissions monitoring requirements are mandating networked detection systems across industrial facilities in the United States and Canada.
- Biotech corridor expansion:Pharmaceutical manufacturing clusters around Boston and San Diego are scaling analytical instrument procurement for quality control workflows.
- Mass spectrometry advancement:Molecular specificity improvements in LC-MS platforms are accelerating adoption for complex biologic characterization in drug development pipelines.
Market Restraints
- Precision optics supply concentration:German and Japanese suppliers dominate high-grade optical component manufacturing, creating single-source vulnerability for spectrometer producers.
- FDA validation documentation burden:Current Good Manufacturing Practice requirements for analytical procedure qualification extend instrument deployment timelines by 12-18 months.
- Helium scarcity:Gas chromatography systems face input cost volatility as United States federal helium reserve depletion constrains carrier gas supply.
Strategic Opportunities
- Environmental agency budgets:Climate monitoring appropriations at state-level environmental departments in California and New York are creating instrument procurement white space outside traditional research channels.
- AI-driven predictive maintenance:Machine learning algorithms are converging with sensor networks to enable remote instrument diagnostics, opening subscription revenue models.
- Mexico manufacturing expansion:Nearshoring of pharmaceutical production to Baja California and Querétaro is extending analytical instrument demand south of the United States border.
Industry Challenges
- Metrology talent scarcity:Qualified calibration technicians and field service engineers are in short supply across the Great Lakes and Pacific Northwest instrument hubs.
- Legacy system integration:Pharmaceutical quality control labs face complexity bridging 21 CFR Part 11-compliant data systems with decades-old chromatography hardware.
- ISO 17025 accreditation timelines:Third-party laboratory certification backlogs are delaying new facility commissioning and instrument qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Scientific Instruments Market |
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $50.16 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analytical Instruments, Laboratory Equipment, Detection Instruments, Measurement Devices End User: Research Labs, Educational Institutions, Pharmaceutical Companies, Environmental Agencies Technology: Chromatography, Spectroscopy, Microscopy, Mass Spectrometry Application: Quality Control, Research & Development, Clinical Testing, Environmental Analysis |
| Companies Covered | Thermo Fisher Scientific, Agilent Technologies, Danaher Corporation, PerkinElmer, Shimadzu Corporation, Waters Corporation, Bruker Corporation, Mettler Toledo, Bio-Rad Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Scientific Instruments Market Strategic Shifts & Innovations
Connected instrument architectures and automated sample handling are displacing manual workflows, while regulatory data integrity requirements are reshaping software validation priorities across laboratory environments.
Modular liquid chromatography platforms with embedded IoT sensors are integrating predictive maintenance algorithms directly into instrument firmware. Pharmaceutical quality control labs in New Jersey and North Carolina are deploying these systems at scale to minimize unplanned downtime. The technology is integrating service revenue streams with hardware sales, compressing traditional aftermarket fragmentation.
The FDA's draft guidance on computerized systems in manufacturing facilities is tightening audit trail requirements for electronic records generated by analytical instruments. This policy shift is forcing chromatography data system upgrades across generic drug manufacturing sites. United States contract manufacturing organizations are responding by consolidating instrument fleets under single-vendor managed service agreements.
Consolidated procurement through group purchasing organizations is concentrating buying power among the largest academic medical centers and pharmaceutical conglomerates. Independent distributors in the Midwest and Southeast are losing share to direct manufacturer relationships and integrated supply contracts. Canada is exhibiting this pattern most acutely as provincial health authorities centralize laboratory capital equipment decisions.
North America Scientific Instruments Market Segmentation
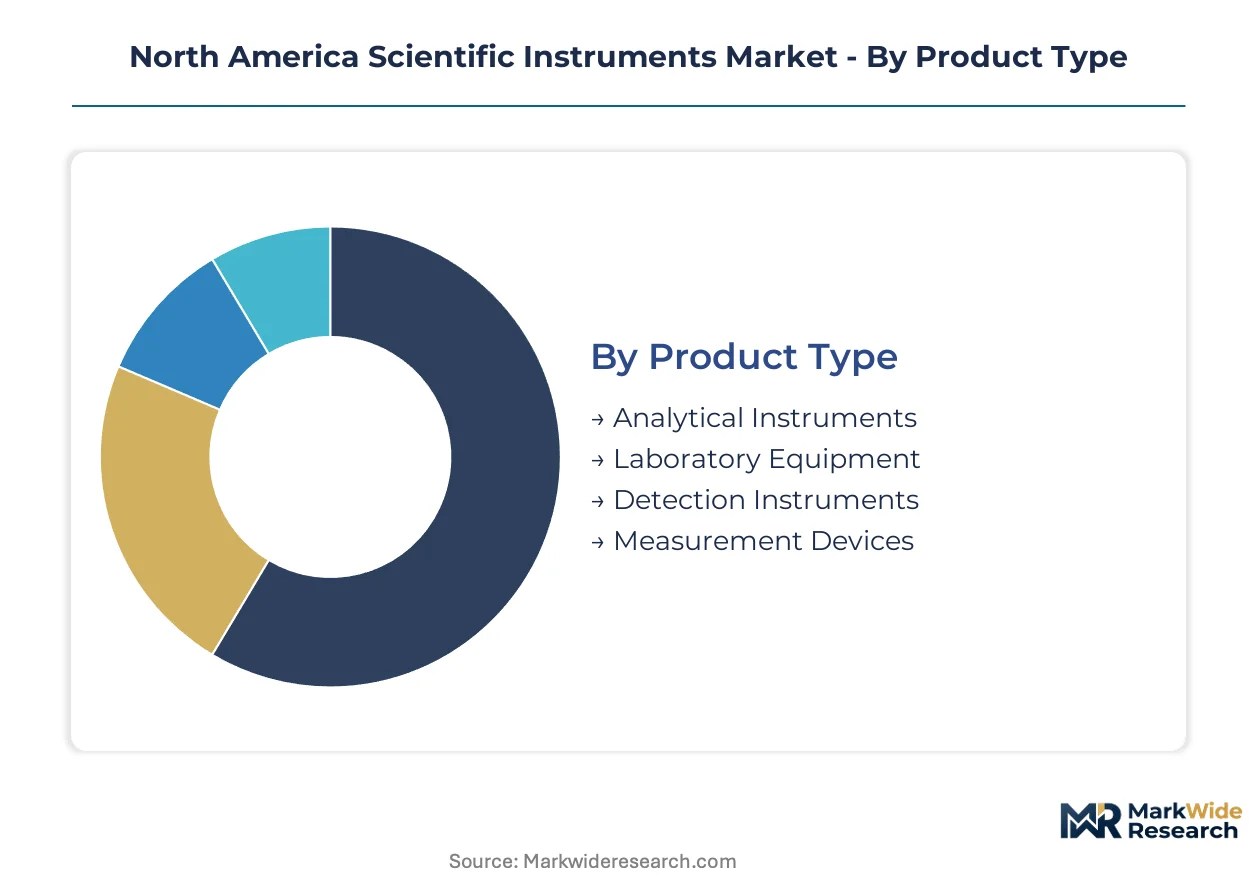
Segmentation in the North America Scientific Instruments Market reveals how capital deployment, regulatory pressure, and end-use specialization create distinct procurement patterns across product categories and customer types.
Product Type:
Capital intensity varies sharply across product categories, with analytical platforms requiring the heaviest upfront investment due to precision engineering and embedded software ecosystems.
- Analytical Instruments:Chromatography and spectrometry systems dominate laboratory capital budgets through precision detection capabilities and recurring consumables attachment. Pharmaceutical quality control labs in New Jersey and North Carolina are scaling procurement of these platforms to meet FDA data integrity mandates.
- Detection Instruments:Real-time emissions monitoring systems command premium pricing as EPA Clean Air Act enforcement mandates networked sensor deployment across industrial facilities. California and Texas refineries are replacing legacy standalone analyzers with connected detection architectures.
- Laboratory Equipment:Centrifuges, incubators, and sample preparation systems serve high-volume research operations with shorter replacement cycles.
- Measurement Devices:Precision metrology tools support manufacturing quality assurance with moderate capital requirements and standardized calibration protocols.
Analytical Instruments absorb the bulk of installed capacity; Detection Instruments are expanding most quickly.
End User:
Customer type determines purchasing authority complexity, with consolidated pharmaceutical conglomerates wielding greater negotiating leverage than fragmented academic buyers.
- Pharmaceutical Companies:Quality control workflows at Boston and San Diego biotech corridors drive demand for validated chromatography and mass spectrometry platforms. FDA Current Good Manufacturing Practice requirements extend instrument qualification timelines and favor single-vendor managed service agreements.
- Research Labs:Academic and government research facilities represent the most mature customer category with established procurement channels and standardized equipment specifications.
- Environmental Agencies:State-level departments in California and New York are emerging as instrument buyers as climate monitoring appropriations expand beyond traditional research channels.
- Educational Institutions:Undergraduate teaching laboratories prioritize cost-efficient equipment packages with simplified maintenance requirements.
Pharmaceutical Companies command the largest share of premium instrument procurement; Environmental Agencies are climbing the fastest as regulatory monitoring budgets expand.
Technology:
Technology selection hinges on molecular specificity requirements, with mass spectrometry platforms demanding the most specialized operator expertise and infrastructure investment.
- Mass Spectrometry:LC-MS and GC-MS platforms achieve detection thresholds in parts per billion for complex biologic characterization in drug development pipelines. Helium scarcity constraints from United States federal reserve depletion are forcing carrier gas substitution strategies.
- Chromatography:Liquid and gas chromatography systems anchor pharmaceutical quality control workflows with modular architectures enabling predictive maintenance integration.
- Spectroscopy:Optical and mass-based detection methods serve environmental monitoring and materials science applications with moderate technical complexity.
- Microscopy:Electron and optical microscopy platforms support cellular and materials research with specialized sample preparation requirements.
Chromatography holds the largest installed base; Mass Spectrometry is gaining share fastest on molecular specificity advancements.
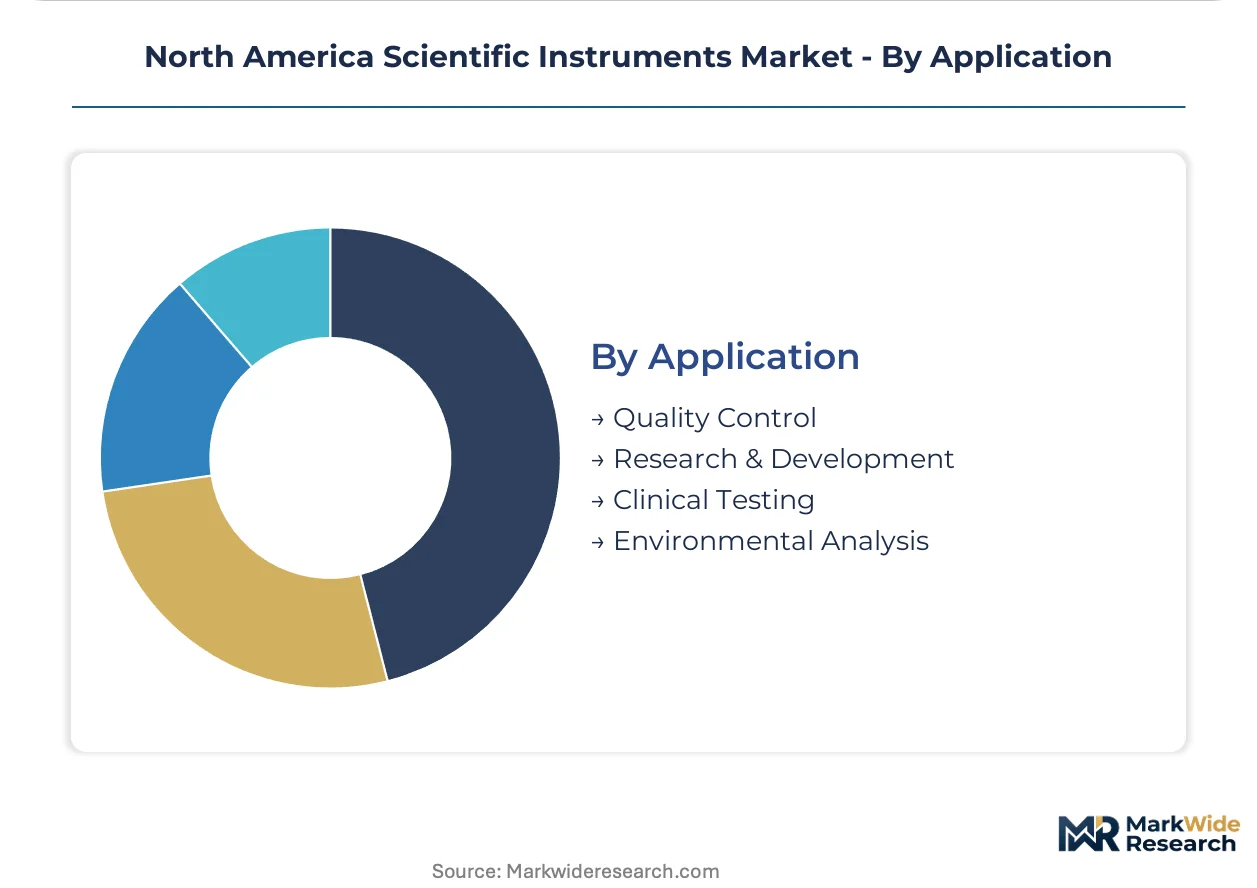
Application:
Application focus shapes software validation priorities, with regulated manufacturing environments imposing stricter data integrity requirements than exploratory research settings.
- Quality Control:Pharmaceutical manufacturing sites deploy validated analytical instruments under FDA 21 CFR Part 11 compliance with comprehensive audit trail capabilities. Generic drug manufacturers are consolidating instrument fleets under managed service agreements to streamline qualification documentation.
- Research & Development:Discovery-phase laboratories prioritize instrumental flexibility and method development speed over regulatory compliance features.
- Clinical Testing:Diagnostic laboratories require high-throughput platforms with standardized protocols and inter-laboratory reproducibility certification.
- Environmental Analysis:EPA method-specified testing protocols dictate instrument performance criteria for water and air quality monitoring applications.
Quality Control represents the largest application segment; Environmental Analysis shows the steepest expansion trajectory on regulatory enforcement intensification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States dominates instrument consumption while manufacturing concentrates in Germany and Japan. Canada and Mexico serve as secondary demand centers with growing environmental compliance requirements.
United States
Pharmaceutical quality control labs and EPA-mandated emissions monitoring drive procurement intensity. FDA Current Good Manufacturing Practice regulations extend instrument qualification timelines across generic drug manufacturing sites. The Boston and San Diego biotech corridors anchor demand for mass spectrometry and chromatography platforms.
Canada
Provincial health authorities centralize laboratory capital equipment decisions, consolidating procurement power. Health Canada guidelines align with FDA data integrity standards for pharmaceutical testing workflows. Ontario and Quebec host the densest concentrations of academic research facilities and contract testing laboratories.
Mexico
Nearshoring of pharmaceutical production to Baja California and Querétaro extends analytical instrument demand southward. COFEPRIS regulatory alignment with FDA standards necessitates validated equipment for export-oriented manufacturing. Mexico City metro area concentrates environmental testing capacity for industrial corridor monitoring.
North America Scientific Instruments Market Key Industry Players
The competitive structure tilts toward diversified life sciences conglomerates with integrated workflow offerings. Three tiers operate: full-solution providers controlling entire analytical workflows, technology specialists dominating single modalities, and regional distributors serving fragmented academic buyers. Consolidation accelerates through strategic acquisitions of consumables suppliers and software platforms.
Among diversified platform providers, Thermo Fisher Scientific, Danaher Corporation, and Agilent Technologies exemplify the integrated workflow archetype. These entities anchor demand from pharmaceutical quality control labs through chromatography, mass spectrometry, and sample preparation ecosystems. Their positions rest on recurring revenue attachment from consumables and service contracts rather than hardware margins alone.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Agilent Technologies |
| Danaher Corporation |
| PerkinElmer |
| Shimadzu Corporation |
| Waters Corporation |
| Bruker Corporation |
| Mettler Toledo |
| Bio-Rad Laboratories |
| Others |
Cost & Logistics Intelligence
Consolidated pharmaceutical conglomerates and group purchasing organizations anchor procurement power, concentrating demand into long-term managed service agreements that embed hardware, consumables, and qualification documentation into unified subscription structures. This buyer concentration compresses transactional pricing leverage for standalone instrument vendors while elevating total-cost-of-ownership negotiations.
Pricing Analysis
Margin tightening in mid-tier analytical platforms reflects helium scarcity constraints and precision optics import dependencies that elevate input cost volatility. Three-tier pricing structure across premium, standard, and economy levels separates validated pharmaceutical-grade systems from teaching laboratory configurations, with FDA 21 CFR Part 11 certification commanding substantial premiums. Price differentiation rests on software validation depth and predictive maintenance bundling. Academic buyers exhibit highest price sensitivity; EPA-mandated industrial facilities show lowest sensitivity due to compliance-driven replacement urgency.
Supply Chain Analysis
Dual-sourcing mandates from pharmaceutical quality control labs and EPA-contracted environmental agencies require qualified secondary suppliers for critical optical and vacuum components, extending vendor qualification timelines. Manufacturing concentrates in Germany, Japan, and the United States for precision optical elements, ion sources, and detector assemblies. Raw material dependencies span high-purity helium, specialized optical glass, and rare-earth magnetic components. Single-source vulnerability concentrates in German precision optics suppliers. Distribution runs through direct manufacturer relationships with large pharmaceutical conglomerates and integrated supply contracts with academic medical center networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision optics fabrication capacity constraints and qualified metrology technician scarcity prop instrument pricing power, creating favorable supply-constrained conditions for incumbent margin defense.
For Market Incumbents: Acquire predictive maintenance software platforms and consumables suppliers to deepen recurring revenue attachment and counter standalone instrument commoditization. Expand captive helium recycling and alternative carrier gas R&D to mitigate input cost volatility threatening chromatography margins. Consolidate channel control through direct relationships with group purchasing organizations to displace independent distributors in the Midwest and Southeast. For New Entrants and Emerging Players: Enter via environmental agency procurement channels in California and New York where climate monitoring budget expansion outpaces established vendor coverage. Target state-level departments with modular detection architectures requiring lower qualification documentation burdens than pharmaceutical applications. Deploy AI-driven remote diagnostics as a service-first wedge to bypass capital-intensive hardware manufacturing barriers. For Investors and Strategic Acquirers: The window for entry favors consumables and software specialists with embedded instrument firmware integration capabilities over pure hardware manufacturers. Long-term viability centers on recurring revenue models with pharmaceutical quality control labs and EPA-mandated industrial facilities. Watch helium market stabilization and alternative carrier gas adoption rates as inflection signals for chromatography platform competitive dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| Consumables Supplier Acquisition | Deepens recurring revenue attachment from pharmaceutical quality control labs through captive reagent supply. |
| Predictive Maintenance Platform Integration | Converts instrument hardware sales into subscription diagnostics contracts with biotech corridors. |
| Helium Recycling Infrastructure Investment | Mitigates carrier gas scarcity risk threatening gas chromatography system cost structures. |
| Environmental Agency Direct Sales Channel | Captures climate monitoring budget expansion outside traditional academic research procurement. |
| 21 CFR Part 11 Software Validation Acceleration | Compresses FDA qualification timelines for generic drug manufacturing site instrument deployments. |
Research Approach
SEC 10-K filings, EPA enforcement action databases, and FDA guidance document repositories formed the secondary backbone, cross-referenced against customs trade records for precision optics and helium import flows. Primary interviews with chromatography data system product managers, pharmaceutical quality control lab directors, EPA regional compliance officers, and group purchasing organization contract specialists validated demand assumptions. Bottom-up and top-down triangulation reconciled instrument shipment data with end-user capital expenditure disclosures.
Bottom-up modeling built from segment-level procurement patterns across analytical, detection, and laboratory equipment categories, with technology splits for mass spectrometry, chromatography, and spectroscopy platforms. End-user segmentation incorporated pharmaceutical manufacturing scale, research lab maturity tiers, and environmental agency budget trajectories. CAGRs derived from replacement cycle compression under EPA real-time monitoring mandates and FDA data integrity enforcement intensification. Helium market dynamics and precision optics supply concentration informed input cost sensitivity analysis.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EPA method updates or FDA guidance revisions on analytical procedure validation. Deviation in helium reserve depletion rates or German-Japanese optical component trade restrictions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Measuring Instruments
Communication Test Equipment (CTE) Market
Measuring Instruments
Global Dissolved Oxygen Meters and Controllers Market
Measuring Instruments
TDS Meter Market
Measuring Instruments
Monitoring Tools Market
Measuring Instruments
Global Laser Measuring Instrument Market
Measuring Instruments
Global Process Instrumentation Market
Measuring Instruments
Global Data Acquisition (DAQ) System Market
Measuring Instruments
Digital Refrigeration Gauge Market
Measuring Instruments
3D Metrology Market
Measuring Instruments
Communication Test and Measurement (Ctandm) Market
Measuring Instruments
India Hydrological and Meteorological Equipment Market
Measuring Instruments
3D Laser Scanner Market
Measuring Instruments
Data Loggers Market
Measuring Instruments
Multifunction Calibrators Market
Measuring Instruments
Ultraviolet Data Logger Market
Measuring Instruments
Global Container Weighing Systems Market