
 Borescope Inspection Camera Market | 2026-2036
Borescope Inspection Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Borescope Inspection Camera Market Outlook
Equipment leasing and pay-per-inspection service models is narrowing the capital barrier for mid-sized maintenance providers. Olympus Corporation leverages its optical heritage to dominate high-end medical and aerospace channels. Baker Hughes Company anchors its position through captive demand from oil and gas infrastructure clients. Fluke Corporation competes by extending its electrical testing brand into portable digital videoscopes for industrial field use.
A borescope inspection camera is an optical or digital instrument with a rigid or flexible insertion tube, typically 2-8mm in diameter, fitted with a lens-CCD array or fiber bundle to transmit images from confined cavities to an external display. Engineers deploy these devices to inspect turbine blades, weld seams, and internal passages without disassembling machinery. Flexible borescopes and videoscopes lead product-type demand because aircraft engine MRO and power-plant turnaround cycles require articulating tips and high-pixel-density imaging. Digital and wireless technologies are displacing purely optical systems where real-time documentation and remote expert consultation matter most. Optical and fiber-optic segments retain share in hazardous environments where electromagnetic interference rules out electronic components.
The FAA mandates borescope inspection intervals for commercial jet engines under Part 121 airworthiness rules, while the EPA enforces leak detection protocols that drive facility operators toward validated remote visual inspection equipment. In Europe, EASA aligns with FAA standards but adds CS-25 certification requirements for borescope equipment used in approved maintenance organizations. Stakeholders must monitor how regulatory harmonization between FAA and EASA affects equipment qualification costs and service provider certification timelines.
Market Dynamics
Equipment leasing and pay-per-inspection service models are narrowing the capital barrier for mid-sized maintenance providers, compressing the traditional hardware-sales cycle and expanding addressable demand beyond capital-rich tier-one operators.
Growth Catalysts
- FAA Part 121 mandates:The FAA's updated airworthiness directives now require more frequent non-destructive testing of engine internals, tightening compliance requirements and expanding inspection frequency across commercial aviation fleets.
- Flexible videoscope articulation:Aircraft engine MRO and power-plant turnaround cycles demand articulating tips and high-pixel-density imaging, pulling procurement toward advanced flexible borescopes with steerable distal ends.
- German precision manufacturing clusters:Demand concentrates in Germany, where MRO hubs and aerospace component suppliers drive procurement of high-definition flexible borescopes for quality assurance protocols.
Market Restraints
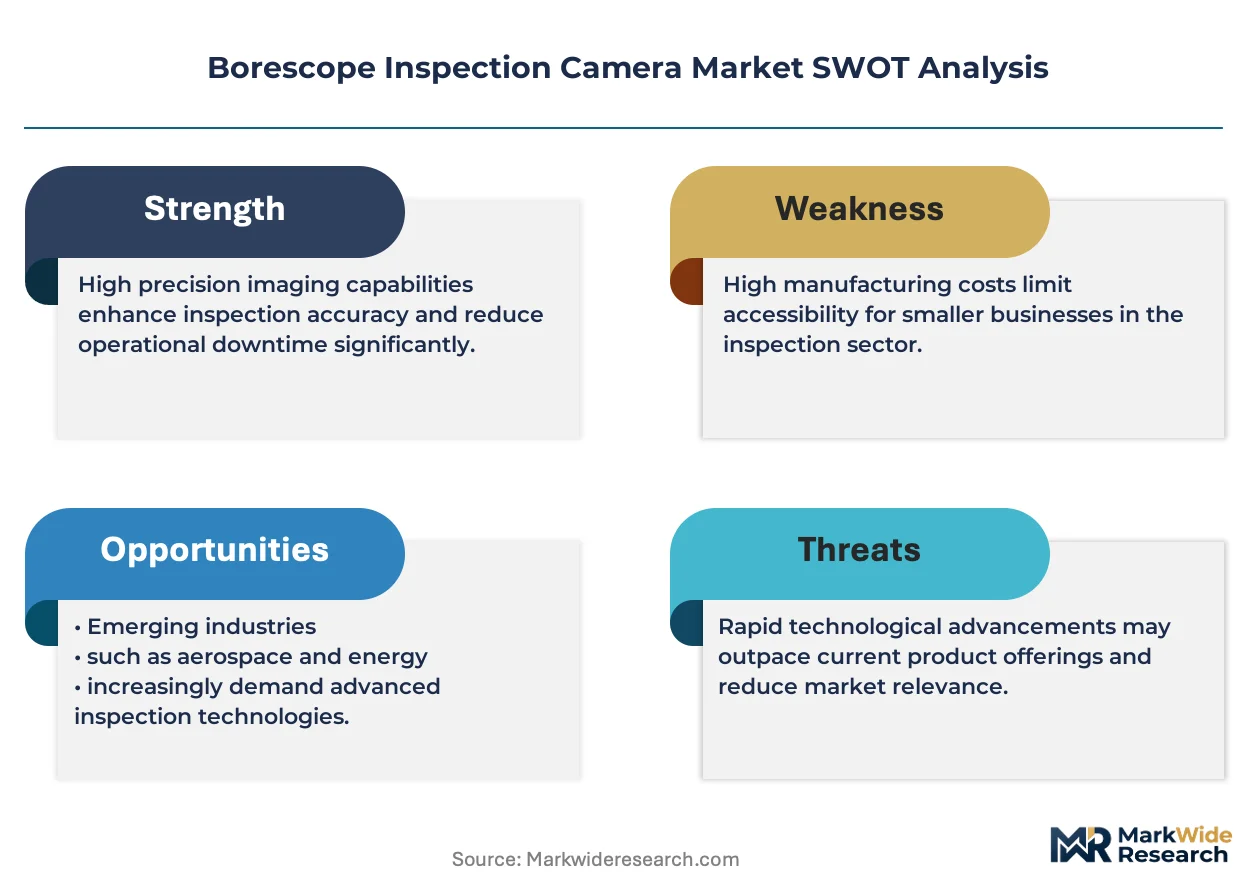
- CCD sensor supply concentration:Specialized image sensors for videoscopes source from a limited supplier base concentrated in East Asian semiconductor foundries, creating vulnerability to supply disruption.
- Optical fiber cost volatility:Fiber bundle borescopes depend on high-purity glass and rare-earth dopants subject to energy-intensive production cycles and input price swings.
- Electromagnetic interference limitations:Hazardous environments including certain oil and gas facilities and explosive atmosphere zones rule out electronic components, restricting videoscope deployment and preserving optical system share.
Strategic Opportunities
- Wireless connectivity convergence:Bluetooth and Wi-Fi modules integrated into handheld videoscope displays enable real-time documentation and remote expert consultation, opening service-revenue streams for inspection-as-a-service providers.
- EPA leak detection protocols:The EPA enforces facility monitoring requirements that drive operators toward validated remote visual inspection equipment for environmental compliance verification.
- India industrial infrastructure buildout:Power plant construction and pipeline network expansion create underpenetrated demand for portable digital videoscopes in emerging MRO ecosystems.
Industry Challenges
- NDT technician certification timelines:EASA CS-25 certification requirements for borescope equipment used in approved maintenance organizations extend qualification periods and constrain service provider scaling.
- Legacy system integration friction:Digital videoscopes must interface with incumbent maintenance management software and documentation platforms, complicating deployment in established aviation MRO operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Borescope Inspection Camera Market |
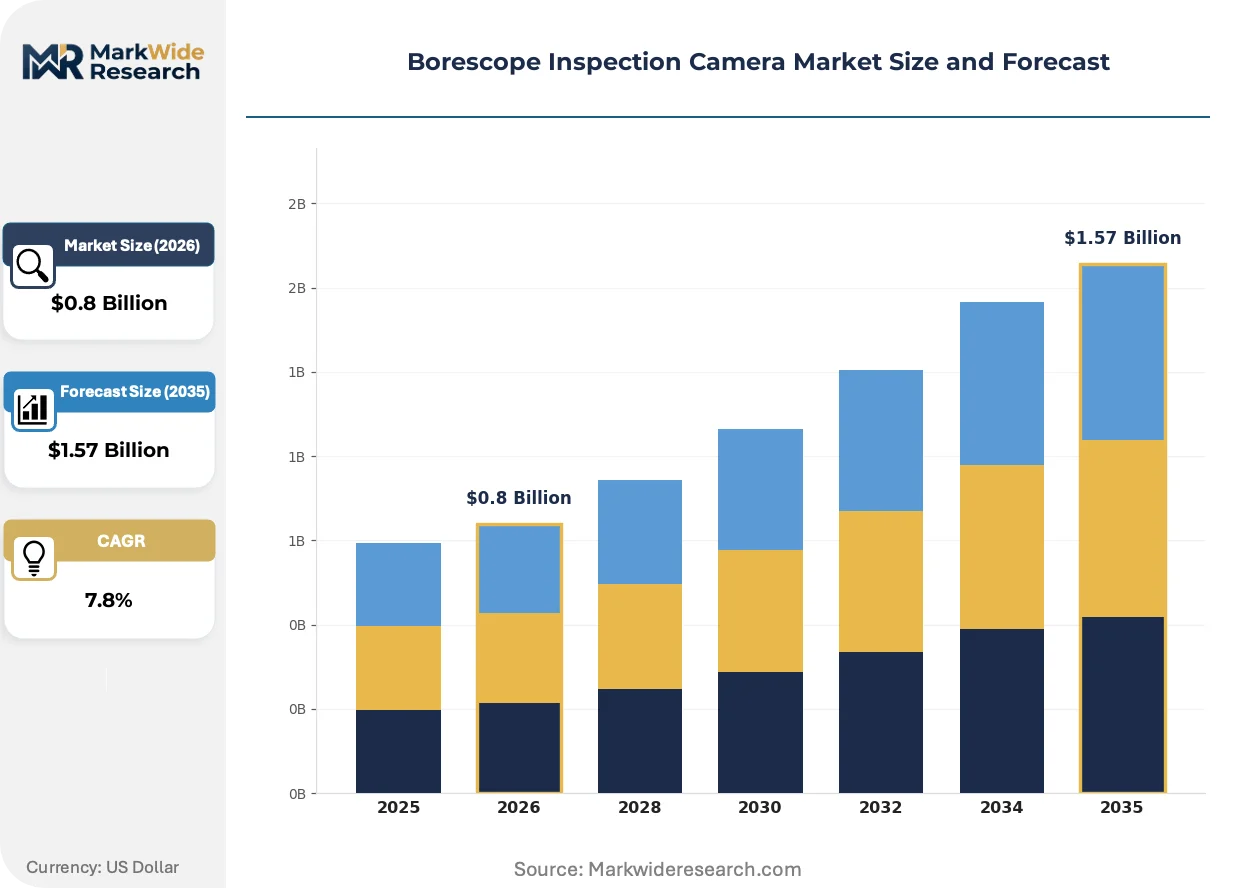
| Market Size in 2026 | $0.8 Billion |
| Market Size in 2035 | $1.57 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Borescopes, Flexible Borescopes, Videoscopes, Industrial Endoscopes Application: Aerospace Maintenance, Automotive Inspection, Medical Diagnostics, Construction Evaluation End User: Manufacturers, Service Providers, Healthcare Facilities, Educational Institutions Technology: Optical, Digital, Wireless, Fiber-Optic |
| Companies Covered | Olympus Corporation, FLIR Systems, Fluke Corporation, Baker Hughes Company, Cognex Corporation, AMETEK, Leica Microsystems, Eddyfi Technologies, Advanced Inspection Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Borescope Inspection Camera Market Strategic Shifts
Digital and wireless technologies are actively compressing the traditional optical-fiber value chain, enabling new service models and documentation standards that reshape how inspection data flows through maintenance organizations.
CMOS-CCD hybrid imaging arrays are digitizing the capture and transmission pipeline for confined-space visual inspection. Aviation MRO teams in Germany and the United States are adopting these sensors at accelerating rates for turbine blade documentation. This shift is digitizing the entire inspection workflow from field capture to cloud-based archival, collapsing the time between defect detection and engineering disposition.
EASA's alignment with FAA standards under CS-25 certification requirements is tightening equipment qualification protocols for approved maintenance organizations. The industrial consequence is extended vendor approval timelines and higher documentation burdens for borescope manufacturers seeking European market access. Aviation sector procurement teams are responding by consolidating supplier relationships toward pre-qualified equipment lines, compressing vendor diversity in approved maintenance channels.
Mid-sized maintenance providers are migrating toward equipment leasing and pay-per-inspection contracts rather than capital purchase. The channel being disrupted is traditional distributor-led hardware sales; replacing it are OEM-direct service agreements and third-party inspection-as-a-service platforms. This pattern is most visible in North American power generation and oil and gas facility maintenance, where turnaround cycle unpredictability favors operational expenditure models over fixed asset ownership.
Borescope Inspection Camera Market Segmentation
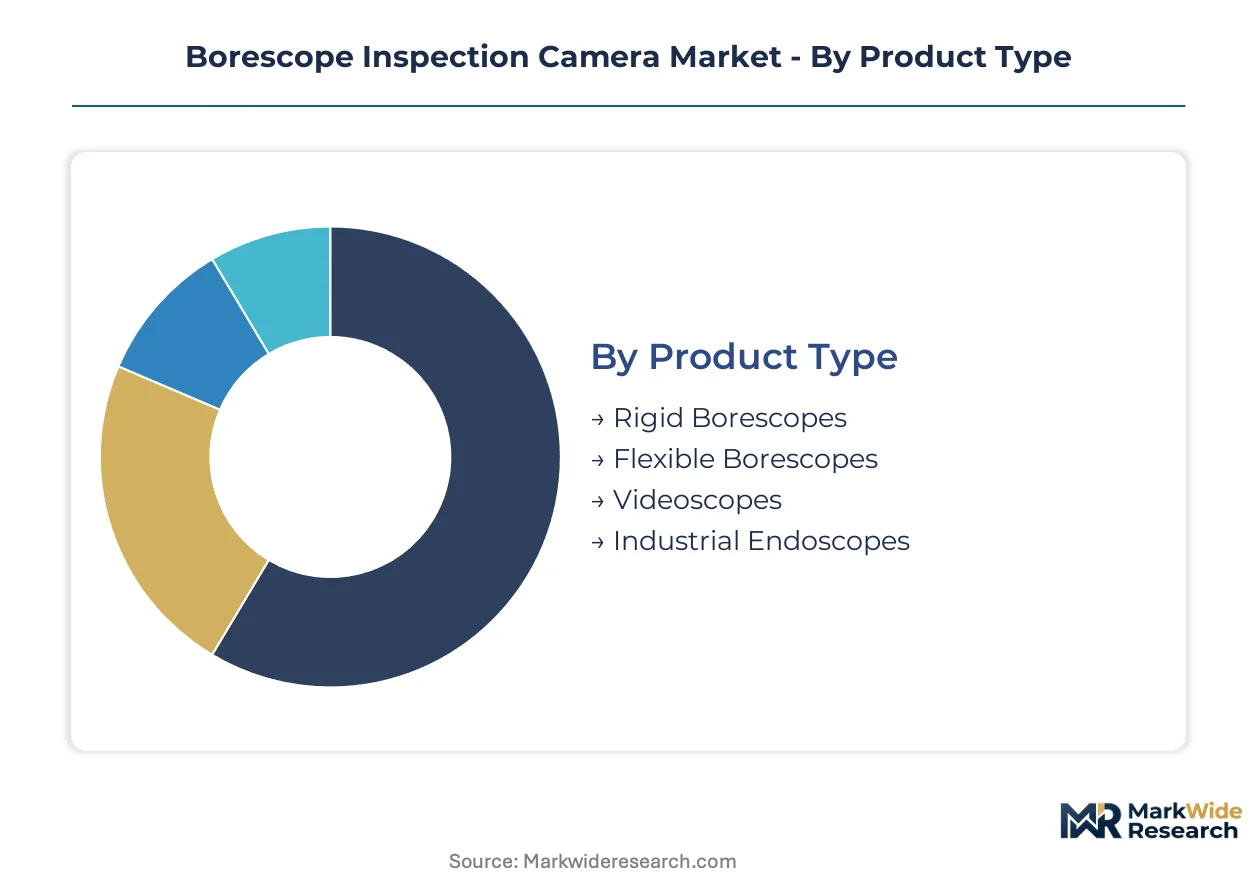
Borescope procurement patterns diverge sharply across product architectures and end-use environments. Equipment specification, compliance certification, and total cost of ownership create distinct segment boundaries that reshape vendor positioning and channel strategy.
Product Type:
The maturity spectrum spans legacy optical systems to emerging wireless platforms, with each architecture commanding different price-performance tradeoffs and replacement cycles.
- Videoscopes:CMOS-CCD hybrid imaging arrays digitize capture and transmission pipelines for confined-space inspection. FAA Part 121 mandates for commercial jet engine borescope intervals pull procurement toward steerable distal ends with high-pixel-density articulation in United States MRO facilities.
- Flexible Borescopes:Fiber bundle or electronic insertion tubes with 2-8mm diameters navigate tortuous internal passages in turbine blade inspections. German precision manufacturing clusters and aerospace component suppliers drive demand for high-definition articulating models with validated measurement capabilities.
- Rigid Borescopes:Straight-line optical rods deliver superior image clarity in straight-bore applications such as gun barrel inspection and straight-pipe weld evaluation.
- Industrial Endoscopes:Ruggedized housings and extended insertion lengths serve power plant heat exchanger and pipeline network applications.
Videoscopes retain volume leadership; flexible borescopes hold the steepest expansion curve.
Application:
Cost tier stratification separates capital-intensive aerospace compliance from price-sensitive construction field use.
- Aerospace Maintenance:Turbine blade inspection, combustion chamber evaluation, and engine internal non-destructive testing dominate specification requirements. EASA CS-25 certification mandates for approved maintenance organizations in European Union member states constrain equipment selection to pre-qualified supplier lines.
- Automotive Inspection:Cylinder bore scuffing analysis, transmission internal verification, and EV battery pack thermal runaway detection reshape demand specifications. United States EPA enforcement of facility monitoring protocols drives validated remote visual inspection equipment adoption for leak detection compliance.
- Medical Diagnostics:Sterilizable insertion tubes and biocompatible materials serve arthroscopy, laparoscopy, and otolaryngology procedures under FDA and EMA device regulations.
- Construction Evaluation:Concrete void detection, HVAC duct integrity assessment, and structural weld verification represent price-sensitive procurement with shorter replacement cycles.
Aerospace maintenance commands premium pricing tiers; automotive inspection represents the fastest-climbing application segment.
End User:
Customer type determines procurement modality, with capital purchase, operational lease, and pay-per-inspection service models segmenting the addressable base.
- Service Providers:Third-party MRO operators and inspection-as-a-service platforms favor equipment leasing to match turnaround cycle unpredictability with operational expenditure flexibility. North American power generation and oil and gas facility maintenance channels exhibit this pattern most visibly.
- Manufacturers:Original equipment producers and precision component suppliers integrate borescope inspection into quality assurance protocols with captive equipment fleets.
- Healthcare Facilities:Hospital systems and outpatient surgical centers prioritize sterilization compatibility and regulatory pre-certification over acquisition cost.
- Educational Institutions:Technical training programs and research laboratories represent sporadic, grant-dependent procurement with extended replacement horizons.
Service providers are expanding most quickly; manufacturers retain the largest installed base.
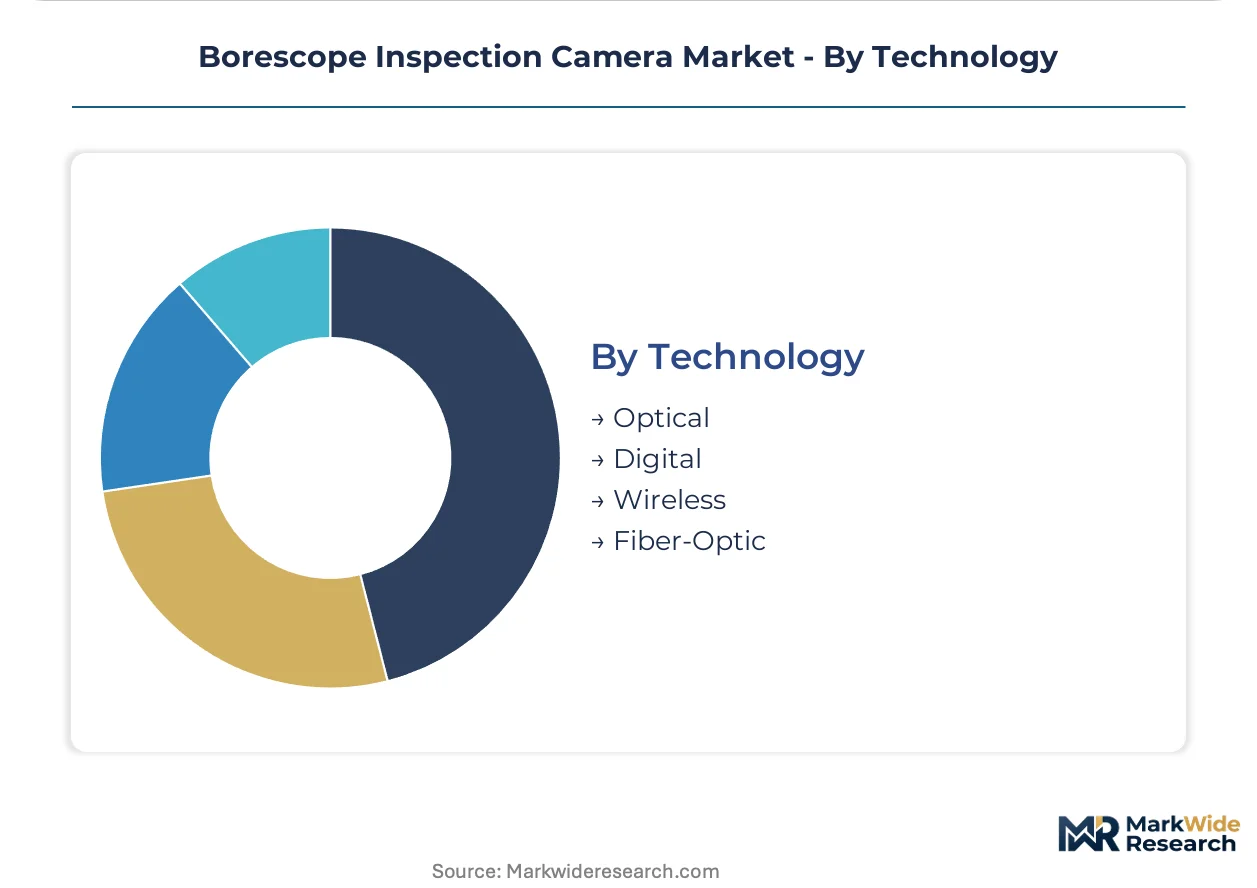
Technology:
Supply concentration in East Asian semiconductor foundries shapes availability and cost structures for electronic imaging systems.
- Digital:Solid-state CMOS sensors with on-chip analog-to-digital conversion eliminate fiber optic transmission losses. Real-time documentation and cloud-based archival integration compress defect-to-disposition timelines in aviation MRO workflows.
- Wireless:Bluetooth and Wi-Fi modules embedded in handheld displays enable remote expert consultation and inspection-as-a-service revenue streams. Electromagnetic interference constraints in oil and gas hazardous atmosphere zones limit deployability.
- Optical:Pure lens-and-prism systems without electronic components survive in explosive atmosphere regulations where spark potential is prohibited.
- Fiber-Optic:Glass bundle image transmission depends on high-purity silica and rare-earth dopants subject to energy-intensive production volatility.
Digital technology leads current procurement volume; wireless platforms gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA Part 121 airworthiness mandates and EASA CS-25 certification requirements are redirecting procurement flows toward pre-qualified equipment corridors. Germany's precision manufacturing clusters, United States MRO hubs, and India's industrial infrastructure buildout concentrate demand for high-definition flexible borescopes and wireless videoscope platforms.
United States
Commercial aviation fleet expansion and power plant turnaround cycles drive videoscope procurement. FAA Part 121 mandates tighten borescope inspection intervals for turbine blade documentation. Dallas-Fort Worth and Atlanta MRO corridors anchor demand for steerable distal-end equipment with real-time cloud archival.
Germany
Aerospace component suppliers and automotive cylinder bore inspection protocols pull high-definition articulating borescopes. EASA CS-25 certification requirements constrain equipment selection to pre-qualified supplier lines in approved maintenance organizations. Munich and Hamburg precision manufacturing clusters validate measurement-capable flexible systems for quality assurance.
China
Power plant construction and pipeline network expansion create demand for portable digital videoscopes. NMPA device regulations and GB standards shape equipment qualification for medical and industrial endoscope deployment. Yangtze River Delta manufacturing zones integrate CMOS-CCD hybrid sensors into captive inspection workflows.
India
Industrial infrastructure buildout and emerging MRO ecosystems drive procurement of cost-optimized digital borescopes. CEA facility monitoring protocols and BIS standards guide equipment selection for power generation leak detection. Maharashtra and Gujarat industrial corridors adopt pay-per-inspection service models to bypass capital expenditure constraints.
Japan
Automotive EV battery pack thermal runaway detection and precision electronics inspection reshape sensor specifications. METI industrial standards and PMDA device regulations govern equipment deployment in manufacturing and medical channels. Kanto and Kansai manufacturing belts prioritize sterilizable insertion tubes and biocompatible materials for hybrid industrial-medical applications.
Borescope Inspection Camera Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered equipment categories. The market structure consolidates around optical heritage conglomerates, industrial testing brands, and captive oilfield service arms. Three strategic archetypes dominate: diversified imaging conglomerates leveraging cross-sector sensor platforms; industrial instrumentation specialists extending electrical testing brands into visual inspection; energy service integrators anchoring demand through infrastructure client captivity. Competitive moves concentrate on wireless module integration and inspection-as-a-service platform development.
Among diversified imaging conglomerates, Olympus Corporation occupies a position exemplifying optical heritage leverage across medical and aerospace channels. Fluke Corporation represents industrial instrumentation specialists extending electrical testing credibility into portable digital videoscopes. Baker Hughes Company anchors the energy service integrator archetype through captive demand relationships with oil and gas infrastructure operators.
| Leading Market Players |
|---|
| Olympus Corporation |
| FLIR Systems |
| Fluke Corporation |
| Baker Hughes Company |
| Cognex Corporation |
| AMETEK |
| Leica Microsystems |
| Eddyfi Technologies |
| Advanced Inspection Technologies Inc. |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta semiconductor foundries anchor CMOS-CCD sensor output for videoscope manufacturers, concentrating upstream pricing power among East Asian component suppliers and compressing margin flexibility for downstream equipment assemblers facing certification-grade procurement mandates.
Pricing Analysis
Certification level (EASA CS-25/FAA-grade versus industrial non-certified) creates the primary spread between premium aerospace channels and price-sensitive construction segments. Three-tier pricing structure across premium, standard, and economy levels segments procurement: EASA-qualified articulating videoscopes command highest tiers, portable digital units for field use occupy mid-range, and basic optical borescopes serve cost-constrained buyers. Cost compression in economy tiers is intensifying because Indian and Southeast Asian MRO providers prioritize operational lease models over capital purchase. Construction evaluation buyers exhibit highest price sensitivity; aerospace maintenance organizations show lowest sensitivity due to regulatory compliance imperatives.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk planning for borescope manufacturers dependent on CMOS sensor imports. Component sourcing concentrates in Taiwan, South Korea, and Japan for specialized image sensors, with final assembly distributed across Germany, United States, and China. Glass fiber bundles draw from high-purity silica deposits in Germany and rare-earth dopant processing in China, creating dual-source dependency. Distribution runs through OEM-direct service agreements for aerospace channels and industrial distributors for field-portable equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Borescope inspection camera penetration remains early-cycle in emerging industrial infrastructure markets, with India's power plant construction pipeline and Southeast Asian MRO ecosystem buildout offering expansion runway before saturation dynamics emerge.
For Market Incumbents: Entrench position through backward integration into CMOS-CCD sensor supply and captive certification laboratories that accelerate EASA CS-25 approval timelines. Wireless module integration represents the priority R&D vector; failure to embed Bluetooth and Wi-Fi capabilities risks displacement by inspection-as-a-service platforms. Capacity addition in Munich and Dallas-Fort Worth MRO corridors reinforces channel control against emerging regional competitors.
For New Entrants and Emerging Players: Pursue white-space opportunity in India's cost-optimized digital borescope segment, where pay-per-inspection service models bypass capital expenditure barriers for mid-sized maintenance providers. Automotive EV battery pack thermal runaway detection offers the most penetrable application vertical given specification flux and absence of entrenched supplier relationships. Go-to-market angle: partner with regional inspection-as-a-service platforms rather than competing for direct hardware sales.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with undermonetized optical divisions lacking aerospace certification depth. Long-term viability over the next decade hinges on regulatory harmonization between FAA and EASA reducing equipment qualification cost burdens. Signal to watch: consolidation of third-party MRO operators into platform-scale entities capable of dictating equipment specification standards.
| Strategic Initiative | Industry Significance |
|---|---|
| Wireless Module Integration | Bluetooth and Wi-Fi enable real-time documentation and remote expert consultation for MRO workflows. |
| Certification Laboratory Investment | EASA CS-25 and FAA Part 121 pre-qualification compresses vendor approval timelines for aerospace channels. |
| Inspection-as-a-Service Platform Development | Operational lease models match turnaround cycle unpredictability with flexible expenditure structures. |
| Backward Integration into Sensor Supply | Captive CMOS-CCD sourcing mitigates East Asian foundry concentration risk for critical imaging components. |
| Regional MRO Partnership Expansion | Dallas-Fort Worth and Hamburg corridor anchoring secures demand visibility through captive maintenance relationships. |
Study Parameters
The analysis maps videoscope, flexible borescope, rigid borescope, and industrial endoscope sub-sectors, each validated through maintenance directors at commercial aviation MRO facilities, plant engineers at power generation operators, biomedical engineers at hospital systems, and procurement leads at precision manufacturing clusters. Primary interview data triangulates against FAA airworthiness directive filings, EASA certification registries, EPA leak detection protocol documentation, and customs trade records for optical instrument imports. Bottom-up equipment shipment estimates and top-down maintenance expenditure aggregates converge through iterative reconciliation.
Forecast assumptions hold regulatory mandate timelines and semiconductor foundry capacity expansion trajectories fixed while varying adoption curve slopes across emerging industrial infrastructure markets. Segmentation dimensions modeled include product architecture, application vertical, end-user procurement modality, and technology platform across the projection horizon. CAGR derivation incorporates equipment replacement cycle analysis, regulatory inspection interval changes, and service model penetration rates for pay-per-inspection contracts.
Sensitivities concentrate around East Asian semiconductor supply disruption, EASA-FAA regulatory harmonization velocity, and industrial infrastructure buildout pace in India. Forecasts reflect documented assumptions about technician certification timeline compression and wireless technology adoption thresholds. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Measuring Instruments
Data Acquisition Market
Measuring Instruments
Monitoring Tools Market
Measuring Instruments
Laser Distance Meter Market
Measuring Instruments
North America Scientific Instruments Market
Measuring Instruments
Temperature Loggers Market
Measuring Instruments
Americas 3D Metrology Market
Measuring Instruments
Moisture Meter Market
Measuring Instruments
Digital Refrigeration Gauge Market
Measuring Instruments
3D Laser Scanner Market
Measuring Instruments
India Hydrological and Meteorological Equipment Market
Measuring Instruments
Base Station Analyzer Market
Measuring Instruments
Global Instrument Calibrator Market
Measuring Instruments
Global Process Instrumentation Market
Measuring Instruments
Communication Test Equipment (CTE) Market
Measuring Instruments
TDS Meter Market
Measuring Instruments
Global Reference Thermometer Market