
 Moisture Meter Market | 2026-2036
Moisture Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Moisture Meter Market Foresight
Equipment leasing and rental financing is rewriting competitive dynamics in moisture meter procurement, allowing smaller contractors to access professional-grade instrumentation without capital outlay. METTLER TOLEDO leverages its precision measurement heritage to dominate laboratory and industrial calibration segments. Delmhorst Instrument Co anchors its position through deep specialization in agricultural and grain moisture applications. FLIR Systems extends its thermal imaging expertise into infrared moisture detection for building diagnostics.
A moisture meter is an electromechanical instrument that quantifies water content in solids, liquids, or gases through dielectric constant measurement, electrical resistance, or electromagnetic wave attenuation, typically calibrated to accuracy within 0.1-1.0% moisture content depending on substrate. Its primary purpose spans quality assurance in building materials, agricultural commodities, and wood products where moisture deviation causes structural failure, spoilage, or manufacturing defects. Pinless technology leads in construction applications where surface damage is unacceptable, while pin-type meters sustain stronger positions in woodworking and firewood markets requiring depth-specific readings. Capacitive technology occupies the fastest-growing tier as manufacturers integrate multi-frequency calibration for heterogeneous materials.
FDA guidelines on pharmaceutical manufacturing moisture control, EPA mold assessment protocols for indoor air quality, and OSHA workplace safety standards for material handling collectively shape product certification requirements and end-user compliance spending. The EU Green Deal's building renovation targets and F-Gas Regulation on insulation materials further tighten moisture verification mandates across European construction. Stakeholders must monitor how regulatory convergence between environmental performance and material durability standards reshapes instrument specification criteria and service revenue models.
Market Dynamics
Equipment leasing and rental financing is rewriting competitive dynamics in moisture meter procurement, allowing smaller contractors to access professional-grade instrumentation without capital outlay. This capital-light access model is compressing traditional ownership cycles and expanding the addressable contractor base.
Growth Catalysts
- EU Green Deal building renovation targets:Stricter energy codes across Germany, France, and the Netherlands mandate moisture verification in insulation retrofits, expanding instrument deployment among renovation specialists.
- China's dual carbon goals:Tighter material quality controls across manufacturing supply chains drive precision moisture monitoring in steel, cement, and chemical processing facilities.
- Pinless electromagnetic technology:Non-destructive testing capabilities enable adoption in high-value finished surfaces where pin penetration is prohibited, particularly in luxury construction and heritage restoration.
Market Restraints
- Semiconductor component volatility:Capacitive sensor chips and precision analog-to-digital converters face supply concentration in East Asian foundries, creating input cost instability.
- Calibration infrastructure gaps:Third-party metrology services remain underdeveloped in Sub-Saharan Africa and Central Asia, limiting instrument lifecycle management.
- Technical substrate limitations:Electromagnetic penetration depth constraints restrict pinless accuracy in dense concrete exceeding 50mm thickness, preserving pin-type dominance in heavy civil applications.
Strategic Opportunities
- India's PLI scheme for precision instruments:Domestic manufacturing incentives create localization pathways for mid-range moisture meters serving agricultural and construction verticals.
- IoT-enabled predictive maintenance:Wireless moisture sensors integrated with building management systems enable continuous monitoring contracts replacing episodic manual inspection.
- Saudi Arabia's giga-project construction pipeline:NEOM and Red Sea tourism developments specify embedded moisture monitoring in smart building envelopes, creating specification pull for advanced instrumentation.
Industry Challenges
- Multi-frequency calibration expertise:Heterogeneous material testing requires technicians trained in dielectric spectroscopy, a skill set scarce outside major metropolitan engineering clusters.
- CE-MDR transition timelines:Laboratory moisture analyzers face reclassification under stricter conformity assessment procedures, extending certification cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Moisture Meter Market |
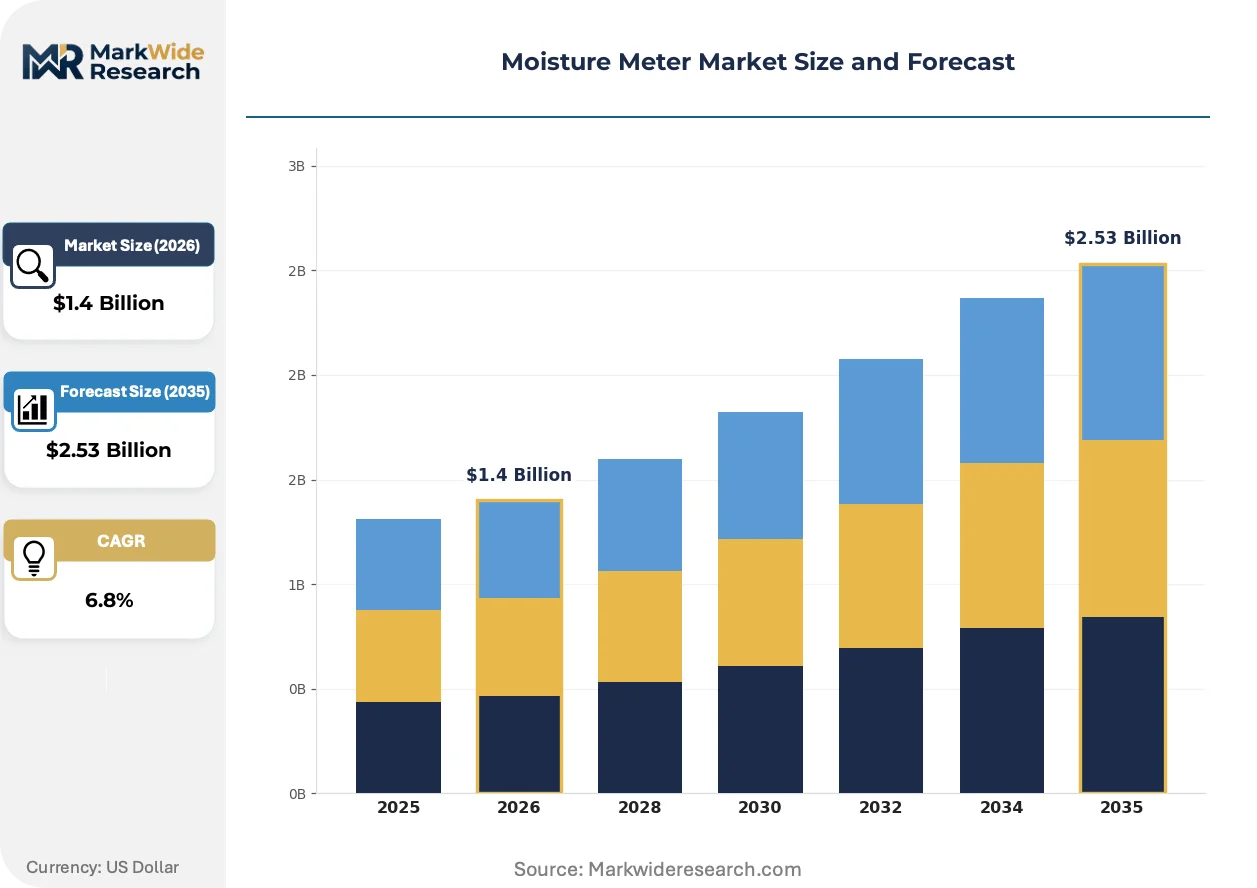
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pin-Type, Pinless, Hygrometer, Digital Application: Agriculture, Construction, Woodworking, Firewood Technology: Capacitive, Resistive, Microwave, Infrared End User: Farmers, Contractors, Woodworkers, Laboratories |
| Companies Covered | METTLER TOLEDO, Delmhorst Instrument Co, FLIR Systems, PCE Instruments, Kett Electric Laboratory, General Tools & Instruments LLC, Testo SE & Co. KGaA, Tramex Ltd., Protimeter, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Moisture Meter Market Shifts & Advancements
Multi-frequency electromagnetic sensing is compressing the performance gap between pinless and pin-type instruments. Three interconnected developments are reshaping product architecture and buyer expectations.
Capacitive moisture detection is hybridizing with thermal imaging analytics to create multi-modal building diagnostics platforms. FLIR Systems and specialized contractors in Germany now deploy combined infrared-electromagnetic instruments that correlate surface temperature differentials with subsurface moisture gradients. This convergence reduces false positives in mold assessment protocols and compresses inspection timeframes by 40-60% compared to sequential single-technology surveys.
The EU F-Gas Regulation on insulation material verification is mandating moisture content documentation for polyurethane and mineral wool installations. Construction material distributors in France and Italy now bundle moisture meters with insulation product sales to ensure contractor compliance. This regulatory embedding is shifting procurement from standalone instrument purchases to integrated material-testing packages, altering channel economics and service attachment rates.
After-sales calibration subscriptions are displacing transactional service models among industrial end-users. Pharmaceutical manufacturers under FDA 21 CFR Part 11 guidelines require continuous instrument qualification, driving annual calibration contract penetration above 70% in GMP-regulated facilities. This recurring revenue concentration is visible most acutely in the Boston-Cambridge biotech cluster and Basel pharmaceutical corridor, where vendor lock-in through service bundling now determines instrument selection criteria.
Moisture Meter Market Segmentation
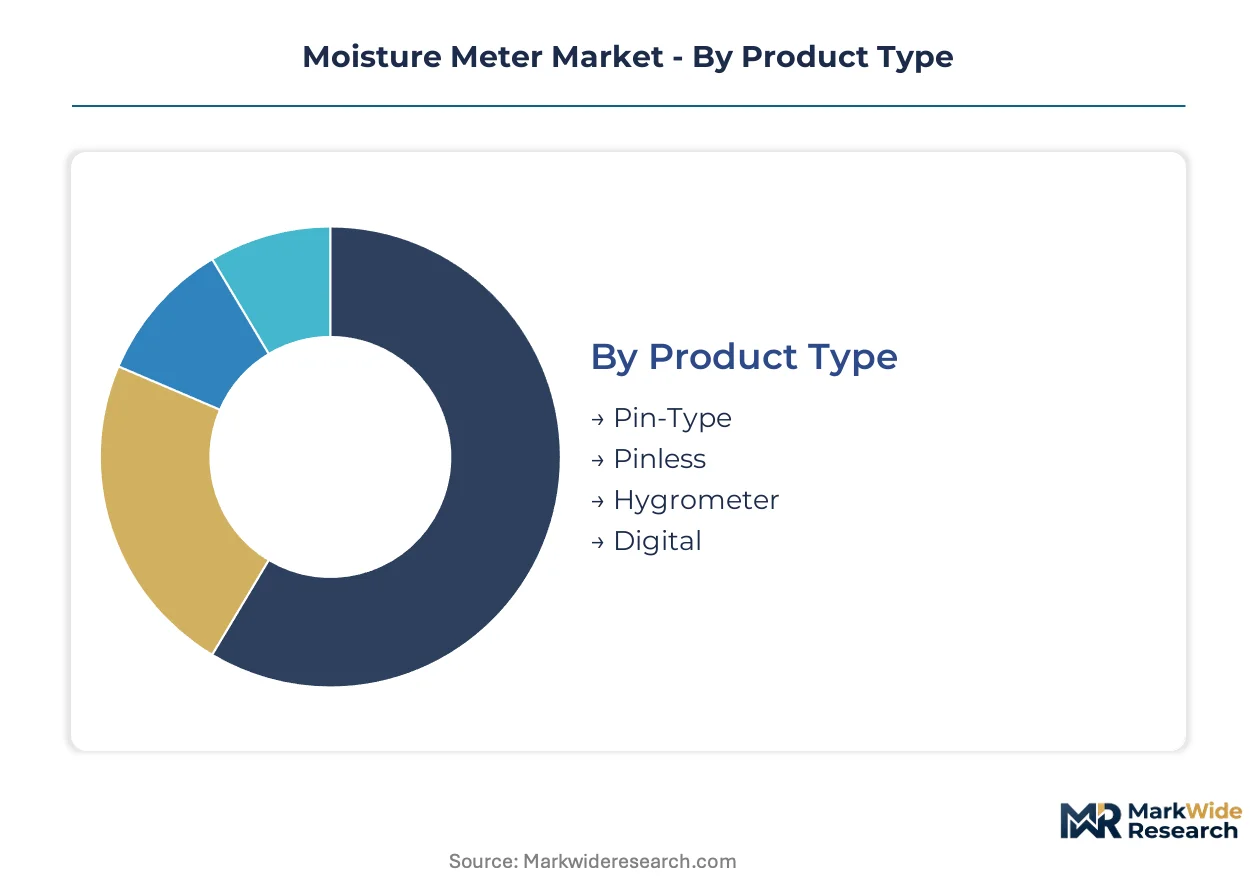
Moisture meter procurement cycles vary dramatically across instrument categories, with construction-grade pinless units turning over every 18-24 months under heavy field use while laboratory analyzers operate on 7-10 year replacement timelines. Understanding these velocity differentials helps vendors align service contracts and upgrade pathways to actual usage intensity patterns.
Product Type:
Replacement velocity separates construction field instruments from laboratory equipment, with rental fleets and contractor-owned units cycling fastest due to jobsite abuse and calibration drift.
- Pin-Type:Electromechanical probes penetrate substrate surfaces to measure electrical resistance between two metal pins, delivering depth-specific readings accurate to 0.5% moisture content in dense materials. Demand concentrates among firewood merchants and sawmill operators in Germany and Austria, where DIN 18560 standards mandate penetration-based verification for structural timber certification.
- Pinless:Electromagnetic sensors detect dielectric constant variations across material surfaces without physical penetration, preserving finished aesthetics in high-value installations. Adoption accelerates in France and Italy as EU F-Gas Regulation compliance drives non-destructive insulation verification during building envelope retrofits.
- Hygrometer:Ambient air moisture measurement instruments serve HVAC commissioning and indoor air quality assessment protocols.
- Digital:Microprocessor-based units with data logging and wireless connectivity support regulatory documentation requirements.
Pin-Type anchors the volume base while Pinless gains share at the steepest rate.
Application:
Margin structures diverge sharply across use cases, with pharmaceutical laboratory applications commanding 3-4x the service attachment rate of agricultural commodity testing.
- Agriculture:Grain moisture verification at harvest and storage prevents spoilage and qualifies commodity pricing. China's dual carbon enforcement tightens moisture documentation across soybean and corn supply chains, driving instrument density in Heilongjiang and Jilin grain belts.
- Construction:Building material verification spans concrete curing, insulation installation, and moisture intrusion detection. German contractors under EU Green Deal renovation mandates deploy instruments across Munich, Hamburg, and Cologne metro renovation corridors.
- Woodworking:Kiln-dried lumber verification ensures dimensional stability in furniture and flooring manufacturing.
- Firewood:Residential and commercial fuel moisture testing optimizes combustion efficiency and EPA compliance.
Construction commands the highest per-unit pricing while Agriculture delivers the steepest volume expansion trajectory.
Technology:
Technology selection tracks substrate heterogeneity, with homogeneous materials favoring simpler resistive approaches and complex composites requiring multi-frequency electromagnetic analysis.
- Capacitive:Dielectric measurement across variable frequencies enables calibration for mixed-material substrates. Pharmaceutical manufacturers in the Boston-Cambridge corridor adopt capacitive laboratory analyzers for FDA 21 CFR Part 11 compliant moisture documentation in solid dosage production.
- Resistive:Direct current measurement between probe pins delivers cost-effective verification for uniform wood and agricultural products. Firewood distributors and small-scale farmers in Poland and Romania favor resistive instruments for sub-$200 price accessibility.
- Microwave:Through-transmission sensing supports bulk material analysis in conveyor and hopper installations.
- Infrared:Thermal emission correlation with surface moisture enables rapid non-contact screening.
Resistive technology anchors installed base volume while Capacitive climbs the fastest as multi-frequency calibration penetrates industrial quality control.
End User:
Customer sophistication determines specification intensity, with regulated laboratories demanding full metrology traceability and field contractors prioritizing durability and speed.
- Farmers:Individual producers and cooperative elevators require portable, battery-operated units for harvest-time grain testing. India's PLI scheme for precision instruments drives domestic manufacturing cost reductions targeting Maharashtra and Punjab agricultural markets.
- Contractors:Building trades specialists need ruggedized instruments with rapid calibration and documentation output. Saudi Arabia's NEOM and Red Sea giga-projects specify embedded moisture monitoring in smart building envelopes, pulling advanced instrumentation into contractor fleets.
- Woodworkers:Millwork and cabinetry producers verify kiln performance and incoming lumber specifications.
- Laboratories:Pharmaceutical, food, and materials testing facilities require NIST-traceable calibration and software validation.
Contractors anchor the volume base while Laboratories expand most quickly on regulatory compliance spending.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in moisture meters track manufacturing specialization and regulatory enforcement intensity. Countries with stringent building codes and agricultural quality mandates import high-specification laboratory units while exporting mid-range field instruments to adjacent markets.
Germany
Construction contractors in Munich, Hamburg, and Cologne deploy pinless moisture meters to meet EU Green Deal renovation targets for building energy efficiency. The F-Gas Regulation mandates moisture verification in polyurethane and mineral wool insulation installations. Bavaria's industrial instrumentation cluster anchors metrology-grade production serving pharmaceutical and automotive quality control labs across Central Europe.
China
Dual carbon enforcement tightens material quality controls across steel, cement, and chemical processing supply chains in the Yangtze River Delta and Pearl River Delta. The MIIT and SAMR coordinate GB standards alignment for moisture monitoring equipment in manufacturing facilities. Heilongjiang and Jilin grain belts drive instrument density for soybean and corn moisture documentation under carbon-reduction compliance protocols.
United States
Pharmaceutical manufacturers in the Boston-Cambridge biotech corridor require FDA 21 CFR Part 11 compliant moisture analyzers for solid dosage production documentation. EPA mold assessment protocols for indoor air quality shape instrument certification requirements in building diagnostics. The Pacific Northwest timber region sustains demand for penetration-based meters in kiln-dried lumber verification for furniture and flooring exports.
India
The PLI scheme for precision instruments creates domestic manufacturing pathways for mid-range moisture meters targeting Maharashtra and Punjab agricultural markets. BIS standards enforcement tightens grain moisture documentation at cooperative elevators and food processing facilities. Gujarat's industrial instrumentation sector expands production capacity for construction-grade pinless units serving Middle East export contracts.
Saudi Arabia
NEOM and Red Sea tourism giga-projects specify embedded moisture monitoring in smart building envelopes, pulling advanced instrumentation into contractor procurement specifications. The Saudi Food and Drug Authority and Saudi Standards, Metrology and Quality Organization align moisture verification protocols with Gulf Cooperation Council technical regulations. Riyadh-based construction material distributors bundle moisture meters with insulation product sales to ensure compliance documentation.
Moisture Meter Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensor modules and calibration services. The vendor base organizes around three functional layers: precision laboratory equipment, ruggedized field instrumentation, and embedded sensor systems. Consolidation pressures concentrate at the laboratory tier where FDA and EU MDR compliance costs favor scale, while field instrumentation remains fragmented across regional specialists. Dominant competitive moves include technology licensing agreements for multi-frequency electromagnetic calibration and geographic expansion through distributor partnerships in high-growth construction corridors.
Among precision measurement specialists, METTLER TOLEDO anchors the laboratory and industrial calibration tier through heritage positioning in analytical instrumentation. Delmhorst Instrument Co exemplifies deep vertical specialization, occupying a position concentrated in agricultural and grain moisture applications. FLIR Systems represents the convergence archetype, extending thermal imaging expertise into infrared moisture detection for building diagnostics and multi-modal inspection platforms.
| Leading Market Players |
|---|
| METTLER TOLEDO |
| Delmhorst Instrument Co |
| FLIR Systems |
| PCE Instruments |
| Kett Electric Laboratory |
| General Tools & Instruments LLC |
| Testo SE & Co. KGaA |
| Tramex Ltd. |
| Protimeter |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese capacitive sensor module production compresses margins for mid-range instrument assemblers while simultaneously lowering entry barriers for new field-equipment brands. This utilization dynamic forces incumbent suppliers to differentiate through calibration service bundling rather than hardware premiums, reshaping procurement economics across contractor and laboratory segments alike.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on NIST-traceable calibration certification and after-sales service attachment, with pharmaceutical laboratories paying 3-4x field-equipment rates for FDA 21 CFR Part 11 compliant documentation. Cost compression in economy-tier resistive instruments intensifies because of Indian domestic manufacturing scale-up under the PLI scheme. Small-scale agricultural cooperatives in Poland and Romania exhibit highest price sensitivity, while GMP-regulated biotech facilities in the Boston-Cambridge corridor demonstrate lowest.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for precision analog-to-digital converter sourcing. Component manufacturing concentrates in China, Taiwan, and South Korea, with moisture meter assemblers drawing from East Asian foundries for capacitive sensor chips and electromagnetic coil assemblies. Single-source vulnerability persists for multi-frequency calibration firmware licensed from German metrology specialists. Distribution runs through construction material distributors in France and Italy, who bundle instruments with insulation product sales under EU F-Gas Regulation compliance mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The moisture meter market sits in early-cycle expansion as IoT-enabled predictive maintenance contracts displace episodic manual inspection across commercial building portfolios. This adoption tailwind accelerates specification pull for wireless-integrated instrumentation in smart building envelopes.
For Market Incumbents: Insulate laboratory-tier positioning through backward integration into NIST-traceable calibration services, locking in pharmaceutical and biotech accounts against emerging metrology-as-a-service competitors. Deepen channel control by embedding instruments within construction material distributor bundles in EU F-Gas Regulation compliance corridors, particularly France and Italy where regulatory embedding is reshaping procurement economics. For New Entrants and Emerging Players: Establish a beachhead in India's agricultural moisture verification segment, where PLI scheme cost reductions and BIS standards enforcement create whitespace for domestic brands against imported European equipment. Target Maharashtra and Punjab grain belt cooperatives with battery-operated resistive units priced below 15,000 INR, leveraging local assembly partnerships to bypass import duty exposure. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because calibration subscription penetration above 70% in GMP-regulated facilities generates predictable cash flows decoupled from hardware replacement cycles. Target acquisition archetype: mid-cap field instrumentation specialists with underdeveloped service revenue streams and established distributor relationships in EU Green Deal renovation corridors. The signal to watch is contract penetration rates in Saudi giga-project specifications, where embedded moisture monitoring mandates indicate service revenue inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Subscription Launch | Captures recurring revenue from FDA 21 CFR Part 11 compliant pharmaceutical facilities in Basel and Boston-Cambridge corridors. |
| Multi-frequency Electromagnetic Licensing Agreement | Accelerates pinless accuracy convergence with pin-type performance for heritage restoration and luxury construction applications. |
| Construction Material Distributor Partnership | Secures specification pull in France and Italy where EU F-Gas Regulation mandates moisture documentation bundles. |
| IoT Sensor Platform Integration | Enables continuous monitoring contracts replacing episodic inspection in Saudi NEOM smart building envelope deployments. |
| Domestic Manufacturing Scale-Up Under PLI Scheme | Reduces cost position for agricultural field instruments targeting Maharashtra and Punjab grain belt cooperatives. |
Research Methodology
The analysis maps pin-type, pinless, hygrometer, and digital instrument sub-sectors, each validated through interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads at construction and agricultural equipment distributors. Primary fieldwork combined with secondary validation from SEC filings, customs and trade data, FDA 510(k) filings, and EU MDR conformity assessment databases. Bottom-up unit economics triangulated against top-down market sizing across technology, application, and end-user segmentation dimensions.
Forecast assumptions held regulatory enforcement timelines and semiconductor supply normalization as fixed boundary conditions while varying IoT adoption rates and service contract penetration across the projection horizon. The analytical framework modeled instrument replacement velocity, calibration service attachment rates, and geographic specification intensity. CAGRs derived from segment-level growth differential analysis anchored in EU Green Deal renovation targets, China's dual carbon enforcement, and Saudi giga-project procurement pipelines.
Sensitivities concentrate around semiconductor component volatility in East Asian foundries and CE-MDR transition timeline extensions for laboratory analyzer reclassification. Forecasts reflect documented assumptions on regulatory convergence between environmental performance and material durability standards. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Measuring Instruments
Network Diagnostic Tools Market
Measuring Instruments
Temperature Loggers Market
Measuring Instruments
Americas 3D Metrology Market
Measuring Instruments
Temperature Calibrator Market
Measuring Instruments
Global Instrument Calibrator Market
Measuring Instruments
Base Station Analyzer Market
Measuring Instruments
TDS Meter Market
Measuring Instruments
Communication Test and Measurement (Ctandm) Market
Measuring Instruments
Global Laser Measuring Instrument Market
Measuring Instruments
Handheld Wind Anemometer Market
Measuring Instruments
Multifunction Calibrators Market
Measuring Instruments
Global Data Acquisition (DAQ) System Market
Measuring Instruments
Global Reference Thermometer Market
Measuring Instruments
Laser Distance Meter Market
Measuring Instruments
Air Velocity Meter Market
Measuring Instruments
Ultraviolet Data Logger Market