
 Directors and Officers (Dando) Insurance Market | 2026-2036
Directors and Officers (Dando) Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Directors and Officers (Dando) Insurance Market Analysis
Market Context with Strategic Players
Technology sector procurement is consolidating as the fastest-growing vertical for Dando coverage, driven by IPO pipelines and SPAC-related litigation tail risks. Chubb Limited leverages its multinational claims infrastructure to dominate complex cross-border Side A placements for multinational technology issuers. American International Group sustains leadership in financial services Dando through its Lloyd's syndicate capacity and specialized underwriting units. Allianz competes aggressively on price in the mid-market private company segment, where fiduciary liability endorsements are becoming standard.
Technical Definition and Structural Segments
Directors and Officers insurance is a liability contract indemnifying corporate leaders against personal financial loss from suits alleging wrongful acts in their managerial capacity, with policies typically written on a claims-made basis requiring continuous coverage maintenance to preserve retroactive protection. The primary commercial purpose is attracting and retaining qualified board talent by shielding personal assets from securities fraud allegations, derivative suits, and regulatory enforcement actions. Claims-made policy structures anchor the market as the dominant architecture, while Side A-only coverage represents the fastest-growing policy type as individual directors prioritize personal asset protection separate from corporate indemnity. Coverage scope segmentation shows regulatory investigations endorsements commanding the steepest premium escalations as SEC and DOJ enforcement intensity broadens.
Regulatory Frame and Forward-Looking Close
SEC disclosure mandates, the EU's Digital Operational Resilience Act for financial entities, and the UK's Senior Managers and Certification Regime collectively reshape Dando demand by expanding the universe of reportable events that trigger coverage activation. SEC rules on cybersecurity incident disclosure and climate-related risk governance specifically expand the litigation exposure surface for named directors, forcing underwriters to recalibrate pricing models and coverage grants. Stakeholders must monitor how emerging AI governance obligations across multiple jurisdictions will be absorbed into standard Dando policy wordings or excluded through new exclusionary language.
Market Dynamics
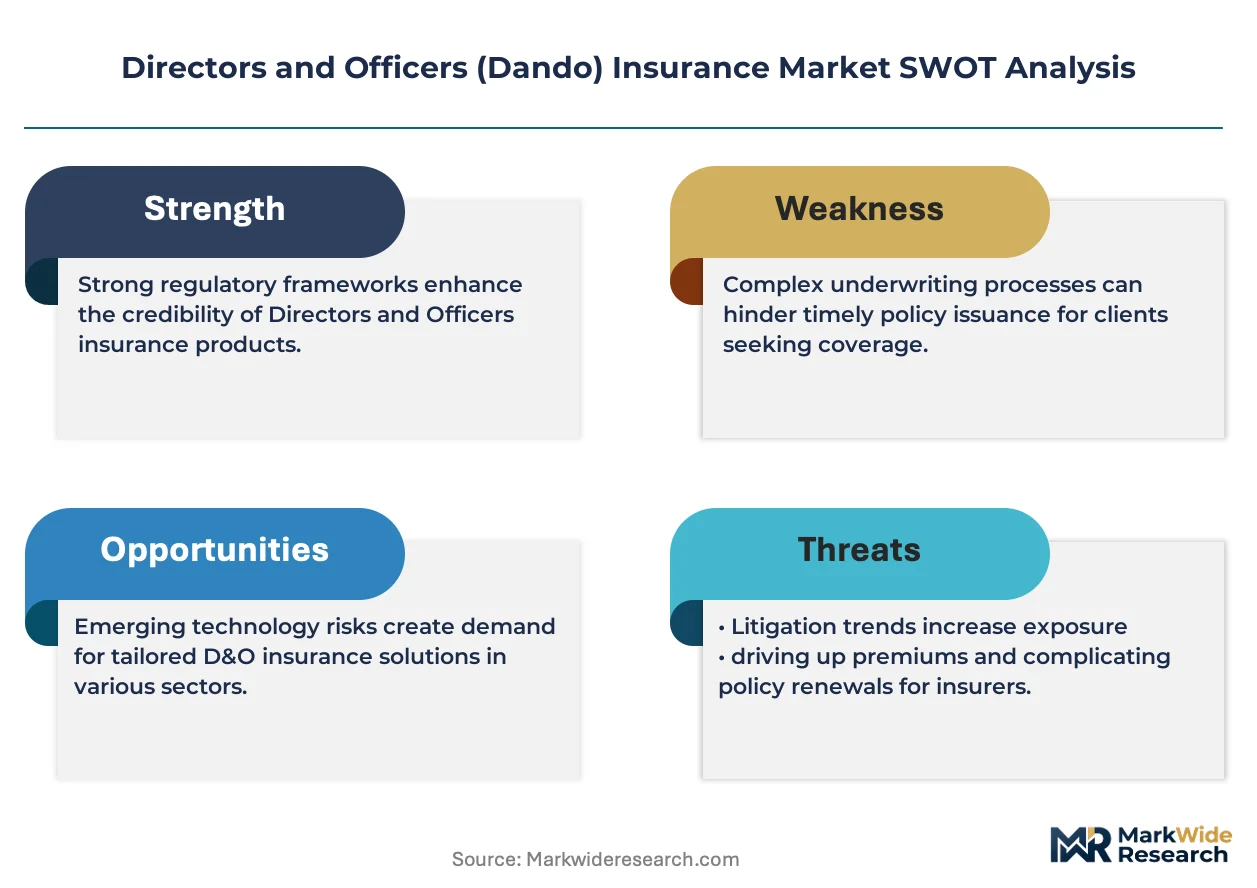
Securities litigation frequency and regulatory enforcement intensity are compressing policy renewal cycles while forcing underwriters to recalibrate coverage grants for cyber and climate-related exposures.
Growth Catalysts
- SEC Cybersecurity Disclosure Rules:Mandatory incident reporting within four business days expands the universe of reportable events triggering Dando coverage activation for public company directors.
- SPAC Litigation Tail Risks:De-SPAC transaction disputes and post-merger shareholder class actions sustain elevated demand for Side A-only protection among technology sector boards.
- Climate Governance Litigation:Derivative suits alleging fiduciary breaches in climate risk oversight are proliferating across European and North American jurisdictions, broadening coverage scope requirements.
Market Restraints
- Capacity Concentration:Lloyd's syndicate and Bermuda market underwriters control disproportionate catastrophe-layer capacity, creating pricing volatility following major securities class action settlements.
- Retroactive Coverage Gaps:Claims-made policy structures expose individual directors to personal asset risk during insurer insolvencies or coverage disputes over prior acts.
- Regulatory Arbitrage Friction:Divergent disclosure standards between SEC, FCA, and EU supervisory authorities complicate multinational program structuring and drive up compliance costs.
Strategic Opportunities
- Private Company Mid-Market:Fiduciary liability endorsements remain underpenetrated among venture-backed technology firms preparing for IPO pipelines.
- AI Governance Integration:Emerging board obligations for algorithmic risk oversight create white space for specialized coverage extensions or standalone policies.
- Parametric Trigger Innovation:Index-based settlement mechanisms tied to securities litigation filing volumes could differentiate offerings for high-frequency exposure sectors.
Industry Challenges
- Underwriting Talent Scarcity:Experienced Dando actuaries with securities litigation forecasting expertise command premium compensation, constraining carrier expansion.
- Legacy System Integration:Incumbent insurers struggle to embed real-time litigation analytics into pricing engines without disrupting existing policy administration platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Directors and Officers (Dando) Insurance Market |
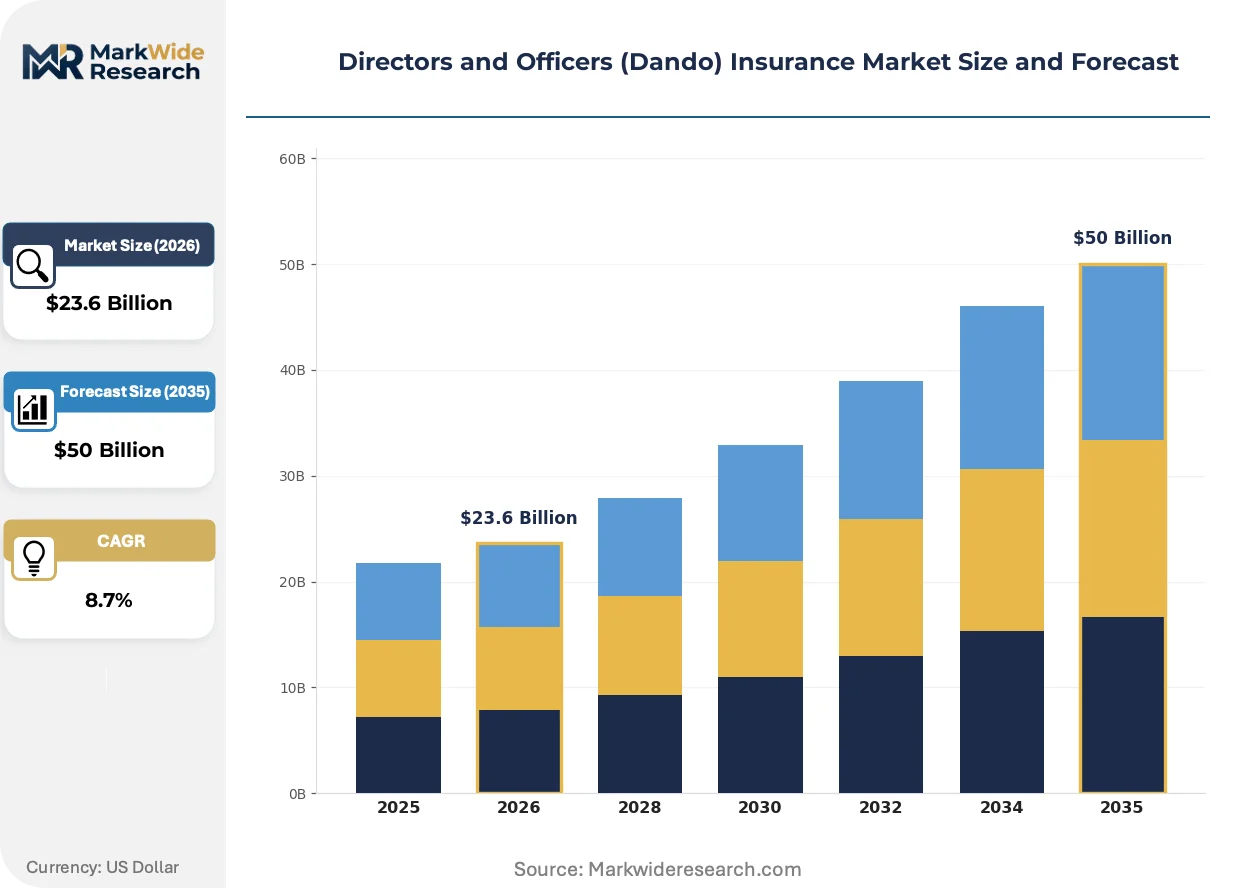
| Market Size in 2026 | $23.6 Billion |
| Market Size in 2035 | $50 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Claims Made, Entry Level, Side A, Side B Coverage Scope: Employment Practices, Securities Claims, Regulatory Investigations, Fiduciary Liability Industry Vertical: Financial Services, Technology, Healthcare, Manufacturing Client Type: Public Companies, Private Firms, Non-Profits, Startups |
| Companies Covered | Chubb Limited, American International Group, Allianz, Travelers Companies Inc., AXA, Zurich Insurance Group, Hiscox Inc., Tokio Marine Group, Berkshire Hathaway, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Directors and Officers (Dando) Insurance Market Emerging Trajectories
Underwriting methodology and policy architecture are evolving in response to intangible risk quantification challenges and director-level demand for personal asset protection decoupled from corporate indemnity.
Predictive litigation analytics platforms are absorbing vast datasets of securities filing patterns, judicial forum selection trends, and settlement outcomes to refine individual director risk scoring. Mid-market public company boards are adopting these tools at accelerating pace to negotiate premium reductions. Carrier pricing models are absorbing algorithmic outputs that compress traditional underwriting cycles and enable dynamic coverage adjustments.
The EU's Digital Operational Resilience Act mandates board-level accountability for ICT risk management across financial entities, expanding the regulatory surface area triggering Dando claims. European insurers are embedding DORA compliance attestations into policy warranties and exclusions. Asset managers and payment institutions face the steepest premium escalations as supervisors intensify enforcement of senior manager certification requirements.
Individual directors are demanding standalone Side A coverage separate from corporate reimbursement agreements, reflecting erosion of trust in balance-sheet strength during insolvency events. Private Dando placements through specialized brokers are displacing traditional bundled programs for high-net-worth board members. This bifurcation is most visible in United States technology and life sciences sectors where personal asset exposure concentrates in founder-director roles.
Directors and Officers (Dando) Insurance Market Segmentation
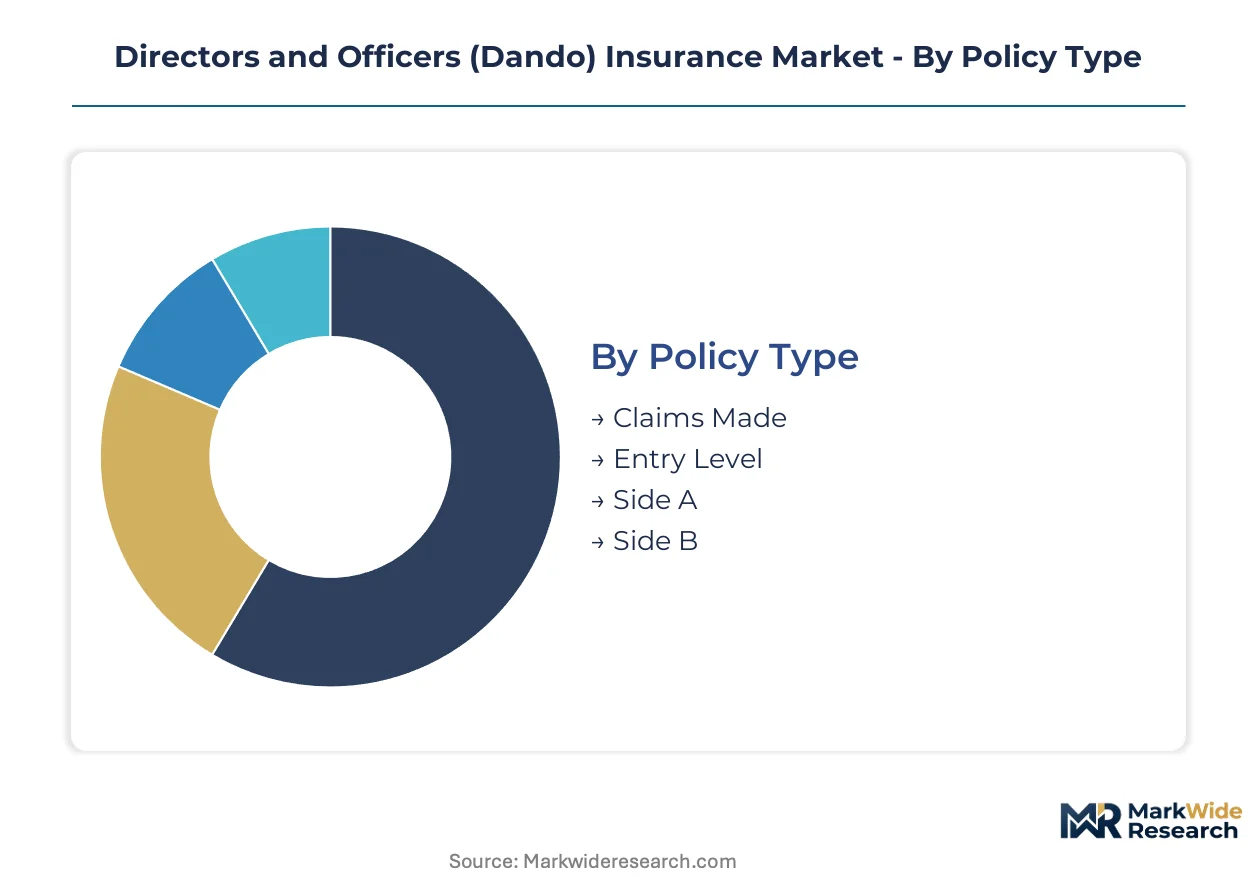
Dando policy structures vary dramatically in pricing, coverage grants, and buyer sophistication. Segmentation reveals where underwriters concentrate capacity and where emerging exposures create white space for product innovation.
Policy Type:
Premium outlays and coverage continuity requirements drive buyer selection more than policy architecture complexity.
- Side A:Standalone personal asset protection for individual directors when corporate indemnity fails or is prohibited by law. Public company boards in the United States facing heightened securities litigation frequency are prioritizing this structure to shield personal wealth from derivative suits and regulatory enforcement actions.
- Claims Made:The dominant market architecture requiring continuous coverage maintenance to preserve retroactive protection for prior acts. Mid-market private firms favor this structure for cost efficiency, though gaps during insurer transitions expose directors to personal asset risk.
- Side B:Reimburses the corporate entity for indemnification payments made to directors and officers. Balance-sheet strength determines uptake, with financially stable public companies in manufacturing verticals maintaining this coverage to attract board talent.
- Entry Level:Simplified underwriting with reduced limits and narrower coverage grants for early-stage ventures. Venture-backed technology startups preparing for IPO pipelines use this as a stepping stone to comprehensive protection.
Volume sits with Claims Made; growth tilts toward Side A.
Coverage Scope:
Regulatory enforcement intensity across jurisdictions reshapes which endorsements command premium escalations.
- Regulatory Investigations:Defense costs for SEC, DOJ, and state attorney general inquiries. The SEC's cybersecurity disclosure mandates and climate governance rules are expanding activation frequency for public company directors.
- Securities Claims:Shareholder class actions and derivative suits alleging misrepresentation or fiduciary breach. SPAC litigation tail risks and de-SPAC transaction disputes sustain demand concentration in United States technology issuers.
- Employment Practices:Allegations of wrongful termination, discrimination, and harassment against directors in supervisory roles. Healthcare and financial services verticals face elevated exposure due to workforce scale and regulatory scrutiny.
- Fiduciary Liability:Breach of duty claims in employee benefit plan administration. Private company mid-market penetration remains underdeveloped despite ERISA exposure expansion.
Premium escalation concentrates in Regulatory Investigations; Securities Claims retain the largest premium pool.
Industry Vertical:
Litigation exposure surface and board composition complexity determine pricing tiers and carrier appetite.
- Technology:IPO pipelines, SPAC-related litigation, and founder-director personal asset concentration create the steepest premium growth trajectory. Cybersecurity disclosure obligations and AI governance emerging risks are accelerating policy upgrades.
- Financial Services:Intensive regulatory supervision and the EU's Digital Operational Resilience Act mandate board-level ICT accountability. Asset managers and payment institutions face premium pressure from senior manager certification requirements.
- Healthcare:FDA enforcement actions and False Claims Act exposure combine with employment practices liability. Clinical trial disclosure obligations and telehealth regulatory evolution expand the coverage surface.
- Manufacturing:Derivative suits tied to climate risk oversight and supply chain disclosure are proliferating. Long-tenured boards with stable governance structures command favorable pricing.
Technology absorbs capacity at the fastest rate; Financial Services maintains the deepest premium base.
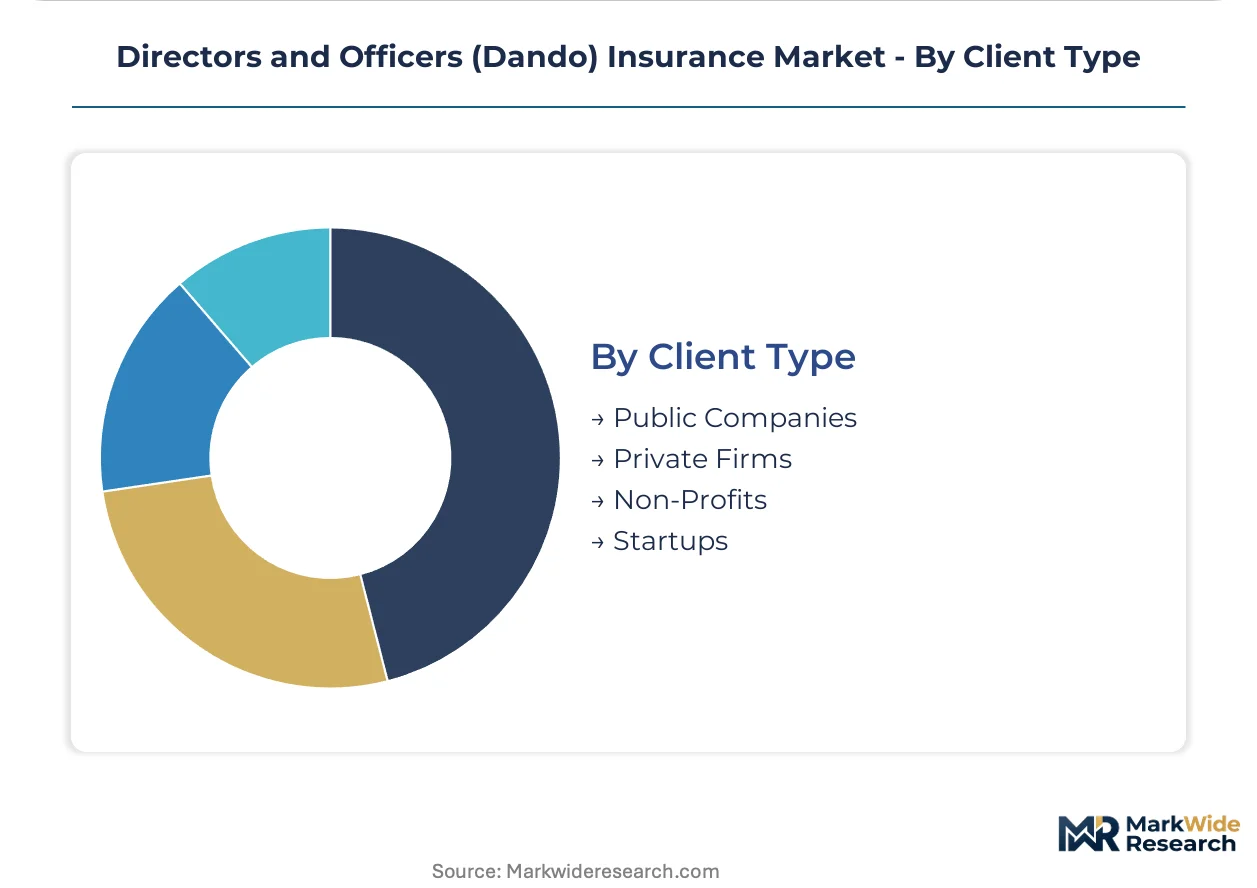
Client Type:
Balance-sheet strength and governance maturity separate buyers into distinct underwriting segments.
- Public Companies:Mandatory disclosure regimes and shareholder litigation exposure necessitate comprehensive Side A and Side B structures. SEC enforcement intensity directly correlates with coverage limits and premium outlays.
- Private Firms:Fiduciary liability endorsements and employment practices coverage dominate procurement. Mid-market technology firms approaching liquidity events are upgrading from entry-level to comprehensive protection.
- Startups:Venture capital governance requirements and director recruitment needs drive entry-level purchases. Pre-IPO preparation triggers coverage upgrades and limit expansions.
- Non-Profits:Volunteer board composition and limited financial resources constrain premium capacity. Regulatory scrutiny of endowment management and donor disclosure is expanding coverage requirements.
Public Companies generate the largest premium volume; Startups represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Delaware's corporate domicile concentration and Lloyd's of London specialty underwriting cluster anchor Dando insurance capacity distribution. Regulatory divergence between common law and civil law jurisdictions shapes policy architecture and claims resolution patterns.
United States
Securities class action frequency in federal district courts sustains the deepest premium pool worldwide. SEC enforcement actions and shareholder derivative suits drive Side A coverage expansion among Nasdaq-listed technology issuers. New York and Delaware corporate headquarters concentrate broker placement activity and specialized underwriting expertise.
United Kingdom
Lloyd's syndicate capacity dominates catastrophe-layer placements for multinational boards. The Senior Managers and Certification Regime imposes personal accountability standards that reshape coverage warranties for financial services directors. London's insurance market cluster attracts cross-border program structuring for FTSE 350 companies.
Germany
DAX board composition rules and co-determination requirements complicate policy structuring for supervisory directors. BaFin enforcement of EU Digital Operational Resilience Act provisions elevates regulatory investigation coverage demand among asset managers. Frankfurt's financial center concentrates captive insurance arrangements for Mittelstand exporters.
Japan
Tokyo Stock Exchange governance code revisions accelerate independent director recruitment and Dando procurement among listed enterprises. METI guidance on board accountability for cybersecurity incidents expands coverage activation triggers. Osaka's commercial insurance market develops specialized capacity for cross-border M&A litigation exposure.
Australia
ASIC enforcement intensity and continuous disclosure obligations sustain premium growth for ASX-listed company boards. Class action funding reforms reshape securities litigation economics and policy limit requirements. Sydney's financial district anchors regional underwriting capacity for Asia-Pacific headquartered multinationals.
Directors and Officers (Dando) Insurance Market Vendor Landscape
Top-tier vendors anchor the multinational program market, while regional specialists and Lloyd's syndicates occupy niche capacity layers. The competitive terrain stratifies across three tiers: integrated global carriers with dedicated financial lines divisions, Lloyd's syndicates specializing in catastrophe-layer Side A placements, and regional mutuals serving captive-domestic requirements. Market consolidation proceeds through capacity alliances rather than outright acquisition, as underwriters pool syndicate participation to deploy larger policy limits.
Among the integrated global tier, Chubb Limited, American International Group, and Allianz exemplify divergent strategic positioning. Chubb occupies the complex cross-border placement segment through multinational claims infrastructure. American International Group anchors financial services specialization via Lloyd's syndicate capacity and dedicated underwriting units. Allianz represents aggressive price competition in the mid-market private company segment where fiduciary liability endorsements standardize.
| Leading Market Players |
|---|
| Chubb Limited |
| American International Group |
| Allianz |
| Travelers Companies Inc. |
| AXA |
| Zurich Insurance Group |
| Hiscox Inc. |
| Tokio Marine Group |
| Berkshire Hathaway |
| Others |
Supply Flow & Price Mechanics
Predictive litigation analytics platforms are compressing underwriting cycles and reshaping cost economics while concentrating placement activity among brokers with real-time data capabilities. This technology shift simultaneously elevates pricing precision for complex risks and widens the capability gap between algorithm-enabled carriers and legacy underwriters.
Pricing Analysis
Short lead-time placements for imminent IPOs or SPAC de-SPAC transactions command premium rate-on-line multiples as underwriters accelerate due diligence. Three-tier pricing structure across premium, standard, and economy levels segments buyers by litigation exposure surface and board composition complexity. Cost compression in entry-level coverage is intensifying because venture-backed startups are consolidating procurement through preferred broker panels. Private technology issuers approaching liquidity events demonstrate the highest price sensitivity, while Nasdaq-listed companies with active securities litigation maintain the least.
Supply Chain Analysis
Carrier financial strength ratings and Lloyd's syndicate accreditation serve as the primary qualification gates for catastrophe-layer capacity participation. Underwriting capital concentrates in Bermuda, the United Kingdom, and the United States, with London's insurance market cluster anchoring cross-border program structuring. Raw material dependencies include actuarial talent pools, securities litigation databases, and regulatory compliance infrastructure. Single-source vulnerability sits with experienced Dando actuaries possessing securities litigation forecasting expertise. Distribution runs through specialized wholesale brokers and managing general agents placing complex Side A structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Underwriting capacity scarcity among carriers with proven claims-paying track records in securities class action settlements sustains pricing power across all policy tiers. Lloyd's syndicate and Bermuda market concentration in catastrophe-layer placements creates the binding constraint.
For Market Incumbents: To counter erosion of trust in corporate balance-sheet strength during insolvency events, incumbents should deepen personal asset protection product development for individual directors through standalone Side A offerings. Capacity addition in Bermuda and London preserves access to the deepest capital pools for multinational program layers. For New Entrants and Emerging Players: Capture the private company mid-market fiduciary liability endorsement white space among venture-backed technology firms preparing for IPO pipelines. The most penetrable segment sits with pre-IPO startups upgrading from entry-level to comprehensive protection. A specialized go-to-market angle centers on parametric trigger innovation tied to securities litigation filing volumes. For Investors and Strategic Acquirers: Exit pathways concentrate in capacity alliances and syndicate participation arrangements rather than outright carrier acquisition. Long-term viability over the next decade hinges on underwriting talent retention and litigation analytics platform integration. The acquisition target archetype combines established Lloyd's syndicate access with proprietary predictive risk scoring capabilities. The signal to watch as inflection indicator is SEC enforcement action frequency against individual directors for cybersecurity disclosure failures.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Analytics Platform Deployment | Chubb's multinational claims infrastructure leverages algorithmic outputs to compress underwriting cycles for technology issuers. |
| Side A-Only Product Line Expansion | American International Group's Lloyd's syndicate capacity anchors specialized standalone personal asset protection offerings. |
| Mid-Market Price Competition | Allianz's aggressive positioning in private company segments standardizes fiduciary liability endorsements as coverage baseline. |
| DORA Compliance Integration | EU Digital Operational Resilience Act mandates reshape policy warranties for financial services directors across asset managers. |
| Parametric Trigger Innovation | Index-based settlement mechanisms tied to litigation filing volumes differentiate offerings for high-frequency exposure sectors. |
Methodological Framework
Document review covered SEC enforcement action databases, Lloyd's syndicate capacity registers, and securities litigation settlement records, complemented by interviews with underwriting executives at global carriers, wholesale brokerage placement specialists, and corporate risk managers at Nasdaq-listed technology issuers. Primary fieldwork with Dando claims adjusters and Side A coverage attorneys validated policy wording evolution patterns. Secondary sources included regulatory filing archives, insurance regulatory capital adequacy reports, and judicial forum selection trend analyses. Bottom-up policy count and limit data triangulated against top-down premium pool estimates from national insurance supervisory authorities.
Segment-level value outputs across the projection horizon reflect modeled interactions between securities litigation frequency, regulatory enforcement intensity, and carrier capacity deployment decisions. The analytical framework incorporated policy type segmentation by Side A, Side B, and claims-made structures; coverage scope dimensions including regulatory investigations and securities claims; and industry vertical splits across technology, financial services, and healthcare. CAGRs were derived from recursive substitution of litigation exposure growth rates into premium rate-on-line elasticity functions. Forecast inputs included SEC cybersecurity disclosure mandate implementation timelines and SPAC litigation tail risk duration assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to judicial forum selection rule changes, carrier insolvency cascades, and divergent multinational regulatory disclosure standards. Forecasts reflect assumptions about securities class action settlement inflation and underwriter capital commitment continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Canada Parametric Insurance Market
Insurance
New Zealand Property and Casualty Insurance Market
Insurance
GCC Bancassurance Market
Insurance
Social Media Analytics-Based Insurance Market
Insurance
UK Electronic Gadgets Insurance Market
Insurance
Europe Road Assistance Insurance Market
Insurance
Takaful Market
Insurance
US Extended Warranty Market
Insurance
France Property and Casualty Insurance Market
Insurance
Europe Entertainment Insurance Market
Insurance
Business Insurance Market
Insurance
Insurance Big Data Analytics Market
Insurance
Europe Bancassurance Market
Insurance
China Online Insurance Market
Insurance
China Business Income Insurance Market
Insurance
Asia-Pacific Group Health Insurance Market