
 Crystal Bracelets Market | 2026-2036
Crystal Bracelets Market Size, Share, and Industry Trends Forecast 2026-2036
Crystal Bracelets Market Insights
Asset-light dropshipping models is rewriting competitive entry dynamics in crystal jewelry, allowing digital-native brands to test designs without inventory risk. Swarovski leverages its Austrian crystal heritage to sustain premium positioning across heritage collections. Pandora anchors mass-market accessibility through modular charm systems that extend into semi-precious stone variants. Mejuri competes via direct-to-consumer pricing that undercuts traditional wholesale markups.
Crystal bracelets are ornamental wristwear composed of faceted or polished mineral specimens—typically amethyst, quartz, or obsidian—set in metal findings or strung on elastic cord, valued for aesthetic display and attributed energetic properties. Manufacturing involves lapidary cutting, drilling, and hand-assembly with nickel-free or sterling silver components to meet skin-contact safety thresholds. Stretch bracelets lead volume through low price points and universal sizing, while bangle and cuff variants command margin pools in the personalization segment where engraving and birthstone pairing create uplift. Healing properties as a feature dimension is accelerating fastest among millennial and Gen Z buyers seeking mindfulness-adjacent consumption.
REACH in Europe mandates disclosure of heavy-metal content in jewelry alloys, pushing suppliers toward certified lead-free and cadmium-free crystal settings. The FDA regulates topical claims tied to crystal healing in the United States, constraining how brands market wellness outcomes without substantiation. Stakeholders must monitor evolving greenwashing enforcement from the FTC and EU Green Deal alignment requirements that will reshape sourcing transparency and carbon footprint disclosure across mineral supply chains.
Market Dynamics
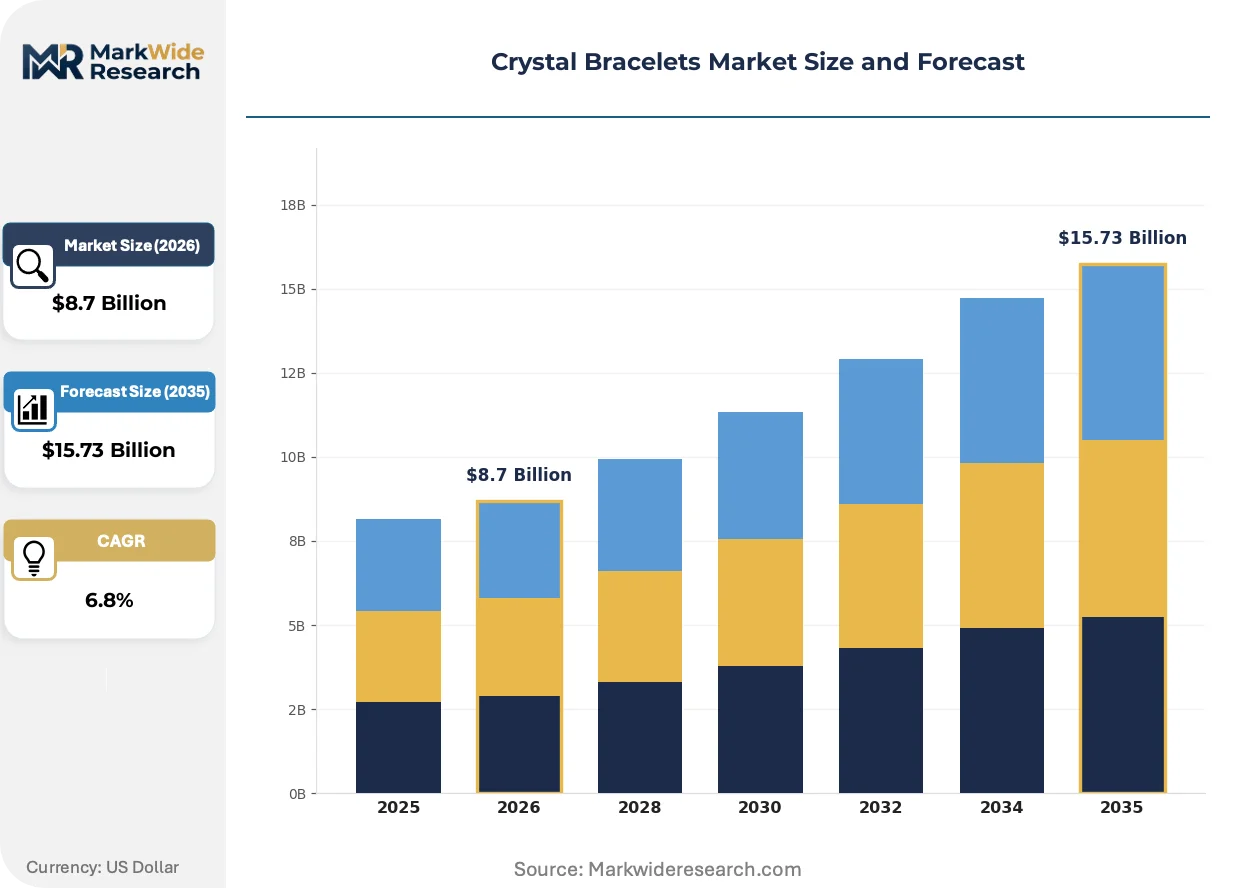
Wellness-adjacent consumption patterns are restructuring crystal bracelet demand around attributed energetic properties rather than purely ornamental value, compressing traditional jewelry retail margins while elevating direct-to-consumer spiritual brand premiums.
Growth Catalysts
- REACH compliance migration:ECHA-mandated heavy-metal disclosure requirements in Europe are accelerating certified lead-free supply chain certification, creating competitive differentiation for compliant suppliers.
- Metaphysical retail channel expansion:Wellness-focused consumers are driving bracelet volume through specialized spiritual commerce platforms that bypass conventional jewelry distribution.
- Elastic cord manufacturing automation:Stretch bracelet production lines are achieving unit cost reductions that sustain accessible price points across universal sizing formats.
Market Restraints
- Raw material concentration risk:Amethyst and quartz rough supply concentrates in Brazilian and Madagascan mining jurisdictions, exposing processors to extraction volatility and export licensing delays.
- FDA topical claim constraints:The US regulator constrains crystal healing outcome marketing without substantiation, limiting wellness-positioned brand messaging and forcing semantic workarounds.
- Synthetic crystal substitution pressure:Laboratory-grown quartz variants are capturing price-sensitive segments, compressing margins on natural stone positioning.
Strategic Opportunities
- EU Green Deal alignment:Carbon footprint disclosure mandates are creating first-mover advantage for suppliers with verified mineral provenance and low-emission lapidary processing.
- Personalization segment expansion:Engraving and birthstone pairing services on bangle and cuff variants are commanding margin pools above commodity stretch bracelet pricing.
- Dropshipping infrastructure maturation:Asset-light fulfillment networks are enabling digital-native brands to test design variants without inventory carrying costs.
Industry Challenges
- Lapidary skill scarcity:Precision cutting and drilling expertise for semi-precious stone finishing is concentrating among aging artisan cohorts with limited apprenticeship pipeline replacement.
- Greenwashing enforcement exposure:FTC substantiation requirements for environmental marketing claims are elevating compliance costs and litigation risk for unverified sourcing claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crystal Bracelets Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bangle, Cuff, Stretch, Chain Material: Amethyst, Quartz, Rose Quartz, Obsidian Feature: Healing Properties, Authenticity, Customization, Durability End User: Women, Men, Children, Gift Buyers |
| Companies Covered | Swarovski, Tiffany & Co., Pandora, Kendra Scott, BaubleBar, Astrid & Miyu, Monica Vinader, Mejuri, Gorjana, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crystal Bracelets Market Trends and Innovations
Material science advances and regulatory transparency mandates are converging to reshape how crystal bracelets are manufactured, marketed, and distributed across wellness-adjacent consumer segments.
Smart material integration is hybridizing traditional crystal wristwear with biometric sensing capabilities. Wearable technology developers are embedding pressure-sensitive conductive threads into elastic bracelet weaves, enabling stress-tracking functionality without compromising aesthetic mineral display. Millennial and Gen Z buyers are adopting these hybrid formats at accelerated rates, compressing the boundary between jewelry and wellness device categories.
EU Green Deal carbon accounting requirements are mandating supply chain disclosure granularity that exceeds current industry practice. ECHA-aligned documentation protocols now require kilogram-level emission tracking from mine extraction through retail distribution, forcing lapidary processors to reconfigure supplier relationships or risk market exclusion. German and French boutique platforms are responding fastest, building proprietary provenance verification systems.
Direct-to-consumer subscription models are displacing wholesale-dependent revenue structures among emerging spiritual brands. Monthly crystal bracelet curation services are capturing recurring revenue streams that traditional one-time retail transactions cannot match, with California and New York metropolitan clusters showing highest adoption density. This channel innovation is compressing inventory risk for digital-native entrants while elevating customer lifetime value metrics.
Crystal Bracelets Market Segmentation
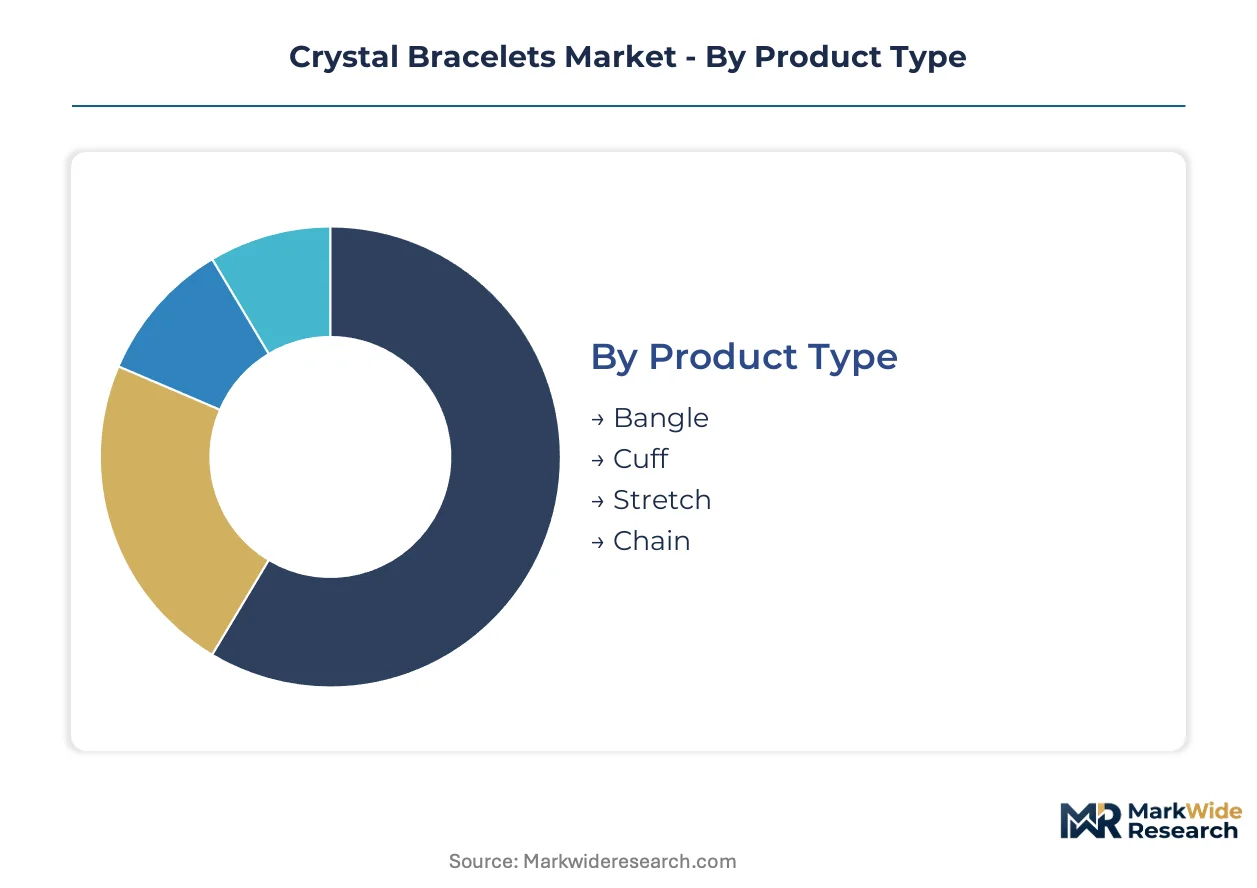
Crystal bracelet segmentation reveals how wellness positioning, material provenance, and wearability preferences fragment demand across distinct consumer cohorts. Each dimension carries divergent margin profiles and regulatory exposure that shape supplier prioritization.
Product Type:
Mature formats dominate unit economics while emerging constructions capture premium expansion.
- Stretch:Elastic cord construction enables universal sizing without metal clasps, minimizing production complexity and return rates. Demand concentrates through direct-to-consumer spiritual brands in California and New York metropolitan clusters where low price points drive impulse conversion. REACH-compliant nickel-free cord components are becoming a procurement differentiator.
- Bangle:Rigid circular forms require precise diameter grading and often incorporate hinge mechanisms or slip-on designs for wrist accommodation. German and French boutique platforms are commanding margin pools through engraving services and birthstone pairing that elevate unit economics above commodity stretch alternatives.
- Cuff:Open-ended metal bands with crystal inlays or terminal accents permit adjustable fit while maintaining structural presence. Austrian heritage crystal houses leverage this format for premium positioning.
- Chain:Linked metal constructions with suspended crystal elements or integrated bezel settings offer formal jewelry aesthetics. FDA topical claim constraints limit wellness marketing for this traditionally ornamental format.
Stretch retains volume leadership; bangle holds the steepest expansion curve through personalization attach rates.
Material:
Cost tier stratification separates mass-market accessibility from scarcity-driven premium positioning.
- Quartz:Abundant silicon dioxide specimens in clear, milky, or smoky variants provide the lowest raw material cost base. Brazilian extraction jurisdictions dominate rough supply, exposing processors to export licensing volatility. Laboratory-grown variants are capturing price-sensitive segments and compressing natural stone premiums.
- Amethyst:Purple quartz varieties command color-premium positioning attributed to stress-reduction properties in wellness marketing. Madagascan and Brazilian mining concentration creates supply vulnerability.
- Rose Quartz:Pink-hued quartz specimens associated with emotional healing attributes attract millennial and Gen Z buyers through mindfulness-adjacent consumption. ECHA-aligned documentation protocols now require provenance verification for EU market access.
- Obsidian:Volcanic glass formations valued for protective energetic properties carry higher lapidary processing costs due to conchoidal fracture patterns. Aging artisan cohorts with precision cutting expertise are concentrating supply capability.
Quartz retains volume leadership; rose quartz holds the steepest expansion curve among Gen Z demographic penetration.
Feature:
Application intensity varies from functional durability claims to unsubstantiated wellness outcomes.
- Healing Properties:Attributed energetic benefits—stress reduction, clarity enhancement, emotional balance—drive the fastest demand acceleration among wellness-focused consumers. FDA constraints on topical claims without substantiation force semantic workarounds in US marketing.
- Authenticity:Natural versus synthetic verification, mine-to-retail provenance documentation, and lapidary origin certification respond to EU Green Deal carbon accounting mandates. German platforms are building proprietary verification systems.
- Customization:Engraving, birthstone pairing, and modular charm integration extend customer lifetime value through repeat purchase stimulation. California subscription curation services are displacing wholesale-dependent revenue structures.
- Durability:Elastic cord tensile strength, metal alloy corrosion resistance, and stone setting security address practical wear concerns. REACH heavy-metal disclosure requirements are pushing suppliers toward certified lead-free components.
Healing properties retains volume leadership; authenticity holds the steepest expansion curve through regulatory compliance differentiation.
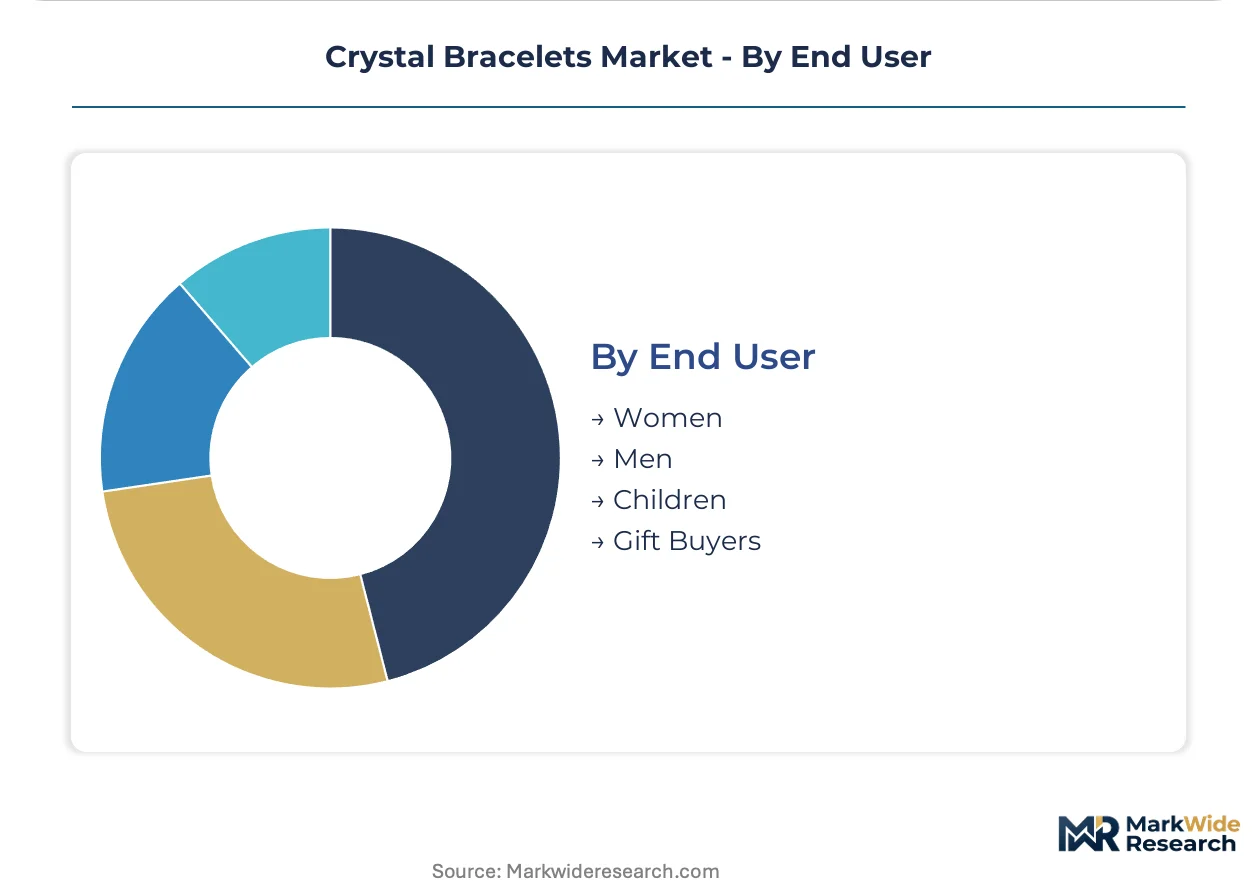
End User:
Customer type concentration determines channel strategy and messaging architecture.
- Women:Primary demand cohort across all product formats, with particular concentration in bangle and cuff variants for formal accessorization. Direct-to-consumer spiritual brands in New York and Los Angeles metropolitan areas show highest adoption density.
- Men:Emerging segment concentrated in obsidian and dark quartz variants marketed through protective or grounding properties. Elastic cord stretch formats dominate for sizing accommodation.
- Children:Safety-constrained segment requiring nickel-free components, breakaway clasps, and non-toxic cord materials. REACH compliance migration shapes sourcing standards.
- Gift Buyers:Occasion-driven purchasers prioritizing packaging presentation, personalization services, and sentiment-appropriate stone selection. Subscription curation models are capturing recurring revenue streams.
Women retain volume leadership; men hold the steepest expansion curve through destigmatized wellness accessory adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in raw quartz and finished crystal jewelry are redrawing trade corridors. Brazil and Madagascar supply rough material to processing hubs in China and India, while finished bracelets flow toward consumer markets in the United States, Germany, and United Kingdom.
United States
Direct-to-consumer spiritual brands and boutique jewelry platforms concentrate demand in California and New York metropolitan clusters. FDA topical claim constraints limit wellness marketing without substantiation, forcing semantic workarounds in product descriptions. Los Angeles hosts the densest concentration of subscription curation services displacing wholesale-dependent revenue structures.
Germany
Boutique platforms command premium margin pools through engraving services and birthstone pairing on bangle variants. ECHA-mandated REACH compliance requires kilogram-level emission tracking from mine extraction through retail distribution. Berlin and Munich processors are building proprietary provenance verification systems to meet EU Green Deal carbon accounting mandates.
United Kingdom
Millennial and Gen Z buyers drive demand for mindfulness-adjacent consumption through specialized spiritual commerce channels. The Competition and Markets Authority enforces greenwashing standards that elevate compliance costs for unverified sourcing claims. London anchors the highest adoption density for direct-to-consumer subscription models among European capitals.
Brazil
Amethyst and quartz rough supply concentrates in Minas Gerais and Rio Grande do Sul mining jurisdictions. Export licensing delays and extraction volatility expose processors to supply interruption risk. São Paulo-based lapidary workshops serve as the primary finishing hub for South American material before trans-Pacific shipment.
China
Laboratory-grown quartz variants capture price-sensitive segments and compress margins on natural stone positioning. The Ministry of Ecology and Environment enforces dual carbon goals that reshape energy-intensive lapidary processing economics. Guangdong Province processors dominate synthetic crystal manufacturing for elastic cord stretch bracelet assembly.
Crystal Bracelets Market Competitive Landscape
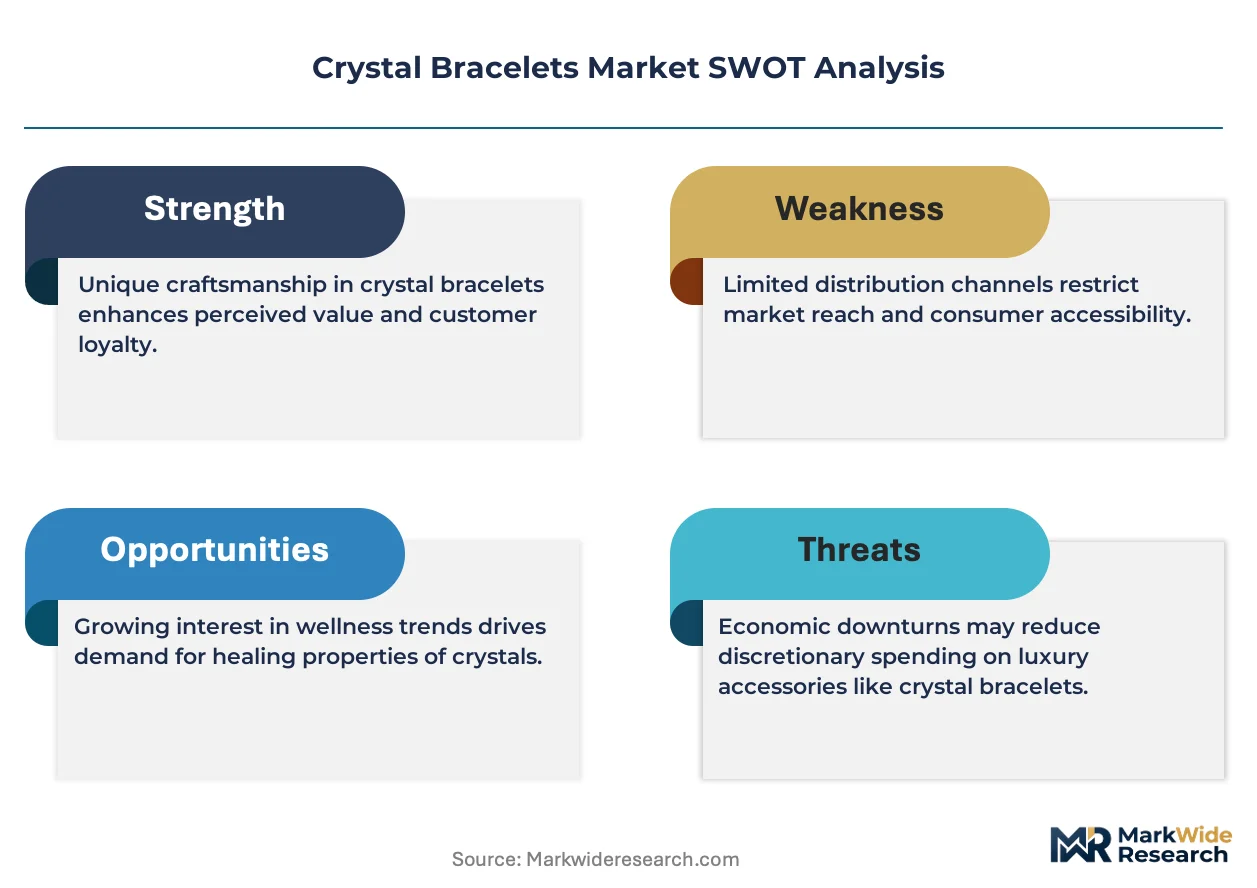
On the supply side, the industry is bifurcated between heritage crystal houses with vertical manufacturing control and asset-light digital-native brands leveraging dropshipping infrastructure. Austrian and Danish heritage players anchor premium positioning through proprietary cutting technology and archival design libraries. Three strategic archetypes dominate: vertically integrated material-science specialists, direct-to-consumer spiritual brands, and fast-fashion jewelry platforms. Competitive moves center on EU Green Deal alignment investments and personalization service attach rates.
Within the heritage crystal tier, Swarovski occupies a position exemplifying premium positioning sustained through Austrian manufacturing heritage and archival collections. Among direct-to-consumer disruptors, Mejuri and Gorjana represent the asset-light archetype, leveraging dropshipping infrastructure to test design variants without inventory carrying costs. Pandora anchors mass-market accessibility through modular charm systems that extend into semi-precious stone variants, sitting within the scale-driven tier that compresses unit economics through volume manufacturing partnerships.
| Leading Market Players |
|---|
| Swarovski |
| Tiffany & Co. |
| Pandora |
| Kendra Scott |
| BaubleBar |
| Astrid & Miyu |
| Monica Vinader |
| Mejuri |
| Gorjana |
| Others |
Pricing and Supply Chain Analysis
Guangdong Province lapidary clusters anchor finished bracelet capacity for elastic cord stretch formats, concentrating downstream pricing power among processors with automated cord-weaving lines and REACH-certified nickel-free component sourcing. Brazilian rough quartz flows through these hubs before reaching California and New York metropolitan retail clusters, with export licensing delays in Minas Gerais mining jurisdictions periodically disrupting contract pricing stability.
Pricing Analysis
Wellness-focused consumers anchor a three-tier pricing structure across premium, standard, and economy levels, with Austrian heritage crystal houses and German boutique platforms commanding brand premiums through engraving services and birthstone pairing. Price differentiation rests on certification grade—ECHA-aligned provenance documentation versus unverified sourcing—and customization depth. Cost compression in economy stretch formats is intensifying because laboratory-grown quartz variants from Chinese processors capture price-sensitive segments. Direct-to-consumer spiritual brands show least price sensitivity; mass-market fast-fashion jewelry platforms exhibit highest.
Supply Chain Analysis
Extended payment terms from São Paulo-based lapidary workshops to Brazilian mining operators are stabilizing rough amethyst and quartz procurement amid extraction volatility. Finished bracelet manufacturing draws from China, India, and Austria, with elastic cord components, nickel-free metal findings, and precision-cut crystal specimens as critical inputs. Single-source vulnerability concentrates in Madagascan rose quartz supply facing export licensing delays. Distribution runs through direct-to-consumer spiritual platforms and boutique jewelry channels displacing wholesale-dependent structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Crystal bracelet demand sits in early-cycle expansion, with Gen Z mindfulness-adjacent consumption penetration in California and New York metropolitan clusters providing durable tailwinds through subscription curation adoption.
For Market Incumbents: Harden EU Green Deal compliance positioning through kilogram-level carbon emission tracking from mine extraction through retail distribution, protecting margin pools against German and French boutique platform proprietary provenance verification systems. Invest in captive lapidary capacity or exclusive artisan apprenticeship pipelines to counter aging cohort scarcity in precision obsidian cutting. For New Entrants and Emerging Players: Male wellness accessory segments in obsidian and dark quartz variants represent the most penetrable entry point, with elastic cord stretch formats eliminating sizing friction and destigmatized protective property marketing bypassing FDA topical claim constraints. California subscription curation infrastructure offers lowest customer acquisition cost through recurring revenue displacement of one-time retail transactions. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors direct-to-consumer spiritual brands with proprietary dropshipping infrastructure and verified mineral provenance systems over asset-heavy manufacturing. Long-term viability hinges on EU Green Deal alignment depth and personalization service attach rates. Monitor ECHA enforcement acceleration as inflection indicator for compliance-differentiated valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| EU Green Deal Alignment Investment | ECHA-mandated carbon accounting creates first-mover advantage for verified provenance suppliers. |
| Personalization Service Expansion | Engraving and birthstone pairing on bangle variants commands margin pools above commodity stretch pricing. |
| Dropshipping Infrastructure Maturation | Asset-light fulfillment networks enable digital-native brands to test design variants without inventory carrying costs. |
| Artisan Apprenticeship Pipeline Development | Precision lapidary skill scarcity threatens obsidian and semi-precious stone finishing capacity. |
| Subscription Curation Model Deployment | Monthly crystal bracelet services capture recurring revenue streams that traditional retail transactions cannot match. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade data, regulatory filings, and industry association reports, combining structured interviews with brand managers at direct-to-consumer spiritual platforms, category buyers at boutique jewelry retailers, supply planners at elastic cord manufacturers, and lapidary workshop operators in São Paulo and Guangdong Province. Bottom-up demand modeling from consumer adoption patterns triangulates against top-down market sizing from customs records and retail audit data.
Forecast inputs incorporate product type segmentation across stretch, bangle, cuff, and chain formats; material tier stratification from laboratory-grown quartz to heritage crystal positioning; and feature intensity from healing property claims to authenticity verification depth. CAGRs derive from regression analysis against wellness-adjacent consumption penetration rates and regulatory compliance migration timelines, with elastic cord manufacturing automation curves and ECHA enforcement acceleration as industry-specific variables across the projection horizon.
Stress conditions across Brazilian and Madagascan export licensing volatility, FDA topical claim enforcement intensity, and synthetic crystal substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding Gen Z mindfulness adoption persistence and EU Green Deal implementation sequencing. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Jewelry
Bead Products Market
Jewelry
Customized Jewelry Market
Jewelry
Global Gems and Jewelry Market
Jewelry
Imitation Jewelry Market
Jewelry
South Korea Luxury Jewelry Market
Jewelry
Chalcedony Earrings Market
Jewelry
3D Printed Jewelry Market
Jewelry
Diamond Jewelry Market
Jewelry
Wedding Rings Market
Jewelry
Demi-Fine Jewelry Market
Jewelry
Latin America Jewelry Market
Jewelry
3D Printing for Jewelry Market
Jewelry
Leather Jewellery Box Market
Jewelry
Colorful Gold Jewelry Market
Jewelry
Pearl Jewelry Market
Jewelry
Luxury Fine Jewellery Market