
 Jewelry Cleaners Market | 2026-2036
Jewelry Cleaners Market Size, Share, and Industry Trends Forecast 2026-2036
Jewelry Cleaners Market Foresight
Individual consumers is rotating toward higher purchase frequency as post-pandemic self-care rituals solidify. Branson leverages its ultrasonic engineering heritage to anchor industrial-grade credibility in residential channels. Connoisseurs Products sustains mass-market penetration through pharmacy and big-box placement. GTSONIC competes aggressively on price-performance ratios in direct-to-consumer ultrasonic units.
Jewelry cleaners encompass specialized chemical formulations and mechanical devices designed to remove tarnish, oils, and particulate matter from precious metals and gemstones without substrate damage; ultrasonic variants operate at frequencies between 20–45 kHz to cavitate cleaning solutions in microscopic crevices. Liquid cleaners maintain the largest volume position due to low cost and universal compatibility, though ultrasonic cleaners capture disproportionate margin as consumers upgrade from manual methods. Eco-friendly formulations represent the fastest-expanding segment within chemical-based offerings, pressured by ingredient transparency mandates and retail buyer ESG screening.
EPA oversight of volatile organic compounds and state-level California Proposition 65 disclosure requirements constrain formulation freedom for chemical-based products sold in the United States. REACH registration obligations in Europe impose similar substance restrictions, while China's GB standards govern labeling and safety thresholds for imported cleaning agents. Stakeholders must monitor evolving chemical restriction lists and certification requirements to sustain cross-border product mobility.
Market Dynamics
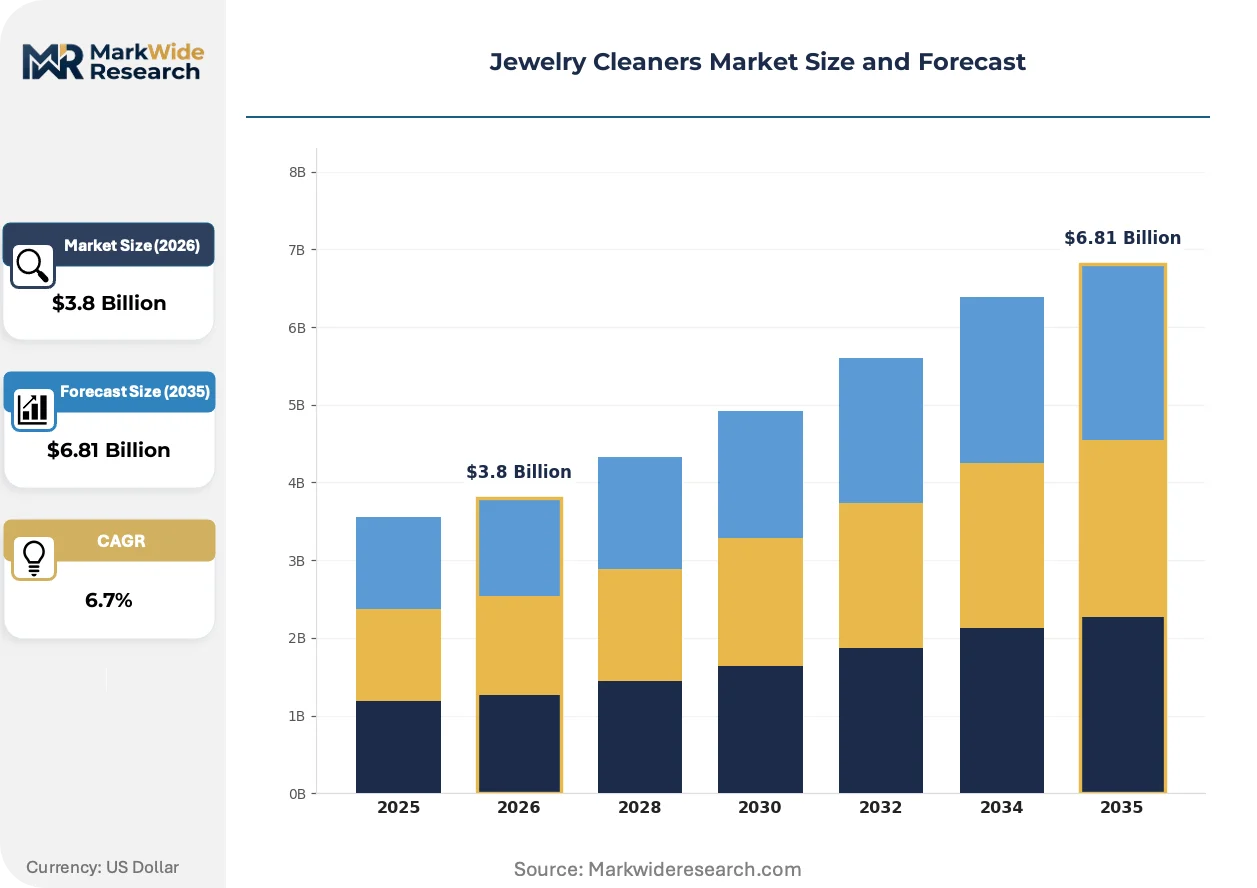
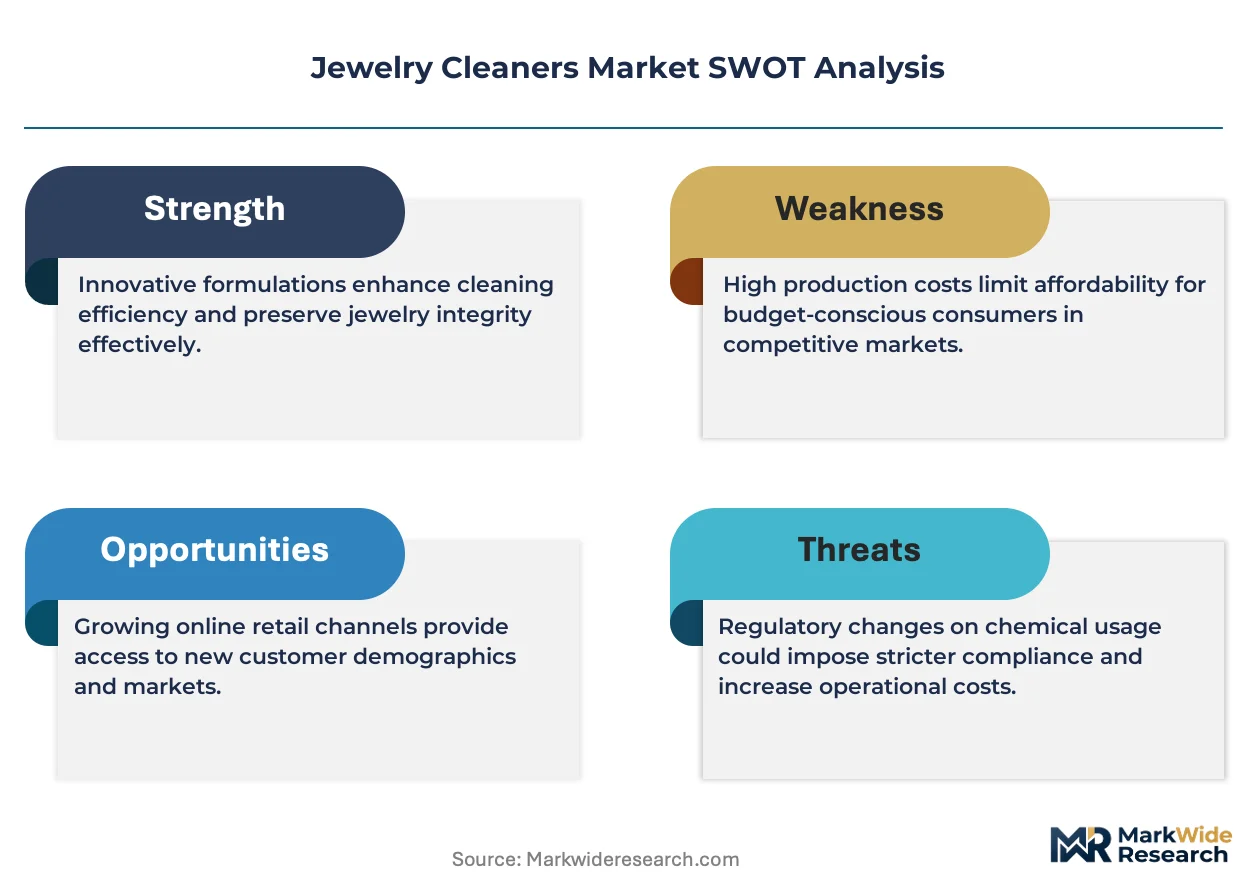
REACH compliance in Europe and California Proposition 65 disclosure mandates are forcing wholesale reformulation of chemical-based jewelry cleaners, compressing legacy solvent portfolios while opening certification premiums for compliant alternatives.
Growth Catalysts
- Ultrasonic frequency engineering:Advancements in 20–45 kHz transducer miniaturization enable residential-grade cavitation performance previously restricted to industrial units.
- EPA volatile organic compound thresholds:Stricter federal emission caps accelerate water-based and plant-derived solvent substitution across US distribution channels.
- Post-pandemic self-care ritualization:Individual consumers in the United States, China, and Germany now treat at-home jewelry maintenance as recurring hygiene practice rather than episodic repair.
Market Restraints
- Petrochemical feedstock volatility:Surfactant and solvent input costs fluctuate with crude oil indices, squeezing margin on mass-market liquid formulations.
- Supply concentration in East Asian transducer manufacturing:Ultrasonic generator and piezoelectric component assembly clusters in Guangdong province create single-point vulnerability for device OEMs.
- Technical ceiling on gemstone compatibility:Organic porous stones including opal, pearl, and turquoise suffer structural damage from ultrasonic cavitation, limiting addressable SKU range.
Strategic Opportunities
- India's underpenetrated premium jewelry aftermarket:Rising gold and diamond ownership in tier-2 cities outpaces professional cleaning infrastructure, creating white space for home-use device penetration.
- EU Green Deal chemical substitution incentives:REACH-registered bio-based surfactant formulations qualify for accelerated retail listing and ESG procurement preferences.
- Subscription replenishment models:Direct-to-consumer brands bundle concentrated cleaning solutions with automated reorder algorithms, capturing lifetime value from ultrasonic device purchasers.
Industry Challenges
- Formulation chemist scarcity:Expertise in precious-metal-safe surfactant chemistry concentrates among aging specialists in Basel and New Jersey corridors, constraining R&D velocity.
- Multi-jurisdiction certification timelines:Simultaneous EPA FIFRA registration, REACH dossier submission, and China GB standard testing extend product launch cycles by 18–24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Jewelry Cleaners Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic Cleaners, Liquid Cleaners, Foam Cleaners, Wipes End User: Retail Jewelers, Online Retailers, Individual Consumers, Professional Cleaners Distribution Channel: Online Stores, Specialty Retailers, Wholesale Distributors, Supermarkets Formulation: Eco-Friendly Solutions, Chemical-Based Cleaners, Alcohol-Based Cleaners, Non-Toxic Options |
| Companies Covered | Branson, Sonicor, GTSONIC, Ultrasonic Power Corporation, Connoisseurs Products, Magnasonic, The Kingswood Company, NuGenTec, iSonic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Jewelry Cleaners Market Shifts & Advancements
Formulation transparency and mechanical automation are converging to split the jewelry cleaners market between premium certified-chemical offerings and connected ultrasonic hardware with consumable lock-in.
Plant-derived surfactant chemistry is decomposing petroleum-based solvent dominance in liquid cleaner portfolios. Boutique formulators in Provence and Oregon commercialize saponin and terpene extracts that satisfy ECHA REACH restrictions without sacrificing tarnish removal efficacy. Individual consumers and independent jewelers adopt these alternatives fastest, compressing shelf space for conventional ammonia-based solutions in European pharmacy and specialty retail.
REACH substance restriction lists now explicitly target boron compounds and certain glycol ethers prevalent in legacy dip formulations. The European Chemicals Agency's 2024 candidate list expansion forces reformulation investments exceeding seven figures for mid-sized chemical suppliers. Professional cleaning service chains in Germany and France accelerate compliance fastest, converting inventory to certified bio-based alternatives ahead of enforcement deadlines.
After-sales service unbundling disrupts traditional jewelry retail. Independent ultrasonic device owners bypass professional cleaning appointments, instead purchasing concentrated solutions and replacement baskets through manufacturer-direct portals. This behavioral shift concentrates most visibly in the United States, where Amazon and DTC brand sites capture consumable reorder frequency previously directed toward mall-based jewelers.
Jewelry Cleaners Market Segmentation
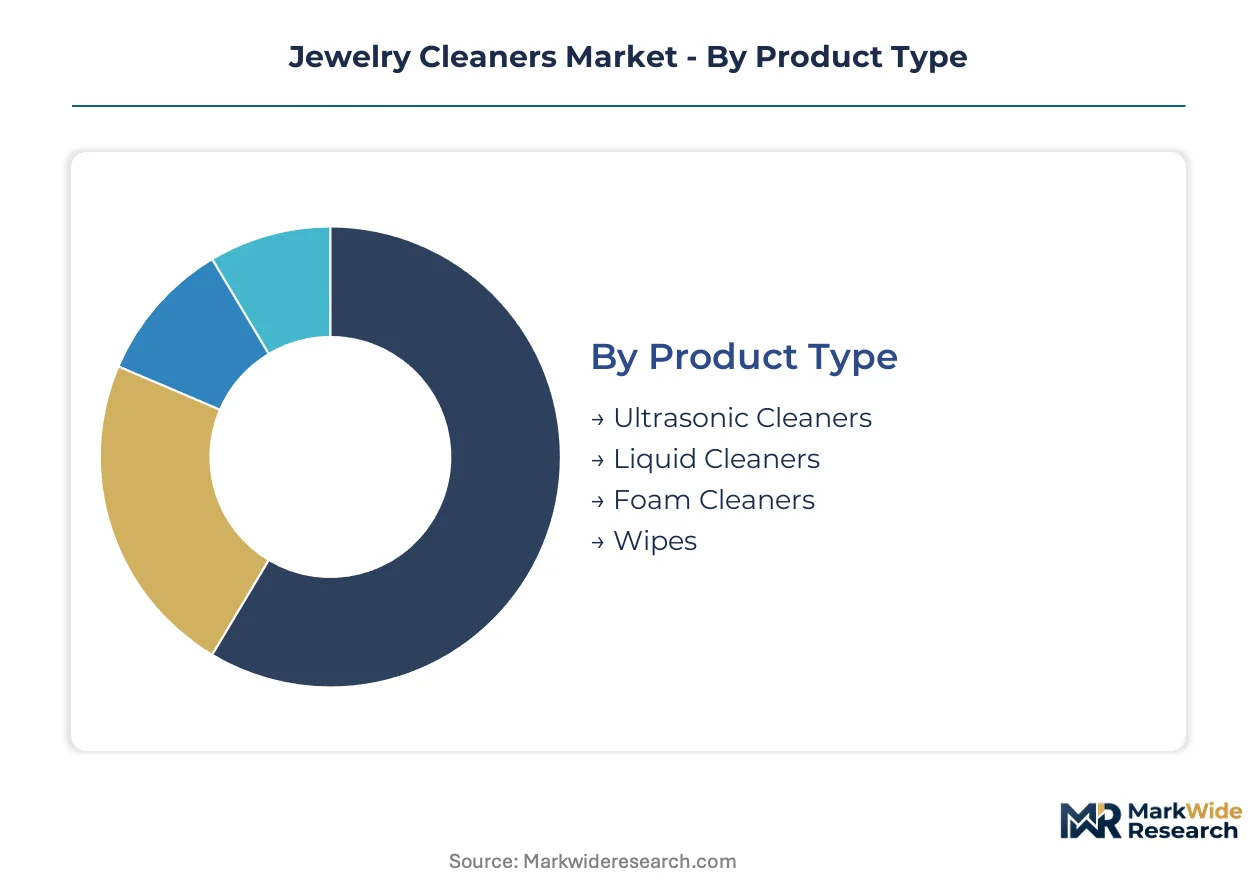
Jewelry cleaner purchasing patterns diverge sharply between maintenance rituals and professional service substitution, with ultrasonic devices displacing chemical solutions in premium households while liquid formulations retain pharmacy-channel dominance for occasional users.
Product Type:
Liquid cleaners face the most acute substitution pressure as ultrasonic devices achieve price-performance parity and consumers upgrade from manual to mechanical maintenance.
- Liquid Cleaners:Water-based and solvent formulations packaged in dip jars or spray bottles, compatible with all gemstone types including porous organic stones. Concentrated demand persists in United States pharmacy chains and German drugstore networks where low price points and impulse placement sustain replenishment cycles despite ultrasonic encroachment.
- Ultrasonic Cleaners:Cavitation devices operating at 20–45 kHz frequencies to dislodge particulate matter from metal settings and stone crevices without abrasive contact. Adoption concentrates in Chinese and American metropolitan households with elevated jewelry ownership density, driven by post-pandemic self-care ritualization and DTC brand marketing emphasizing professional-grade results.
- Foam Cleaners:Aerosol-dispensed surfactant formulations offering controlled application for intricate settings.
- Wipes:Pre-saturated disposable cloths targeting travel and on-the-go maintenance occasions.
Liquid cleaners anchor the volume base while ultrasonic cleaners gain share at the steepest rate.
End User:
Cost tier stratification separates professional service providers from at-home adopters, with retail jewelers absorbing margin compression from device-enabled consumer bypass.
- Individual Consumers:Household purchasers treating jewelry maintenance as recurring hygiene practice rather than episodic repair event. This segment in the United States, China, and Germany drives ultrasonic device volume and concentrated solution subscription models, displacing professional cleaning appointments at accelerating rates.
- Retail Jewelers:Brick-and-mortar operators offering in-house cleaning as customer retention and traffic generation tool. German and French chains face the steepest revenue erosion as device ownership penetrates their client base, forcing pivot toward repair services and certified stone treatments.
- Professional Cleaners:Dedicated service operations handling estate jewelry and high-value collections.
- Online Retailers:E-commerce platforms bundling devices with consumable replenishment.
Retail jewelers retain the highest transaction values per cleaning event while individual consumers expand the addressable population fastest.
Distribution Channel:
Application context determines channel selection, with specialty retailers capturing education-intensive ultrasonic sales and online stores dominating replenishment economics.
- Online Stores:Direct-to-consumer portals and marketplace platforms capturing ultrasonic device sales and concentrated solution subscriptions. Amazon and manufacturer-direct sites in the United States now handle the majority of post-purchase consumable reorders, consolidating lifetime value previously fragmented across mall-based jewelers.
- Specialty Retailers:Independent jewelers and watch boutiques providing hands-on demonstration and purchase consultation. These outlets in Germany and Switzerland sustain premium device placement through staff training and in-store trial experiences that validate cavitation claims.
- Supermarkets:Mass-market liquid cleaner placement for impulse and routine replenishment.
- Wholesale Distributors:B2B supply to professional cleaning operations and retail chains.
Specialty retailers anchor premium device penetration while online stores capture the steepest expansion in consumable reorder frequency.
Formulation:
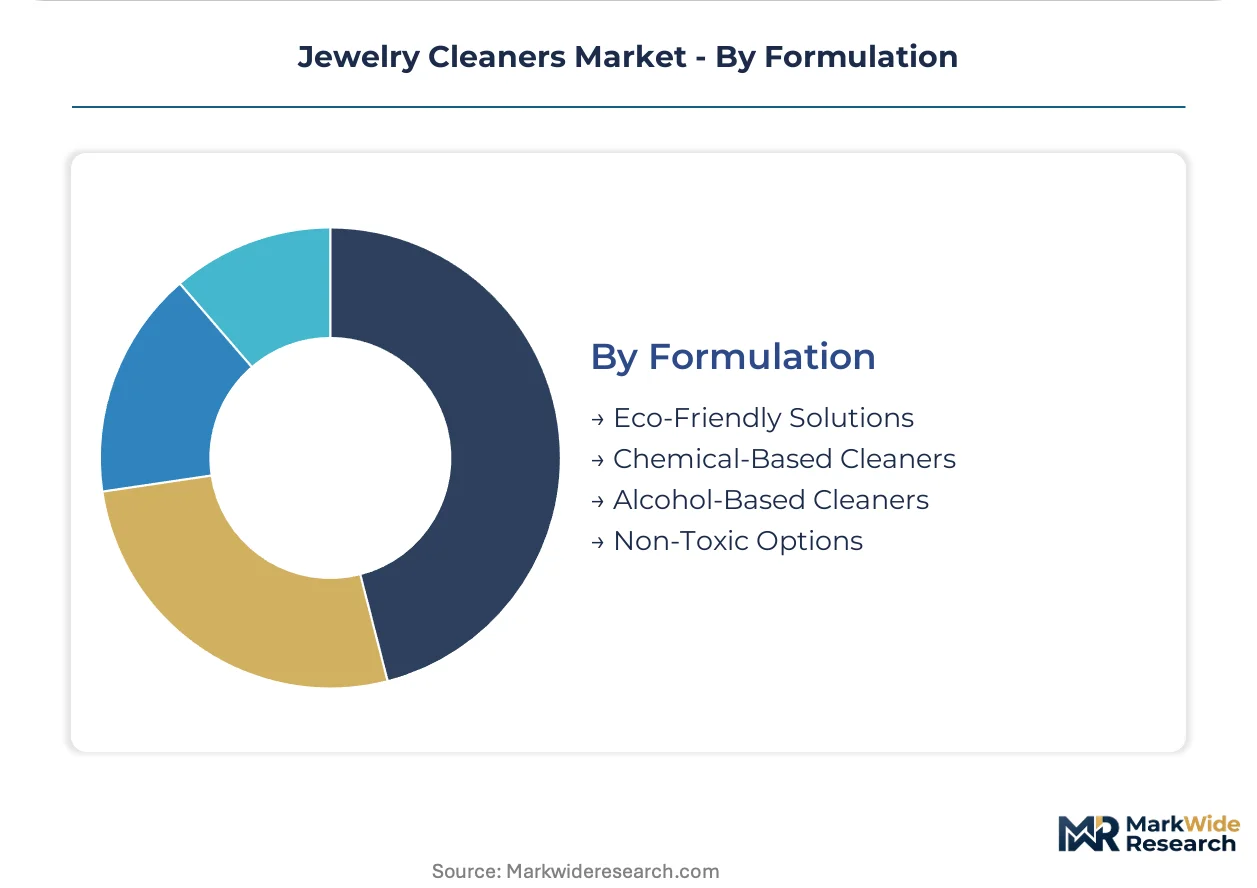
Margin structure separates certified-compliant offerings from commodity chemistry, with REACH and EPA registration costs creating tiered pricing stratification.
- Eco-Friendly Solutions:Plant-derived surfactant formulations utilizing saponin and terpene extracts from Provence and Oregon suppliers. Demand concentrates in European pharmacy networks and ESG-screened procurement channels, where REACH registration and EU Green Deal incentives accelerate shelf space conversion from ammonia-based alternatives.
- Chemical-Based Cleaners:Petroleum-derived solvent and surfactant formulations including ammonia and glycol ether variants. Legacy portfolios face reformulation mandates from ECHA candidate list expansions and California Proposition 65 disclosure requirements, compressing margin and extending certification timelines.
- Alcohol-Based Cleaners:Isopropyl and ethanol formulations targeting rapid evaporation and residue-free finishing.
- Non-Toxic Options:Marketing-positioned alternatives emphasizing child and pet safety claims.
Chemical-based cleaners anchor current volume while eco-friendly solutions climb the fastest under regulatory substitution pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Individual consumers in the United States, China, and Germany anchor jewelry cleaner demand, with professional service substitution and at-home maintenance rituals driving divergent channel preferences across these core markets.
United States
Post-pandemic self-care ritualization sustains ultrasonic device adoption in metropolitan households with elevated jewelry ownership density. EPA volatile organic compound thresholds and California Proposition 65 disclosure mandates compress legacy solvent portfolios while accelerating water-based formulation substitution. Amazon and manufacturer-direct portals in California and New York now capture the majority of concentrated solution reorders, consolidating lifetime value previously fragmented across mall-based jewelers.
China
Rising gold and diamond ownership in tier-2 cities outpaces professional cleaning infrastructure, creating white space for home-use device penetration. GB standards govern labeling and safety thresholds for imported cleaning agents, while dual carbon goals pressure domestic formulators toward bio-based surfactant development. Guangdong province clusters ultrasonic generator and piezoelectric component assembly, creating single-point vulnerability for device OEMs dependent on East Asian transducer manufacturing.
Germany
Professional cleaning service chains accelerate REACH compliance fastest, converting inventory to certified bio-based alternatives ahead of enforcement deadlines. ECHA candidate list expansions force reformulation investments exceeding seven figures for mid-sized chemical suppliers. Independent jewelers in Munich and Hamburg sustain premium device placement through staff training and in-store trial experiences that validate cavitation claims.
India
Underpenetrated premium jewelry aftermarket in tier-2 cities creates expansion opportunity for ultrasonic device brands and concentrated solution subscriptions. BIS standards and DGFT import regulations govern device safety certifications and chemical labeling requirements for foreign suppliers. Maharashtra and Gujarat industrial corridors host emerging domestic assembly operations targeting price-sensitive consumer segments.
France
Boutique formulators in Provence commercialize saponin and terpene extracts that satisfy ECHA REACH restrictions without sacrificing tarnish removal efficacy. EU Green Deal chemical substitution incentives accelerate retail listing for bio-based surfactant formulations. Paris pharmacy networks and specialty retailers compress shelf space for conventional ammonia-based solutions as ESG-screened procurement preferences reshape category management.
Jewelry Cleaners Market Competitive Landscape
Player mix skews toward ultrasonic engineering specialists and mass-market chemical formulators, with mid-tier device OEMs competing aggressively on price-performance ratios. The market exhibits moderate concentration at the premium tier, where industrial-grade heritage anchors residential credibility, while private-label and regional brands fragment the liquid cleaner base. Strategic archetypes include transducer technology licensors, pharmacy-channel chemical suppliers, and direct-to-consumer device brands with consumable lock-in models. Dominant competitive moves center on REACH-compliant formulation certification and subscription replenishment algorithm development.
Among engineering-heritage specialists, Branson leverages its ultrasonic engineering heritage to anchor industrial-grade credibility in residential channels. GTSONIC competes aggressively on price-performance ratios in direct-to-consumer ultrasonic units. Connoisseurs Products sustains mass-market penetration through pharmacy and big-box placement, representing the chemical-formulation archetype with established retail relationships. These three occupy positions across the technology-chemistry spectrum, with Branson exemplifying premium engineering credibility, GTSONIC anchoring accessible device pricing, and Connoisseurs Products representing legacy retail-channel dominance.
| Leading Market Players |
|---|
| Branson |
| Sonicor |
| GTSONIC |
| Ultrasonic Power Corporation |
| Connoisseurs Products |
| Magnasonic |
| The Kingswood Company |
| NuGenTec |
| iSonic |
| Others |
Supply & Pricing Matrix
Plant-derived surfactant substitution for petroleum-based solvents simultaneously shifts procurement geography toward Provence and Oregon suppliers while compressing margin structures for legacy ammonia-based formulations. This input transition redistributes value capture from commodity chemical producers to certified bio-based specialists, altering price-setting power across formulation tiers.
Pricing Analysis
Current-generation ultrasonic devices command three-to-five-fold premiums over prior-generation manual cleaning kits, while next-generation connected units with subscription lock-in are testing further upward extensions. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in mass-market liquid formulations is intensifying because REACH registration expenses and feedstock volatility squeeze mid-tier chemical suppliers. Individual consumers in pharmacy channels exhibit highest price sensitivity, whereas professional cleaning service chains absorb premium pricing for certified-compliant alternatives.
Supply Chain Analysis
China anchors ultrasonic generator and piezoelectric component assembly, with Guangdong province hosting concentrated transducer manufacturing. Germany and Switzerland supply precision-engineered cavitation hardware for premium residential units. Raw material flows draw from rare earth elements for piezoelectric ceramics, petrochemical feedstocks for surfactant synthesis, and botanical extracts for bio-based formulations. Single-source vulnerability in East Asian transducer manufacturing exposes device OEMs to logistics chokepoint risk. Distribution runs through Amazon and manufacturer-direct portals for consumable replenishment, while specialty retailers handle education-intensive ultrasonic device sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Jewelry cleaners represent an early-cycle expansion story as at-home maintenance rituals displace professional service appointments across United States, Chinese, and German households. Post-pandemic behavioral shifts toward recurring self-care hygiene sustain penetration velocity for ultrasonic devices and concentrated solution subscriptions.
For Market Incumbents: Fortify certification moats by accelerating REACH dossier completion and EPA FIFRA registration ahead of enforcement deadlines. Secure backward integration into bio-based surfactant supply through partnerships with Provence and Oregon boutique formulators. Channel control represents the critical lever against DTC entrants capturing consumable reorder frequency via Amazon and manufacturer-direct portals. For New Entrants and Emerging Players: Subscription replenishment algorithm development offers the most penetrable service-layer gap where incumbents under-serve device owners with automated reorder experiences. Target India's tier-2 cities where gold and diamond ownership growth outpaces professional cleaning infrastructure. A direct-to-consumer launch bundling ultrasonic hardware with concentrated solution subscriptions captures lifetime value faster than pharmacy-channel liquid cleaner placement. For Investors and Strategic Acquirers: The market sits at a consolidation-ready phase that favors vertically integrated specialists with captive formulation and device assembly capabilities. Acquisition targets should demonstrate REACH-registered bio-based portfolios and established Amazon storefront operations. Watch ultrasonic device penetration rates in Indian tier-2 cities as the signal indicating whether geographic expansion justifies capacity buildout investments.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Formulation Certification | ECHA registration unlocks EU pharmacy shelf space and ESG procurement preferences. |
| Subscription Replenishment Model Launch | Automated reorder algorithms capture lifetime value from ultrasonic device purchasers. |
| Backward Integration into Bio-Based Surfactants | Provence and Oregon supplier partnerships secure input cost stability and differentiation. |
| Direct-to-Consumer Channel Expansion | Amazon and manufacturer-direct portals consolidate consumable reorder frequency. |
| India Market Entry | Tier-2 city penetration addresses gold ownership growth outpacing professional cleaning infrastructure. |
Research Methodology
The analysis maps liquid cleaners, ultrasonic devices, foam formulations, and eco-friendly surfactants, each validated through procurement managers at retail jewelers, pharmacy category buyers, ultrasonic device OEM engineers, and formulation chemists at chemical suppliers. Primary interview insights triangulate against customs records, EPA FIFRA registration databases, ECHA REACH dossiers, and SEC 10-K filings from listed chemical and device manufacturers. Bottom-up unit economics and top-down category sizing converge through iterative stakeholder cross-checking.
Consistency checks validate volume and value outputs against external benchmarks across the analysis window. Segmentation dimensions model product type, end-user archetype, distribution channel, and formulation chemistry tier. CAGRs derive from installed base growth rates for ultrasonic devices, replenishment frequency shifts in liquid cleaners, and regulatory-driven substitution elasticities for eco-friendly formulations. Pricing trajectories incorporate feedstock cost indices and certification premium elasticities.
Forecasts assume regulatory continuity in EU REACH, US EPA, and China GB standards; material policy shifts would require re-modeling. Forecasts reflect assumptions about self-care ritual persistence, professional service substitution velocity, and transducer manufacturing supply stability. Recalibration cycles align with material shifts in ECHA candidate list expansions, EPA emission threshold revisions, and Indian BIS standard adoptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Jewelry
Global Costume Jewelry Market
Jewelry
Smart Jewelry Market
Jewelry
3D Printing for Jewelry Market
Jewelry
Brazil Jewelry Market
Jewelry
Global Jewelry Market
Jewelry
Jewellery Box Market
Jewelry
Chalcedony Earrings Market
Jewelry
Pearl Jewelry Market
Jewelry
Asia-Pacific Luxury Jewelry Market
Jewelry
Colorful Gold Jewelry Market
Jewelry
Leather Jewellery Box Market
Jewelry
South Africa Luxury Jewelry Market
Jewelry
Beaded Jewelry Market
Jewelry
Bead Products Market
Jewelry
3D Printed Jewelry Market
Jewelry
South Korea Luxury Jewelry Market