
 Global Gems and Jewelry Market | 2026-2036
Global Gems and Jewelry Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gems and Jewelry Market Analysis
Luxury gifting is repositioning as the fastest-expanding end-use vertical, overtaking traditional ceremonial purchases in volume growth across digital channels. Chow Tai Fook Jewellery Company leverages its mainland China retail density to dominate mass-premium bridal segments. Cartier sustains its heritage positioning through controlled scarcity in high-jewelry collections. Harry Winston anchors ultra-high-net-worth demand with exceptional stone sourcing and private salon distribution.
Gems and jewelry encompass precious and semi-precious stones set in noble metals, with karat purity, cut grades, and clarity indices determining commercial value and industrial application in both adornment and wealth storage. Gold and diamond materials command the deepest margin pools due to enduring cultural liquidity and certification premiums, while platinum competes on density and hypoallergenic properties in bridal applications. Online retail distribution is accelerating fastest among channels, though specialty stores retain transaction value leadership through tactile verification and bespoke services.
The U.S. Federal Trade Commission (FTC) Guides for the Jewelry, Precious Metals, and Pewter Industries enforce disclosure standards for gemstone treatments and metal content, shaping product labeling and consumer trust across export markets. India's BIS hallmarking mandate and the EU's Conflict Minerals Regulation together force upstream traceability investments that filter through to retail pricing and supplier qualification. Stakeholders must monitor evolving ESG disclosure requirements from mine to retail, as provenance transparency becomes a non-negotiable purchase criterion rather than a premium differentiator.
Market Dynamics
Digital provenance verification and hallmarking mandates are compressing traditional opacity in gem sourcing, forcing upstream traceability investments that reshape margin allocation between miners, cutters, and retailers.
Growth Catalysts
- India's BIS Hallmarking Mandate:Mandatory purity certification expands addressable demand among trust-sensitive middle-class buyers entering organized retail channels.
- Luxury Gifting Digitalization:High-net-worth purchasers now complete exceptional stone acquisitions through encrypted virtual consultations, collapsing geographic friction in ultra-premium transactions.
- Blockchain Traceability Protocols:Distributed ledger systems document mine-to-retail custody chains, satisfying EU Conflict Minerals Regulation disclosure requirements without manual audit burden.
Market Restraints
- Gold Price Volatility:Input cost swings compress fabrication margins for karat-heavy bridal inventory held across extended selling seasons.
- Antwerp Cutting Concentration:Rough diamond polishing gravity in Belgium creates single-point vulnerability for midstream supply continuity.
- Lab-Grown Diamond Substitution:Cultured stones erode natural diamond price premiums in sub-one-carat bridal segments where clarity documentation matters less.
Strategic Opportunities
- Vietnam's Underpenetrated Bridal Market:Rising urban household wealth and limited organized retail presence create first-mover positioning for certified jewelry chains.
- Regenerative Mining Certification:EU Green Deal-aligned environmental standards reward compliant African producers with preferential European market access.
- AI-Assisted Custom Design:Generative tools converge with 3D printing to enable mass-customized ceremonial pieces without master craftsman bottlenecks.
Industry Challenges
- Gemmologist Talent Scarcity:Trained stone graders capable of origin verification command premium compensation, constraining expansion timelines for certification-dependent retailers.
- Legacy ERP Integration:Traceability data formats from artisanal mining cooperatives resist seamless ingestion into corporate supply chain management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gems and Jewelry Market |
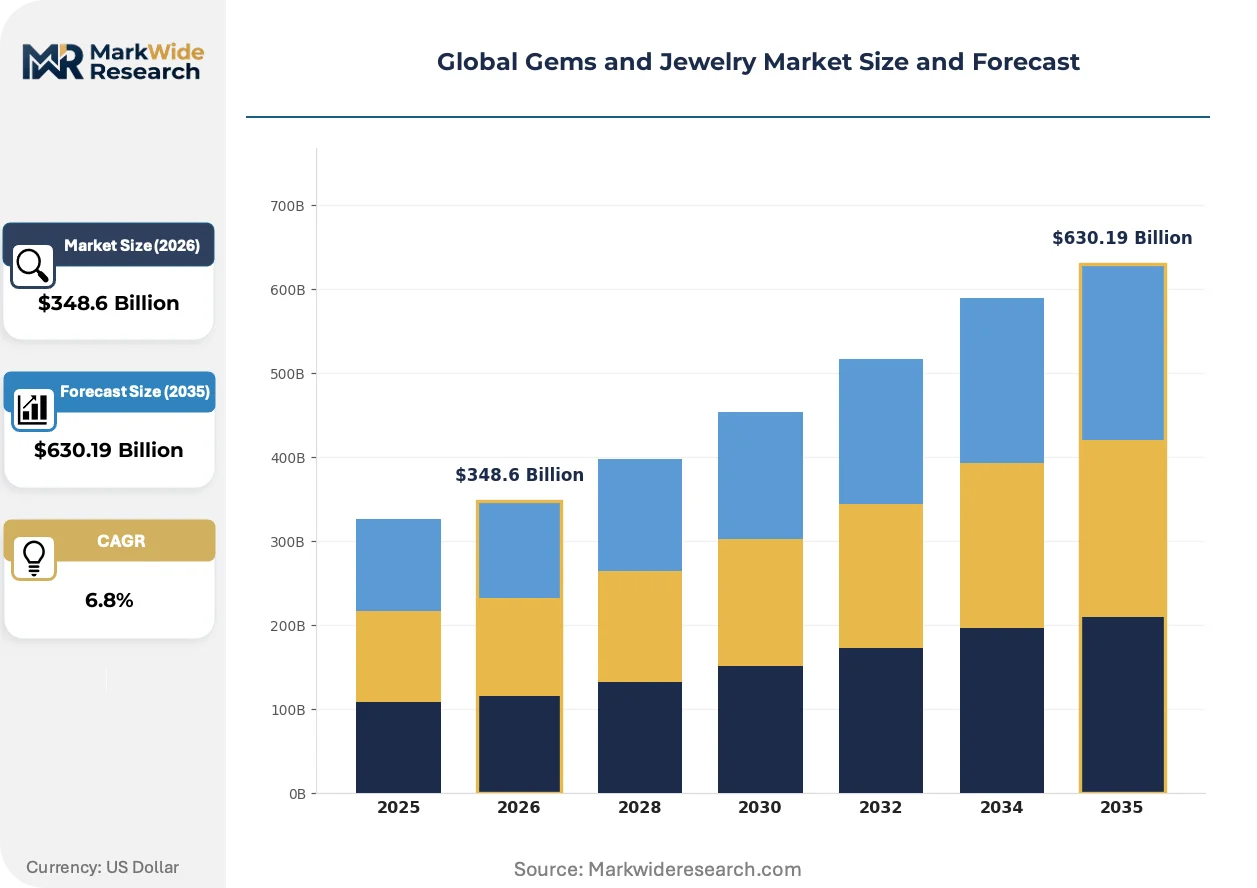
| Market Size in 2026 | $348.6 Billion |
| Market Size in 2035 | $630.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rings, Necklaces, Bracelets, Earrings Material: Gold, Silver, Platinum, Diamonds Distribution Channel: Online Retail, Specialty Stores, Department Stores, Direct Sales Customer Type: Bridal, Fashion, Luxury, Custom |
| Companies Covered | Bvlgari, Graff, Cartier, Boucheron, Chopard, Van Cleef & Arpels, Harry Winston, Chow Tai Fook Jewellery Company, Tiffany & Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gems and Jewelry Market Emerging Trajectories
Blockchain-based custody documentation and AI-driven personalization engines are dissolving traditional information asymmetries between sellers and buyers across all price tiers.
Laser inscription technology is integrating microscopic identification codes directly onto diamond girdles, linking physical stones to digital provenance records. Mid-market bridal retailers adopt these systems fastest to differentiate against uncertified competitors. The technology is integrating previously fragmented custody documentation into unified, transferable asset records that reduce resale authentication friction.
The EU's Conflict Minerals Regulation now requires downstream jewelry manufacturers to conduct and disclose supply chain due diligence for tin, tantalum, tungsten, and gold originating from conflict-affected regions. Compliance costs concentrate on small-scale fabricators lacking dedicated legal resources. Italian luxury houses have responded by consolidating supplier bases to pre-qualified, audit-ready mining cooperatives in Botswana and Canada.
Certification-driven purchasing now dominates engagement ring selection, with buyers prioritizing GIA or IGI grading reports over brand heritage in final decisions. Digital-native retailers capture this shift through transparent pricing tools that decompose cut, color, clarity, and carat premiums in real time. China and India exhibit this behavior most acutely, where first-generation middle-class consumers lack inherited brand loyalties and rely on documented quality metrics for confidence.
Global Gems and Jewelry Market Segmentation
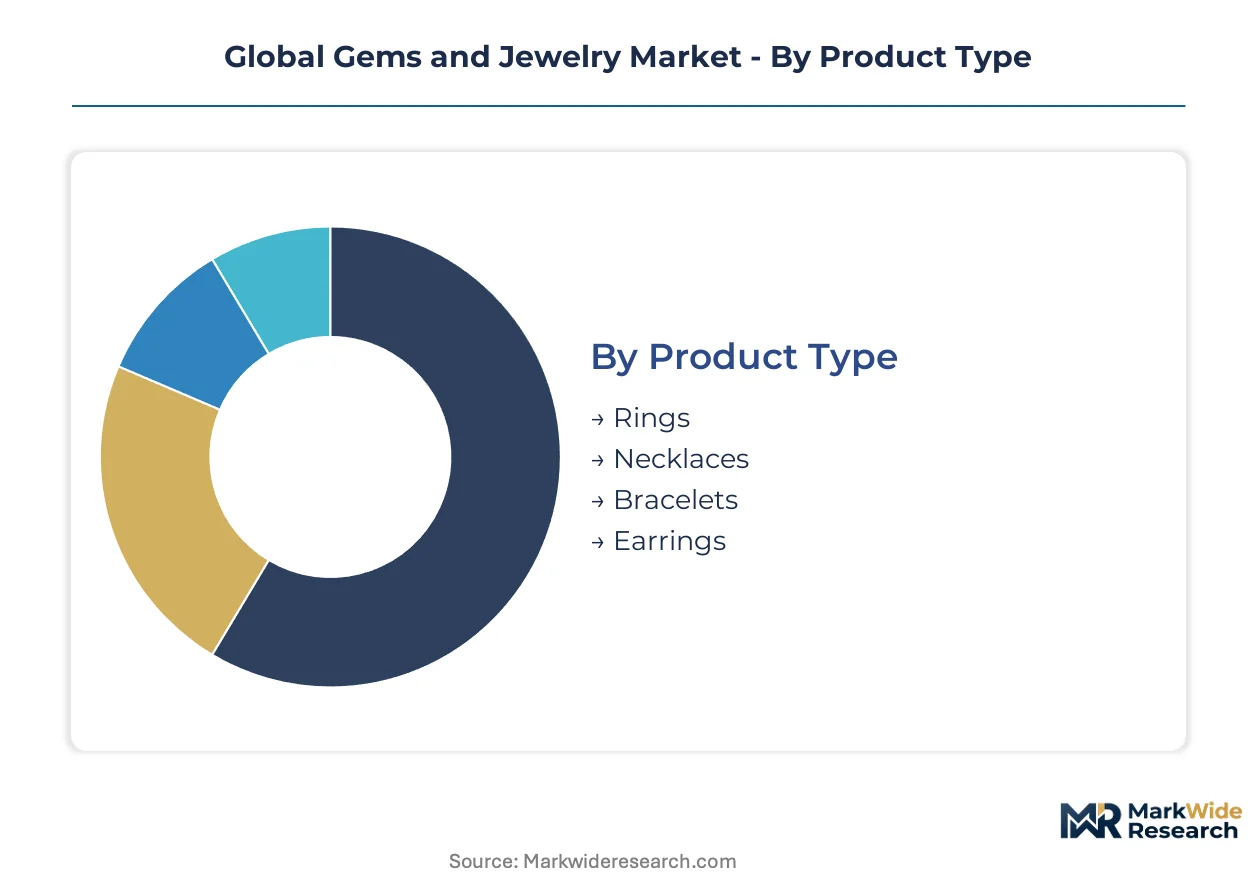
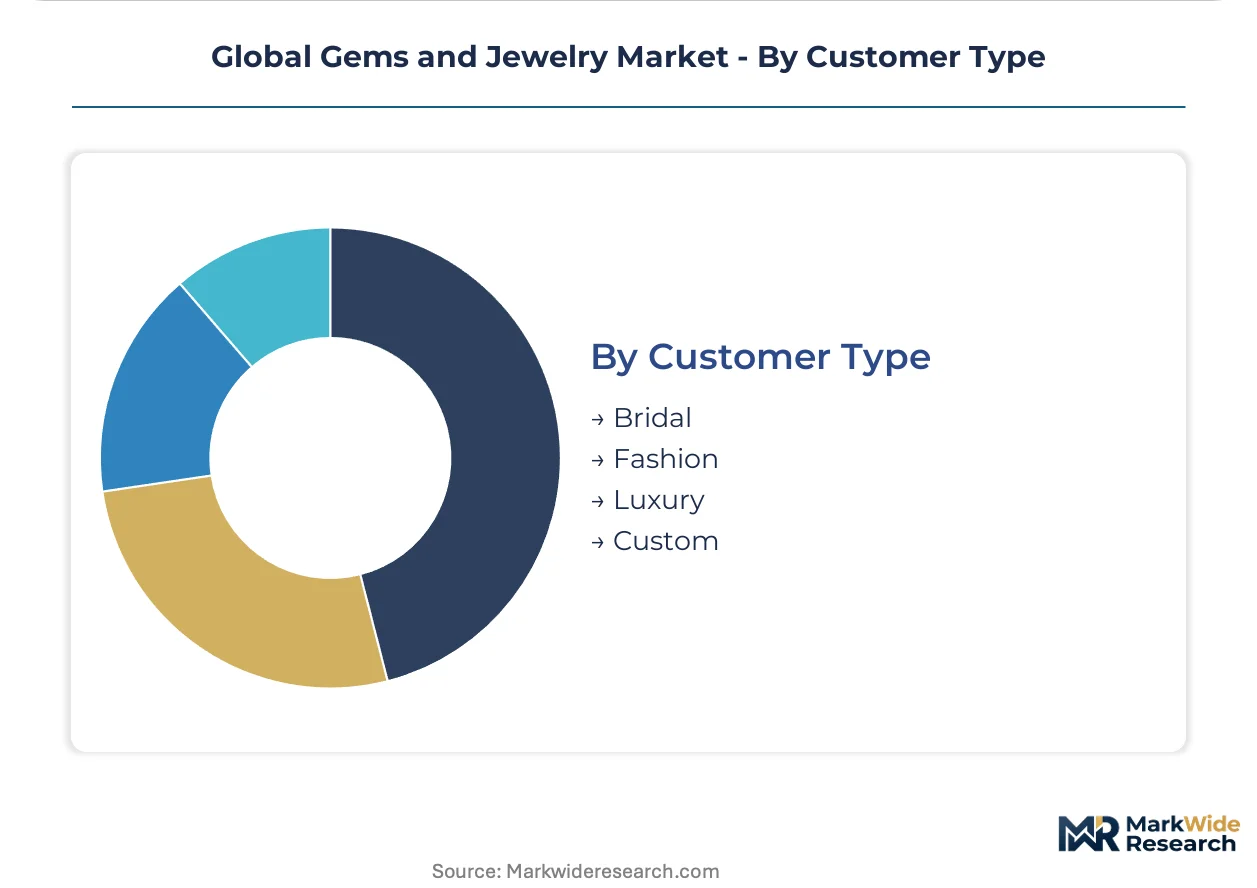
Segmentation in gems and jewelry reveals how capital intensity, certification requirements, and channel economics allocate margin across distinct buyer occasions. Understanding these divisions exposes where traceability investments concentrate and which product-material-channel combinations generate sustainable returns.
Product Type:
Capital intensity varies sharply across form factors, with inventory carrying costs and certification complexity driving divergent investment thresholds.
- Rings:Bridal applications dominate volume, requiring substantial karat-weight gold holdings and GIA grading documentation for diamond center stones. China and India absorb the majority of production, where mandatory BIS hallmarking and digital provenance verification reshape working capital requirements for retailers.
- Necklaces:Higher average ticket sizes and complex clasp engineering demand specialized manufacturing partnerships. Italian fabrication clusters in Vicenza and Arezzo supply luxury houses with 18-karat chain assemblies, while Indian manufacturers compete on 22-karat ceremonial lengths for Middle Eastern export markets.
- Bracelets:Modular link construction enables mass customization without master craftsman bottlenecks, lowering unit capital requirements compared to solitaire settings.
- Earrings:Smaller stone weights reduce per-unit certification costs, making this form factor attractive to entry-level digital-native retailers.
Rings absorb the bulk of installed capacity; earrings are expanding most quickly through direct-to-consumer digital channels.
Material:
Raw material procurement shapes balance sheet structure, with precious metal vaulting and rough diamond sourcing demanding fundamentally different financing instruments.
- Gold:Bullion banking relationships and hedging instruments dominate working capital strategy. Indian organized retailers maintain 22-karat inventory depth for wedding season demand, while Italian luxury houses concentrate on 18-karat alloys for EU export compliance.
- Diamonds:Rough sourcing through De Beers sightholder contracts or Antwerp tenders requires multi-million dollar credit facilities. Midstream cutters in Surat, India process the majority of global volume, creating geographic concentration risk for downstream manufacturers.
- Silver:Lower price points expand addressable demand among younger demographics, though fabrication margins compress against gold alternatives.
- Platinum:Density and hypoallergenic properties anchor bridal positioning in Japanese and North American markets, with South African mining concentration creating supply vulnerability.
Gold commands the deepest working capital deployment; platinum is climbing the fastest among alternative bridal metals.
Distribution Channel:
Channel selection determines customer acquisition economics and post-sale service obligations, with digital penetration reshaping traditional location-based strategies.
- Specialty Stores:Tactile verification and bespoke design consultations justify premium pricing. Chow Tai Fook's mainland China network demonstrates how retail density in Tier-1 and Tier-2 cities captures bridal market share through immediate inventory availability.
- Online Retail:Encrypted virtual consultations and AI-assisted visualization tools collapse geographic friction. Digital-native retailers capture certification-driven buyers through transparent pricing decomposition, particularly in China and India where first-generation middle-class consumers prioritize documented quality metrics.
- Department Stores:Foot traffic dependency and concession fee structures erode margin compared to standalone specialty formats.
- Direct Sales:Private salon distribution anchors ultra-high-net-worth transactions, with Harry Winston's model demonstrating how controlled scarcity sustains pricing power.
Specialty stores retain transaction value leadership; online retail is gaining share fastest among channels.
Customer Type:
Buyer occasion segmentation aligns product development, marketing spend, and inventory planning with distinct psychological purchase triggers and decision timelines.
- Bridal:Ceremonial consumption persists across cultures, with engagement and wedding bands generating predictable seasonal demand. Certification-driven purchasing now dominates selection, with buyers prioritizing GIA or IGI grading reports over brand heritage in final decisions.
- Luxury:Exceptional stone acquisitions and high-jewelry collections sustain margin through controlled scarcity. Cartier's heritage positioning demonstrates how archival design language and limited production runs defend pricing power against commoditization.
- Fashion:Trend-responsive velocity demands rapid inventory turns, with silver and semi-precious materials reducing exposure to precious metal volatility.
- Custom:Generative AI tools and 3D printing convergence enable mass-customized ceremonial pieces, collapsing traditional master craftsman bottlenecks.
Bridal absorbs the bulk of production planning cycles; custom is expanding most quickly through digital design platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India processes the majority of global rough diamonds in Surat while China absorbs the largest share of finished jewelry consumption. Belgium retains cutting mastery for exceptional stones. The United States drives premium bridal demand. Italy anchors luxury fabrication clusters.
India
Surat's diamond cutting and polishing units handle approximately ninety percent of global rough volume, converting Antwerp-sourced stones for export markets. BIS hallmarking mandates for gold purity expand organized retail penetration among trust-sensitive middle-class buyers entering formal channels. Mumbai's Zaveri Bazaar bullion banking infrastructure finances inventory-heavy wedding season procurement cycles for domestic distribution networks.
China
Tier-1 and Tier-2 city middle-class wealth expansion sustains mass-premium bridal and luxury gifting velocity through digital channels. SAMR consumer protection standards enforce disclosure requirements for gemstone treatments and precious metal content in domestic commerce. Shenzhen's manufacturing clusters supply finished jewelry for both domestic consumption and export processing trade through bonded logistics zones.
United States
Engagement ring certification-driven purchasing concentrates demand for GIA-graded diamonds through specialty retail and digital-native channels. FTC Guides for the Jewelry, Precious Metals, and Pewter Industries enforce treatment disclosure and metal content standards across interstate commerce. New York's Diamond District maintains rough and polished stone trading liquidity despite geographic dispersion of fabrication to lower-cost jurisdictions.
Belgium
Antwerp's diamond exchanges and tender houses retain price discovery authority for exceptional rough stones despite midstream cutting migration to India. EU Conflict Minerals Regulation due diligence requirements filter through to downstream jewelry manufacturers sourcing tin, tantalum, tungsten, and gold from conflict-affected regions. The city's banking and logistics infrastructure supports high-value custody chains for ultra-premium transactions.
Italy
Vicenza and Arezzo fabrication clusters supply 18-karat chain assemblies and high-jewelry components to luxury houses for global distribution. EU Green Deal environmental standards and CSRD sustainability disclosure requirements reward compliant producers with preferential European market access. Milan's design studios and trade fair infrastructure anchor stylistic influence for seasonal collections across export markets.
Global Gems and Jewelry Market Vendor Landscape
Top-tier vendors anchor heritage positioning and controlled scarcity, while mid-market chains compete on retail density and certification transparency. The vendor base stratifies across three tiers: ultra-high-net-worth private salons, mass-premium retail networks, and digital-native certification specialists. Two strategic archetypes dominate competitive dynamics: vertically integrated miners-to-retailers and specialist design houses sourcing through pre-qualified supplier bases. Consolidation concentrates among heritage European maisons acquiring regional chains; technology licensing partnerships proliferate among digital-native entrants seeking AI-assisted customization capabilities.
Among heritage European maisons, Cartier and Van Cleef & Arpels exemplify controlled-scarcity archetypes through archival design language and limited production runs. Chow Tai Fook Jewellery Company occupies a position representing mass-premium retail density strategies across mainland China Tier-1 and Tier-2 cities. Harry Winston anchors the ultra-high-net-worth private salon distribution model, demonstrating how exceptional stone sourcing and controlled appointment access sustain pricing power against commoditization pressures in broader bridal segments.
| Leading Market Players |
|---|
| Bvlgari |
| Graff |
| Cartier |
| Boucheron |
| Chopard |
| Van Cleef & Arpels |
| Harry Winston |
| Chow Tai Fook Jewellery Company |
| Tiffany & Co. |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-caps in Surat and Vicenza anchor midstream cutting and luxury fabrication, their concentrated ownership enabling patient capital deployment that resists quarterly margin pressure while sustaining premium pricing discipline through certified quality tiers.
Pricing Analysis
Cost-down pressure on mass-premium bridal tiers accelerates because lab-grown diamond substitution erodes natural stone premiums in sub-one-carat segments. Three-tier pricing structure across heritage luxury, certified mid-market, and unbranded economy levels dominates, with GIA grading reports and BIS hallmarks driving differentiation. Price erosion runs through silver fashion accessories where younger buyers prioritize trend velocity over metal value. Certification-driven purchasers in China and India exhibit lowest price sensitivity, while fashion-forward demographics in Western markets demonstrate highest elasticity.
Supply Chain Analysis
Dual-sourcing mandates from EU luxury houses now require pre-qualified mining cooperatives in Botswana and Canada alongside traditional Antwerp tender channels. Raw material procurement draws from South African platinum, Russian and Canadian rough diamonds, and recycled gold bullion. Single-source vulnerability concentrates in Antwerp's exceptional-stone tender system, where disruption would paralyze ultra-premium inventory pipelines. Distribution runs through bonded logistics zones in Shenzhen and Dubai before final retail placement in specialty stores and encrypted virtual consultations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Upstream control over rough diamond sightholder contracts and downstream retail density in Tier-1 Chinese cities constitute the vertical-integration race defining competitive durability.
For Market Incumbents: Anticipate lab-grown substitution by securing exclusive natural-stone sourcing agreements with De Beers and Alrosa, while deploying AI-assisted customization tools to collapse master craftsman bottlenecks in bespoke bridal. Certification investment in blockchain traceability protocols defends margin position against digital-native entrants exploiting transparency gaps.
For New Entrants and Emerging Players: Begin with Vietnam's underpenetrated bridal market, where rising urban household wealth and limited organized retail presence create first-mover positioning for certified jewelry chains. Direct-to-consumer encrypted virtual consultations capture certification-driven buyers in India and China without legacy store network overhead.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-market digital-native specialists with proven AI customization platforms in Southeast Asian geographies, where working capital constraints force consolidation. Watch Antwerp cutting concentration as inflection indicator—geographic dispersion to Surat alternatives signals structural supply chain reconfiguration opportunity.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Integration | Mine-to-retail custody documentation satisfies EU Conflict Minerals Regulation disclosure without manual audit burden. |
| AI-Assisted Custom Design Platform | Generative tools converge with 3D printing to enable mass-customized ceremonial pieces without craftsman bottlenecks. |
| Regenerative Mining Certification | EU Green Deal-aligned environmental standards reward compliant African producers with preferential European market access. |
| Encrypted Virtual Consultation Infrastructure | High-net-worth purchasers complete exceptional stone acquisitions through secure digital channels, collapsing geographic friction. |
| BIS Hallmarking Compliance Investment | Mandatory purity certification expands addressable demand among trust-sensitive Indian middle-class buyers entering organized retail. |
Methodological Framework
Multi-period observation of rough diamond tender volumes, gold bullion lease rates, and bridal inventory turnover anchored the trend analysis, supplemented by interviews with Surat cutting house operators, Antwerp tender house managers, Italian fabrication cluster technical directors, and Mumbai bullion banking relationship managers. Secondary validation drew from De Beers production reports, BIS hallmarking registration databases, EU Conflict Minerals Regulation disclosure filings, and GIA grading volume statistics. Bottom-up unit economics triangulated against top-down national consumption estimates refined the demand sizing.
Input-output matrices mapped rough stone throughput through cutting, polishing, and setting stages across product-material-channel combinations. Segmentation dimensions modeled included product form factor, karat purity tier, distribution channel type, and buyer occasion archetype. CAGRs derived from trend extrapolation of historical volume and value trajectories, calibrated against consumer wealth expansion projections and regulatory implementation timelines. Forecast inputs incorporated sightholder contract renewal patterns and hallmarking mandate enforcement intensity.
Underlying measurement precision varies by segment; bridal rings and certified diamonds carry tighter precision than fashion silver and uncertified estate jewelry. Forecasts reflect assumptions regarding gold price stability, Antwerp supply continuity, and digital channel penetration rates. Deviation in lab-grown diamond substitution velocity or BIS enforcement rigor would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Jewelry
China Luxury Jewelry Market
Jewelry
Demi-Fine Jewelry Market
Jewelry
3D Printing for Jewelry Market
Jewelry
Jewellery Box Market
Jewelry
Saudi Arabia Luxury Jewelry Market
Jewelry
Pearl Jewelry Market
Jewelry
Imitation Jewelry Market
Jewelry
3D Printed Jewelry Market
Jewelry
Qatar Jewelry Market
Jewelry
Diamond Jewelry Market
Jewelry
China Jewellery Market
Jewelry
Jewelry Repair Market
Jewelry
Mexico Luxury Jewelry Market
Jewelry
Beaded Jewelry Market
Jewelry
Wedding Rings Market
Jewelry
Global Costume Jewelry Market