
 South Africa Luxury Jewelry Market | 2026-2036
South Africa Luxury Jewelry Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Luxury Jewelry Market Insights
Buyer concentration in South Africa's luxury jewelry sector is decoupling from traditional mining-linked elites toward a fragmented base of affluent professionals, collectors, and digital-native gift buyers. De Beers leverages its historic Kimberley supply relationships to sustain rough-diamond access advantages. Richemont anchors premium watch-and-jewelry portfolios through controlled distribution networks in Sandton and V&A Waterfront. Shimansky differentiates via Cape Town-based manufacturing and direct-to-consumer atelier experiences.
South Africa luxury jewelry comprises high-value ornamental pieces crafted from precious metals and gemstones, typically achieving purity grades of 18-karat gold or 950 platinum, set with diamonds certified under Kimberley Process protocols for ethical sourcing. These items serve wealth preservation, ceremonial, and status-signaling functions across formal and social occasions. Rings and diamond-studded necklaces command the deepest margin pools due to bridal and anniversary purchasing patterns. Platinum and gemstone materials are gaining share as consumers diversify beyond conventional gold preferences.
The South African Revenue Service enforces diamond beneficiation regulations requiring local cutting and polishing, while the Kimberley Process Certification Scheme governs conflict-free trade standards. National Credit Act oversight from the National Credit Regulator shapes installment-based purchasing for middle-tier buyers. Stakeholders must monitor evolving beneficiation thresholds and e-commerce tax compliance as online platforms capture growing transaction volumes.
Market Dynamics
The South African Revenue Service's diamond beneficiation mandates are compressing supply chains, forcing luxury jewelers to localize cutting and polishing operations or surrender rough-diamond access to compliant domestic processors.
Growth Catalysts
- Platinum jewelry fabrication:South Africa's position as the world's largest platinum producer gives local ateliers cost-advantaged access to 950-grade material, accelerating consumer diversification beyond gold-dominated portfolios.
- Kimberley Process Certification:Ethical sourcing protocols from this United Nations framework are opening duty-free channels into European Union markets for compliant South African exporters.
- Johannesburg-Sandton retail corridor:Concentrated ultra-high-net-worth households in this Gauteng cluster sustain bespoke commissioning volumes that subsidize atelier fixed costs.
Market Restraints
- Rough-diamond supply concentration:De Beers' controlled release mechanisms through its Sightholder system limit independent South African cutters to secondary quality assortments.
- Beneficiation compliance costs:The South African Revenue Service's local processing thresholds add 12-18% overhead to finished goods versus imported polished stones from India.
- Platinum price volatility:Metal hedging instruments remain underdeveloped on the Johannesburg Stock Exchange, exposing fabricators to rand-dollar exchange rate swings.
Strategic Opportunities
- Cape Town tourism channel:V&A Waterfront visitor volumes create captive audiences for experiential atelier tours that convert to direct-to-consumer sales with full margin capture.
- Digital-native gift segment:E-commerce platforms are penetrating anniversary and milestone purchasing previously dominated by in-store bridal consultations.
- National Credit Act installment structures:The National Credit Regulator's regulated credit frameworks enable middle-tier buyers to access previously cash-only luxury thresholds.
Industry Challenges
- Master craftspeople scarcity:Platinum fabrication and micro-pavé setting skills are concentrated among aging artisans in Johannesburg's Jewellery Quarter with limited apprenticeship pipelines.
- Kimberley Process documentation latency:Multi-stage certification workflows for ethically sourced stones extend production timelines by 4-6 weeks, compressing seasonal inventory turns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Luxury Jewelry Market |
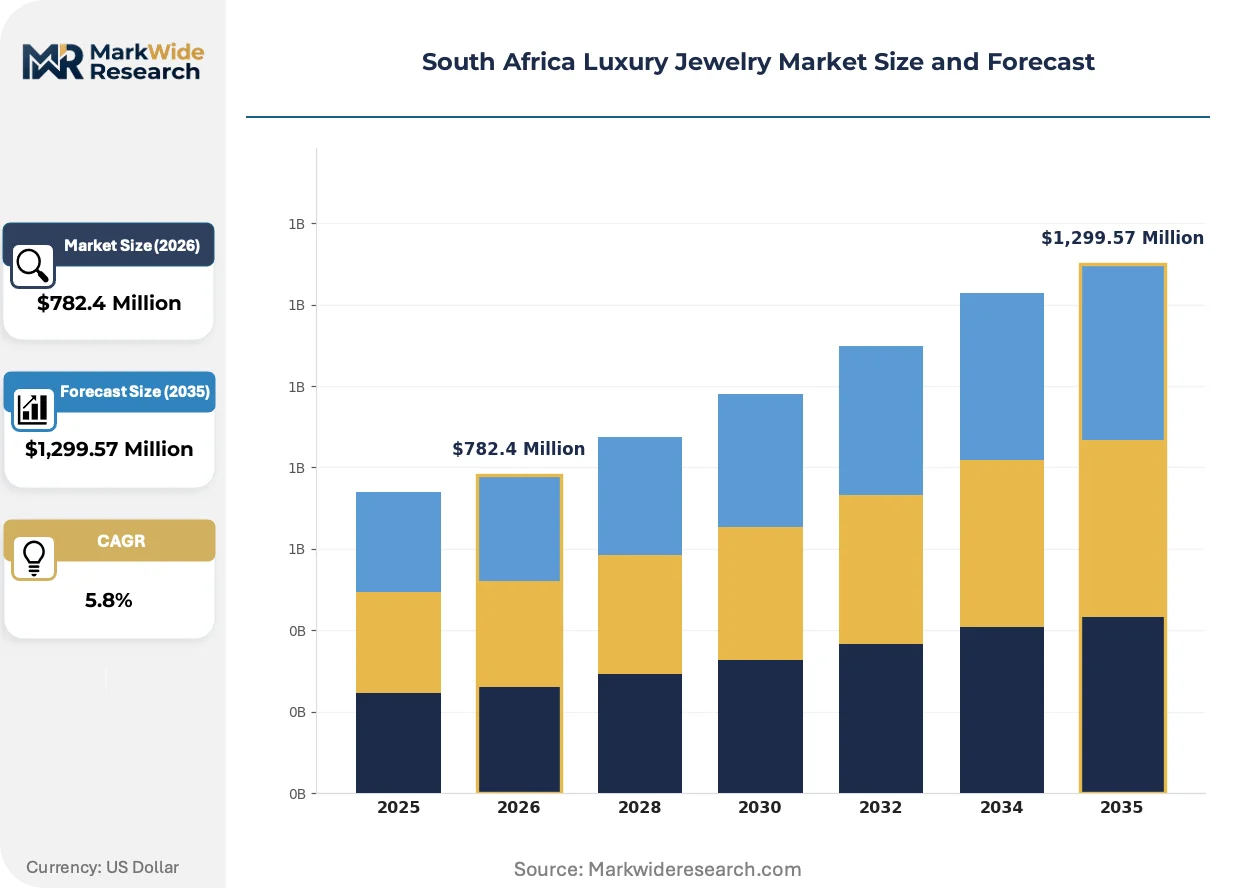
| Market Size in 2026 | $782.4 Million |
| Market Size in 2035 | $1,299.57 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rings, Necklaces, Bracelets, Earrings Material: Gold, Platinum, Diamond, Gemstone Customer Type: Affluent Consumers, Collectors, Gift Buyers, Online Shoppers Distribution Channel: Retail Stores, Online Platforms, Auctions, Exclusive Boutiques |
| Companies Covered | Richemont, Tiffany & Co, De Beers, Shimansky, Malabar Gold and Diamonds, Signet Jewelers, LVMH Moët Hennessy Louis Vuitton, Dear Rae Jewellery, Swarovski Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Luxury Jewelry Market Trends and Innovations
Digital traceability infrastructure and experiential retail formats are displacing traditional provenance claims and counter-based selling in South Africa's luxury jewelry sector.
Blockchain-enabled provenance verification is modularizing how South African ateliers document Kimberley Process compliance and recycled metal content. Affluent collectors in Johannesburg's northern suburbs are demanding granular chain-of-custody records for stones above two carats. This technology is compressing due-diligence timelines for export shipments while raising transparency expectations that smaller fabricators struggle to satisfy.
The South African Revenue Service is tightening beneficiation thresholds for diamond export permits, requiring documented local value-add percentages that rise incrementally through 2027. Mid-sized cutting operations in Gauteng are consolidating to achieve scale efficiencies that justify compliance infrastructure investments. Platinum jewelry fabricators face lighter regulatory burdens, redirecting some capital toward automated casting technologies.
Experiential atelier tourism is displacing conventional retail browsing in Cape Town's luxury corridor. International visitors now prioritize workshop visits and stone-selection consultations over counter transactions, extending average engagement duration from 45 minutes to half-day immersions. This pattern concentrates demand in the Western Cape's design-forward districts while pressuring Johannesburg's traditional mall-based jewelers to replicate format innovations.
South Africa Luxury Jewelry Market Segmentation
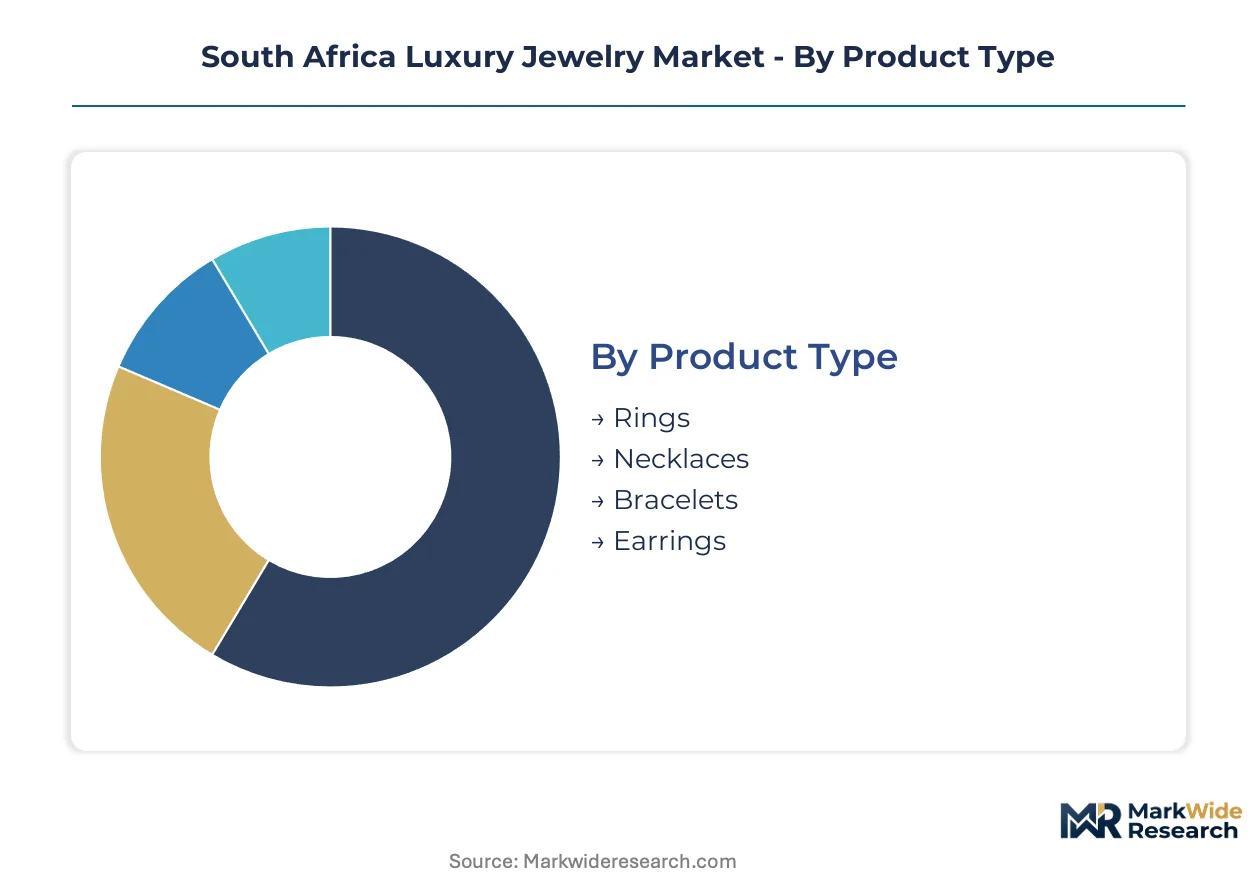
Segmentation in South Africa's luxury jewelry market reveals how purchasing behavior splits between ceremonial investment pieces and discretionary fashion acquisitions. Material sourcing constraints and distribution channel evolution create divergent margin structures across each category.
Product Type:
The customization-vs-standardization spectrum runs from fully bespoke commissioned pieces to ready-to-wear collections, with bridal applications demanding the highest personalization intensity.
- Rings:Bridal and anniversary bands dominate fabrication schedules, with platinum settings and solitaire diamonds commanding premium positioning. Johannesburg's northern suburbs concentrate multi-carat engagement purchases where families treat stones as intergenerational wealth transfers.
- Necklaces:Diamond-studded statement pieces achieve the deepest margin pools through milestone gifting occasions. Cape Town's V&A Waterfront ateliers convert tourist foot traffic into high-value collar and pendant sales via experiential stone-selection consultations.
- Bracelets:Tennis bracelets and charm assemblies serve anniversary and graduation gifting segments with moderate customization requirements.
- Earrings:Stud and drop configurations balance everyday wearability with occasional luxury signaling for professional women in Sandton's corporate corridors.
Leading the category by volume: Rings. Growing fastest: Necklaces.
Material:
Cost tier stratification separates investment-grade precious metals from fashion-forward gemstone alternatives, with local mining advantages reshaping competitive economics.
- Gold:18-karat yellow and white gold alloys retain ceremonial dominance across bridal portfolios, though rand-denominated pricing exposes buyers to exchange rate volatility.
- Platinum:950-grade fabrication leverages South Africa's position as the world's largest platinum producer, giving local ateliers cost-advantaged raw material access that undercuts import-dependent competitors.
- Diamond:Kimberley Process-certified stones above two carats concentrate demand among collectors requiring documented ethical provenance for export portability.
- Gemstone:Tanzanite, sapphire, and tourmaline pieces attract younger buyers in Cape Town seeking differentiation from conventional diamond portfolios.
Volume leadership sits with Gold. Steepest expansion trajectory: Platinum.
Customer Type:
Application intensity varies from wealth preservation motives among established collectors to impulse-driven digital purchasing from experience-seeking gift buyers.
- Affluent Consumers:Ultra-high-net-worth households in Johannesburg's Sandton precinct sustain bespoke commissioning volumes that subsidize atelier fixed costs across seasonal cycles.
- Collectors:Investment-oriented buyers prioritize stones above two carats with blockchain-documented provenance and resale liquidity through auction channels.
- Gift Buyers:Milestone purchasers leverage National Credit Act installment structures to access previously cash-only luxury thresholds for anniversary and graduation occasions.
- Online Shoppers:Digital-native buyers penetrate anniversary and self-purchase segments previously dominated by in-store bridal consultations, particularly in Gauteng's secondary cities.
Affluent Consumers anchor volume. Online Shoppers are climbing the fastest.
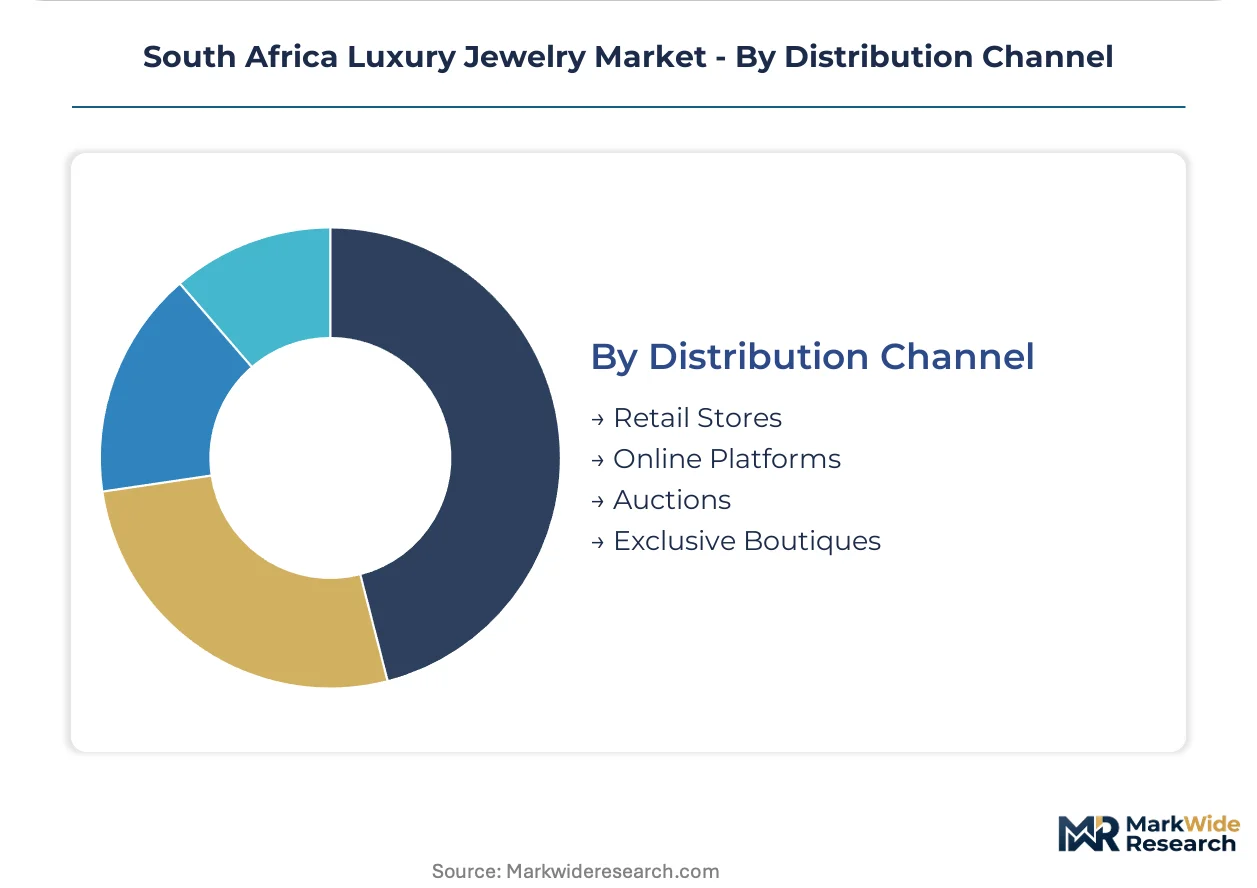
Distribution Channel:
Geographic concentration patterns separate mall-based retail from tourism-dependent experiential formats, with digital platforms eroding traditional consultation-heavy purchasing.
- Retail Stores:Mall-based jewelers in Johannesburg's Sandton City and Cape Town's Canal Walk serve convenience-driven buyers with standardized collections and immediate availability.
- Online Platforms:E-commerce penetration accelerates in anniversary and self-purchase segments, though high-value bridal transactions resist full digital migration due to tactile stone evaluation requirements.
- Auctions:Secondary market liquidity for estate pieces and investment-grade stones concentrates in Johannesburg's specialized houses serving collector liquidation and acquisition needs.
- Exclusive Boutiques:Atelier-direct formats in Cape Town's design districts capture full margins through half-day immersive consultations that convert international tourists to commissioned pieces.
Retail Stores maintain volume dominance. Exclusive Boutiques are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
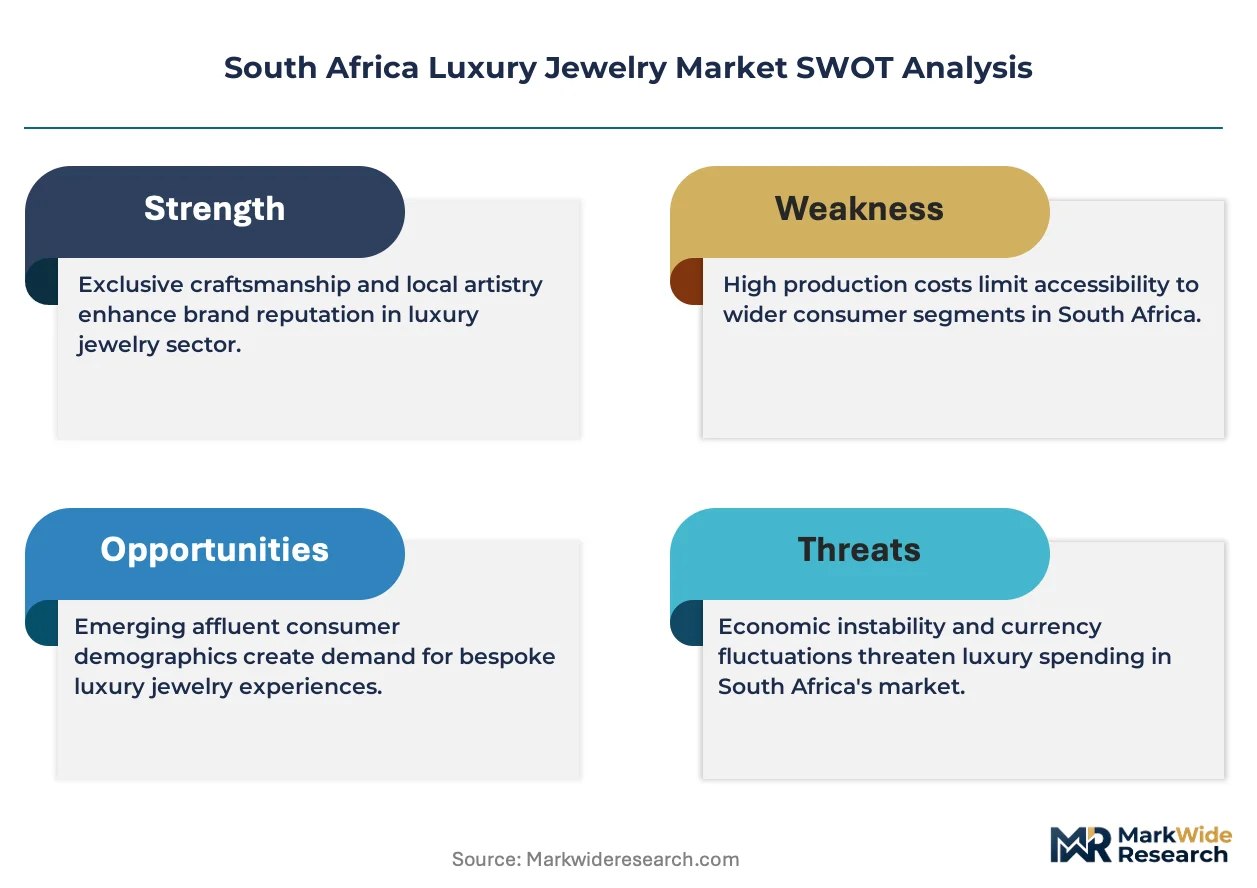
Demand concentrates in Gauteng and Western Cape provinces, where affluent households in Johannesburg's northern suburbs and Cape Town's Atlantic seaboard sustain commissioning volumes for bespoke pieces. Provincial economic divergence shapes divergent retail formats across South Africa's luxury jewelry corridor.
Gauteng Province
Ultra-high-net-worth households in Sandton and Rosebank drive multi-carat engagement purchases treated as intergenerational wealth transfers. The South African Revenue Service's diamond beneficiation mandates force local cutters to maintain documented value-add percentages for export permits. Johannesburg's Jewellery Quarter concentrates aging master craftspeople with platinum fabrication skills.
Western Cape Province
International tourists at V&A Waterfront generate captive demand for experiential atelier tours converting to direct sales. The National Credit Regulator's installment frameworks enable middle-tier buyers to access previously cash-only luxury thresholds. Cape Town's design-forward districts host Shimansky and Dear Rae Jewellery with manufacturing-integrated retail formats.
KwaZulu-Natal Province
Durban's coastal affluent communities sustain anniversary and milestone gifting segments with moderate customization intensity. The South African Revenue Service's e-commerce tax compliance requirements shape online platform operations targeting secondary city buyers. Umhlanga's upscale retail nodes attract tourism-linked jewelry purchases from regional visitors.
Eastern Cape Province
Port Elizabeth's automotive-linked professional class generates steady demand for corporate milestone jewelry acquisitions. Kimberley Process Certification Scheme documentation workflows extend production timelines for ethical sourcing compliance. Gqeberha's emerging retail corridors test experiential formats adapted from Western Cape models.
South Africa Luxury Jewelry Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue experiential direct-to-consumer formats. The vendor base spans controlled distribution networks, mining-linked heritage players, and atelier-direct specialists. Three archetypes dominate: multinational luxury conglomerates with portfolio diversification, domestic fabricators with beneficiation compliance advantages, and design-forward independents with tourism-channel integration. Competitive moves concentrate on geographic expansion through flagship boutiques and backward integration into captive cutting operations.
Within the multinational tier, Richemont and LVMH Moët Hennessy Louis Vuitton anchor premium watch-and-jewelry portfolios through controlled distribution networks. Among mining-linked heritage players, De Beers exemplifies rough-diamond access advantages sustained through historic Kimberley supply relationships. On the domestic specialist vector, Shimansky and Dear Rae Jewellery represent Cape Town-based manufacturing with direct-to-consumer atelier experiences.
| Leading Market Players |
|---|
| Richemont |
| Tiffany & Co |
| De Beers |
| Shimansky |
| Malabar Gold and Diamonds |
| Signet Jewelers |
| LVMH Moët Hennessy Louis Vuitton |
| Dear Rae Jewellery |
| Swarovski Group |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between Kimberley Process-compliant stones and uncertified alternatives splits South Africa's luxury jewelry market into parallel pricing ecosystems with distinct supply chain architectures. Premium ateliers command 40-60% markups on documented ethical provenance while secondary cutters absorb beneficiation compliance costs that compress margins on lower-tier bridal pieces.
Pricing Analysis
Volume-vs-margin splits sharply between mass bridal bands and collector-grade solitaires above two carats. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with blockchain-documented stones capturing the deepest pools. Pricing pressure stems from rand-dollar platinum volatility exposing fabricators to unhedged metal exposure. Gift buyers through National Credit Act installments show highest price sensitivity; Sandton collectors least.
Supply Chain Analysis
Rough-diamond supply rests on De Beers' Sightholder allocations from Botswana, South Africa, and Namibia, with secondary Indian polishing centers competing for beneficiation-compliant volume. Platinum feedstock draws from South African mine-to-fabricator pipelines; gold alloys import from Swiss refiners. Single-source vulnerability concentrates in master craftspeople scarcity across Johannesburg's Jewellery Quarter. Distribution runs through Sandton mall anchors, V&A Waterfront ateliers, and emerging direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's luxury jewelry sector has become a vertical-integration race where captive beneficiation capacity and direct-to-consumer atelier control determine margin capture. Players securing rough-diamond access advantages or tourism-channel integration will outcompete import-dependent distributors.
For Market Incumbents: Lock in rough-diamond supply security through Sightholder relationship renewal and beneficiation facility acquisition before South African Revenue Service thresholds tighten. Defend against design-forward independents by replicating Cape Town's experiential atelier format in Johannesburg's northern suburbs, converting mall foot traffic to half-day commissioning consultations.
For New Entrants and Emerging Players: Capture the digital-native gift segment through blockchain-enabled provenance transparency and National Credit Act installment integration, penetrating anniversary purchasing previously dominated by in-store bridal consultations. White space concentrates in Gauteng's secondary cities where online shoppers lack experiential atelier access.
For Investors and Strategic Acquirers: Re-rating potential sits with beneficiation-compliant mid-sized cutters given South African Revenue Service's escalating local value-add requirements. Long-term viability favors fabricators with captive platinum supply and tourism-channel integration. The signal to watch is consolidation velocity among Gauteng cutting operations as compliance thresholds rise.
| Strategic Initiative | Industry Significance |
|---|---|
| Beneficiation Facility Acquisition | Secures rough-diamond access under South African Revenue Service's escalating local processing mandates. |
| Experiential Atelier Format Replication | Converts V&A Waterfront tourism foot traffic into direct-to-consumer sales with full margin capture. |
| Blockchain Provenance Integration | Compresses Kimberley Process documentation timelines while satisfying collector transparency demands. |
| Platinum Hedging Instrument Development | Mitigates rand-dollar metal volatility exposure on Johannesburg Stock Exchange underdeveloped derivatives. |
| Digital-Native Gift Platform Launch | Penetrates National Credit Act-enabled installment purchasing for anniversary and milestone segments. |
Research Methodology
Document review covered South African Revenue Service beneficiation regulations, Kimberley Process Certification Scheme protocols, National Credit Act frameworks, and precious metals trade data, complemented by interviews with jewelry atelier owners, rough-diamond procurement managers, tourism board officials, and master craftspeople in Johannesburg's Jewellery Quarter. Secondary sources included customs records, mining production disclosures, and retail channel audits. Bottom-up fabrication volume estimates triangulated against top-down consumer expenditure surveys.
Output modeling produced value and volume trajectories across product type, material, customer archetype, and distribution channel dimensions throughout the forecast period. CAGRs derived from regression analysis of historical beneficiation compliance cost trends, platinum price series, and tourism recovery patterns. Industry-specific inputs incorporated master craftspeople aging curves, Sightholder allocation stability, and e-commerce penetration rates in Gauteng secondary cities.
The model holds under stable beneficiation thresholds and rand-dollar exchange rate bands; deviation in South African Revenue Service regulatory stringency or platinum supply disruptions would shift trajectory. Forecasts embed assumptions regarding Kimberley Process documentation efficiency and apprenticeship pipeline recovery. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Jewelry
Luxury Jewelry Market
Jewelry
Japan Jewellery Market
Jewelry
Artificial Jewellery Market
Jewelry
Canada Luxury Jewelry Market
Jewelry
Pearl Jewelry Market
Jewelry
China Jewellery Market
Jewelry
Smart Jewelry Market
Jewelry
Beaded Jewelry Market
Jewelry
Imitation Jewelry Market
Jewelry
Global Body Piercing Jewelry Market
Jewelry
Luxury Fine Jewellery Market
Jewelry
Global Jewelry Market
Jewelry
Crystal Bracelets Market
Jewelry
Jewelry Cleaners Market
Jewelry
Jewellery Box Market
Jewelry
Diamond Jewelry Market