
 Custom Dog Tags Market | 2026-2036
Custom Dog Tags Market Size, Share, and Industry Trends Forecast 2026-2036
Custom Dog Tags Market Analytics
Multi-source sourcing for metal blanks and engraving equipment is expanding as custom dog tag producers diversify away from single domestic suppliers. DogTagsInc leverages in-house laser engraving capabilities to control turnaround times and design fidelity. GoTags sustains competitive positioning through broad material portfolios spanning stainless steel, aluminum, and brass substrates. Silver Paw Pet Tags anchors its operations in premium finishing techniques that command higher price points in direct-to-consumer channels.
Custom dog tags are identification accessories manufactured from stamped or cast metal substrates, typically incorporating engraved or printed owner contact information, medical alerts, or decorative motifs, with dimensions ranging from one to two inches in standard military-style formats. Stainless steel dominates material selection due to corrosion resistance and engraving clarity, while aluminum competes on weight and cost efficiency in high-volume segments. The personalization type dimension splits between engraved products, which retain premium positioning for durability, and printed alternatives that serve price-sensitive buyers through faster production cycles. Online retail channels are capturing disproportionate growth by eliminating geographic constraints and enabling real-time design customization interfaces.
The Consumer Product Safety Commission oversees material safety standards for pet accessories sold in the United States, while the Federal Trade Commission monitors advertising claims related to durability and engraving permanence. Compliance with California Proposition 65 labeling requirements for metal alloys shapes sourcing decisions and product liability exposure for manufacturers. Stakeholders must monitor evolving state-level microplastics regulations that could restrict certain coating applications on plastic tag variants and evaluate supply chain redundancy strategies before raw material cost volatility intensifies.
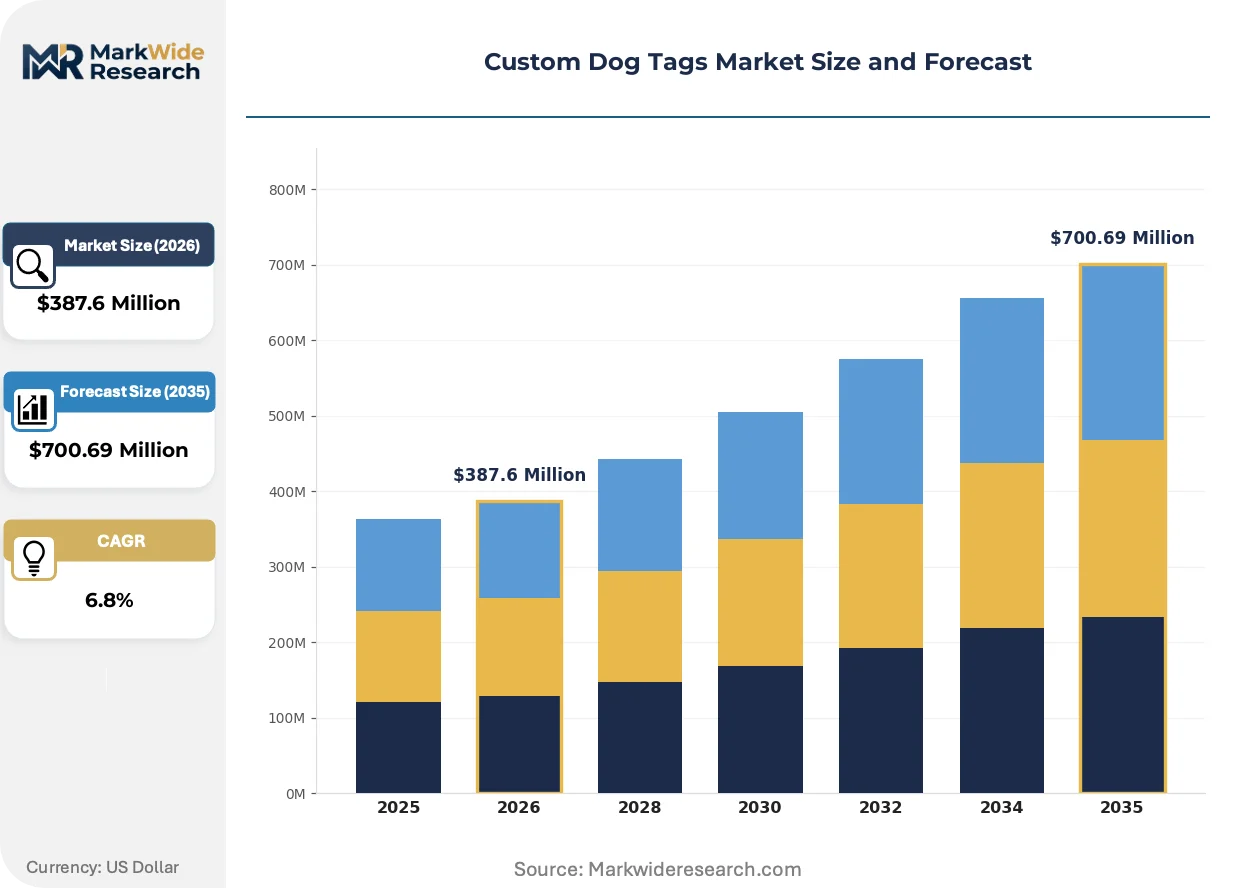
Market Dynamics
Pet humanization trends among millennial and Gen Z households are fundamentally restructuring demand for identification accessories, shifting purchasing decisions from functional utility toward emotional expression and design personalization.
Growth Catalysts
- Laser Engraving Technology:Fiber laser systems now deliver sub-millimeter precision on stainless steel substrates, enabling real-time customization without tooling changeover delays.
- California Proposition 65 Compliance:Manufacturers investing in lead-free alloy sourcing capture preferential placement in premium retail channels serving liability-conscious buyers.
- Direct-to-Consumer E-Commerce:Shopify and Amazon storefronts eliminate geographic constraints for specialty producers, compressing customer acquisition costs versus wholesale distribution.
Market Restraints
- Aluminum Price Volatility:London Metal Exchange aluminum contract swings constrain margin predictability for volume-oriented producers serving price-sensitive segments.
- Single-Source Engraving Equipment:Dependence on Chinese-manufactured fiber laser sources creates supply vulnerability amid tariff uncertainty and shipping disruptions.
- Coating Durability Limitations:Anodized color finishes on aluminum substrates exhibit faster wear in marine environments, restricting warranty terms and repeat purchase cycles.
Strategic Opportunities
- Medical Alert Applications:Expansion into veterinary-prescribed identification for diabetic and epileptic pets opens reimbursement-adjacent revenue streams through veterinary clinic partnerships.
- EU Green Deal Alignment:Recycled stainless steel certification and carbon footprint labeling command shelf space differentiation in German and French specialty retail.
- Augmented Reality Preview Tools:WebAR integration allows buyers to visualize tag scale and font legibility on their specific pet breed before purchase completion.
Industry Challenges
- Laser Operator Certification Delays:Fiber laser safety training requirements extend onboarding timelines for production scaling, constraining peak season capacity expansion.
- Legacy ERP Integration Friction:Real-time design-to-production workflows require middleware development to connect consumer-facing configurators with shop floor engraving controllers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Custom Dog Tags Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Stainless Steel, Aluminum, Brass, Plastic Personalization Type: Engraved, Printed, Colorful, Embossed Size: Small, Medium, Large, Extra Large Distribution Channel: Online Retail, Pet Stores, Custom Shops, Wholesale |
| Companies Covered | Dog Tuff, Puplife, DogTagsInc, Silver Paw Pet Tags, Love Your Pets, Dog Tag Art, Rockstar Puppy Boutique, GoTags, dogIDs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Custom Dog Tags Market Evolving Landscape
Digital fabrication workflows and regulatory transparency mandates are compressing traditional manufacturing timelines while elevating material provenance as a purchase determinant. Three developments warrant particular attention.
Fiber laser engraving is overtaking mechanical stamping as the dominant personalization method. Veterinary clinics and premium pet retailers specify laser-etched products for their superior legibility retention after years of abrasion exposure. The technology is overtaking legacy equipment investment cycles, forcing mid-volume producers to accelerate capital replacement schedules or surrender high-margin custom orders to digitally equipped competitors.
REACH substance restrictions on nickel release rates are reshaping alloy specifications for European-bound shipments. Manufacturers now segregate production lines between 316L surgical-grade stainless steel for EU markets and standard 304 grades for domestic US distribution. German distributors are demanding batch-level material test certificates, adding documentation overhead that smaller producers struggle to automate.
Subscription-based tag replacement programs are displacing one-time purchase patterns among urban pet owners. Chewy and Amazon subscription tiers offer annual engraving updates for relocated owners or redesigned medical information, capturing lifetime value through recurring revenue rather than single transactions. This model concentrates adoption in coastal metropolitan markets where pet mobility and veterinary service density support frequent information changes.
Custom Dog Tags Market Segmentation
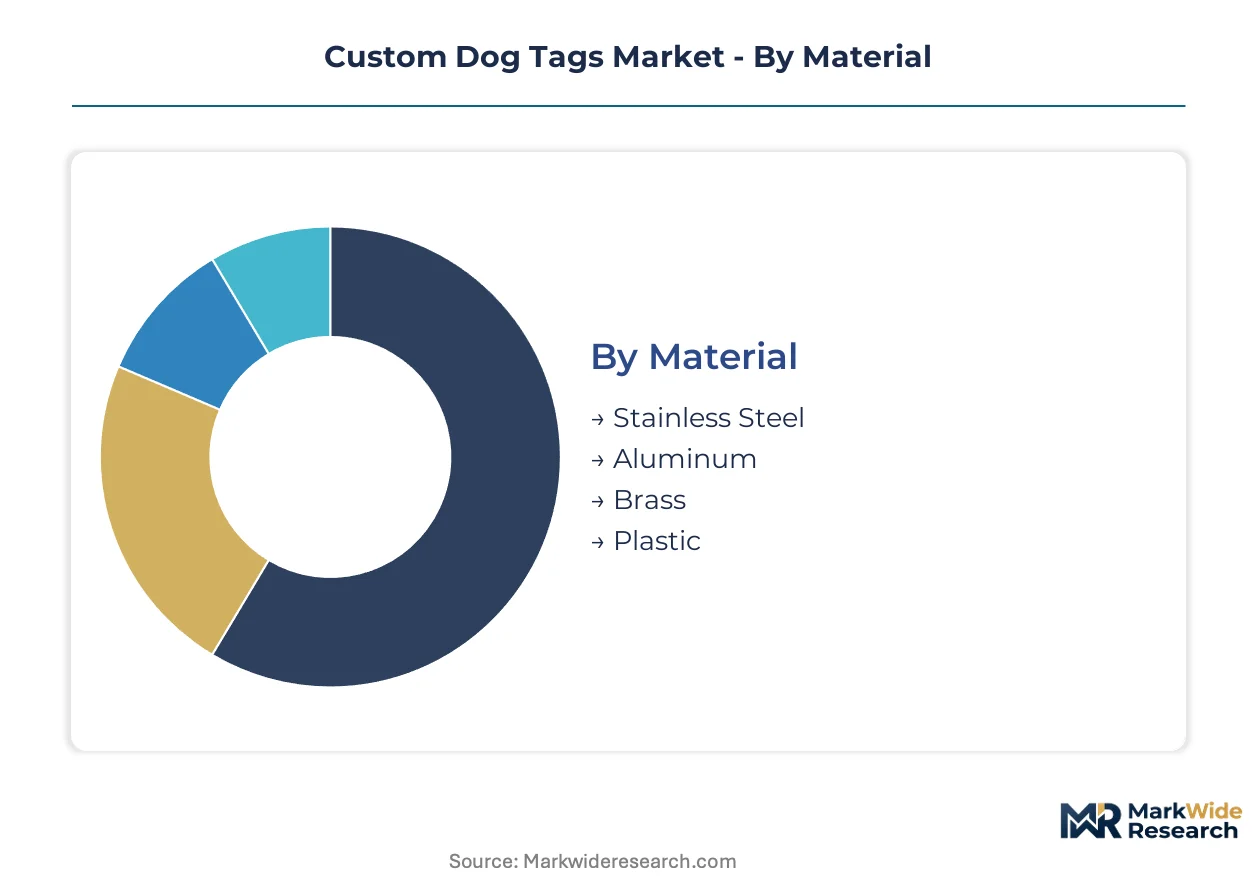
Material selection and personalization technology define competitive positioning in custom dog tags. Segmentation reveals where capital deployment concentrates and which production configurations command margin premiums.
Material:
Fiber laser engraving systems require the highest upfront investment for stainless steel processing, while aluminum stamping equipment operates at lower capital thresholds.
- Stainless Steel:316L and 304 grades deliver superior corrosion resistance and engraving clarity under fiber laser systems. Demand clusters in coastal United States households and veterinary clinic procurement channels where durability justifies price premiums. REACH nickel release compliance for European shipments adds certification overhead that smaller producers struggle to absorb.
- Aluminum:Lightweight substrates reduce shipping costs and enable anodized color finishes for decorative applications. Price-sensitive buyers in high-volume segments favor aluminum for tag replacement programs and promotional giveaways. London Metal Exchange volatility constrains margin predictability for producers serving this segment.
- Brass:Antique aesthetic appeal drives demand in premium gift markets and heritage-style military tag reproductions.
- Plastic:Lowest material cost enables mass-market penetration and temporary identification for shelter adoption programs.
Most installed capacity flows through Stainless Steel. Expansion is steepest in Aluminum.
Personalization Type:
Production cycle economics separate segments by throughput speed and equipment utilization rates.
- Engraved:Fiber laser and rotary engraving systems deliver permanent marking with sub-millimeter precision on metal substrates. Premium pet retailers and veterinary clinics specify engraved products for legibility retention after years of abrasion exposure. Capital replacement cycles for legacy mechanical equipment are accelerating as competitors invest in digital fabrication workflows.
- Printed:UV-cured inkjet systems enable full-color photographic reproduction and rapid turnaround without tooling setup. E-commerce configurators leverage printed personalization for real-time design previews and same-day fulfillment. Ink adhesion durability on metal surfaces limits warranty terms compared to engraved alternatives.
- Colorful:Anodized, powder-coated, and enamel-filled finishes command attention in direct-to-consumer visual merchandising.
- Embossed:Raised-character stamping retains niche demand for military-style authenticity and tactile identification.
Revenue concentration favors Engraved for premium positioning. Printed gains share fastest in subscription-based replacement programs.
Size:
Substrate yield optimization and shipping dimensional weight pricing create divergent margin structures across size categories.
- Small:Compact formats for cats and toy dog breeds maximize material utilization per sheet but require precision fixturing for accurate engraving placement. Urban apartment dwellers in dense metropolitan markets favor discreet identification that does not snag on furniture or clothing.
- Medium:Standard one-inch military-style dimensions dominate volume production and inventory stocking decisions.
- Large:Enhanced visibility for working breeds and service animals drives procurement from training facilities and professional handlers.
- Extra Large:Specialty formats for livestock guardian breeds and decorative statement pieces occupy limited production capacity.
Medium size captures the majority of production runs. Small formats show the steepest expansion trajectory in urban coastal markets.
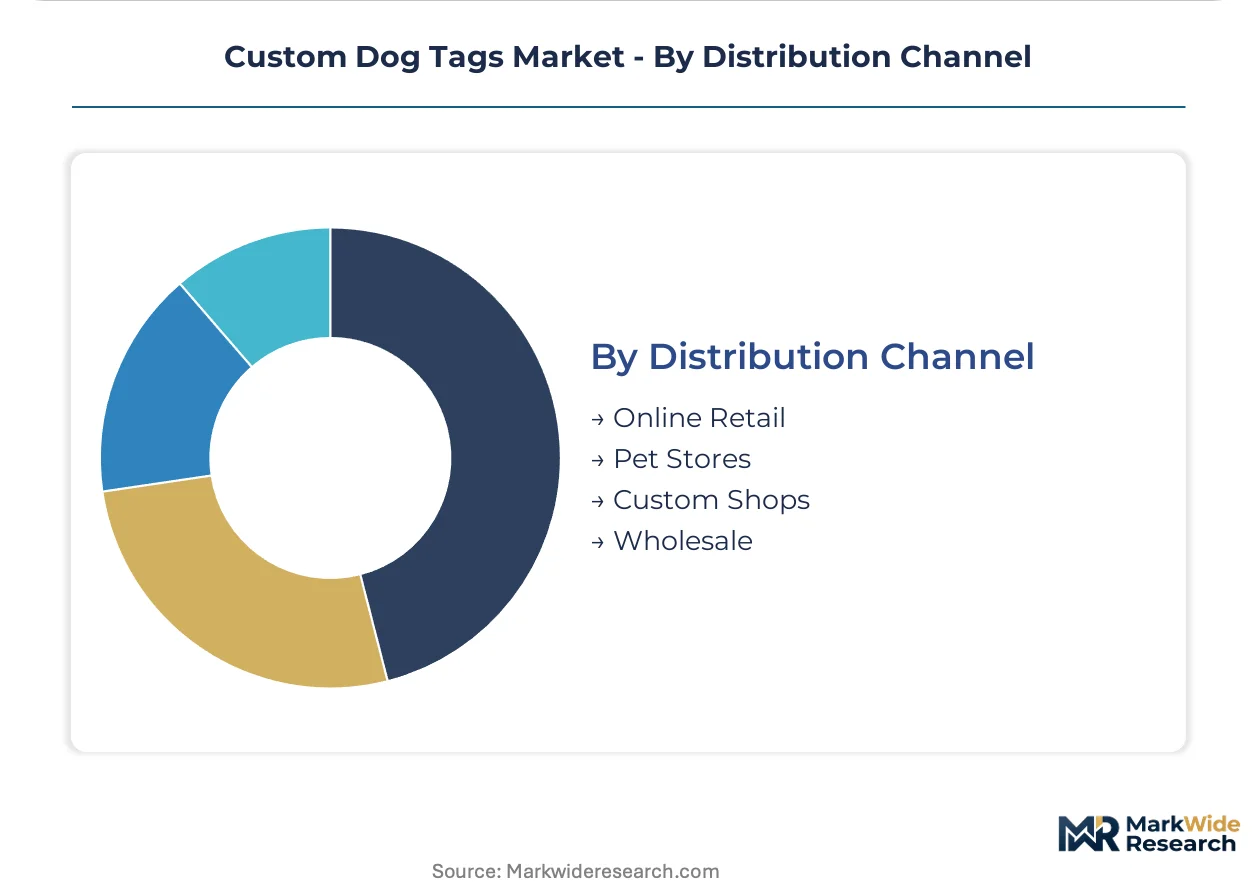
Distribution Channel:
Customer acquisition cost and fulfillment infrastructure requirements segment producers by scale and geographic reach.
- Online Retail:Shopify and Amazon storefronts eliminate geographic constraints and enable real-time design customization interfaces. Direct-to-consumer economics compress customer acquisition costs versus wholesale distribution while capturing lifetime value through subscription replacement programs. Chewy and Amazon subscription tiers concentrate adoption in metropolitan markets with high pet mobility.
- Pet Stores:Physical retail placement requires slotting fees and inventory consignment arrangements that strain working capital for smaller producers. Premium finishing techniques command shelf space differentiation in specialty chains serving affluent suburban households.
- Custom Shops:Local engraving services and boutique pet boutiques capture impulse purchases and same-day fulfillment demand.
- Wholesale:Volume contracts with veterinary distributors and shelter networks prioritize cost efficiency over customization depth.
Order volume concentrates in Online Retail. Custom Shops expand most quickly in destination tourism markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as manufacturers migrate engraving operations toward jurisdictions with lower compliance burdens for metal alloy sourcing and laser equipment safety certification. Cost-of-compliance gaps between North American and Asian fabrication centers now exceed fifteen percentage points on landed cost calculations.
United States
Millennial pet humanization drives premium personalization demand across coastal metropolitan markets. The Consumer Product Safety Commission enforces material safety standards for pet accessories sold through interstate commerce. Los Angeles and New York City clusters host direct-to-consumer engraving studios that compress fulfillment windows to under forty-eight hours.
Germany
REACH substance restrictions on nickel release rates mandate surgical-grade 316L stainless steel for all European-bound shipments. The EU Green Deal incentivizes recycled stainless steel certification through carbon footprint labeling requirements. Bavarian fabrication centers specialize in batch-level material test documentation for distributor compliance.
China
Domestic e-commerce platforms accelerate fiber laser engraving equipment adoption for export-oriented contract manufacturers. GB standards govern laser safety certification for industrial engraving systems. Shenzhen and Dongguan industrial corridors concentrate equipment assembly capacity serving North American private label clients.
United Kingdom
Post-Brexit regulatory divergence creates dual compliance tracks for EU and domestic market shipments. The Office for Product Safety and Standards oversees pet accessory material safety enforcement. London and Manchester urban markets favor subscription-based tag replacement programs among high-mobility pet owners.
Canada
Cross-border e-commerce integration with US platforms expands market access for domestic engraving specialists. Health Canada regulates metal alloy safety in pet accessories through consumer product safety legislation. Toronto and Vancouver metropolitan areas concentrate premium pet retail placement for imported stainless steel products.
Custom Dog Tags Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue subscription-based replacement programs and veterinary clinic partnerships. The vendor base distributes across three operational scales: in-house laser engraving specialists, broad-material portfolio generalists, and premium finishing boutiques. Three strategic archetypes dominate: technology-integrated direct-to-consumer operators, wholesale veterinary distributors, and artisan craft-positioned specialty retailers. Capacity expansion and strategic partnerships represent the dominant competitive moves, with producers securing redundant fiber laser equipment sources and aligning with Chewy and Amazon subscription infrastructure.
Within the technology-integrated tier, DogTagsInc and GoTags exemplify divergent capital deployment strategies. DogTagsInc represents the in-house fabrication archetype, while GoTags occupies a position emphasizing material breadth across stainless steel, aluminum, and brass substrates. Silver Paw Pet Tags anchors the premium finishing segment, commanding price point differentiation through direct-to-consumer channels.
| Leading Market Players |
|---|
| Dog Tuff |
| Puplife |
| DogTagsInc |
| Silver Paw Pet Tags |
| Love Your Pets |
| Dog Tag Art |
| Rockstar Puppy Boutique |
| GoTags |
| dogIDs |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between REACH-compliant 316L surgical steel and standard 304 grades splits pricing power across Atlantic supply corridors. Buyers in Germany and France absorb documentation premiums for batch-level test certificates while domestic US procurement tolerates lower-grade substrates at compressed price points.
Pricing Analysis
Distributor margin layers compress as direct-to-consumer Shopify and Amazon storefronts disintermediate traditional wholesale channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by personalization technology—fiber laser engraving commands premium positioning against UV-cured inkjet alternatives. Price differentiation stems from alloy certification grade and engraving durability warranties. Cost compression in aluminum segments is intensifying because London Metal Exchange volatility constrains margin predictability. Shelter networks and high-volume promotional buyers exhibit greatest price sensitivity; veterinary clinics and premium pet retailers demonstrate least.
Supply Chain Analysis
Fiber laser engraving equipment supply rests on Chinese-manufactured sources concentrated in Shenzhen and Dongguan industrial corridors. Raw material flows draw from stainless steel mills in China, Germany, and the United States; aluminum sheet from Canadian and Australian smelters; and specialty alloys from Japanese and South Korean refiners. Single-source vulnerability for fiber laser systems creates supply risk amid tariff uncertainty and shipping disruptions. Distribution runs through direct-to-consumer e-commerce platforms, pet store retail networks, and veterinary distributor wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities concentrate where REACH nickel release compliance costs exceed fifteen percentage points against domestic US production economics. Manufacturers can capture margin expansion by segregating production lines between regulatory jurisdictions.
For Market Incumbents: Deepen redundant fiber laser equipment sourcing to mitigate single-source exposure from Chinese manufacturers. Secure captive supply of lead-free alloy substrates to defend premium channel positioning against emerging entrants exploiting California Proposition 65 liability gaps. Certification investment in recycled stainless steel documentation opens EU Green Deal-aligned shelf space differentiation. For New Entrants and Emerging Players: Subscription-based tag replacement programs among high-mobility urban pet owners represent an underserved buyer archetype with concentrated lifetime value potential. Veterinary-prescribed medical alert applications offer reimbursement-adjacent revenue streams through clinic partnership programs. Direct-to-consumer WebAR configurators enable lowest-friction go-to-market entry against legacy wholesale-dependent incumbents. For Investors and Strategic Acquirers: Consolidation pressure builds where fiber laser safety certification delays constrain peak season capacity scaling for mid-volume producers. Long-term viability favors vertically integrated engraving specialists with redundant equipment sources and direct Amazon subscription infrastructure alignment. Watch fiber laser equipment tariff classification rulings as inflection indicators for supply chain cost restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Sourcing | Lead-free certification secures preferential placement in California and EU retail channels. |
| Fiber Laser Equipment Redundancy | Dual-source procurement mitigates tariff exposure from Shenzhen-dependent supply chains. |
| Veterinary Clinic Partnership Program | Medical alert tag prescriptions open reimbursement-adjacent revenue streams through clinic networks. |
| Subscription Replacement Infrastructure | Chewy and Amazon tier integration captures recurring lifetime value from metropolitan pet owners. |
| REACH Compliance Documentation Automation | Batch-level test certificate digitization reduces overhead for German and French distributor requirements. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged laser engraving equipment manufacturers, pet retailer category buyers, veterinary clinic procurement managers, and direct-to-consumer brand operators. Secondary validation drew from Consumer Product Safety Commission enforcement records, Federal Trade Commission advertising claim monitoring, London Metal Exchange aluminum contract data, and EU REACH substance restriction updates. Bottom-up production capacity assessments and top-down retail channel revenue estimates were triangulated against customs and trade flow records.
Segment-weighting approaches distributed value and volume projections across material grade, personalization technology, size format, and distribution channel dimensions throughout the forecast period. CAGRs were derived from installed equipment capacity trajectories, e-commerce penetration curves, and pet humanization spending elasticity models. Veterinary clinic procurement patterns and subscription program adoption rates served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; online retail and fiber laser engraved categories carry tighter precision than custom shop and printed alternatives. Forecasts reflect assumptions regarding laser equipment import tariff stability, alloy price volatility bands, and state-level microplastics regulatory evolution. Raw material cost spikes, shipping disruption recurrence, or REACH nickel release threshold revisions could necessitate forecast revision. A small set of tariff classification rulings, veterinary reimbursement policy shifts, and fiber laser safety certification backlogs warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fashion & Accessories
Europe Fashion Accessories Market
Fashion & Accessories
Sustainable Fashion Market
Fashion & Accessories
Hair Accessories Market
Fashion & Accessories
Global Handbags Market
Fashion & Accessories
Selfie Accessories Market
Fashion & Accessories
North America Fashion Accessories Market
Fashion & Accessories
Personal Accessories Market
Fashion & Accessories
Decorative Accessories Market
Fashion & Accessories
North America Lingerie Market
Fashion & Accessories
Fashion Accessories Market
Fashion & Accessories
North America Handbag Market
Fashion & Accessories
Cufflink Market
Fashion & Accessories
Hair Scrunchies Market
Fashion & Accessories
Middle East and Africa Leather Goods Market
Fashion & Accessories
South America Handbags Market
Fashion & Accessories
Asia Pacific Fashion Accessories Market