
 Fashion Accessories Market | 2026-2036
Fashion Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Fashion Accessories Market Analysis
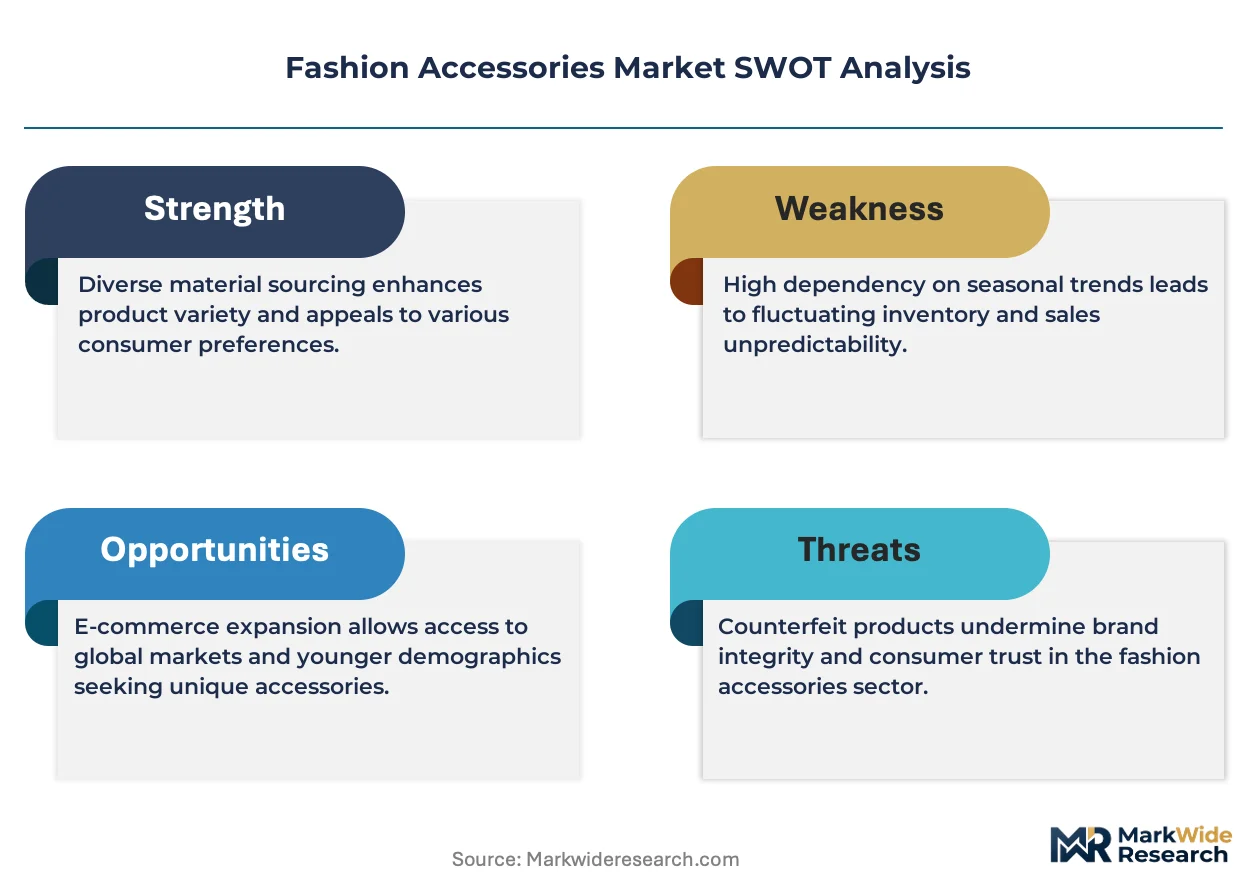
The EU Green Deal is repositioning how European fashion houses source raw materials, forcing traceability investments across leather tanning and precious metal extraction. LVMH Moët Hennessy Louis Vuitton SE anchors its competitive edge through captive tanneries and in-house goldsmith ateliers. Kering S.A. differentiates via open-source environmental profit and loss accounting that extends to its entire supplier network. Richemont SA dominates the hard luxury watch and jewelry segment through vertically integrated manufacturing in Switzerland.
Fashion accessories encompass wearable items including jewelry, handbags, belts, and scarves, typically manufactured from leather, metal, fabric, or synthetic substrates through processes such as cut-and-sew assembly, die-casting, weaving, or electroplating, serving primarily aesthetic, status-signaling, and functional storage purposes for consumers. Handbags generate the deepest margin pools due to leather scarcity and artisan labor intensity, while jewelry benefits from metal price appreciation and gem certification premiums. The online distribution channel is capturing the fastest volume growth as direct-to-consumer platforms bypass wholesale markups and capture first-party customer data.
REACH governs chemical restrictions across metal plating and synthetic dyes in Europe, while the EU Green Deal mandates supply chain due diligence that affects leather sourcing from Brazilian ranchlands and African mining operations. The US Federal Trade Commission enforces jewelry labeling standards that dictate precious metal purity disclosures and gemstone treatment notifications. Stakeholders must monitor tightening traceability mandates that will determine market access for unverified supply chains.
Market Dynamics
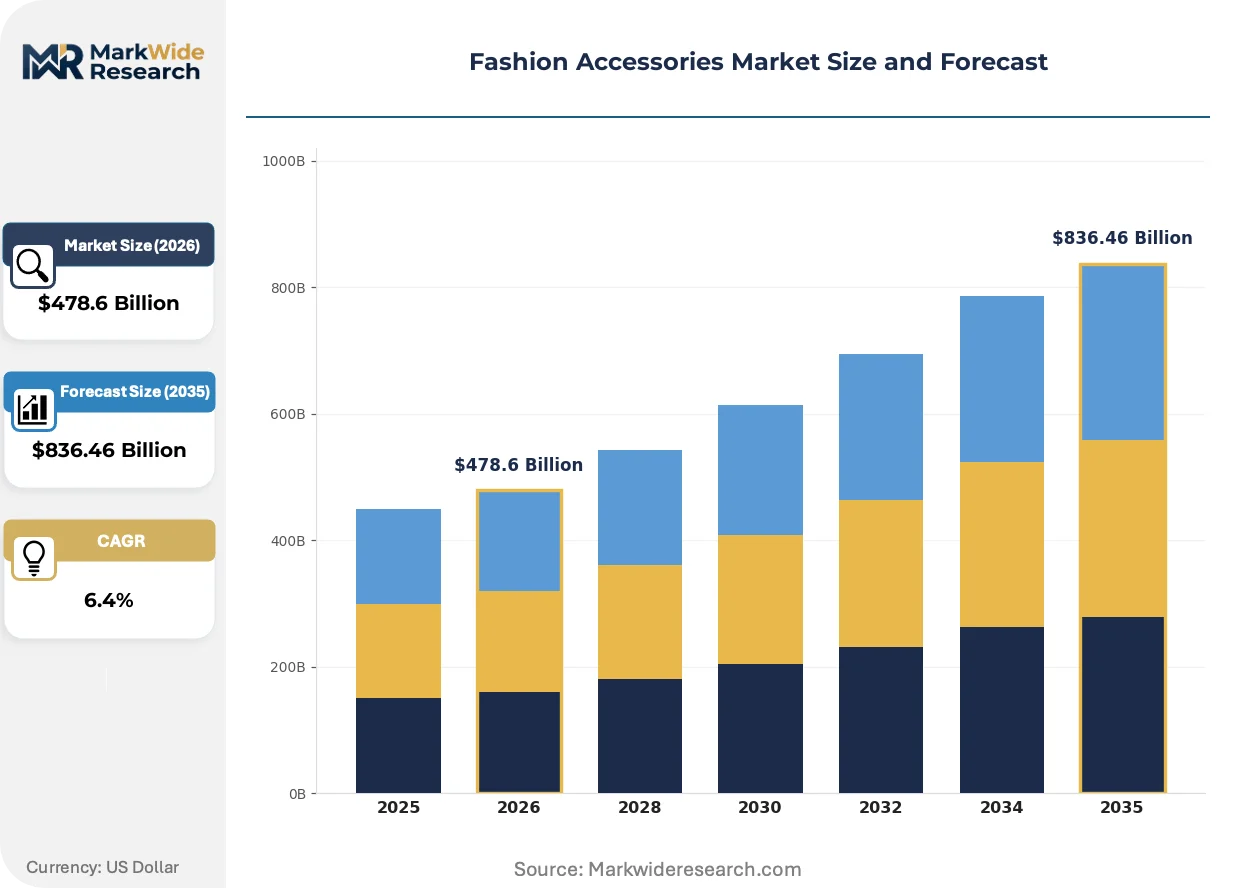
EU Green Deal due diligence mandates are forcing fashion houses to rebuild leather and precious metal supply chains around traceability infrastructure, compressing margins for non-compliant suppliers while rewarding vertically integrated producers.
Growth Catalysts
- EU Green Deal supply chain mandates:European regulators now require documented provenance for leather sourced from Brazilian ranchlands and metals from African mining operations, creating competitive advantage for houses with captive tanneries.
- Millennial HNW jewelry demand:High-net-worth individuals under age forty are driving hard luxury consumption in China, prioritizing gem certification and artisan provenance over traditional retail channels.
- Direct-to-consumer platform expansion:Online distribution is capturing volume growth as brands bypass wholesale markups and build first-party data assets for personalization.
Market Restraints
- Artisan labor scarcity:Handbag manufacturing depends on skilled leatherworkers concentrated in Italian and French ateliers, where generational talent pipelines are thinning.
- Precious metal price volatility:Gold and platinum input costs fluctuate with central bank reserve policies and mining output disruptions in South Africa and Russia.
- REACH chemical compliance friction:ECHA restrictions on electroplating baths and synthetic dyes force reformulation cycles that extend product development timelines by twelve to eighteen months.
Strategic Opportunities
- Domestic Chinese luxury consumption:Trade volatility is accelerating repatriation of spending by Chinese nationals, favoring brands with mainland retail and digital infrastructure.
- Open-source environmental accounting:Kering's profit-and-loss methodology offers a template for supplier network transparency that regulators in France and Italy are beginning to reference.
- Blockchain gem certification:Distributed ledger technology is converging with spectroscopic analysis to create tamper-proof provenance records for colored stones and diamonds.
Industry Challenges
- Traceability system integration:Legacy ERP platforms at mid-sized tanneries lack API connectivity with emerging supply chain mapping tools, forcing expensive middleware deployments.
- Dual certification timelines:Gemological Institute of America and Responsible Jewellery Council approvals now run sequentially rather than in parallel, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fashion Accessories Market |
| Market Size in 2026 | $478.6 Billion |
| Market Size in 2035 | $836.46 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jewelry, Handbags, Belts, Scarves Material: Leather, Metal, Fabric, Plastic End User: Women, Men, Children, Unisex Distribution Channel: Online, Retail Stores, Department Stores, Specialty Shops |
| Companies Covered | LVMH Moët Hennessy Louis Vuitton SE, Kering S.A., Richemont SA, Hermès International S.A., Chanel S.A., Burberry Group plc, Prada S.p.A., Tiffany & Co., Coach Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fashion Accessories Market Emerging Trajectories
Material science breakthroughs and regulatory transparency mandates are converging to reshape how fashion accessories are sourced, authenticated, and sold, with technology investments concentrating in traceability and personalization infrastructure.
Laboratory-grown diamond and gemstone production is electrifying traditional jewelry supply chains. LVMH and Richemont are integrating synthetic stones into entry-tier collections while maintaining mined gem lines for high jewelry. This technology is compressing the pricing power of De Beers sightholders and forcing recalibration of rarity-based marketing.
CSRD disclosure requirements in Europe are mandating scope-three emissions reporting for leather tanning and metal refining operations. Fashion houses must now audit Brazilian cattle ranching and Peruvian silver mining for deforestation and water contamination. Swiss hard luxury manufacturers are responding by consolidating extraction partnerships under direct equity arrangements.
Chinese consumers are bypassing duty-free channels in favor of mainland boutiques and WeChat mini-programs. Domestic retail in Shanghai and Beijing is displacing Hong Kong and Paris as the primary transaction geography for luxury handbags. This rotation is forcing brands to rebuild inventory allocation algorithms around real-time domestic demand signals rather than historical tourist spending patterns.
Fashion Accessories Market Segmentation
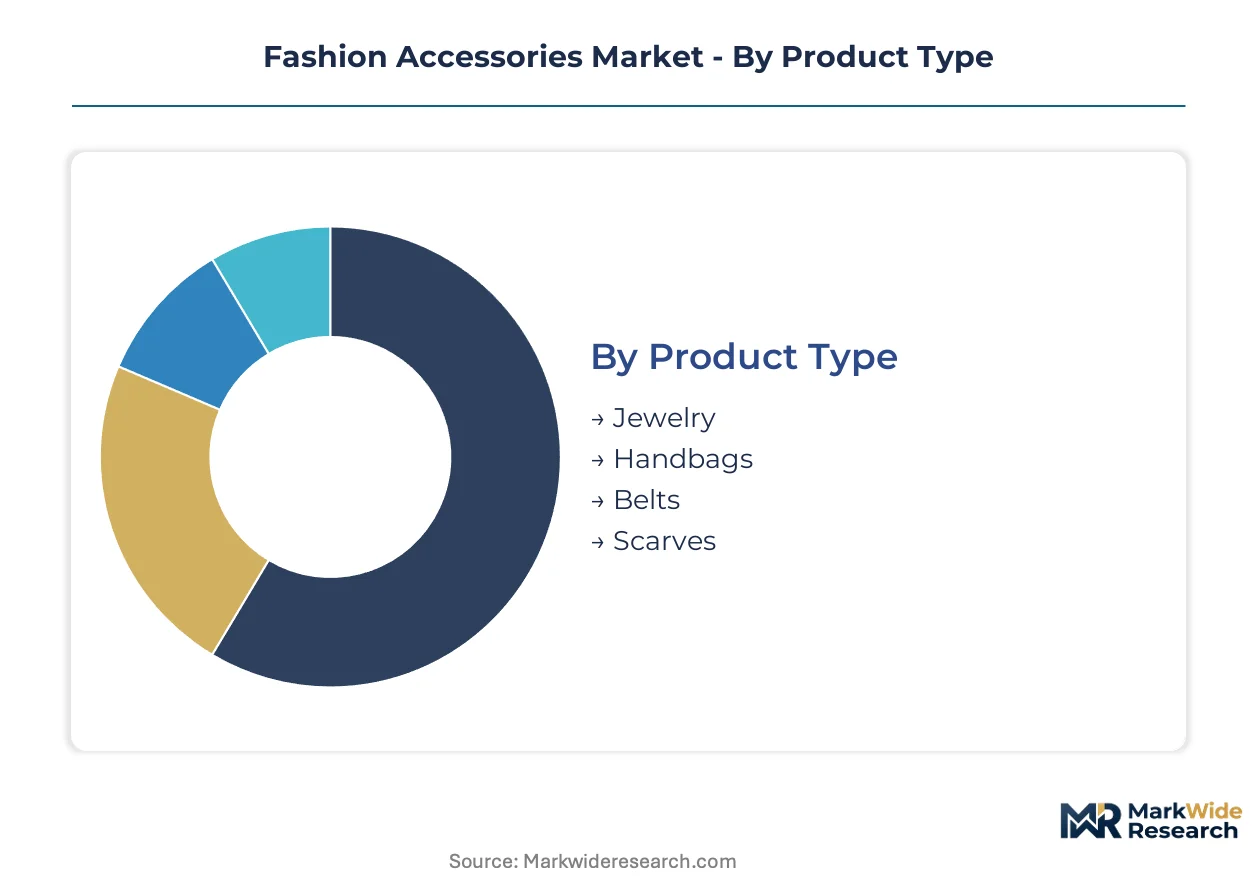
Fashion accessories demand fragments across four intersecting dimensions that determine margin structure and channel strategy. Product-material combinations create distinct supply chain requirements, while end-user demographics and distribution channels dictate pricing architecture and inventory velocity.
Product Type:
Consumer purchase decisions in this market pivot on occasion-based usage frequency and perceived longevity of ownership.
- Jewelry:Precious and semi-precious metal compositions with gem inclusions serve ceremonial gifting and personal adornment functions. Chinese high-net-worth millennials under forty are concentrating demand here, prioritizing gem certification from GIA and artisan provenance documentation over mass retail channels.
- Handbags:Structured leather goods with hardware closures function as portable storage and status signaling devices. Italian and French ateliers dominate artisan production, though generational talent scarcity is compressing output capacity and extending lead times for top-tier houses.
- Belts:Leather and webbing straps with metal buckles serve functional waist adjustment and aesthetic coordination purposes. Entry-tier synthetic variants compete on price in fast-fashion channels.
- Scarves:Woven silk, cashmere, and printed fabric rectangles provide thermal regulation and pattern-based outfit completion. Seasonal color cycles drive replacement purchasing in European markets.
Handbags lead on scale; jewelry leads on momentum.
Material:
Raw material selection determines regulatory exposure, supply chain complexity, and end-market pricing tiers.
- Leather:Tanned bovine and exotic hides from Brazilian ranchlands and Italian tanneries constitute the dominant premium substrate. EU Green Deal due diligence mandates are forcing traceability investments that favor vertically integrated producers with captive tanning operations.
- Metal:Precious alloys and base metals for jewelry findings, buckles, and hardware face REACH electroplating restrictions and volatile gold pricing tied to central bank reserve policies. African mining operations now require documented provenance for European market access.
- Fabric:Silk, wool, cotton, and synthetic textiles serve scarf and soft accessory production with shorter development cycles than leather or metal goods.
- Plastic:Acrylic, polyurethane, and recycled polymer substrates enable entry-tier price positioning and vegan positioning strategies, though CSRD scope-three reporting is pressuring petrochemical-dependent supply chains.
Leather commands the highest value per kilogram; metal faces the steepest compliance cost escalation.
End User:
Gender-based segmentation correlates sharply with average transaction value and repurchase frequency patterns.
- Women:The dominant volume segment spanning all product categories, with particular concentration in handbags and jewelry. Chinese domestic consumption is displacing historical tourist-channel purchasing for this demographic.
- Men:Narrower category participation concentrated in belts, leather goods, and watches, though hard luxury jewelry is gaining traction among Asian professional classes.
- Children:Accessories sized for juvenile wearers with safety-compliant hardware and licensed character motifs, distributed primarily through mass retail.
- Unisex:Growing designation for scarves, certain jewelry forms, and minimalist leather goods marketed across gender lines.
Women's segment anchors absolute revenue; unisex positioning is climbing fastest among younger cohorts.
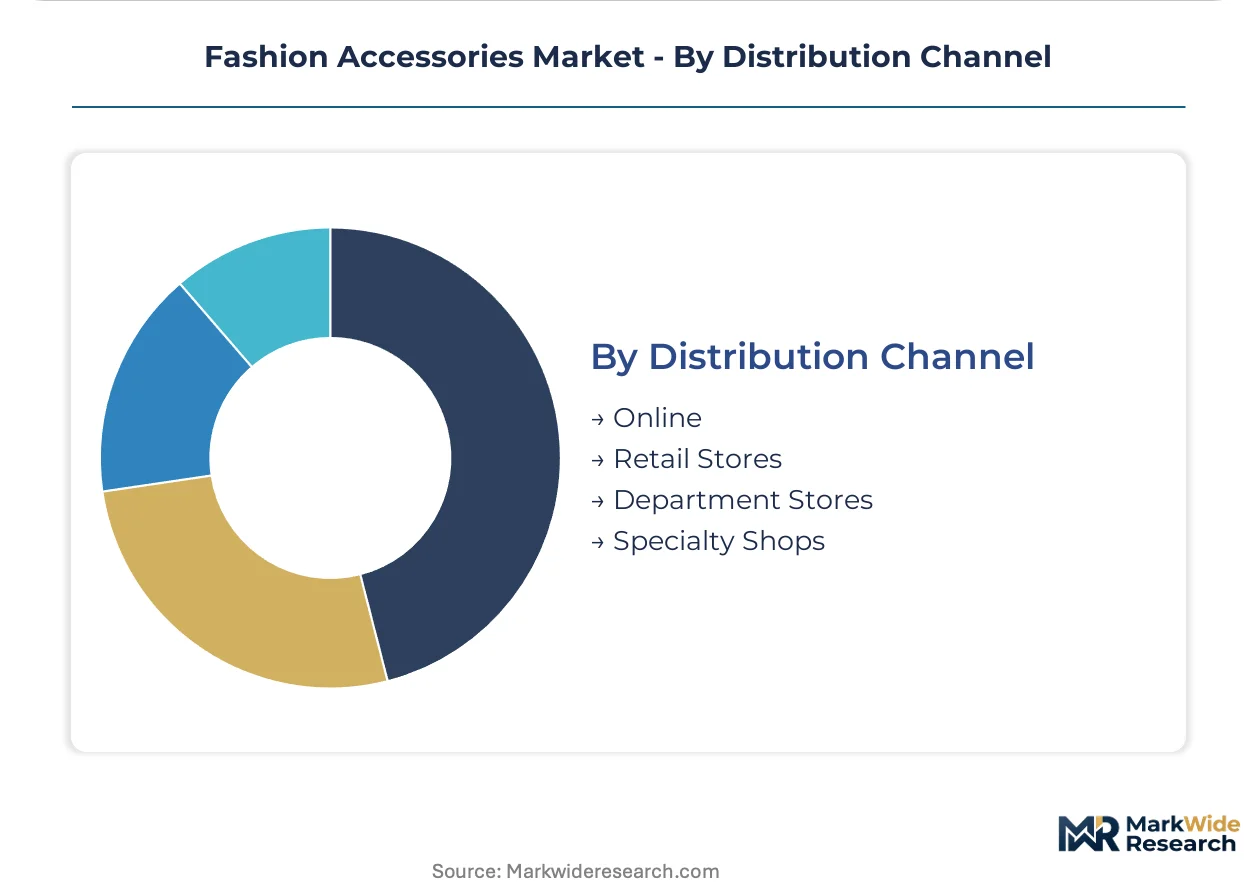
Distribution Channel:
Channel selection determines margin retention, customer data ownership, and inventory risk allocation between brand and intermediary.
- Online:Direct-to-consumer platforms and brand-operated e-commerce capture volume growth by eliminating wholesale markups and enabling first-party data collection for personalization algorithms.
- Retail Stores:Flagship and mall-based brand boutiques control presentation environment and full-price positioning, requiring heavy fixed-cost investment in prime locations.
- Department Stores:Concessions and wholesale arrangements within multi-brand retailers like Galeries Lafayette and Nordstrom provide reach but compress margins and dilute brand control.
- Specialty Shops:Independent jewelers, leather ateliers, and curated concept stores serve discovery-oriented shoppers seeking artisan provenance and limited distribution.
Online channels are expanding most quickly; retail stores retain pricing power for experiential categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian leather artisans and Swiss watchmakers anchor the industry's geographic talent base, with French design houses and Chinese manufacturing clusters completing the core production network across four continents.
France
Paris-based luxury conglomerates drive hard jewelry and leather goods demand through vertically integrated ateliers. EU Green Deal due diligence mandates from Brussels force documented provenance for African-sourced precious metals. The Marais district and Lyon satellite workshops concentrate artisan talent for hardware finishing and gem setting.
Italy
Tuscan tanneries in Santa Croce sull'Arno supply premium bovine leather to handbag manufacturers facing generational workforce scarcity. REACH restrictions from ECHA regulate chrome-tanning effluents and synthetic dye formulations. Milan's Via Montenapoleone retail corridor anchors domestic luxury consumption while Florence maintains leatherworking apprenticeship pipelines.
Switzerland
Geneva and the Jura Arc dominate mechanical watch and high jewelry manufacturing through vertically integrated production. Swissmedic and federal precious metals assay offices enforce purity certification standards. The Neuchâtel canton concentrates movement assembly and gemological laboratories serving Richemont and independent maisons.
China
Shanghai and Beijing boutiques capture repatriated luxury spending as domestic consumption displaces Hong Kong and Paris tourist channels. SAMR enforces jewelry labeling standards and anti-counterfeiting measures for precious metal disclosures. The Yangtze River Delta manufacturing belt produces hardware components and synthetic gem substrates for entry-tier collections.
United States
New York's Fifth Avenue and Los Angeles Rodeo Drive flagships serve HNW millennial collectors prioritizing gem certification and artisan provenance. FTC jewelry labeling standards mandate precious metal purity disclosures and gemstone treatment notifications. Miami's Design District is emerging as a Latin American clientele gateway with expanded leather goods inventory allocation.
Fashion Accessories Market Vendor Landscape
Capital-heavy producers with captive tanneries and in-house goldsmith ateliers compete with asset-light designers relying on contracted manufacturing networks. The market structure concentrates around three strategic archetypes: vertically integrated European luxury houses, specialist hard jewelry manufacturers, and accessible-lifestyle brands with outsourced production. Dominant competitive moves include backward integration into Brazilian cattle ranching and Peruvian silver extraction, plus direct-to-consumer platform buildouts that bypass wholesale markups.
Within the vertically integrated tier, LVMH Moët Hennessy Louis Vuitton SE and Kering S.A. exemplify divergent sourcing philosophies—one through captive supply chains, the other through open-source environmental accounting extending to supplier networks. Richemont SA anchors the hard jewelry specialist position with Swiss manufacturing concentration. These three European-based entities represent distinct competitive templates: conglomerate scale, sustainability transparency, and segment-focused vertical integration respectively.
| Leading Market Players |
|---|
| LVMH Moët Hennessy Louis Vuitton SE |
| Kering S.A. |
| Richemont SA |
| Hermès International S.A. |
| Chanel S.A. |
| Burberry Group plc |
| Prada S.p.A. |
| Tiffany & Co. |
| Coach Inc. |
| Others |
Supply Flow & Price Mechanics
Family-owned Italian tanneries and French leather goods houses anchor supply discipline through generational ownership structures that resist quarterly margin pressure, enabling sustained artisan wage premiums and selective customer pricing power. This ownership pattern insulates premium handbag pricing from commodity volatility while concentrating bargaining leverage over Brazilian hide suppliers.
Pricing Analysis
Bundled artisan provenance and gem certification services command premium positioning against unbundled fast-fashion accessories competing on unit economics. Three-tier pricing structure across haute joaillerie, bridge collections, and entry-tier lines separates GIA-certified stones from untreated synthetics from plated base metals. Pricing pressure stems from laboratory-grown diamond proliferation compressing rarity premiums in entry jewelry tiers. Fast-fashion retailers show highest price sensitivity; ultra-high-net-worth collectors demonstrate inelastic demand for documented provenance.
Supply Chain Analysis
Italian vegetable-tanned leather supply rests on Tuscan tannery clusters in Santa Croce sull'Arno and limited Brazilian ranchland partnerships subject to EU Green Deal traceability mandates. Gold and platinum feed from Swiss refiners and South African mining operations; silk weaving concentrates in Como and Lyon ateliers. Single-source vulnerability runs through generational artisan labor scarcity in French and Italian hardware finishing workshops. Distribution runs through Paris and Milan flagship boutiques for experiential categories, with direct-to-consumer platforms capturing volume growth in entry-tier segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fashion accessories function as a stable compounder anchored by durable brand equity that transcends cyclical consumer spending shifts and generates recurring replacement demand across jewelry, leather goods, and seasonal textiles.
For Market Incumbents: Lock in captive tannery capacity and in-house goldsmith ateliers before generational artisan retirements accelerate. Defend margin structure by accelerating blockchain gem certification deployment against laboratory-grown diamond substitution threats in bridge jewelry tiers. Prioritize WeChat mini-program and mainland China digital infrastructure to capture repatriated domestic consumption.
For New Entrants and Emerging Players: Direct-to-consumer platform operators offer the most accessible entry vector for unbranded designers seeking first-party customer data assets. White-space targets include unisex minimalist leather goods and entry-tier synthetic gem jewelry with carbon-neutral positioning. Penetrate through TikTok Shop and Instagram-native commerce before wholesale channel dependence crystallizes.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-sized Italian leather goods houses with underexploited Asian distribution footprints and aging founder-owners lacking succession plans. Long-term viability centers on transferable artisan apprenticeship pipelines and documented supply chain provenance systems. Watch GIA certification backlogs and REACH reformulation timelines as inflection signals for inventory risk and margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Tannery Acquisition | Secures Brazilian hide traceability compliance under EU Green Deal due diligence mandates. |
| Blockchain Provenance Deployment | Creates tamper-proof gem certification records that satisfy Chinese HNW millennial documentation demands. |
| Direct-to-Consumer Platform Launch | Bypasses Galeries Lafayette and Nordstrom wholesale markups while capturing first-party personalization data. |
| Laboratory-Grown Gem Integration | Compresses entry-tier pricing to compete with De Beers sightholder scarcity-based marketing. |
| Mainland China Digital Infrastructure | Captures repatriated luxury spending through Shanghai and Beijing boutique networks plus WeChat commerce. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with leather goods brand managers, Italian tannery procurement directors, GIA gemological certification specialists, and mainland China luxury retail channel heads. Secondary validation drew from customs records for hide and precious metal trade flows, SEC filings for LVMH and Kering segment disclosures, EU ECHA regulatory bulletins on REACH reformulation timelines, and Swissmedic precious metals assay reports. Bottom-up demand modeling across product-material-end user-channel intersections was triangulated against top-down macroeconomic consumption indicators.
Historical reference periods anchored volume and value projections across the modeling period, with growth trajectories derived from segment-specific adoption curves rather than aggregate extrapolation. Segmentation dimensions included product type, material substrate, end-user demographic, and distribution channel, with additional modeling for gem certification tier and artisan provenance documentation level. Forecast inputs incorporated REACH compliance cost escalations, generational artisan labor supply constraints, and Chinese domestic consumption repatriation velocity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Green Deal enforcement severity and laboratory-grown diamond price compression trajectories. Projections reflect documented assumptions regarding trade policy stability and central bank gold reserve accumulation patterns. A small set of named triggers warrants ongoing watch: GIA certification backlog durations, ECHA electroplating restriction amendments, and SAMR anti-counterfeiting enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fashion & Accessories
Couture Millinery Market
Fashion & Accessories
Sustainable Fashion Market
Fashion & Accessories
North America Handbag Market
Fashion & Accessories
Europe Fashion Accessories Market
Fashion & Accessories
North America Lingerie Market
Fashion & Accessories
Hair Scrunchies Market
Fashion & Accessories
South America Handbags Market
Fashion & Accessories
Personal Accessories Market
Fashion & Accessories
Asia Pacific Fashion Accessories Market
Fashion & Accessories
Selfie Accessories Market
Fashion & Accessories
Custom Dog Tags Market
Fashion & Accessories
North America Fashion Accessories Market
Fashion & Accessories
Hair Accessories Market
Fashion & Accessories
Decorative Accessories Market
Fashion & Accessories
Cufflink Market
Fashion & Accessories
Middle East and Africa Leather Goods Market