
 North America Lingerie Market | 2026-2036
North America Lingerie Market Size, Share, and Industry Trends Forecast 2026-2036
North America Lingerie Market Analytics
Mix-and-match modular bra-and-panty bundling is expanding as the dominant purchase configuration across North American lingerie retail, replacing rigid pre-packaged sets with personalized size combinations. Victoria's Secret & Co. leverages its established brick-and-mortar footprint to sustain in-store fitting services that anchor customer loyalty. ThirdLove competes through algorithm-driven half-cup sizing that differentiates its online channel. Savage X Fenty navigates subscription-based replenishment models that extend recurring revenue streams.
Lingerie encompasses structured undergarments engineered with underwire support, elasticized banding, and blended fiber compositions—typically incorporating nylon, spandex, or cotton—to provide breast support, body contouring, and foundational layering beneath apparel. Bras and panties occupy the mature volume core of the category, while shapewear captures concentrated margin pools due to higher unit prices and technical construction requirements. Sleepwear segments are gaining velocity through loungewear crossover positioning that blurs residential and casual-outdoor use cases.
The US Federal Trade Commission enforces textile fiber labeling rules that mandate accurate content disclosure, while California's Proposition 65 requires warning protocols for certain dye chemicals that affect material sourcing decisions. Health Canada regulates intimate apparel safety standards for products entering the Canadian market, creating dual-compliance obligations for cross-border suppliers. Stakeholders must monitor evolving state-level chemical restrictions and direct-to-consumer return-policy legislation that reshape inventory risk and last-mile economics.
Market Dynamics
Direct-to-consumer sizing algorithms are compressing traditional fitting-room dependence across North American lingerie retail, forcing established players to rebuild customer acquisition economics around virtual try-on infrastructure and return-policy absorption costs.
Growth Catalysts
- California Proposition 65 compliance protocols:Chemical disclosure mandates are accelerating clean-dye sourcing investments that premium brands leverage for sustainability positioning and price-premium capture.
- Half-cup sizing granularity:Algorithmic fit-matching technology is reducing return rates in online channels by addressing the 40% of wearers falling between standard sizes.
- New York and Los Angeles design clusters:Geographic concentration of technical talent and sample-production infrastructure shortens lead times for trend-responsive capsule collections.
Market Restraints
- Petrochemical input volatility:Nylon and spandex feedstock costs fluctuate with crude oil derivatives, compressing margin stability for mid-market producers lacking forward-contract coverage.
- Asian cut-and-sew concentration:Over 70% of North American lingerie assembly relies on Vietnam, Bangladesh, and Sri Lankan facilities, exposing supply continuity to shipping-rate spikes and labor-action risks.
- Technical limitation in seamless construction:3D-knit shaping technology cannot yet replicate underwire support structures for D+ cup sizes, capping addressable market expansion in full-figure segments.
Strategic Opportunities
- Mexico nearshoring expansion:Duty-free access under USMCA and 10-day shipping lanes from Guanajuato and Puebla states enable responsive replenishment models for fast-fashion lingerie lines.
- Subscription-based replenishment:Automated bra-replacement cycles timed to elastic degradation patterns are capturing recurring revenue streams from millennial and Gen Z cohorts.
- Health Canada intimate-apparel safety harmonization:Alignment with US FTC textile labeling rules simplifies cross-border compliance for brands entering the Canadian market through Toronto and Vancouver retail corridors.
Industry Challenges
- Technical pattern-making talent scarcity:Specialized skills in grading complex curves across 40+ size permutations command wage premiums that strain emerging brand operating budgets.
- Multi-channel inventory fragmentation:Size-specific demand unpredictability across wholesale, owned-retail, and direct-to-consumer channels elevates obsolescence risk for seasonal colorways.
- Return-logistics cost absorption:Fit-driven return rates averaging 25-35% in online lingerie purchases require reverse-supply-chain infrastructure that erodes unit economics for pure-play digital entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Lingerie Market |
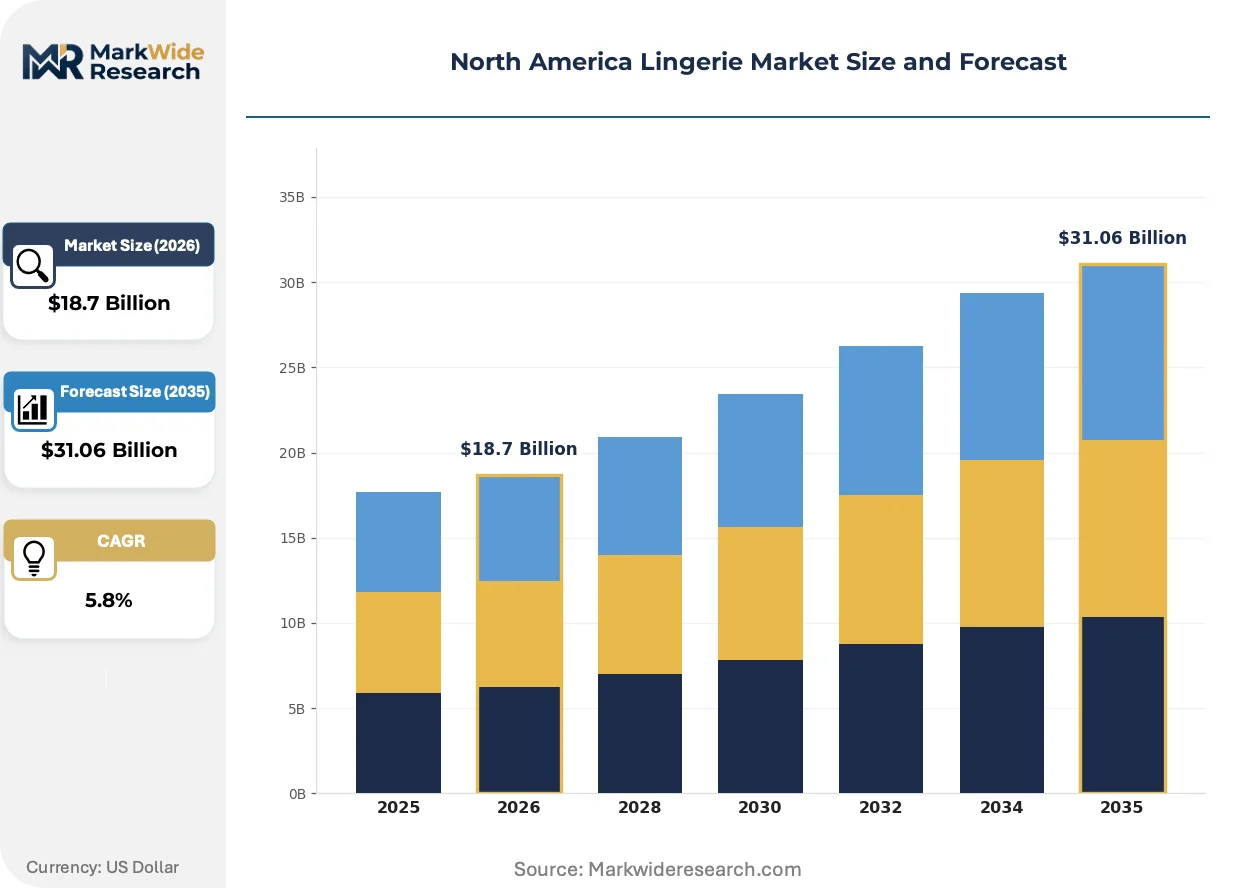
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bras, Panties, Shapewear, Sleepwear Material: Cotton, Lace, Satin, Nylon End User: Women's Fashion, Maternity, Plus Size, Mass Market Distribution Channel: Online Retail, Department Stores, Specialty Boutiques, Discount Stores |
| Companies Covered | Victoria's Secret & Co., PVH Corp., Hanesbrands Inc., American Eagle Outfitters, Calvin Klein, Jockey International, ThirdLove, Savage X Fenty, Spanx, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Lingerie Market Evolving Landscape
Material science breakthroughs and regulatory disclosure mandates are converging to reshape product architecture and sourcing transparency across North American intimate apparel, with implications spanning fiber selection through end-of-life recovery systems.
Smart textile sensor integration is embedding stretch-responsive conductive threads into sports bra bands to monitor biometric signals during athletic activity. Early adopters in the boutique fitness and marathon-training segments are driving pilot orders despite 40% unit-cost premiums over standard compression garments. This functionality is integrating performance-apparel positioning into lingerie categories previously segmented by occasion rather than activity state.
The US Federal Trade Commission's Textile Fiber Products Identification Act enforcement is tightening accuracy requirements for fiber-content claims and origin labeling, with 2023-2024 audit expansions targeting recycled-content assertions. Penalty exposure and class-action litigation risk are forcing reformulation of marketing claims around "sustainable" material blends. California-based direct-to-consumer brands face the steepest compliance costs given Proposition 65's overlapping chemical-warning obligations.
Buyers are consolidating purchase authority around modular bundling platforms that algorithmically suggest complementary bra-and-panty combinations based on prior fit data rather than pre-packaged set configurations. Specialty boutiques in Brooklyn, Austin, and Portland are deploying this approach through clienteling apps that replace traditional seasonal collection launches with continuous replenishment. This pattern concentrates most visibly among 25-34 year-old purchasers prioritizing personalization over brand loyalty in metropolitan coastal markets.
North America Lingerie Market Segmentation
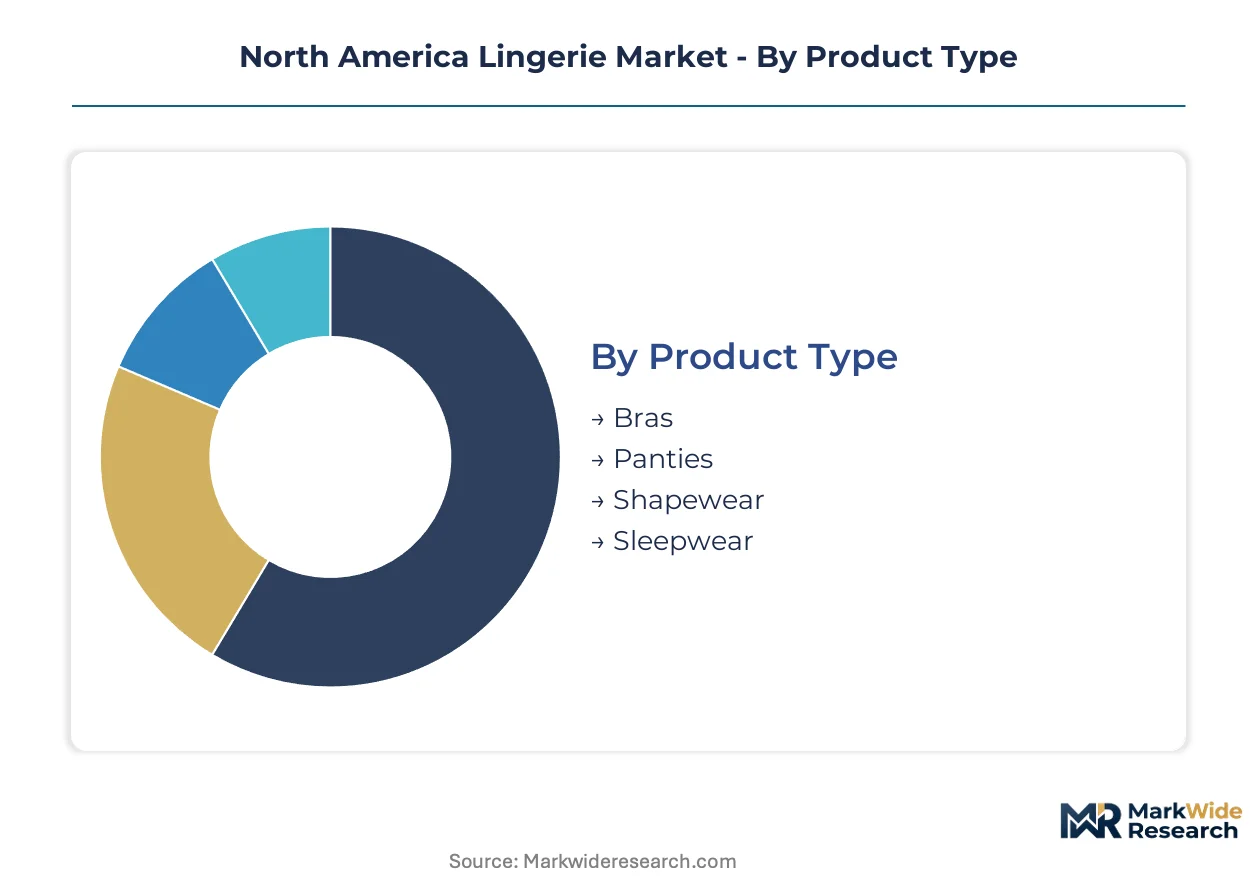
Segmentation in North American lingerie retail separates volume-driven essentials from margin-rich technical categories. Understanding where consumer willingness-to-pay concentrates enables brands to allocate design talent and inventory investment across divergent profitability profiles.
Product Type:
Volume leadership sits with everyday replenishment items, while premium capture concentrates in technical construction categories requiring specialized pattern-making expertise.
- Bras:Structured undergarments incorporating underwire support, elasticized banding, and blended fiber compositions of nylon, spandex, or cotton. Demand clusters in California and New York metropolitan corridors where direct-to-consumer fitting algorithms reduce return rates for half-cup sizing configurations.
- Shapewear:Compression garments engineered with targeted paneling and high-gauge knit structures for body contouring beneath apparel. Higher unit prices and technical construction requirements generate concentrated margin pools, with Health Canada safety standards creating dual-compliance obligations for cross-border suppliers entering Canadian markets through Toronto retail corridors.
- Panties:Lower-complexity bottoms in brief, thong, and boyshort configurations, typically manufactured through cut-and-sew assembly in Vietnam and Bangladesh facilities.
- Sleepwear:Loungewear-crossover positioning blurs residential and casual-outdoor use cases, gaining velocity through relaxed dress codes in Austin and Portland metropolitan markets.
Today's leader: Bras. Tomorrow's challenger: Shapewear.
Material:
Cost tier stratification separates commodity naturals from performance synthetics, with regulatory disclosure mandates reshaping sourcing transparency.
- Nylon:Petroleum-derived synthetic fiber delivering durability, elasticity, and moisture-wicking performance in high-compression applications. Petrochemical input volatility exposes mid-market producers lacking forward-contract coverage to margin compression.
- Cotton:Natural cellulose fiber prized for breathability and skin-contact comfort in everyday wear segments. California Proposition 65 compliance protocols accelerate clean-dye sourcing investments that premium brands leverage for sustainability positioning.
- Lace:Open-weave decorative fabric requiring specialized needlework or raschel knitting equipment, concentrated in European and Asian supply bases.
- Satin:Smooth, glossy weave structure produced through filament yarn arrangements, commanding price premiums in occasion-wear and bridal adjacent segments.
Current procurement prioritizes Nylon for performance. Clean-label momentum favors Cotton expansion.
End User:
Customer type segmentation reveals divergent fit complexity and price elasticity profiles across body-stage and size-range requirements.
- Plus Size:Full-figure segments requiring extended size runs and reinforced support engineering. Technical limitation in seamless 3D-knit construction prevents underwire-equivalent support replication for D+ cup sizes, capping addressable market expansion.
- Women's Fashion:Style-driven purchasers prioritizing trend-responsive colorways and seasonal collection cycles. New York and Los Angeles design clusters shorten lead times for capsule collections targeting 25-34 year-old metropolitan coastal demographics.
- Maternity:Adaptive sizing for gestational body changes, with nursing functionality integration driving specialized clasp and panel engineering.
- Mass Market:Price-sensitive volume segments served through discount retail and private-label programs, with Asian cut-and-sew concentration exposing supply continuity to shipping-rate volatility.
Established base: Women's Fashion. Steepest expansion trajectory: Plus Size.
Distribution Channel:
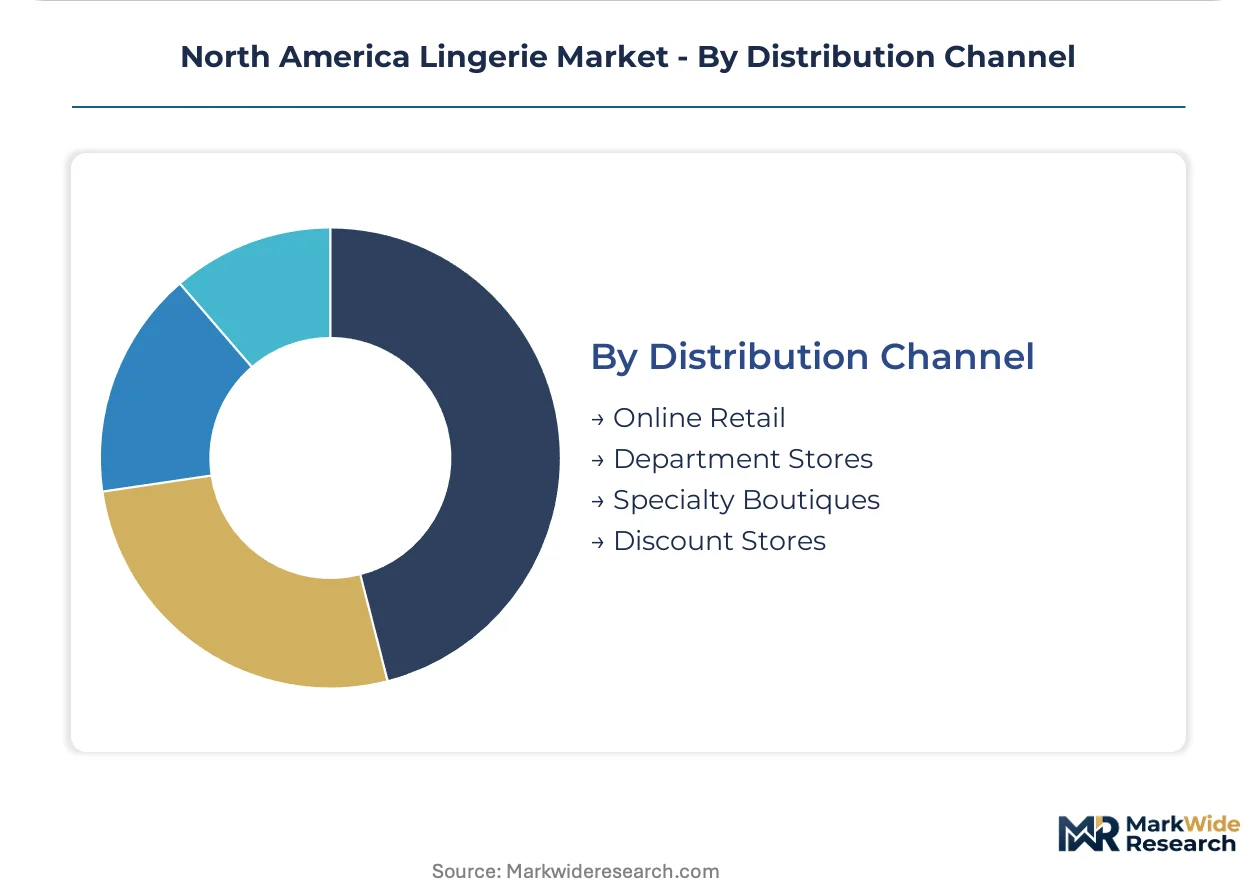
Channel economics determine return-policy absorption capacity and customer acquisition cost structures.
- Online Retail:Algorithm-driven fit-matching and virtual try-on infrastructure serving younger demographics seeking inclusive sizing. Fit-driven return rates averaging 25-35% require reverse-supply-chain infrastructure that erodes unit economics for pure-play digital entrants.
- Specialty Boutiques:Clienteling apps and in-store fitting services in Brooklyn, Austin, and Portland replace seasonal launches with continuous replenishment. Mix-and-match modular bundling concentrates most visibly among personalization-prioritizing purchasers.
- Department Stores:Legacy wholesale partnerships with established lingerie brands, facing compression from direct-to-consumer channel shift.
- Discount Stores:Value-oriented mass-market access, dependent on offshore manufacturing scale and limited size-range offerings.
Dominant growth vector: Online Retail. Defensive anchor: Specialty Boutiques.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lingerie manufacturing scaled through New York's garment district in the early twentieth century, establishing technical pattern-making expertise that persists in today's design clusters. California and New York remain the twin poles of demand concentration, with metropolitan coastal markets driving innovation in fit technology and direct-to-consumer distribution models.
United States
Algorithmic fit-matching and virtual try-on infrastructure serve younger demographics seeking inclusive sizing across California and New York metropolitan corridors. The US Federal Trade Commission enforces textile fiber labeling rules that mandate accurate content disclosure and recycled-content claim verification. Los Angeles design clusters shorten lead times for trend-responsive capsule collections targeting 25-34 year-old purchasers.
Canada
Toronto and Vancouver retail corridors anchor cross-border demand for premium lingerie brands entering through Health Canada-regulated import channels. Health Canada regulates intimate apparel safety standards that create dual-compliance obligations for US-based suppliers. Montreal's technical textile research institutions support regional innovation in sustainable fiber development and clean-dye processing protocols.
Mexico
Guanajuato and Puebla states enable responsive replenishment models for fast-fashion lingerie lines through duty-free access under USMCA provisions. Mexico's national consumer protection agency (PROFECO) oversees textile labeling requirements that align with US disclosure standards. Nearshoring expansion from these manufacturing zones compresses shipping lanes to 10-day turnaround for North American distribution networks.
North America Lingerie Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technical construction and brand positioning dimensions, with algorithmic fit specialists commanding price premiums over mass-market assemblers. The vendor base separates into three strategic archetypes: established brick-and-mortar retailers with fitting-service infrastructure, direct-to-consumer digital natives leveraging half-cup sizing granularity, and subscription-based replenishment platforms capturing recurring revenue. Dominant competitive moves include geographic diversification into Mexico nearshoring corridors and technology licensing for virtual try-on infrastructure.
Within the established retail tier, Victoria's Secret & Co. and PVH Corp. represent legacy brick-and-mortar anchors sustaining customer loyalty through in-store fitting services and wholesale department store partnerships. ThirdLove occupies a position among algorithm-driven digital specialists differentiating through granular sizing configurations that reduce online return rates.
| Leading Market Players |
|---|
| Victoria's Secret & Co. |
| PVH Corp. |
| Hanesbrands Inc. |
| American Eagle Outfitters |
| Calvin Klein |
| Jockey International |
| ThirdLove |
| Savage X Fenty |
| Spanx |
| Others |
Value Network & Pricing Analysis
Algorithmic fit-matching technology is compressing traditional fitting-room economics while simultaneously redrawing cost structures across North American lingerie retail, concentrating margin pressure on pure-play digital entrants absorbing 25-35% return rates while rewarding vertically integrated incumbents with captive sizing infrastructure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates algorithmic fit specialists from mass-market assemblers and private-label programs. Price differentiation hinges on sizing granularity and fiber-content certification grade, with California Proposition 65 compliance investments enabling premium capture. Cost compression in the economy tier is intensifying because of petrochemical input volatility in nylon and spandex feedstocks. Mass-market purchasers show highest price sensitivity, while full-figure segments accept premiums for technical construction.
Supply Chain Analysis
USMCA domestic-content provisions are accelerating Mexico nearshoring from Guanajuato and Puebla states, reshaping sourcing patterns for North American bound production. Assembly draws from Vietnam, Bangladesh, and Sri Lankan cut-and-sew facilities, with raw material dependencies centering on petroleum-derived nylon, elasticized banding components, and clean-dye cotton inputs. Single-source vulnerability in Asian assembly exposes continuity to shipping-rate spikes. Distribution runs through direct-to-consumer algorithms, specialty boutique clienteling apps, and legacy department store wholesale partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America lingerie market functions as a regulatory compounder where FTC textile labeling enforcement and California Proposition 65 chemical disclosure mandates are accelerating clean-dye sourcing investments that reshape competitive positioning.
For Market Incumbents: Deploy virtual try-on infrastructure licensing to counter algorithm-driven digital specialists eroding wholesale channel share. Fortify in-store fitting services in California and New York metropolitan corridors where tactile experience anchors loyalty against subscription-based replenishment models. Channel control through captive boutique networks offers defensive leverage against direct-to-consumer return-policy absorption costs.
For New Entrants and Emerging Players: Direct-to-consumer half-cup sizing algorithms open white-space penetration in the 40% of wearers falling between standard sizes, particularly among 25-34 year-old metropolitan coastal demographics. Plus-size segments present the most penetrable opportunity given technical limitations in seamless 3D-knit construction capping incumbent addressable market expansion. Launch through modular bundling platforms replacing rigid pre-packaged set configurations.
For Investors and Strategic Acquirers: Roll-up economics work for algorithmic fit-technology platforms because specialized pattern-making talent scarcity commands wage premiums that strain emerging brand operating budgets. Five-to-ten year viability favors acquisition targets with proprietary sizing databases and Health Canada compliance infrastructure for cross-border expansion. Monitor subscription-based replenishment adoption rates among millennial and Gen Z cohorts as inflection signal for recurring revenue model validation.
| Strategic Initiative | Industry Significance |
|---|---|
| Virtual Try-On Infrastructure Deployment | FTC labeling enforcement pressures accuracy claims that algorithmic fitting validates. |
| Mexico Nearshoring Expansion | USMCA duty-free access from Guanajuato compresses replenishment lead times for fast-fashion lines. |
| Clean-Dye Sourcing Investment | California Proposition 65 compliance protocols enable sustainability positioning and price-premium capture. |
| Subscription-Based Replenishment Launch | Automated bra-replacement cycles timed to elastic degradation patterns capture recurring revenue. |
| Half-Cup Sizing Technology Licensing | Granular fit-matching reduces online return rates that erode unit economics for pure-play entrants. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with brand managers, category buyers at specialty boutiques, supply planners at cut-and-sew facilities, and channel sales heads with secondary validation against FTC textile labeling enforcement records, USMCA trade documentation, Health Canada intimate apparel safety standards, and retail audit data from Nielsen and Circana. Bottom-up sizing algorithm adoption rates and top-down market value estimates were triangulated for convergence.
Historical reference periods anchored the projection horizon to pre-pandemic baseline demand patterns and post-acceleration digital channel shifts. Segmentation dimensions modeled include product type, material composition, end-user body stage, and distribution channel complexity. CAGRs were derived from fitted trend extrapolation moderated by petrochemical input volatility assumptions and regulatory compliance cost trajectories. Forecast inputs incorporated elastic degradation replacement cycles and virtual try-on adoption curves.
The model assumes a particular technology adoption path; alternative pathways for 3D-knit seamless construction reaching D+ cup support equivalence would alter the outlook for plus-size addressable market expansion. Forecasts reflect assumptions around USMCA stability, Asian shipping-rate normalization, and FTC audit intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fashion & Accessories
North America Handbag Market
Fashion & Accessories
Hair Scrunchies Market
Fashion & Accessories
Asia Pacific Fashion Accessories Market
Fashion & Accessories
Hair Accessories Market
Fashion & Accessories
Cufflink Market
Fashion & Accessories
Couture Millinery Market
Fashion & Accessories
Personal Accessories Market
Fashion & Accessories
South America Handbags Market
Fashion & Accessories
Global Handbags Market
Fashion & Accessories
Decorative Accessories Market
Fashion & Accessories
Sustainable Fashion Market
Fashion & Accessories
Selfie Accessories Market
Fashion & Accessories
Middle East and Africa Leather Goods Market
Fashion & Accessories
North America Fashion Accessories Market
Fashion & Accessories
Custom Dog Tags Market
Fashion & Accessories
Europe Fashion Accessories Market