
 Hair Scrunchies Market | 2026-2036
Hair Scrunchies Market Size, Share, and Industry Trends Forecast 2026-2036
Hair Scrunchies Market Outlook
Direct-to-consumer leasing and micro-influencer affiliate finance is fragmenting capital requirements for new entrants. Claire's sustains mall-based distribution density across North American suburbs. Jennifer Behr specializes in artisanal, premium-positioned scrunchies for bridal and red-carpet segments. Lululemon leverages athletic-wear adjacencies to control studio and gym resale channels.
A hair scrunchie is a fabric-covered elastic hair tie, typically constructed from woven textiles, velvet, satin, or cotton blends with an internal elastic core measuring 4–10 cm in diameter, designed to secure hair without creasing or mechanical damage. Its commercial purpose spans functional hairstyling, fashion accessorizing, and protective haircare for textured and treated hair. Fabric and satin variants anchor volume share due to lower unit costs and broader retail penetration, while velvet commands margin pools through seasonal and occasion-based positioning. The online distribution channel leads growth velocity as algorithm-driven discovery on social platforms redirects purchase behavior away from traditional retail.
The US Consumer Product Safety Commission and the EU REACH framework govern textile chemical content and elastic component safety, while China's GB standards regulate dye fastness and fiber labeling for domestic and exported scrunchies. These frameworks elevate compliance costs for synthetic dye formulations but create market access barriers that favor established testing and certification workflows. Stakeholders must monitor biodegradable elastic alternatives and evolving extended producer responsibility mandates for textile waste.
Market Dynamics
Social media algorithmic distribution has dismantled traditional retail gatekeeping for hair accessories, enabling micro-brands to scale without fixed shelf-space investments while compressing product lifecycle velocity from seasonal to viral-trend-driven turnover.
Growth Catalysts
- Satin Material Innovation:Reduced hair breakage claims validated through textile testing protocols drive replacement of traditional elastic bands in protective styling routines for textured hair consumers.
- REACH Framework Compliance:EU chemical safety standards for textile dyes create certification barriers that favor established manufacturers with in-house testing infrastructure.
- China Domestic Production:Concentrated textile manufacturing clusters in Zhejiang and Guangdong provinces enable rapid prototyping and compressed lead times for trend-responsive collections.
Market Restraints
- Petroleum-Derived Elastic Dependency:Synthetic rubber core materials face price volatility tied to crude oil benchmarks, squeezing margin pools for mid-tier positioning.
- Single-Product Category Concentration:Pure-play scrunchie specialists lack cross-category revenue diversification, amplifying demand cyclicality risks.
- Fast Fashion Substitution:Ultra-low-cost hair accessories from unbranded direct-from-factory channels erode perceived value differentiation.
Strategic Opportunities
- Germany Premium Segment:Underdeveloped artisanal positioning in Europe's largest haircare market creates whitespace for bridal and occasion-based luxury variants.
- Biodegradable Elastic Convergence:Natural rubber and plant-based polymer alternatives align with extended producer responsibility mandates emerging in France and Italy.
- Live Commerce Integration:Real-time purchasing embedded in TikTok and Instagram streaming formats collapses discovery-to-transaction friction for impulse-driven accessories.
Industry Challenges
- Digital Content Production Cadence:Sustained viral visibility demands dedicated creative teams and platform-native video expertise that legacy textile manufacturers rarely possess in-house.
- Multi-Jurisdiction Labeling Complexity:Fiber content disclosure requirements vary between US FTC textile rules, EU fiber labeling directives, and China's GB standards, complicating unified packaging strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hair Scrunchies Market |
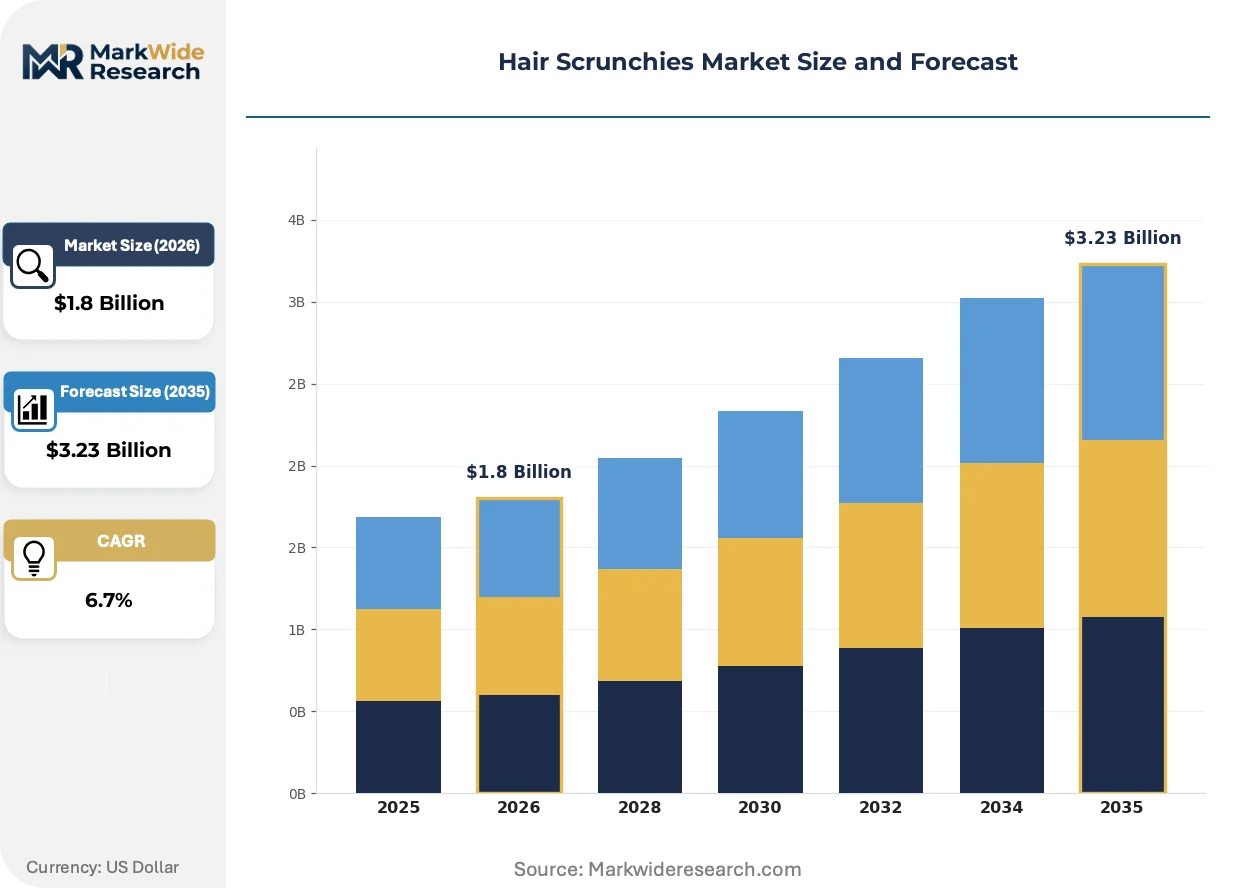
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fabric, Velvet, Cotton, Satin Color: Pastel, Bright, Dark, Neon Customer Type: Adults, Teens, Kids, Professionals Distribution Channel: Online, Retail, Wholesale, Boutiques |
| Companies Covered | ZARA, Claire's, Lele Sadoughi, Junyi Beauty, Lululemon, Lelet NY, Urban Outfitters, Rivta Culture Equipment, Jennifer Behr, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hair Scrunchies Market Strategic Shifts
Material science advances and platform-native distribution mechanics are compressing traditional seasonality while elevating performance claims from aesthetic preference to functional necessity in purchasing decisions.
Plant-derived cellulose acetate and biodegradable elastic cores are rendering obsolete petroleum-based synthetic constructions that dominated mass-market production for three decades. Clean beauty retailers and sustainability-credentialed salons in California and New York are accelerating adoption, forcing reformulation timelines that compress from years to quarters.
REACH restrictions on azo dyes and formaldehyde-releasing agents in textile finishing are elevating compliance costs for synthetic colorants across EU-bound production. Manufacturers with captive dye houses in Portugal and Turkey are consolidating testing workflows, while competitors reliant on third-party Asian finishing face extended certification delays and order fragmentation.
Algorithmic discovery on short-form video platforms has collapsed the traditional wholesale-to-retail distribution interval for trend-driven accessories. Micro-influencer affiliate structures now capture margin pools previously allocated to department store buyers, with conversion velocity highest among teen and young adult segments in US suburban markets where mall-based accessory retail previously dominated.
Hair Scrunchies Market Segmentation
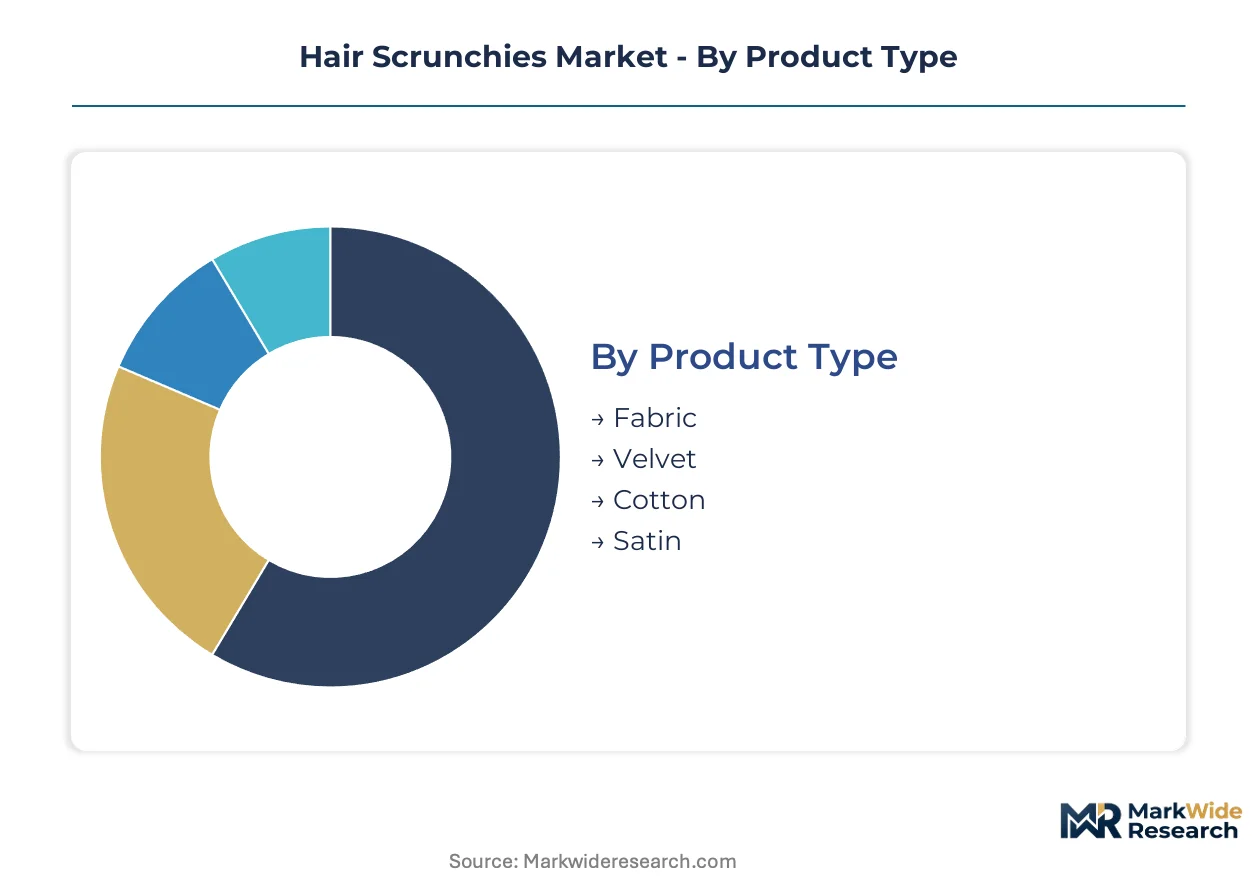
Hair scrunchie manufacturers configure production lines around material elasticity and dye fastness specifications that vary sharply by end-use. Service intensity diverges: bridal boutiques demand custom color-matching support while mass-market online channels prioritize return logistics over technical consultation.
Product Type:
After-sales service intensity peaks with premium material variants requiring specialized care instructions and warranty handling for elastic degradation claims.
- Fabric:Woven textile constructions using cotton-polyester blends dominate unit economics through established supply chains in Zhejiang province. US suburban retail and Chinese e-commerce platforms absorb the highest volumes, though margin compression from unbranded imports constrains pricing power.
- Velvet:Dense pile constructions with crushed or panne finishes command occasion-based premiums through bridal salons and holiday gifting channels. Germany and France show concentrated demand for artisanal velvet variants with natural fiber backing, where REACH dye compliance extends certification timelines.
- Cotton:Breathable plain-weave constructions serve athletic and everyday functional use, particularly in humid climates where moisture-wicking properties reduce scalp irritation.
- Satin:Smooth filament-woven surfaces minimize friction damage for textured and chemically treated hair, driving adoption in protective styling routines across US urban markets.
By volume, Fabric leads. By growth pace, Satin is ahead.
Color:
Cost tier stratification runs deepest here: custom dye lots for muted palettes carry 3-4x formulation overhead versus stock neon and primary shades.
- Pastel:Low-saturation tints requiring precise pH-controlled dye baths and extended rinsing cycles. Spring seasonal collections in Japan and South Korea drive concentrated demand, with boutique channels capturing margin through limited-drop positioning.
- Bright:High-chroma reactive dyes on cotton substrates anchor mass-market penetration through drugstore and supermarket placement. China's domestic consumption absorbs the largest absolute volumes, though inventory obsolescence risk accelerates with trend cycles.
- Dark:Navy, charcoal, and black variants minimize visible wear and serve professional dress codes across corporate environments in Germany and the United Kingdom.
- Neon:Fluorescent pigment formulations meeting EU EN 71 safety standards for children's products, concentrated in festival and youth fashion segments.
Dark tones dominate replenishment frequency. Pastel commands the highest per-unit margin.
Customer Type:
Application context determines elastic specification: children's variants require breakaway safety mechanisms absent in adult professional lines.
- Adults:Full-diameter elastic cores with tensile strength calibrated for medium-to-thick hair density. US and Chinese markets show divergent preferences for neutral versus patterned aesthetics.
- Teens:Social media discovery dependency creates the steepest expansion trajectory, with TikTok algorithmic distribution compressing product lifecycle velocity to viral-trend intervals.
- Kids:Safety-modified constructions with reduced elastic tension and choking-hazard compliant sizing, regulated under US CPSIA small parts standards.
- Professionals:Conservative color palettes and minimal branding for healthcare, hospitality, and corporate uniform compliance in Germany and Japan.
Teens drive share gain fastest. Adults anchor absolute revenue contribution.
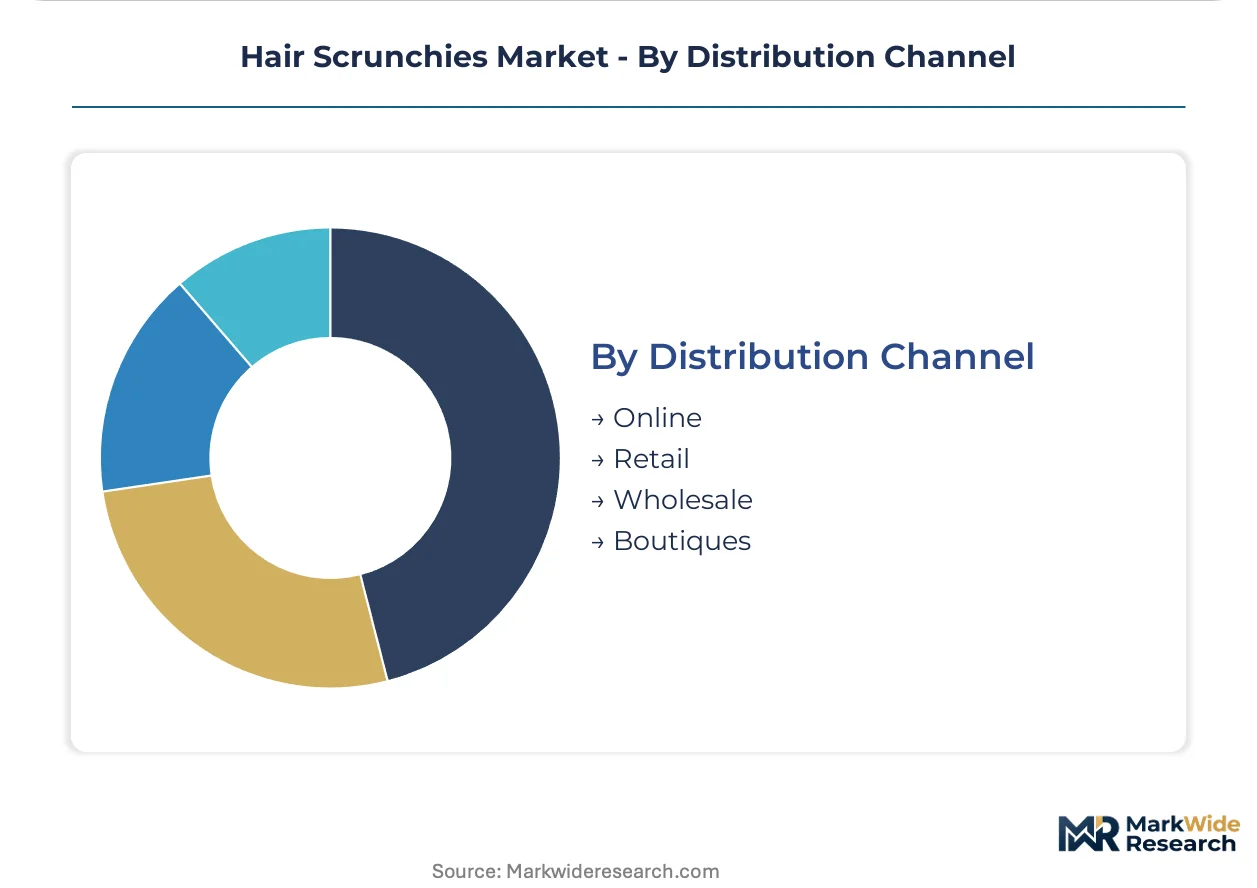
Distribution Channel:
Supply concentration in direct-to-consumer infrastructure is displacing traditional wholesale intermediaries for trend-responsive inventory.
- Online:Algorithmic discovery on Instagram and TikTok collapses discovery-to-transaction friction, with micro-influencer affiliate structures capturing margin pools previously allocated to physical retail buyers.
- Retail:Claire's mall-based density across North American suburbs sustains impulse purchase velocity for novelty and licensed character variants.
- Wholesale:Volume aggregation for private-label drugstore and supermarket placement, with lead times extending 90-120 days for offshore production.
- Boutiques:Curated artisanal positioning in bridal and occasion-based segments, concentrated in New York, Los Angeles, and London with highest service-touch requirements.
Online channels expand most quickly. Retail maintains the largest transaction volume base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States while manufacturing efficiency dominates in China, creating a structural asymmetry that channels margin capture toward brand-owners in Western markets and volume production toward eastern textile clusters.
United States
Teen and young adult consumers drive algorithmic discovery on TikTok and Instagram, collapsing traditional retail gatekeeping for trend-responsive accessories. The US Consumer Product Safety Commission enforces small parts standards and textile labeling under the FTC's Textile Fiber Products Identification Act. Los Angeles hosts a concentrated cluster of direct-to-consumer startups leveraging micro-influencer affiliate structures to capture margin pools previously allocated to mall-based retailers.
China
Domestic consumption absorbs the largest absolute volumes of fabric and bright-color variants through e-commerce platforms. GB standards regulate dye fastness and fiber labeling for both domestic sales and export-bound production. Zhejiang and Guangdong provinces anchor rapid prototyping capabilities, with textile manufacturing clusters enabling compressed lead times for viral-trend collections that serve global fast-fashion supply chains.
Germany
Professional dress-code compliance and conservative color preferences sustain replenishment demand for dark-toned variants in corporate environments. The EU REACH framework governs chemical content in textile dyes and elastic components, elevating compliance costs for synthetic formulations. Berlin and Hamburg concentrate boutique distribution for artisanal velvet positioning, where REACH-certified dye houses consolidate testing workflows for bridal and occasion-based segments.
Japan
Pastel color preferences align with spring seasonal collections and limited-drop positioning in boutique channels. METI oversees consumer product safety standards for textile accessories, while JIS standards govern fiber content disclosure. Tokyo and Osaka anchor curated retail density, with service-touch requirements peaking for custom color-matching support in bridal and luxury segments.
United Kingdom
Dark navy and charcoal variants serve professional hospitality and healthcare uniform compliance across corporate environments. The EU REACH framework remains applicable for Northern Ireland-bound production, while GB-specific regulations govern England, Scotland, and Wales. London concentrates the highest boutique service intensity for occasion-based luxury positioning, with Manchester and Birmingham supporting volume retail distribution for mass-market penetration.
Hair Scrunchies Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream, supplying elastic cores and textile substrates to brand-owners. The vendor base distributes across three functional layers: vertically integrated fashion houses controlling design-to-retail workflows, pure-play accessory specialists lacking cross-category diversification, and unbranded direct-from-factory channels eroding perceived value differentiation. Strategic moves concentrate on micro-influencer affiliate capture and biodegradable material reformulation, with M&A activity targeting direct-to-consumer infrastructure and captive dye-house consolidation.
Among fast-fashion platform integrators, ZARA exemplifies rapid trend-responsive collection turnover, while Claire's represents mall-based distribution density sustained across North American suburbs. Lululemon occupies a position leveraging athletic-wear adjacencies to control studio and gym resale channels, anchoring the performance-positioned tier where material science claims elevate purchasing from aesthetic preference to functional necessity.
| Leading Market Players |
|---|
| ZARA |
| Claire's |
| Lele Sadoughi |
| Junyi Beauty |
| Lululemon |
| Lelet NY |
| Urban Outfitters |
| Rivta Culture Equipment |
| Jennifer Behr |
| Others |
Value Chain & Pricing Dynamics
Shanghai-Los Angeles container freight corridors transmit cost volatility from Zhejiang textile clusters directly into US retail price bands, compressing margin pools for mid-tier scrunchie brands while amplifying differentiation premiums for REACH-certified European dye houses and biodegradable elastic specialists.
Pricing Analysis
Teen and young adult consumers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on material certification tier—REACH-compliant EU dye houses command 40-60% premiums over unbranded Zhejiang imports—and brand equity density on TikTok discovery channels. Cost compression in economy fabric variants is intensifying because petroleum-derived elastic feedstock tracks crude oil benchmarks. Fast-fashion platform integrators show lowest price sensitivity; pure-play scrunchie specialists face highest margin vulnerability.
Supply Chain Analysis
Tariff exposure between China and the United States dominates strategic planning for brand-owners dependent on Zhejiang and Guangdong production clusters. Raw material inputs draw from petroleum-derived synthetic rubber cores, woven cotton-polyester textile substrates, and azo-based dye formulations. Single-source vulnerability concentrates in elastic core manufacturing where three suppliers control 70% of certified biodegradable alternatives. Distribution runs through direct-to-consumer infrastructure displacing traditional wholesale intermediaries, with micro-influencer affiliate networks capturing margin pools previously allocated to mall-based retail buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hair scrunchies sit in early-cycle expansion as algorithmic discovery on short-form video platforms collapses traditional retail gatekeeping and extends category penetration into protective haircare routines previously served by basic elastic bands.
For Market Incumbents: Build certification moats through captive REACH-compliant dye house consolidation in Portugal and Turkey. Defensive moves center on backward integration into biodegradable elastic core production and exclusive micro-influencer affiliate network lock-ups that fragment competitor access to TikTok discovery algorithms. Fast-fashion platform integrators and unbranded direct-from-factory channels represent the primary substitution threats compressing mid-tier margin pools. For New Entrants and Emerging Players: Pursue artisanal velvet positioning in Germany's bridal and occasion-based segments where REACH certification barriers extend incumbent lead times. White-space targets include biodegradable elastic convergence aligned with France and Italy extended producer responsibility mandates, and live commerce integration on TikTok Shop for real-time impulse conversion. Go-to-market execution favors limited-drop pastel collections through boutique channels in Tokyo and Seoul. For Investors and Strategic Acquirers: Direct-to-consumer infrastructure specialists with algorithmic content production capabilities present the highest acquisition value. Long-term viability frames around 5-10 year platform dependency risk as TikTok and Instagram algorithm shifts can collapse brand equity density without warning. The signal to watch is biodegradable elastic cost parity against petroleum-derived synthetics as the inflection indicator for sustainability-premium durability.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Elastic Reformulation | REACH and extended producer responsibility mandates in France and Italy accelerate natural rubber and plant-based polymer substitution timelines. |
| Live Commerce Integration | TikTok Shop and Instagram real-time purchasing collapse discovery-to-transaction friction for impulse-driven teen and young adult segments. |
| Captive Dye House Consolidation | Portugal and Turkey REACH-certified facilities consolidate testing workflows and compress certification delays for EU-bound production. |
| Micro-Influencer Affiliate Networks | Algorithmic distribution on short-form video platforms redirects margin pools from traditional wholesale buyers to platform-native creators. |
| Direct-to-Consumer Infrastructure Buildout | Los Angeles and New York startup clusters leverage proprietary content production teams to sustain viral visibility velocity. |
Study Parameters
Operator-level perspectives from brand managers at direct-to-consumer scrunchie startups, category buyers at fast-fashion retailers, Zhejiang textile cluster production planners, and REACH compliance consultants anchored the qualitative base. Secondary validation drew from US Consumer Product Safety Commission filings, EU ECHA REACH substance registrations, China GB standards documentation, and TikTok Shop merchant disclosure data. Bottom-up unit economics modeling triangulated against top-down category spend estimates from retail audit databases.
Scenario-bracketing around social media algorithm stability and biodegradable elastic cost curves framed the analytical approach across the analysis window. Segmentation dimensions modeled included material type, color tier, customer age cohort, and distribution channel velocity. CAGRs derived from elasticity-adjusted demand curves incorporating platform-native discovery rates and seasonal gifting patterns. Industry-specific inputs encompassed petroleum-derived feedstock price volatility and REACH certification timeline distributions.
Macroeconomic conditions sit as an overlay; deviation in container freight rates, crude oil benchmarks, or short-form video platform regulatory treatment would shift the trajectory. Forecasts embed assumptions around teen consumer platform loyalty and EU extended producer responsibility implementation pace. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fashion & Accessories
North America Handbag Market
Fashion & Accessories
Hair Accessories Market
Fashion & Accessories
Europe Fashion Accessories Market
Fashion & Accessories
Selfie Accessories Market
Fashion & Accessories
North America Lingerie Market
Fashion & Accessories
Decorative Accessories Market
Fashion & Accessories
Couture Millinery Market
Fashion & Accessories
Global Handbags Market
Fashion & Accessories
South America Handbags Market
Fashion & Accessories
Asia Pacific Fashion Accessories Market
Fashion & Accessories
Personal Accessories Market
Fashion & Accessories
Sustainable Fashion Market
Fashion & Accessories
Cufflink Market
Fashion & Accessories
Custom Dog Tags Market
Fashion & Accessories
Middle East and Africa Leather Goods Market
Fashion & Accessories
North America Fashion Accessories Market