
 North America Fashion Accessories Market | 2026-2036
North America Fashion Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
North America Fashion Accessories Market Analytics
Artisan leatherworking and digital design talent scarcity is redrawing competitive boundaries across the North America fashion accessories landscape. Tapestry, Inc. leverages its vertical control over raw material sourcing to secure consistent hide quality for its Coach and Kate Spade divisions. LVMH Moët Hennessy Louis Vuitton SE sustains dominance through Paris-atelier-trained craftsmanship deployed in its California and Texas ateliers. Fossil Group, Inc. competes on watch-and-wearable hybridization, anchoring its North American position in mid-tier metal accessories.
North America fashion accessories encompass wearable adornments and functional items including jewelry, handbags, hats, and scarves, typically manufactured through cut-and-sew assembly, die-cast metal forming, or hand-finished leather tooling with specifications ranging from full-grain vegetable-tanned hides to recycled polyester blends. These products serve commercial purposes spanning personal expression, status signaling, and seasonal wardrobe extension across retail and direct-to-consumer channels. Handbags occupy the largest margin pool within the product type dimension, while unisex customer categories are expanding fastest as gender-fluid styling gains retail floor space. Online retail channels are capturing disproportionate growth, though department stores retain critical brand-discovery functions for heritage leather and metal collections.
The US Federal Trade Commission enforces truth-in-labeling standards that govern leather authenticity claims and country-of-origin disclosures, directly influencing product development cycles and packaging compliance costs. Mexico's Ministry of Economy administers NOM standards for textile and accessory safety, while Health Canada regulates phthalate and heavy-metal content in children's jewelry through its Consumer Product Safety Act. Stakeholders must monitor evolving extended producer responsibility frameworks in California and New York that will mandate accessory take-back programs and recycled-content thresholds.
Market Dynamics
Millennial and Gen Z purchasing power is consolidating demand around sustainable materials and personalized production, forcing legacy manufacturers to reconfigure supply chains toward small-batch, on-demand fulfillment models.
Growth Catalysts
- Extended Producer Responsibility frameworks:California and New York mandates for accessory take-back programs and recycled-content thresholds are accelerating circular economy infrastructure investment across domestic manufacturing.
- US-Mexico-Canada Agreement rules of origin:Leather goods sourcing patterns are reorienting toward tri-national supply base integration, reducing tariff exposure for finished goods.
- Direct-to-consumer incubation clusters:Los Angeles-San Francisco corridor density in celebrity-backed launches and digital-native brand formation is compressing trend-to-shelf cycles.
Market Restraints
- Artisan leatherworking scarcity:Paris-atelier-trained craftsmanship pipelines cannot scale to meet California and Texas atelier expansion plans.
- Hide quality volatility:Full-grain vegetable-tanned hide supply concentrates in specific tannery regions, creating input cost instability for heritage leather collections.
- Truth-in-labeling compliance friction:US Federal Trade Commission enforcement of leather authenticity claims extends product development cycles and elevates packaging compliance expenditures.
Strategic Opportunities
- Gender-fluid styling expansion:Unisex customer categories are capturing disproportionate retail floor space allocation across department store networks.
- Watch-and-wearable hybridization:Mid-tier metal accessories convergence with health-monitoring sensors opens adjacent revenue pools in functional adornment.
- Online retail channel acceleration:Digital-native discovery platforms are supplanting traditional brand-launch pathways while heritage collections retain department store presence for credibility signaling.
Industry Challenges
- Digital design talent acquisition:CAD-to-pattern automation expertise remains concentrated in apparel software hubs, forcing accessories firms to compete outside traditional talent pools.
- NOM standards navigation:Mexico's Ministry of Economy textile and accessory safety certifications require parallel testing protocols, extending cross-border shipment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Fashion Accessories Market |
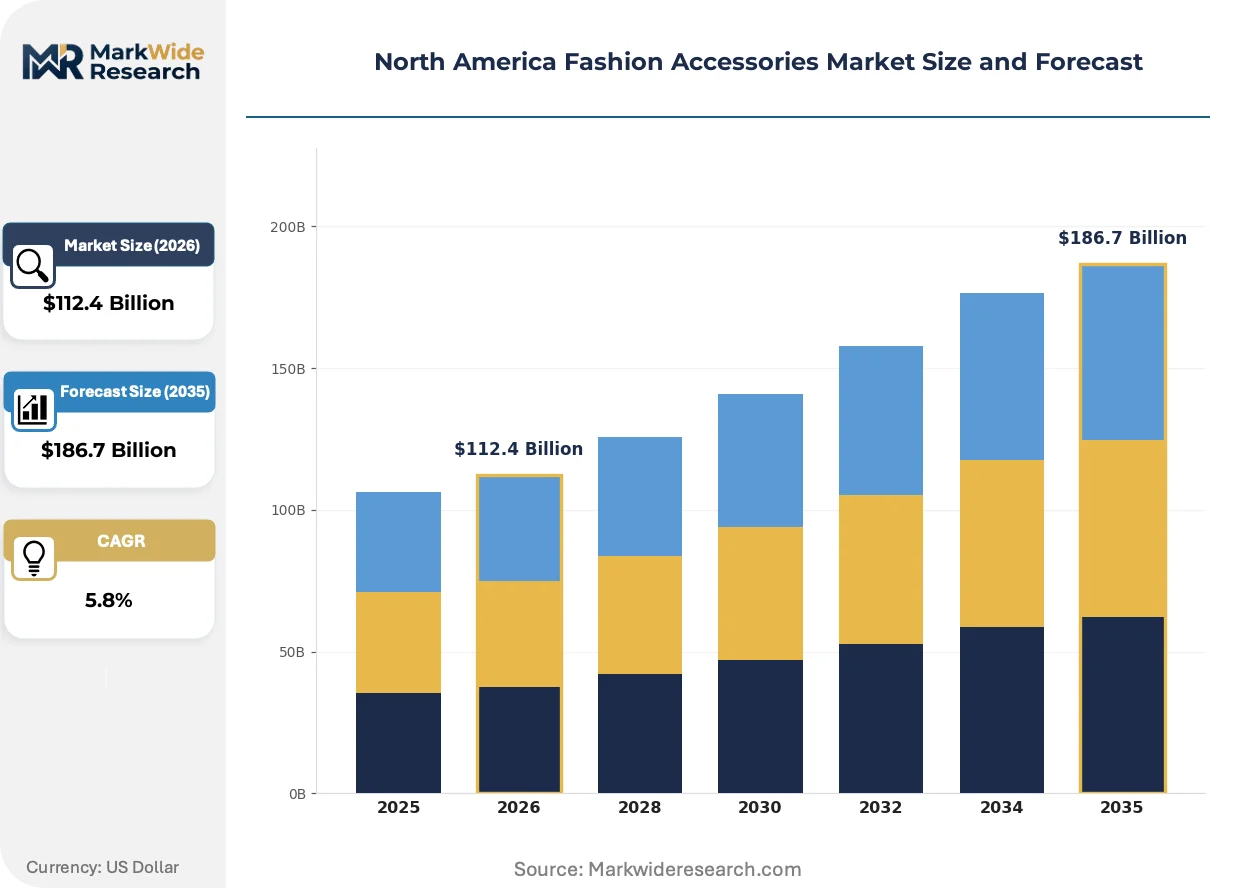
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $186.7 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jewelry, Handbags, Hats, Scarves Material: Leather, Metal, Fabric, Plastic Customer Type: Men, Women, Children, Unisex Distribution Channel: Online Retail, Department Stores, Specialty Stores, Direct Sales |
| Companies Covered | Tapestry, Inc., LVMH Moët Hennessy Louis Vuitton SE, Fossil Group, Inc., Kering S.A., Nike Inc., Adidas AG, Guess Inc., Prada SpA, Capri Holdings Limited, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Fashion Accessories Market Evolving Landscape
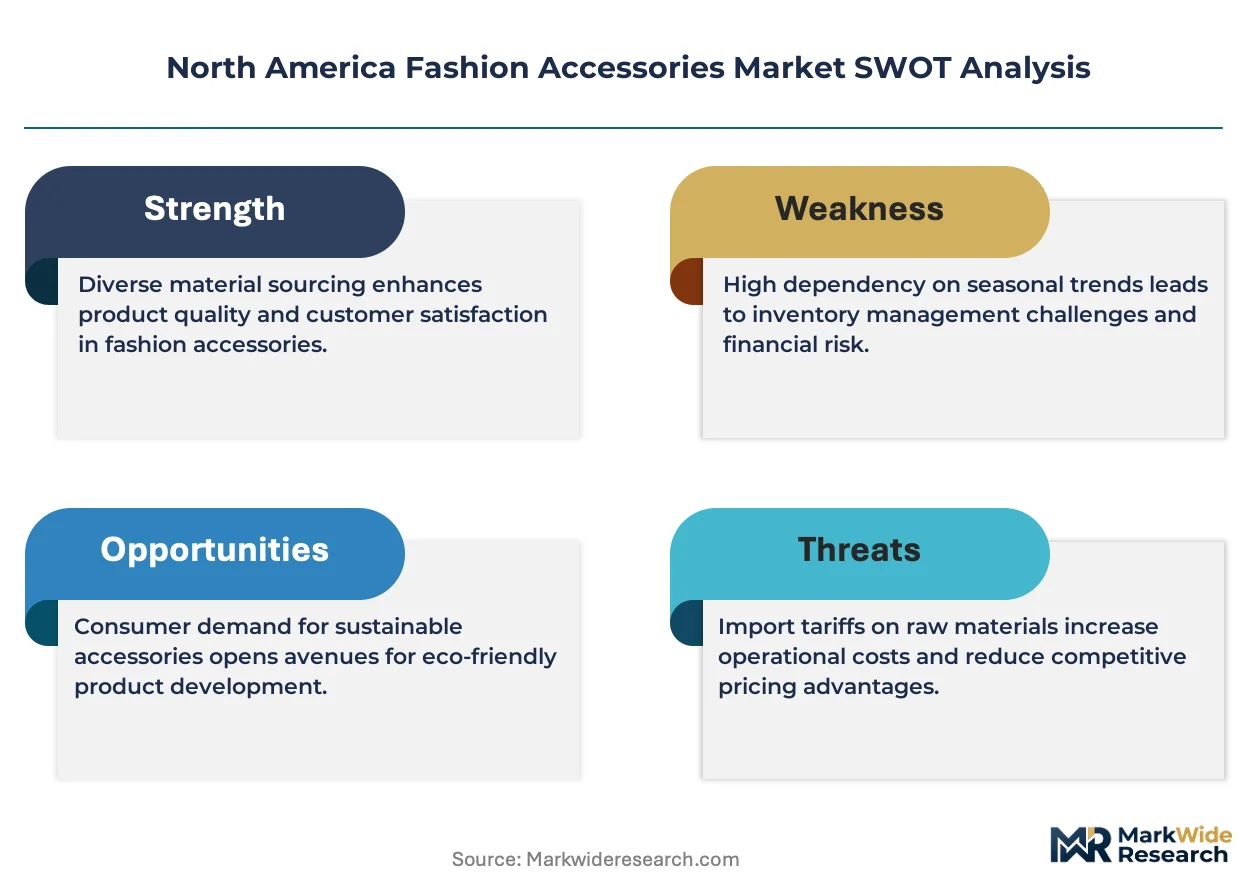
Three interconnected developments are restructuring how accessories move from conception to consumer: materials science advancement, regulatory transparency mandates, and generational purchasing behavior transformation.
Recycled polyester blends are supplanting virgin synthetic inputs across scarf and soft accessory categories. Gen Z-preferred digital-native brands are adopting these materials at twice the rate of heritage houses. This shift is compressing margin structures for petroleum-dependent supply chains while opening premium pricing tiers for closed-loop certified collections.
Health Canada's Consumer Product Safety Act phthalate and heavy-metal restrictions for children's jewelry are tightening testing protocols. Domestic manufacturers are absorbing additional laboratory validation costs. Small-batch children's accessory producers in Ontario and Quebec are consolidating to share compliance infrastructure.
Secondhand authentication services are fragmenting traditional brand-discovery pathways. Resale platforms are capturing value-conscious millennial spend that previously flowed to mid-tier department store entry points. This behavioral pivot concentrates most visibly in California's Los Angeles-San Francisco corridor, where circular fashion infrastructure density supports rapid inventory turnover.
North America Fashion Accessories Market Segmentation
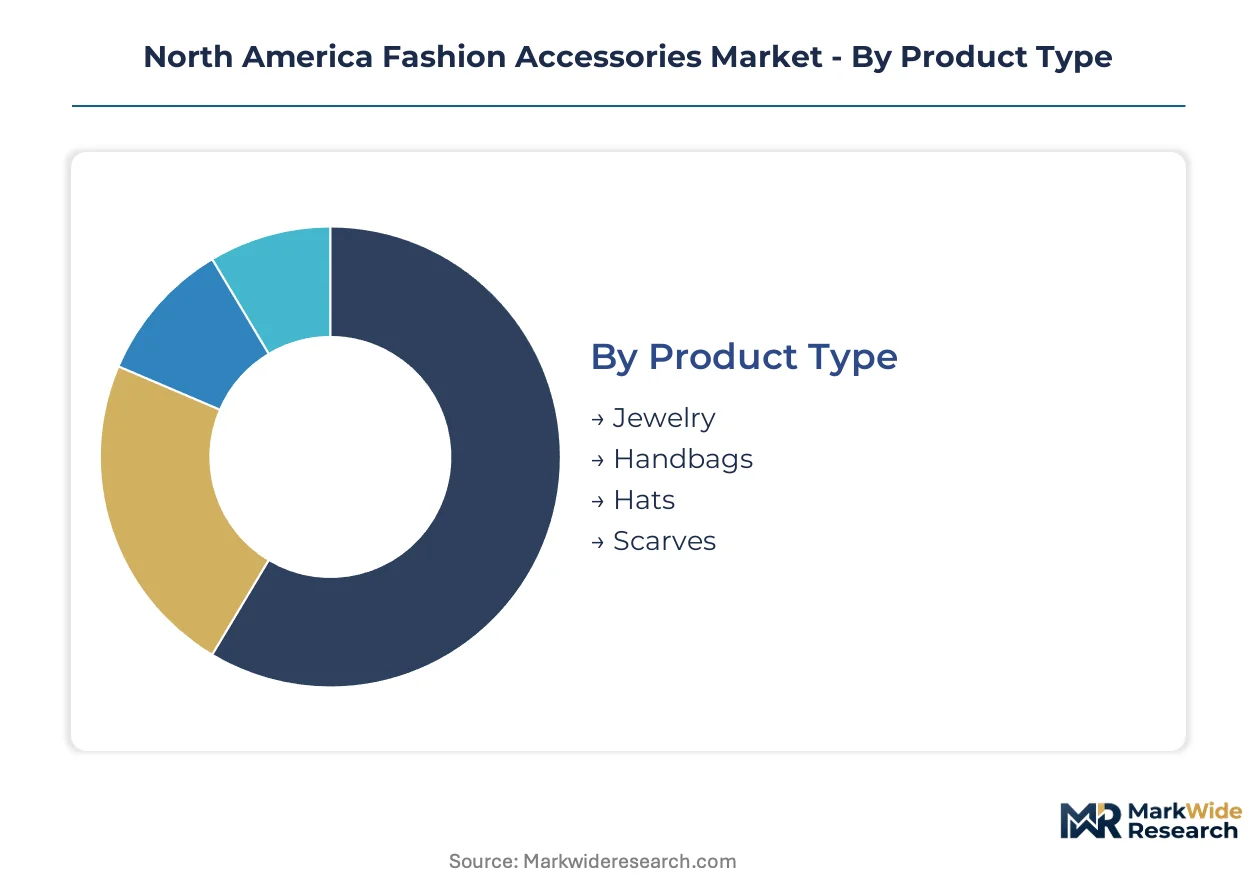
Segmentation in North American fashion accessories reveals divergent margin profiles and channel strategies. Handbags and jewelry concentrate heritage brand investment, while unisex categories and online retail are capturing disproportionate growth velocity.
Product Type:
Channel mix varies sharply by accessory category, with handbags and jewelry dominating department store floor space while hats and scarves flow primarily through digital-native discovery platforms.
- Handbags:Full-grain vegetable-tanned leather and recycled polyester constructions define premium and entry tiers respectively. Demand concentrates in California's Los Angeles-San Francisco corridor, where direct-to-consumer incubation accelerates trend-to-shelf cycles and celebrity-backed launches compress design lead times.
- Jewelry:Die-cast metal forming and hand-finished tooling span mid-tier to luxury positioning, with Health Canada's phthalate and heavy-metal restrictions tightening testing protocols for children's sub-segments. Ontario and Quebec producers are consolidating to share compliance infrastructure.
- Hats:Cut-and-sew assembly of wool, straw, and recycled fiber blends serves seasonal wardrobe extension demand.
- Scarves:Recycled polyester blends are supplanting virgin synthetics, with Gen Z-preferred digital-native brands adopting closed-loop certified materials at twice the rate of heritage houses.
By volume, handbags lead. By growth pace, scarves are climbing the fastest as material science advancement opens premium pricing tiers.
Material:
Cost tier stratification across material inputs determines manufacturing location and margin exposure, with leather commanding captive supply investments and metal driving hybridization R&D.
- Leather:Full-grain vegetable-tanned hides concentrate in specific tannery regions, creating input cost instability. Tapestry, Inc.'s vertical control over raw material sourcing secures consistent hide quality for heritage collections.
- Metal:Die-cast forming and precision machining enable watch-and-wearable hybridization, with Fossil Group, Inc. anchoring North American position in mid-tier functional adornment.
- Fabric:Recycled polyester and organic cotton blends dominate scarf and soft accessory production.
- Plastic:Virgin petroleum-dependent supply chains face margin compression as closed-loop certification requirements expand.
By revenue concentration, leather dominates. By supply chain reconfiguration intensity, fabric is gaining share fastest.
Customer Type:
Application context varies by demographic, with women driving heritage leather discovery and unisex categories capturing expanded retail floor space allocation.
- Women:Heritage brand loyalty and seasonal wardrobe extension demand concentrate in department store channels.
- Unisex:Gender-fluid styling gains retail floor space across department store networks, with California and New York incubators leading design normalization.
- Men:Watch-and-wearable hybridization and leather goods form the core purchase occasions.
- Children:Health Canada Consumer Product Safety Act compliance costs are driving Ontario and Quebec producer consolidation.
By current spend base, women lead. By space allocation expansion, unisex is expanding most quickly.
Distribution Channel:
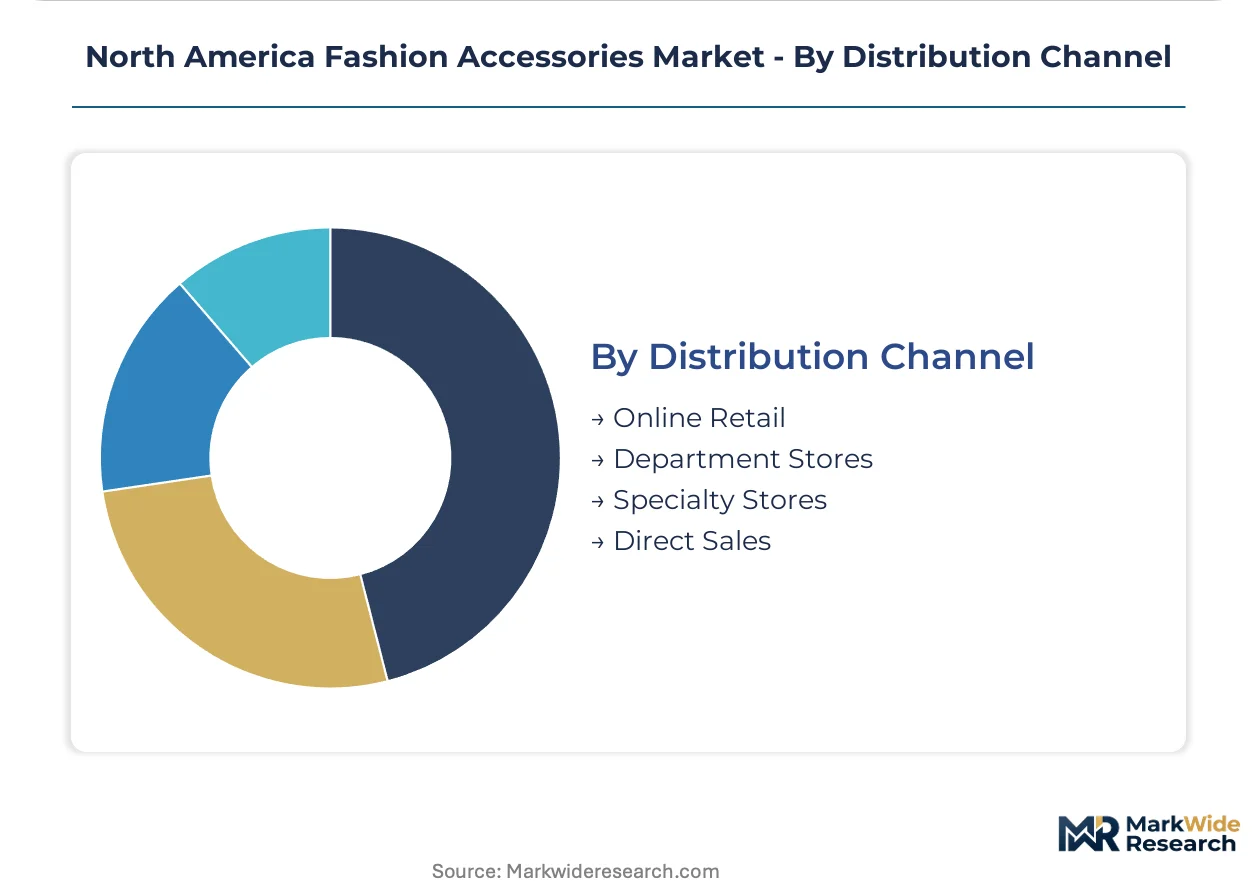
Volume concentration and margin profile diverge across channels, with online retail capturing growth velocity and department stores retaining brand-discovery credibility.
- Online Retail:Digital-native discovery platforms supplant traditional brand-launch pathways, with secondhand authentication services fragmenting traditional discovery and capturing value-conscious millennial spend.
- Department Stores:Critical brand-discovery functions persist for heritage leather and metal collections, though resale platform competition erodes mid-tier entry point traffic.
- Specialty Stores:Curated selection and personalized service support premium positioning for artisan leatherworking and limited editions.
- Direct Sales:Celebrity-backed launches and incubator-driven brand formation concentrate in the Los Angeles-San Francisco corridor.
By transaction volume, online retail leads. By credibility signaling for heritage launches, department stores remain essential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across the tri-national landscape. The United States drives volume through direct-to-consumer velocity, while Mexico and Canada concentrate manufacturing compliance and circular economy infrastructure respectively.
United States
Millennial and Gen Z purchasing power concentrates demand for sustainable materials and personalized production in California's Los Angeles-San Francisco corridor. The FTC enforces truth-in-labeling standards governing leather authenticity claims and country-of-origin disclosures. Celebrity-backed launches and digital-native brand incubation compress trend-to-shelf cycles in this coastal cluster.
Canada
Health Canada regulates phthalate and heavy-metal content in children's jewelry through its Consumer Product Safety Act. Ontario and Quebec producers are consolidating to share compliance infrastructure and laboratory validation costs. Toronto and Montreal anchor circular fashion infrastructure supporting rapid secondhand inventory turnover.
Mexico
The Ministry of Economy administers NOM standards for textile and accessory safety requiring parallel testing protocols. Leather goods sourcing patterns reorient toward tri-national supply base integration under USMCA rules of origin provisions. Guanajuato and Querétaro tannery regions supply full-grain vegetable-tanned hides to heritage collections.
North America Fashion Accessories Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the North America fashion accessories landscape. Tapestry and LVMH maintain vertical control over raw material sourcing and Paris-atelier-trained craftsmanship pipelines respectively. Three archetypes dominate: heritage leather houses, mid-tier metal hybridizers, and digital-native direct-to-consumer incubators. Competitive moves center on supply chain backward integration and celebrity-backed launch partnerships.
Within the heritage leather tier, Tapestry, Inc. and LVMH Moët Hennessy Louis Vuitton SE exemplify divergent sourcing strategies. Tapestry anchors its position through captive supply of consistent hide quality for Coach and Kate Spade divisions. LVMH occupies a position sustained by Paris-atelier-trained craftsmanship deployed in California and Texas ateliers. Fossil Group, Inc. represents the mid-tier metal hybridization archetype, anchoring North American presence in watch-and-wearable convergence.
| Leading Market Players |
|---|
| Tapestry, Inc. |
| LVMH Moët Hennessy Louis Vuitton SE |
| Fossil Group, Inc. |
| Kering S.A. |
| Nike Inc. |
| Adidas AG |
| Guess Inc. |
| Prada SpA |
| Capri Holdings Limited |
| Others |
Value Network & Pricing Analysis
Recycled polyester blends displacing virgin synthetic inputs across scarf and soft accessory categories simultaneously redraws sourcing geography toward certified fiber hubs and compresses margin structures for petroleum-dependent supply chains. This substitution dynamic forces manufacturers to rebalance cost tiers while securing closed-loop certification premiums.
Pricing Analysis
Long-term offtake contracts dominate hide procurement for heritage leather collections, insulating Tapestry and LVMH from spot-market volatility in full-grain vegetable-tanned supply. Three-tier pricing structure across premium, standard, and economy levels separates Paris-atelier-crafted pieces from Texas-trained artisan output and mass-market die-cast alternatives. Cost compression in mid-tier metal accessories is intensifying because Fossil Group's watch-and-wearable hybridization investments reset consumer value expectations. Value-conscious millennials show highest price sensitivity through secondhand authentication platforms, while celebrity-backed direct-to-consumer launches command lowest elasticity.
Supply Chain Analysis
Just-in-time inventory strategies prevail for digital-native brands in California's Los Angeles-San Francisco corridor, whereas heritage houses maintain strategic stockpiles of premium hides in Guanajuato and Querétaro tannery regions. Supply concentration spans Mexico for leather finishing, China for die-cast metal components, and Vietnam for recycled polyester textile processing. The network draws from full-grain hides, precision-machined metal casings, and closed-loop certified synthetic fibers. Single-source vulnerability concentrates in Paris-atelier-trained craftsmanship pipelines unable to scale California and Texas expansion. Distribution runs through tri-national USMCA-integrated logistics with Los Angeles port anchoring Pacific Rim material inflow.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Paris-atelier-trained artisan pipelines cannot satisfy California and Texas atelier expansion, creating a bottleneck that rewards firms securing captive craft capacity or automated CAD-to-pattern alternatives.
For Market Incumbents: Secure backward integration into Guanajuato tannery regions to lock consistent hide quality against input cost volatility threatening heritage leather margins. Invest in California-based digital design talent acquisition before CAD-to-pattern automation expertise concentrates further in apparel software hubs, displacing traditional accessories pattern-making capabilities. For New Entrants and Emerging Players: Differentiate on gender-fluid styling normalization where unisex categories capture disproportionate retail floor space expansion across department store networks. Target Ontario and Quebec children's jewelry consolidation opportunities created by Health Canada compliance cost pressures. Launch through secondhand authentication platforms to capture value-conscious millennial spend fragmenting traditional brand-discovery pathways. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed digital-native incubators in the Los Angeles-San Francisco corridor facing succession and scale challenges. Five-to-ten year viability favors firms with tri-national USMCA supply base integration and closed-loop material certification infrastructure. Watch California extended producer responsibility implementation thresholds as the inflection signal for circular economy infrastructure valuation resets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tannery Operations | Captive hide supply secures margin stability against Guanajuato input cost volatility. |
| CAD-to-Pattern Automation Investment | Digital design talent scarcity in California forces technology-led pattern-making displacement. |
| Closed-Loop Material Certification | Gen Z-preferred brands command premium pricing tiers through recycled polyester adoption. |
| Tri-National Supply Base Reconfiguration | USMCA rules of origin provisions reduce tariff exposure for finished leather goods. |
| Secondhand Authentication Platform Partnership | Resale infrastructure captures value-conscious millennial spend fragmenting department store traffic. |
Research Methodology
Operator-level perspectives from brand managers at heritage leather houses, category buyers at department store networks, supply planners at tri-national logistics providers, and artisan atelier directors anchored the qualitative base. Primary interviews combined with secondary validation from SEC 10-K filings, USMCA customs documentation, Health Canada Consumer Product Safety Act enforcement records, and California extended producer responsibility regulatory drafts. Bottom-up demand modeling and top-down macroeconomic triangulation cross-verified segment-level outputs.
Sensitivity analysis tested forecast robustness across material substitution scenarios, regulatory implementation timelines, and generational purchasing behavior shifts over the projection horizon. Segmentation dimensions modeled include product type, material input tier, customer demographic, and distribution channel complexity alongside craft-capacity utilization rates. CAGRs derived from historical trajectory analysis and forward-looking demand elasticity estimates incorporated recycled-content threshold compliance costs and digital-native brand incubation velocity.
The analysis sits within stated boundaries; outcomes outside USMCA tariff stability, closed-loop certification adoption curves, or Paris-atelier craft pipeline expansion would require recalibration. Forecasts reflect documented assumptions regarding millennial and Gen Z purchasing power consolidation and extended producer responsibility framework implementation. Revision becomes warranted when Health Canada phthalate enforcement intensity or California take-back program mandates cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fashion & Accessories
Global Handbags Market
Fashion & Accessories
Fashion Accessories Market
Fashion & Accessories
North America Handbag Market
Fashion & Accessories
Custom Dog Tags Market
Fashion & Accessories
Hair Scrunchies Market
Fashion & Accessories
Decorative Accessories Market
Fashion & Accessories
Cufflink Market
Fashion & Accessories
Selfie Accessories Market
Fashion & Accessories
Hair Accessories Market
Fashion & Accessories
South America Handbags Market
Fashion & Accessories
Personal Accessories Market
Fashion & Accessories
Europe Fashion Accessories Market
Fashion & Accessories
North America Lingerie Market
Fashion & Accessories
Asia Pacific Fashion Accessories Market
Fashion & Accessories
Couture Millinery Market
Fashion & Accessories
Sustainable Fashion Market