
 South America Handbags Market | 2026-2036
South America Handbags Market Size, Share, and Industry Trends Forecast 2026-2036
South America Handbags Market Analytics
INMETRO certification for synthetic leather labeling is bifurcating the competitive landscape between compliant manufacturers and informal producers. Arezzo COAREZZO INDUSTRIA E COMERCIO SA anchors its position through integrated Brazilian manufacturing and deep retail penetration. LVMH Moet Hennessy Louis Vuitton competes via controlled flagship distribution in São Paulo and Buenos Aires luxury corridors. Kering SA differentiates through sustainability-linked sourcing protocols that resonate with younger South American consumers.
A handbag constitutes a portable container constructed with specified dimensions, closure mechanisms, and strap configurations, typically employing stitched leather, woven canvas, or bonded synthetic substrates to secure personal items during transit. The primary commercial purpose centers on fashion-aligned utility for daily mobility and status signaling across social and professional contexts. Shoulder bags occupy the dominant volume position across South American retail channels, while leather materials command the strongest margin pool due to durability premiums and artisan heritage associations. Online distribution channels represent the fastest-growing structural segment, though specialty shops retain disproportionate influence over premium brand discovery and trial.
ANVISA oversight of chemical treatments in synthetic materials and Argentina's consumer protection framework on product labeling collectively elevate compliance costs for imported and domestically produced goods. Brazil's INMETRO standards and regional customs harmonization under Mercosur technical regulations further condition market access requirements for handbags entering South American trade corridors. Stakeholders must monitor evolving traceability mandates and digital tax regimes affecting cross-border e-commerce fulfillment.
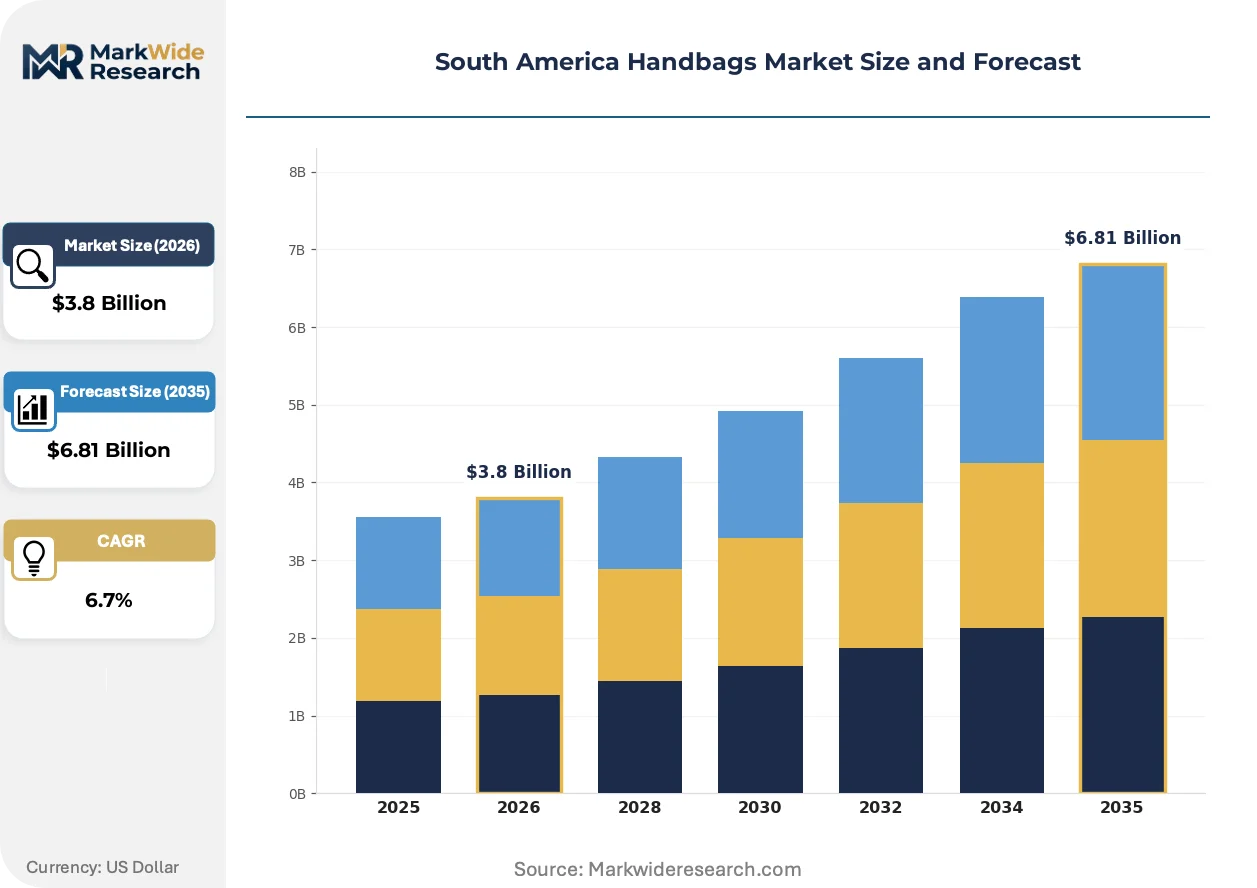
Market Dynamics
INMETRO certification requirements for synthetic leather labeling are restructuring competitive positioning across Brazilian manufacturing, forcing facility upgrades and supplier audits while creating compliance-based segmentation between formal and informal production networks.
Growth Catalysts
- Urban Professional Demand:Working women in São Paulo and Buenos Aires drive structured leather tote adoption through daily commuting and status-conscious workplace accessorizing.
- Mercosur Harmonization:Regional customs technical regulations streamline cross-border trade corridors, reducing documentation friction for handbags moving between Brazil, Argentina, and Uruguay.
- Artisan Heritage Positioning:Leather materials command durability premiums through associations with traditional craftsmanship and generational repairability.
Market Restraints
- Argentine Import Friction:Consumer protection frameworks on product labeling create extended clearance timelines for goods entering Buenos Aires retail channels.
- Synthetic Input Volatility:Petrochemical-derived substrates face price instability tied to international oil benchmark fluctuations and currency hedging costs.
- Southeast Brazil Concentration:Production gravity centers on Rio de Janeiro fashion corridors, exposing distribution networks to localized logistics disruptions.
Strategic Opportunities
- Colombian Channel Expansion:Underpenetrated Andean retail markets present whitespace for specialty shop formats targeting Bogotá and Medellín professional segments.
- Digital Tax Adaptation:Evolving cross-border e-commerce fulfillment regimes create first-mover advantage for platforms optimizing customs pre-clearance.
- Sustainability Protocol Convergence:Traceability mandates from European buyers are accelerating adoption of blockchain-linked supply chain documentation among export-oriented tanneries.
Industry Challenges
- Skilled Stitching Labor Scarcity:Traditional leatherworking craft transmission gaps in São Paulo industrial zones constrain artisan-grade production scaling.
- ANVISA Chemical Compliance Timelines:Extended approval cycles for synthetic material treatments delay product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Handbags Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shoulder Bags, Tote Bags, Clutches, Backpacks Material: Leather, Canvas, Synthetic, Hemp End User: Women, Men, Children, Unisex Distribution Channel: Online, Retail Stores, Specialty Shops, Department Stores |
| Companies Covered | Michael Kors (USA), Inc., Arezzo COAREZZO INDUSTRIA E COMERCIO SA, LVMH Moet Hennessy Louis Vuitton, Hermes International SA, Capri Holdings Ltd, Kering SA, Tory Burch LLC, Ryzí, Prada Holding SpA, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Handbags Market Evolving Landscape
Digital-native distribution models are compressing traditional retail hierarchies while regulatory transparency mandates and material science advances reshape product development cycles across Andean and Southern Cone markets.
Plant-based leather alternatives derived from cactus and pineapple fibers are fragmenting material sourcing strategies among mid-tier Brazilian manufacturers. São Paulo-based design houses pilot these substrates for capsule collections targeting environmentally credential-seeking professionals. The technology is fragmenting established supplier relationships as tanneries face displacement from conventional hide procurement networks.
Brazil's INMETRO synthetic labeling standards mandate disclosure of polyurethane and polyvinyl chloride composition percentages on all retail packaging. Domestic manufacturers have absorbed compliance costs through facility certification and laboratory testing partnerships. Imported goods face elevated rejection rates at port inspection points, advantaging locally certified production.
Social commerce platforms integrated with WhatsApp Business API are displacing traditional department store discovery for handbag purchases in Buenos Aires and Santiago. Younger consumers complete transactions through conversational interfaces rather than branded e-commerce portals. Chilean cross-border shoppers demonstrate the strongest platform adoption, leveraging favorable exchange rate arbitrage for Brazilian-sourced goods.
South America Handbags Market Segmentation
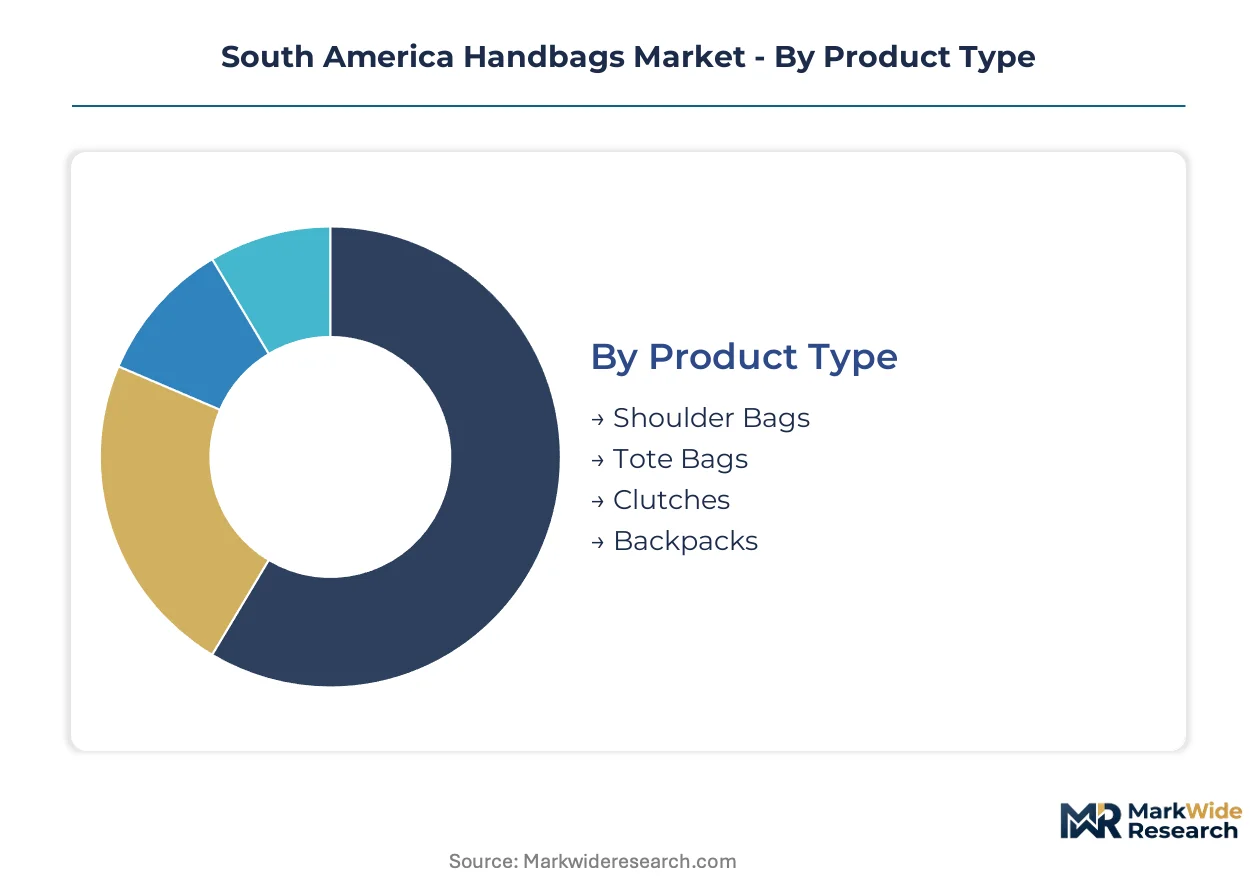
Segmentation reveals how Brazilian INMETRO certification and Argentine import protocols reshape competitive boundaries across product tiers. Distinct material and channel strategies separate compliant formal producers from informal networks in São Paulo and Buenos Aires corridors.
Product Type:
Shoulder bags face the strongest substitution pressure from crossbody variants and belt bags among younger São Paulo professionals seeking hands-free commuting solutions.
- Shoulder Bags:These feature single or dual straps designed for over-shoulder carry with typical dimensions of 25-35cm width. Demand concentrates among working women in São Paulo's financial district who require structured silhouettes for daily office accessorizing, though commuter rail congestion limits bulky designs.
- Tote Bags:Open-top rectangular containers with parallel handles and reinforced base panels. Buenos Aires professional segments drive adoption for laptop transport and document storage, with leather variants commanding durability premiums in Recoleta retail corridors.
- Clutches:Compact envelope or box-structured evening accessories lacking shoulder straps. Rio de Janeiro hospitality workers and event attendees form the core demand cluster.
- Backpacks:Dual-strap designs with weight-distributed frames targeting students and bicycle commuters in Bogotá and Medellín urban cores.
Shoulder bags anchor the volume base while tote bags gain share at the steepest rate among professional segments prioritizing laptop capacity.
Material:
Cost tier stratification separates artisan-grade leather from commodity synthetics, with certification compliance costs widening the gap between formal and informal production networks.
- Leather:Full-grain and top-grain hides from Brazilian and Argentine tanneries provide structural integrity and patina development. São Paulo design houses source from Minas Gerais heritage tanneries, though skilled stitching labor scarcity constrains artisan-grade scaling.
- Synthetic:Polyurethane and polyvinyl chloride substrates formed through casting or coating processes. INMETRO labeling mandates force facility upgrades among domestic manufacturers while informal imports face elevated port rejection rates.
- Canvas:Woven cotton or linen fabrics treated for water resistance. Colombian outdoor and travel segments show rising preference for lightweight durability.
- Hemp:Bast fiber from cannabis sativa stalks processed into coarse-weave textiles. Brazilian sustainability-focused capsules pilot this substrate for environmental credential positioning.
Leather dominates margin pools while synthetic materials expand most quickly among price-sensitive mass-market segments navigating certification barriers.
End User:
Application-driven demand concentration in professional accessorizing shapes product development priorities across São Paulo and Buenos Aires corridors.
- Women:The primary volume driver spanning structured totes for workplace use, evening clutches for hospitality settings, and crossbody variants for retail and transit contexts. Brazilian Southeast region concentration exposes this segment to localized logistics disruptions.
- Men:Messenger bags, briefcases, and minimalist backpacks targeting corporate and creative professional segments. Buenos Aires shows stronger relative penetration than São Paulo due to European-influenced workplace dress codes.
- Children:Scaled-down backpacks and novelty-shaped shoulder bags for school and recreational use. Seasonal demand spikes align with academic calendar cycles.
- Unisex:Neutral silhouettes and colorways designed for shared household use or resale flexibility. Online channels drive discovery for this emerging positioning.
Women's segments anchor the volume base while unisex positioning gains share at the steepest rate among digital-native younger consumers.
Distribution Channel:
Supply concentration in Rio de Janeiro fashion corridors and São Paulo industrial zones dictates fulfillment architecture and last-mile economics.
- Online:Digital-native platforms and brand-direct e-commerce with WhatsApp Business API integration displacing traditional discovery in Buenos Aires and Santiago. Chilean cross-border shoppers leverage exchange rate arbitrage for Brazilian-sourced goods.
- Retail Stores:Multi-brand boutiques and chain outlets in high-footfall districts. Argentine consumer protection frameworks on product labeling create extended clearance timelines for imported inventory.
- Specialty Shops:Curated single-brand or artisan-focused stores retaining disproportionate influence over premium brand discovery and trial. Underpenetrated Andean markets present whitespace for Bogotá and Medellín expansion.
- Department Stores:Large-format retail anchors in São Paulo and Rio de Janeiro luxury corridors. LVMH and Kering compete via controlled flagship distribution within these formats.
Specialty shops anchor the volume base while online channels gain share at the steepest rate as social commerce platforms compress traditional retail hierarchies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Santos container terminals anchor Brazil's handbag export infrastructure, handling bonded warehousing for finished leather goods destined for Mercosur trade corridors and transatlantic routes to Europe.
Brazil
Urban working women in São Paulo's financial district drive structured leather tote adoption for daily commuting. INMETRO certification requirements for synthetic material labeling force facility upgrades among domestic manufacturers while informal imports face elevated port rejection rates. Production gravity concentrates in Rio de Janeiro fashion retail corridors and São Paulo industrial zones.
Argentina
Buenos Aires professional segments prioritize open-top tote bags for laptop transport and document storage in Recoleta retail corridors. The country's consumer protection framework on product labeling creates extended clearance timelines for imported inventory. Local design houses source from domestic tanneries while navigating currency hedging costs for petrochemical-derived synthetic inputs.
Chile
Santiago-based younger consumers complete handbag transactions through WhatsApp Business API-integrated social commerce platforms rather than branded e-commerce portals. Chilean cross-border shoppers demonstrate the strongest platform adoption, leveraging favorable exchange rate arbitrage for Brazilian-sourced goods. Last-mile fulfillment networks concentrate in the Santiago Metropolitan Region.
Colombia
Bogotá and Medellín professional segments present whitespace for specialty shop format expansion targeting structured work bags. Colombian outdoor and travel segments show rising preference for lightweight canvas variants treated for water resistance. Andean retail markets remain underpenetrated relative to Southern Cone corridors.
Uruguay
Montevideo's Mercosur-aligned customs technical regulations streamline cross-border trade documentation for handbags moving between Brazil and Argentina. The country's leatherworking heritage supports artisan-grade production for regional export. Distribution networks leverage the Colonia Free Trade Zone for bonded transit operations.
South America Handbags Market Competitive Landscape
Listed leaders compete with private specialists across certification compliance and retail channel control, creating a tiered structure where formal networks separate from informal production. Brazilian integrated manufacturers anchor mid-market positioning through captive tannery relationships and multi-format retail penetration. Three archetypes dominate: heritage luxury houses with controlled flagship distribution, vertically integrated domestic producers with deep regional retail networks, and digital-native specialists leveraging social commerce platforms. Competitive moves center on sustainability-linked sourcing protocol adoption and cross-border e-commerce fulfillment optimization.
Within the heritage luxury tier, LVMH Moet Hennessy Louis Vuitton and Hermes International SA occupy positions defined by controlled scarcity and flagship corridor presence in São Paulo and Buenos Aires. Arezzo COAREZZO INDUSTRIA E COMERCIO SA exemplifies the vertically integrated domestic archetype with Brazilian manufacturing and retail penetration. Kering SA sits within the sustainability-vector segment, representing traceability-linked sourcing protocols that resonate with younger South American consumers.
| Leading Market Players |
|---|
| Michael Kors (USA), Inc. |
| Arezzo COAREZZO INDUSTRIA E COMERCIO SA |
| LVMH Moet Hennessy Louis Vuitton |
| Hermes International SA |
| Capri Holdings Ltd |
| Kering SA |
| Tory Burch LLC |
| Ryzí |
| Prada Holding SpA |
| Others |
Value Network & Pricing Analysis
Plant-based leather alternatives displacing conventional hides from Minas Gerais tanneries are redrawing procurement geography toward Brazilian cactus fiber cultivators while compressing margin structures for heritage leather suppliers locked into multi-year hide contracts.
Pricing Analysis
Certification level under INMETRO standards creates the primary spread between formal and informal production tiers. Pricing stratifies across artisan-grade leather, certified synthetics, and uncertified imports based on traceability documentation and laboratory testing costs. Cost compression in uncertified synthetics is intensifying because port rejection rates advantage compliant domestic manufacturers. Mass-market segments show highest price sensitivity while heritage luxury buyers absorb durability premiums without volume trade-offs.
Supply Chain Analysis
Inventory lead times for ANVISA-compliant chemical treatments extend product launch cycles by 8-14 months, forcing manufacturers to pre-position speculative stock. Supply concentrates in Brazil, Argentina, and Uruguay with raw material dependencies on Minas Gerais tanneries, petrochemical-derived polyurethane substrates, and Colombian canvas weavers. Single-source vulnerability in skilled stitching labor constrains artisan-grade scaling. Distribution runs through Rio de Janeiro fashion corridors and São Paulo industrial zones with bonded warehousing at Port of Santos.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Repair and restoration services represent a service-attach opportunity expanding faster than hardware sales as São Paulo professionals seek generational durability from heritage leather acquisitions.
For Market Incumbents: Compound market position through backward integration into captive tannery relationships and certification investment against ANVISA compliance timelines. Threat from digital-native entrants leveraging WhatsApp Business API commerce demands channel control reinforcement through specialty shop format expansion in underpenetrated Andean corridors. For New Entrants and Emerging Players: Anchor in Colombian whitespace targeting Bogotá and Medellín professional segments with structured work bags. The most penetrable geography remains the Andean retail corridor where specialty shop density lags Southern Cone benchmarks. Go-to-market execution should prioritize social commerce platform integration over traditional department store placement. For Investors and Strategic Acquirers: The market sits at a compliance-consolidation phase that favors vertically integrated domestic manufacturers with INMETRO certification and multi-format retail penetration. Long-term viability over the next decade hinges on traceability protocol adoption and blockchain-linked supply chain documentation. The signal to watch is cross-border e-commerce fulfillment optimization as digital tax regimes mature.| Strategic Initiative | Industry Significance |
|---|---|
| INMETRO Certification Investment | Facility upgrades and laboratory partnerships secure port clearance advantages against informal imports. |
| Specialty Shop Format Expansion | Curated retail presence in Bogotá and Medellín captures whitespace in underpenetrated Andean professional segments. |
| Blockchain Traceability Implementation | Supply chain documentation meets European buyer mandates and resonates with younger South American consumers. |
| WhatsApp Business API Integration | Conversational commerce platforms displace traditional discovery in Buenos Aires and Santiago younger segments. |
| Plant-Based Material Pilot Programs | Cactus and pineapple fiber capsules target environmental credential-seeking professionals in São Paulo design houses. |
Research Methodology
Operator-level perspectives from tannery operations managers, retail category buyers at São Paulo department stores, ANVISA regulatory affairs specialists, and logistics coordinators at Port of Santos anchored the qualitative base. Secondary validation drew from INMETRO certification registries, Mercosur customs documentation, Brazilian customs trade statistics, and ANVISA chemical approval databases. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Sensitivity analysis tested forecast outputs against alternative scenarios for petrochemical price volatility and currency hedging cost fluctuations. The modeling framework segmented by product type, material grade, end-user demographic, and distribution channel across the projection horizon. CAGRs derived from historical trajectory analysis and forward-looking regulatory impact assessment. Industry-specific inputs included skilled labor availability indices and cross-border e-commerce penetration rates.
Decision-makers should treat outputs as directional under assumptions of sustained Mercosur customs harmonization and stable ANVISA approval timelines; material deviation in regulatory processing speed or petrochemical benchmark volatility would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fashion & Accessories
Decorative Accessories Market
Fashion & Accessories
Sustainable Fashion Market
Fashion & Accessories
Europe Fashion Accessories Market
Fashion & Accessories
Middle East and Africa Leather Goods Market
Fashion & Accessories
Cufflink Market
Fashion & Accessories
Personal Accessories Market
Fashion & Accessories
Fashion Accessories Market
Fashion & Accessories
Hair Scrunchies Market
Fashion & Accessories
North America Lingerie Market
Fashion & Accessories
Custom Dog Tags Market
Fashion & Accessories
Global Handbags Market
Fashion & Accessories
Hair Accessories Market
Fashion & Accessories
North America Fashion Accessories Market
Fashion & Accessories
Asia Pacific Fashion Accessories Market
Fashion & Accessories
Selfie Accessories Market
Fashion & Accessories
Couture Millinery Market