
 Asia Pacific Fashion Accessories Market | 2026-2036
Asia Pacific Fashion Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Fashion Accessories Market Outlook
Artisan craft labor pools across Vietnam and Bangladesh is rotating toward mechanized production, easing capacity bottlenecks for mid-tier accessories. Titan Company Limited anchors its position through captive jewelry manufacturing in South India. LVMH Moët Hennessy Louis Vuitton SE leverages exclusive leather sourcing relationships to sustain pricing power. Kering SA specializes in artisan-led small-batch production for its luxury houses.
Asia Pacific fashion accessories encompass wearable adornments including jewelry, bags, belts, and scarves, typically manufactured through die-casting, hand-assembly, stitching, and surface finishing processes using leather, metal, fabric, or plastic substrates. These items serve both functional purposes and identity signaling for consumers across demographic segments. Jewelry and bags command the dominant share of value pools, with leather material grades capturing the highest margin concentration. Online distribution channels are expanding fastest, though retail stores and boutiques continue to control premium customer access.
India's BIS hallmarking regulations, China's GB standards for metal content and product safety, and Japan's JIS quality frameworks collectively shape material compliance costs and market entry requirements across the region. Regulatory divergence between these regimes forces multi-country operators to maintain parallel testing and certification workflows. Stakeholders must monitor evolving ESG disclosure obligations under India's emerging sustainability rules and China's dual carbon goals to anticipate sourcing and reporting investments.
Market Dynamics
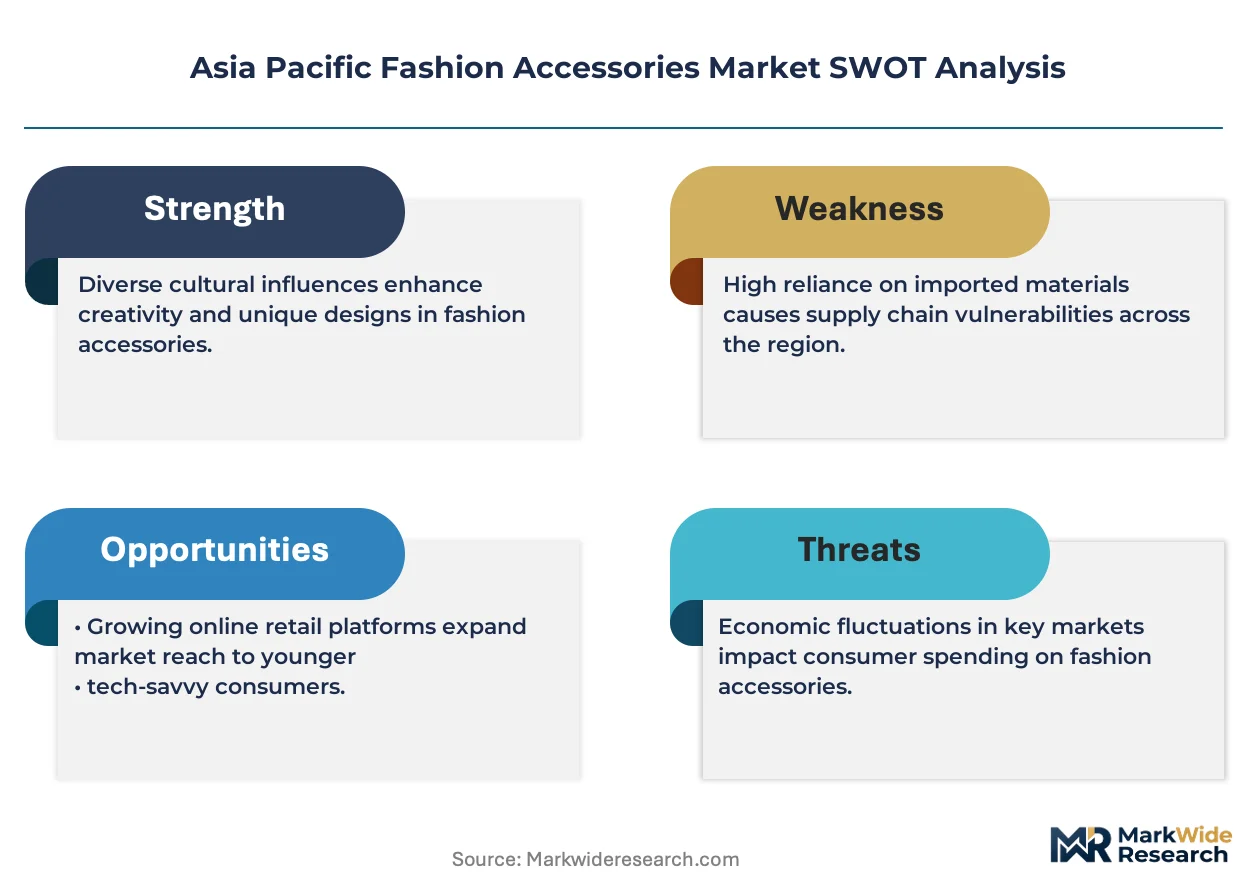
China's evolving GB standards for metal content and India's BIS jewelry hallmarking mandate are compressing supplier margins while forcing parallel certification workflows across the Asia Pacific fashion accessories supply chain.
Growth Catalysts
- BIS Hallmarking Mandate:India's mandatory precious metal certification is consolidating fragmented jewelry suppliers into organized channels, expanding addressable market reach for compliant manufacturers.
- Young Professional Demand:Metropolitan centers in India and China are expanding purchases of statement jewelry and premium bags as disposable incomes rise in tier-one cities.
- Mechanized Production Transition:Artisan craft labor pools across Vietnam and Bangladesh are rotating toward automated stitching and die-casting, easing capacity bottlenecks for mid-tier accessories.
Market Restraints
- Regulatory Divergence Costs:Parallel testing workflows for India's BIS, China's GB standards, and Japan's JIS frameworks inflate compliance overhead for multi-country operators.
- Leather Input Volatility:Exclusive sourcing relationships for premium hides concentrate pricing power among a limited supplier base in Southeast Asian tanneries.
- Substitution Threat from Synthetic Materials:Plant-based leather alternatives and recycled polymers are displacing conventional substrates in mass-market bags and belts.
Strategic Opportunities
- Underpenetrated Tier-Two India:India's tier-two cities remain underserved for branded accessories, presenting whitespace for organized retailers with localized pricing.
- Online Channel Expansion:E-commerce platforms are capturing the fastest-growing distribution share, enabling direct-to-consumer access without boutique infrastructure.
- China's Dual Carbon Goals:Beijing's emissions reduction mandates are creating preferential procurement terms for accessories manufacturers with verified low-carbon leather processing.
Industry Challenges
- Artisan Skill Attrition:Traditional hand-assembly expertise in Vietnam and Bangladesh is eroding as younger workers migrate to mechanized factory roles.
- ESG Disclosure Timeline Pressure:India's emerging sustainability rules and China's evolving carbon reporting standards are forcing accelerated data infrastructure investments.
- Multi-Standard Certification Delays:Staggered approval timelines across BIS, GB, and JIS regimes extend product launch cycles for cross-border collections.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Fashion Accessories Market |
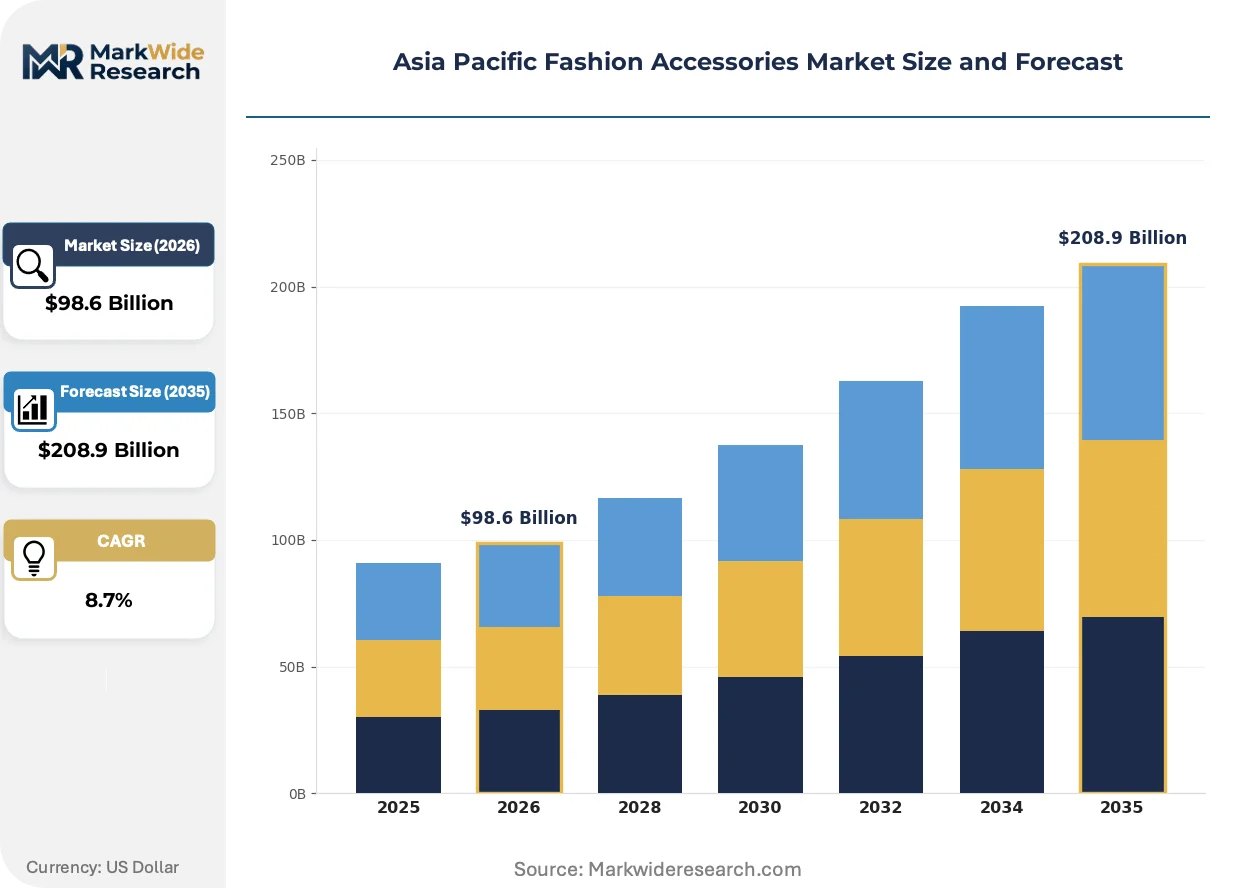
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $208.9 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jewelry, Bags, Belts, Scarves Material: Leather, Metal, Fabric, Plastic Customer Type: Adults, Teens, Children, Seniors Distribution Channel: Online, Retail Stores, Boutiques, Wholesalers |
| Companies Covered | Titan Company Limited, LVMH Moët Hennessy Louis Vuitton SE, Kering SA, Hermès International, Nike Inc., Adidas AG, Puma SE, Industria de Diseno Textil S.A. (Inditex S.A.), Li-Ning Company Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Fashion Accessories Market Strategic Shifts
Digital traceability systems and automated surface finishing are compressing traditional craftsmanship timelines while regulatory pressure on material provenance intensifies across the Asia Pacific accessories value chain.
Laser-based personalization technology is bifurcating the jewelry segment. High-volume manufacturers in China's coastal clusters are adopting fiber laser marking systems for mass customization of metal substrates. This capability is enabling real-time engraving services in retail environments while compressing margins for traditional hand-engraving artisans.
China's GB standards for metal content and product safety are tightening disclosure requirements for alloy composition in costume jewelry. Manufacturers must now submit batch-level testing documentation to SAMR-approved laboratories before market release. Small-batch artisan producers in South India are responding by consolidating production runs to amortize certification costs across larger volumes.
Young professionals in metropolitan India and China are compressing replacement cycles for statement accessories, treating bags and jewelry as seasonal wardrobe components rather than durable investments. Fast-fashion platforms and social commerce channels are displacing traditional boutique discovery for this demographic. This behavioral shift is most visible in Mumbai, Bangalore, and Shanghai, where rental and resale platforms are capturing incremental wallet share from primary purchases.
Asia Pacific Fashion Accessories Market Segmentation
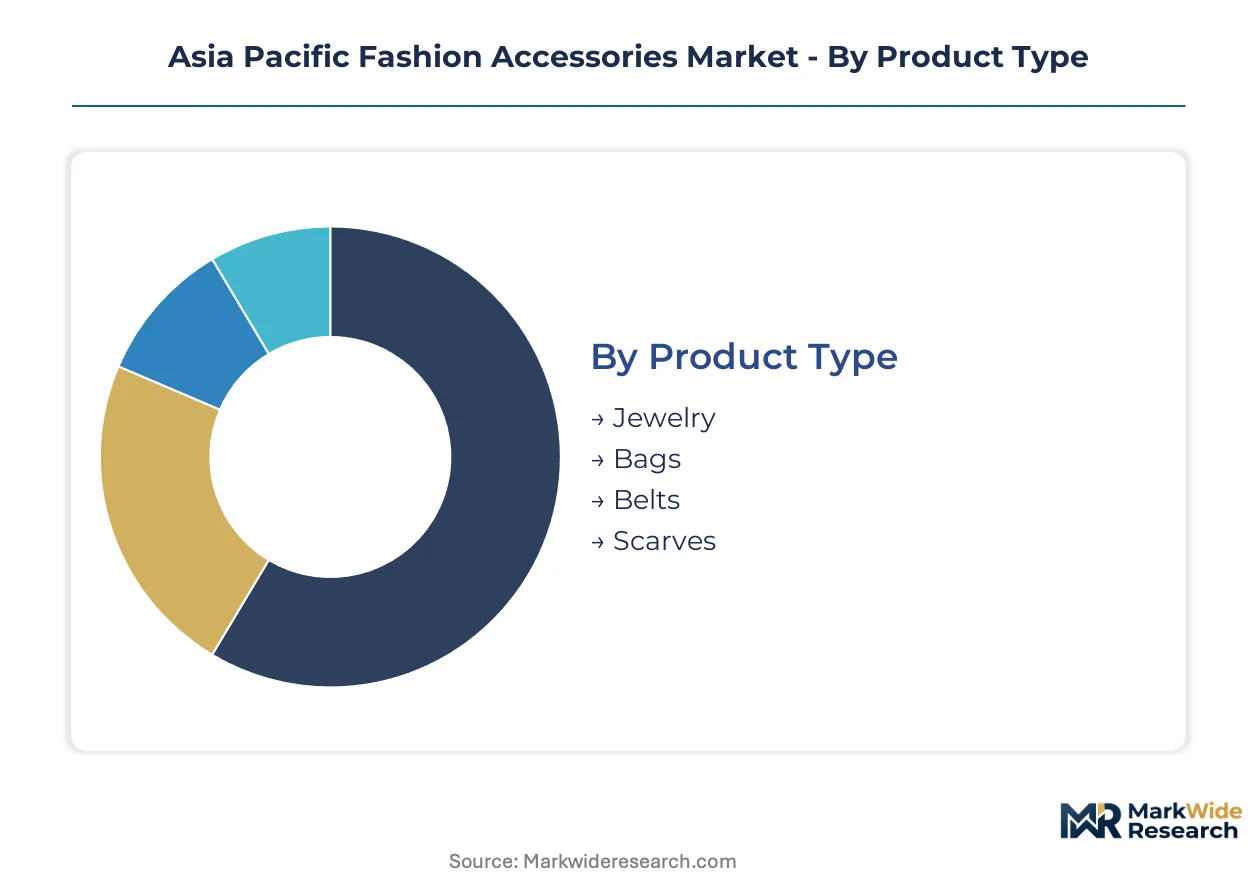
Segmentation in Asia Pacific fashion accessories reveals divergent growth vectors across material grades and channel economics. Product mix and customer demographics stratify sharply between India's organized retail corridors and China's export-oriented manufacturing clusters.
Product Type:
Jewelry production concentrates in India's BIS-certified organized channels for domestic consumption, while bags manufacturing skews toward China's coastal export zones serving international brands.
- Jewelry:Precious and costume metal adornments manufactured through die-casting, stone setting, and surface finishing processes. Demand clusters in Mumbai, Bangalore, and Delhi's tier-one retail corridors where BIS hallmarking compliance enables organized retail penetration. India's mandatory certification regime is consolidating fragmented suppliers into traceable supply chains.
- Bags:Carried containers constructed from leather, fabric, or synthetic substrates via stitching and hardware assembly. China's Guangdong and Zhejiang provinces anchor export-volume production for premium European houses, while domestic demand concentrates in Shanghai and Beijing's luxury retail footprints.
- Belts:Waist-worn straps combining leather or fabric substrates with metal buckles, serving functional and aesthetic purposes across formal and casual applications.
- Scarves:Fabric neck and head coverings produced through weaving, printing, and finishing processes, with silk grades commanding premium positioning in Japan's mature accessory market.
Jewelry commands the established base. The steepest expansion runs through bags.
Material:
Cost tiers separate premium hide grades from mass-market synthetics, with compliance burdens varying sharply across metal content regulations.
- Leather:Processed animal hides graded by tannage quality and surface finish, sourced predominantly from Southeast Asian tanneries. Exclusive supply relationships concentrate pricing power among Vietnamese and Bangladeshi processors serving LVMH and Kering's luxury houses. China's dual carbon goals are pressuring tanneries to verify low-carbon processing credentials.
- Metal:Alloy-based substrates for jewelry and hardware subject to China's GB standards for metal content and India's BIS hallmarking mandates. Batch-level testing documentation to SAMR-approved laboratories extends certification timelines for small-batch artisan producers in South India.
- Fabric:Woven textile substrates spanning silk, cotton, and synthetic blends for scarves and bag linings, with regional specialization in India's Varanasi silk clusters.
- Plastic:Molded polymer components and synthetic leather alternatives displacing conventional substrates in mass-market belts and casual bags.
Leather anchors value concentration. Synthetic alternatives are climbing the fastest as plant-based substitutes penetrate mid-tier positioning.
Customer Type:
Volume distribution reflects demographic purchasing power gradients across metropolitan India's young professional cohort and Japan's aging accessory consumer base.
- Adults:Working-age consumers aged 25-55 driving premium bag and statement jewelry replacement cycles. Mumbai and Shanghai professionals treat accessories as seasonal wardrobe components, compressing purchase intervals and expanding fast-fashion platform penetration.
- Teens:Style-conscious younger consumers prioritizing trend-responsive, lower-unit-price accessories through social commerce discovery channels.
- Children:Functional and occasion-driven purchases concentrated in gifting occasions and school-year cycles.
- Seniors:Quality-prioritizing demographic in Japan's mature market, sustaining demand for traditional craft techniques and durable investment-grade pieces.
Adults dominate current revenue contribution. Teen engagement through digital channels shows the steepest upward trajectory.
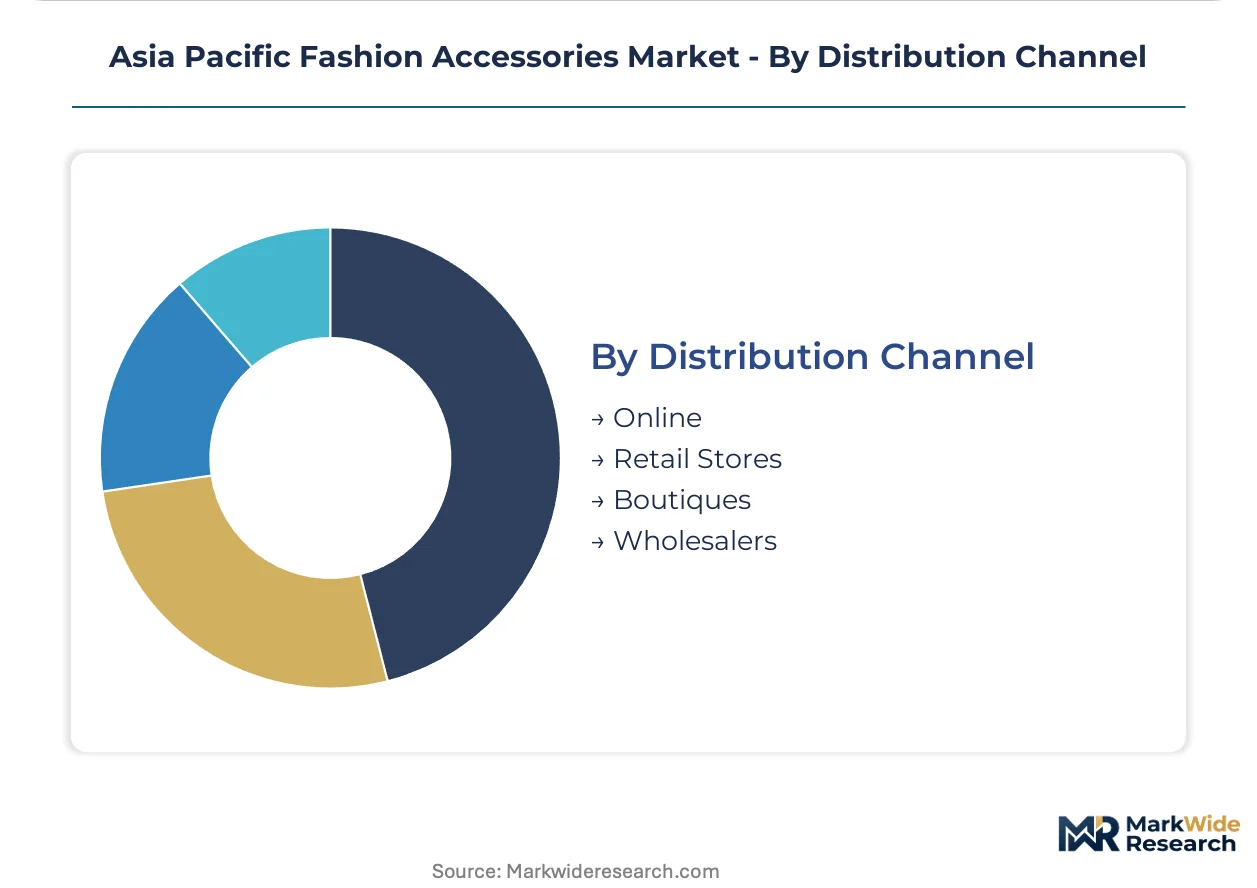
Distribution Channel:
Channel economics bifurcate between asset-light digital expansion and fixed-cost boutique infrastructure for premium customer access.
- Online:E-commerce platforms and social commerce channels capturing wallet share from primary purchases through algorithmic discovery and convenience positioning. Fastest-growing distribution share enables direct-to-consumer access without boutique infrastructure investments.
- Retail Stores:Multi-brand and department store formats controlling mid-market customer access across India's tier-one and tier-two city expansion.
- Boutiques:Exclusive single-brand environments sustaining premium customer relationships and personalized service in Shanghai, Tokyo, and Delhi's luxury corridors.
- Wholesalers:Bulk distribution intermediaries serving smaller retailers and export markets, with margin compression from direct-to-consumer platform competition.
Retail stores maintain the installed base. Online channels deliver the sharpest growth acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's SAMR anchors the regulatory framework that shapes metal content compliance across the Asia Pacific accessories trade. India's BIS hallmarking mandate and Japan's JIS quality standards create parallel certification requirements that fragment supply chain workflows.
China
Young professionals in Shanghai and Beijing compress replacement cycles for statement bags and jewelry, treating accessories as seasonal wardrobe components. SAMR's evolving GB standards for metal content and product safety now require batch-level testing documentation before market release. Guangdong and Zhejiang provinces anchor export-volume production for premium European houses.
India
Metropolitan demand concentrates in Mumbai, Bangalore, and Delhi's tier-one retail corridors where organized retailers expand penetration. BIS mandatory precious metal certification consolidates fragmented jewelry suppliers into traceable supply chains. South India's captive manufacturing clusters, including Titan's integrated operations, serve domestic consumption with hallmarking-compliant production.
Japan
Senior consumers sustain demand for traditional craft techniques and durable investment-grade pieces in a mature accessory market. METI's JIS quality frameworks shape material compliance costs alongside product safety expectations. Tokyo's luxury retail corridors maintain exclusive boutique environments for premium customer relationships.
Vietnam
Artisan craft labor pools rotate toward mechanized stitching and die-casting, easing capacity bottlenecks for mid-tier accessories. The country's tanneries concentrate pricing power through exclusive supply relationships for premium hides serving luxury houses. Ho Chi Minh City and Hanoi manufacturing zones absorb production migration from higher-cost regional competitors.
Bangladesh
Apparel-adjacent accessory manufacturing leverages existing textile infrastructure for belt and fabric-based product expansion. Younger workers migrate from traditional hand-assembly to mechanized factory roles, eroding artisan skill availability. Dhaka and Chittagong industrial zones attract mid-tier brand sourcing with competitive labor costs and improving compliance infrastructure.
Asia Pacific Fashion Accessories Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive structure. Luxury conglomerates with captive leather sourcing and jewelry manufacturing capabilities occupy the upper tier, while regional specialists and fast-fashion platforms fill volume segments below. Three archetypes dominate: vertically integrated precious goods manufacturers, exclusive material sourcers for premium positioning, and algorithmic fast-fashion distributors. Competitive moves concentrate on exclusive supply contracting and mechanized production scaling to compress unit economics.
Within the integrated manufacturing tier, Titan Company Limited exemplifies captive jewelry production with hallmarking-compliant South Indian operations. LVMH Moët Hennessy Louis Vuitton SE and Kering SA occupy positions anchored by exclusive leather sourcing relationships and artisan-led small-batch production capabilities respectively. These three entities represent divergent strategic paths: domestic regulatory compliance, upstream material control, and craft-preservation positioning.
| Leading Market Players |
|---|
| Titan Company Limited |
| LVMH Moët Hennessy Louis Vuitton SE |
| Kering SA |
| Hermès International |
| Nike Inc. |
| Adidas AG |
| Puma SE |
| Industria de Diseno Textil S.A. (Inditex S.A.) |
| Li-Ning Company Limited |
| Others |
Value Chain & Pricing Dynamics
Plant-based leather alternatives displacing conventional hides in mid-tier bags and belts are simultaneously shifting procurement geography toward Southeast Asian biopolymer labs and compressing price premiums previously sustained by exclusive tannery relationships. This substitution dynamic redraws cost curves across the value chain as buyers arbitrage between certified sustainable synthetics and legacy hide grades.
Pricing Analysis
Price spreads between Mumbai boutique channels and Vietnam factory-direct procurement exceed threefold for equivalent leather grades. Three-tier pricing structure across premium, standard, and economy levels separates BIS-hallmarked jewelry from uncertified artisan production and mass-market costume alternatives. Pricing pressure stems from mechanized production scaling in Bangladesh and Vietnam eroding hand-assembly premiums. Young professionals in tier-one Indian cities demonstrate highest price sensitivity, while Japan's senior demographic sustains investment-grade positioning with minimal elasticity.
Supply Chain Analysis
Inventory cycles for premium hardware components now stretch fourteen to eighteen weeks following China's SAMR batch-testing documentation requirements. Raw material flows draw from Vietnamese tanneries, South Indian gold alloy suppliers, and Guangdong synthetic polymer clusters. Single-source vulnerability concentrates in exclusive hide supply relationships serving LVMH and Kering houses. Distribution runs through Alibaba's Tmall and Reliance's JioMart platforms alongside traditional boutique infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern discovery and transaction mechanics as social commerce algorithms displace boutique relationships for young professional cohorts. Interoperability between Instagram commerce layers and WhatsApp Business APIs creates closed-loop purchase ecosystems previously fragmented across channels.
For Market Incumbents: Consolidate captive manufacturing in South India and Vietnam to defend margin position against fast-fashion platform entrants. Deepen backward integration into BIS-certified alloy supply and exclusive tannery contracting to sustain pricing power. Mechanized production scaling represents the priority capability investment. For New Entrants and Emerging Players: BIS hallmarking fast-track partnerships with organized South Indian manufacturers unlock tier-two Indian city whitespace. Target underpenetrated Bangalore and Hyderabad retail corridors with localized pricing below Titan's premium positioning. Direct-to-consumer social commerce launch bypasses fixed boutique infrastructure costs. For Investors and Strategic Acquirers: India's expanding BIS enforcement reshapes the acquisition landscape toward compliant organized manufacturers. Long-term viability favors vertically integrated operators with captive alloy sourcing and mechanized production capabilities. Watch SAMR disclosure timeline acceleration as inflection indicator for cross-border collection economics.| Strategic Initiative | Industry Significance |
|---|---|
| Mechanized Production Scale-Up | Bangladesh and Vietnam factory automation compresses unit costs for mid-tier bag manufacturers. |
| BIS Hallmarking Certification Investment | Organized jewelry suppliers in Mumbai and Delhi consolidate fragmented market share through compliance. |
| Exclusive Tannery Supply Contracting | Vietnamese hide processors concentrate pricing power for LVMH and Kering leather goods divisions. |
| Social Commerce Platform Integration | Instagram and WhatsApp Business APIs enable direct-to-consumer discovery without boutique infrastructure. |
| Low-Carbon Processing Verification | China's dual carbon goals create preferential procurement terms for verified sustainable tanneries. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with jewelry brand managers, leather goods procurement leads at European houses, BIS certification consultants, and e-commerce category heads at Reliance and Tata platforms. Secondary validation drew from SAMR batch-testing disclosure records, BIS hallmarking registry data, Vietnam customs export statistics, and Alibaba Group transaction disclosures. Bottom-up production capacity modeling and top-down consumer expenditure estimates were triangulated to anchor volume and value outputs.
Across the analysis window, the forecasting framework modeled jewelry and bag segments separately with material grade, distribution channel, and city-tier stratification. CAGRs were derived from trend extrapolation of mechanized production penetration rates and online channel share shifts. Industry-specific inputs included BIS compliance cost amortization curves and SAMR documentation timeline assumptions.
Decision-makers should treat outputs as directional under sustained regulatory enforcement and platform economics adoption; material deviation in hallmarking mandate implementation or social commerce growth would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fashion & Accessories
Cufflink Market
Fashion & Accessories
Couture Millinery Market
Fashion & Accessories
Hair Accessories Market
Fashion & Accessories
North America Fashion Accessories Market
Fashion & Accessories
Global Handbags Market
Fashion & Accessories
North America Handbag Market
Fashion & Accessories
Fashion Accessories Market
Fashion & Accessories
Custom Dog Tags Market
Fashion & Accessories
Middle East and Africa Leather Goods Market
Fashion & Accessories
Europe Fashion Accessories Market
Fashion & Accessories
Decorative Accessories Market
Fashion & Accessories
Selfie Accessories Market
Fashion & Accessories
Personal Accessories Market
Fashion & Accessories
Sustainable Fashion Market
Fashion & Accessories
Hair Scrunchies Market
Fashion & Accessories
South America Handbags Market