
 Personal Accessories Market | 2026-2036
Personal Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Personal Accessories Market Analysis
The gap between artisan-crafted premium goods and mass-produced commodity accessories is repositioning how brands allocate capital and talent. LVMH Moet Hennessy Louis Vuitton leverages vertical integration across leather goods and watchmaking to sustain margin control from tannery to boutique. Apple Inc. competes on technology leadership in wearable sub-categories, embedding health sensors and connectivity into wrist-worn formats that challenge traditional horology.
Personal accessories encompass wearable items including watches, handbags, jewelry, and sunglasses, typically manufactured from leather, metal, fabric, or synthetic substrates through processes ranging from hand-stitching to precision CNC machining and electroplating. These products serve commercial purposes spanning personal adornment, status signaling, functional utility, and digital connectivity integration. Watches and jewelry command the deepest margin pools due to material scarcity and heritage branding, while sunglasses represent the most penetrated category with manufacturing scale concentrated among Italian and Chinese optical clusters. Handbags sustain the fastest growth trajectory as gender-neutral and mini-format designs expand addressable demand across demographic segments.
The European Chemicals Agency enforces REACH substance restrictions on nickel release and chromium tanning agents, directly affecting metal jewelry and leather goods compliance costs for exporters targeting EU consumers. The Federal Trade Commission in the United States monitors greenwashing claims and precious metal purity disclosures, shaping how brands communicate sourcing and authenticity. China's State Administration for Market Regulation oversees domestic quality certification and anti-counterfeiting enforcement, creating divergent market access requirements across major consumption zones. Stakeholders must monitor how diverging chemical safety and digital product passport mandates reshape supplier qualification and inventory localization strategies.
Market Dynamics
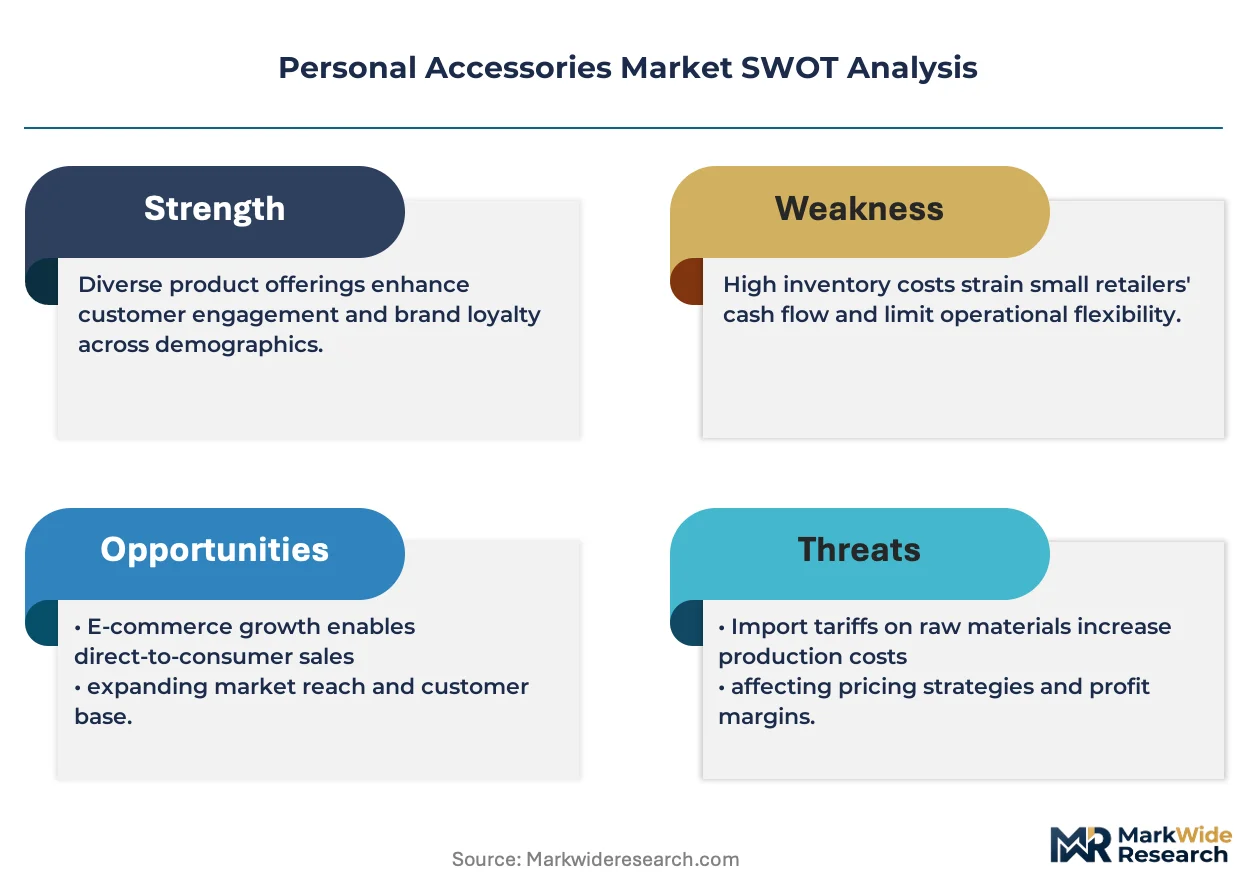
REACH substance restrictions from the European Chemicals Agency are forcing tanneries and electroplating facilities to reformulate chromium-based processes and nickel release protocols, compressing supplier margins and accelerating inventory localization decisions for brands serving EU consumers.
Growth Catalysts
- Dual carbon goals in China:Domestic luxury consumption receives policy tailwinds through carbon-neutral manufacturing incentives, strengthening local designer brand loyalty among millennial buyers.
- Health sensor miniaturization:Wearable sub-categories embed biometric tracking into wrist-worn formats, pulling demand from traditional horology toward tech-integrated accessories.
- REACH compliance:Stricter chemical safety protocols in Europe create competitive moats for early-adopter brands with certified supply chains, locking out smaller exporters.
Market Restraints
- Italian leather cluster concentration:Premium handbag manufacturing relies on tanneries concentrated in Tuscany and Veneto, exposing brands to regional supply disruption and input cost volatility.
- Battery disposal rules:Evolving regulations for smart accessories create compliance friction across EU member states, requiring separate logistics networks for wearable electronics.
- Lab-grown gemstone substitution:Synthetic diamond and cultured pearl alternatives threaten natural material scarcity premiums in entry-luxury jewelry segments.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for textiles and leather goods attract contract manufacturing investment from European luxury houses seeking supply diversification.
- Digital product passports:EU mandates for traceability documentation create first-mover advantage for brands with blockchain-integrated supply chains.
- Biometric payment authentication:Convergence of wearable devices with contactless payment rails opens white space in wrist-worn fintech accessories.
Industry Challenges
- Artisan skill scarcity:Hand-stitching and fine metalworking competencies concentrate among aging craftspeople in France and Italy, constraining capacity expansion for heritage-positioned brands.
- Multi-jurisdiction certification timelines:Simultaneous compliance with REACH, FTC greenwashing monitors, and SAMR quality certification extends product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personal Accessories Market |
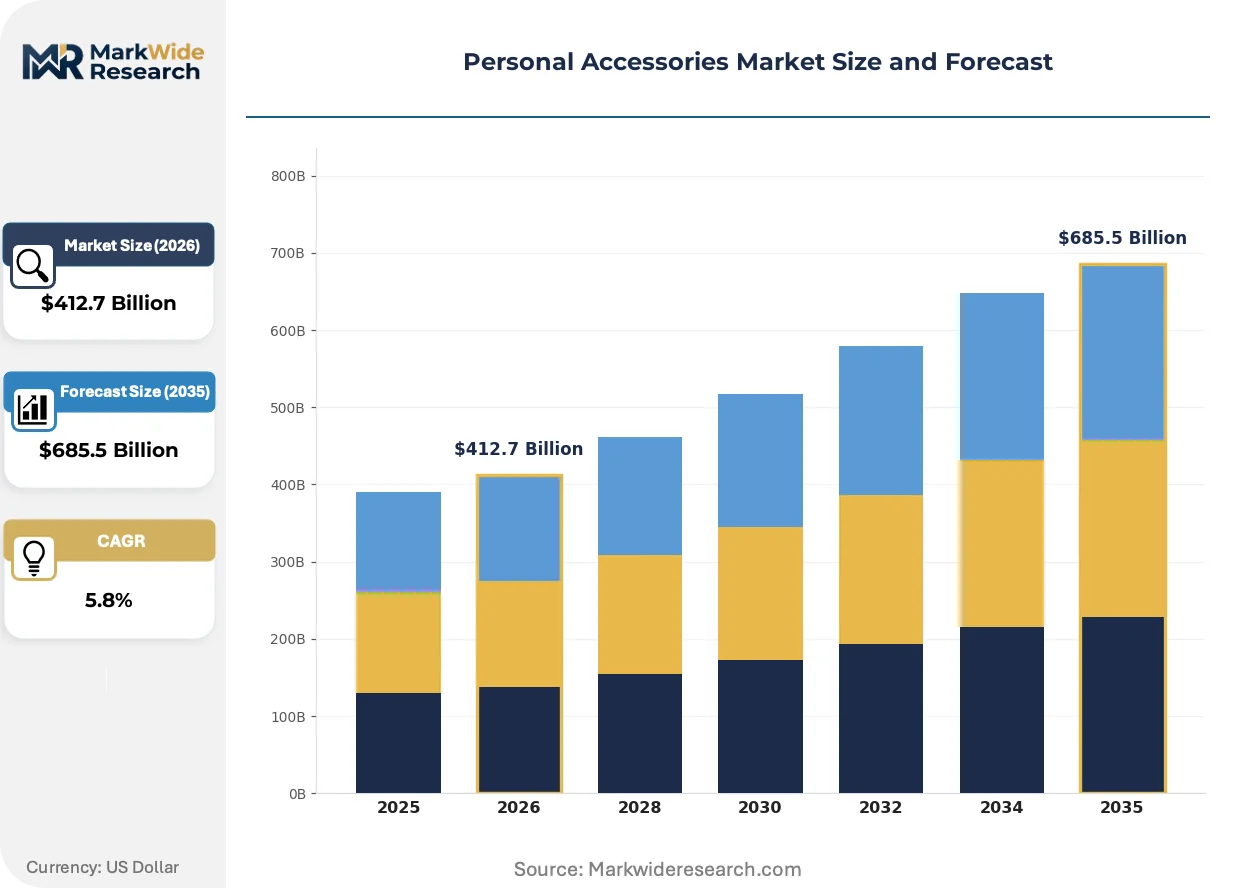
| Market Size in 2026 | $412.7 Billion |
| Market Size in 2035 | $685.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Watches, Handbags, Jewelry, Sunglasses Material: Leather, Metal, Fabric, Plastic End User: Men, Women, Children, Unisex Sales Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Kering Group, Chanel S.A., LVMH Moet Hennessy Louis Vuitton, Tapestry, Inc., Rolex SA, Compagnie Financiere Richemont SA, The Swatch Group Ltd, Pandora A/S, Apple Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personal Accessories Market Emerging Trajectories
Material science breakthroughs and regulatory digitization are compressing traditional craftsmanship timelines while opening new functional categories at the intersection of adornment and connectivity.
Ceramic matrix composites are expanding into watch case production, offering scratch resistance and thermal stability that challenge precious metal positioning. Swiss and Japanese manufacturers adopt these substrates fastest, enabling thinner profiles that accommodate larger sensor arrays without bulk increases. The technology is expanding into entry-luxury tiers previously dominated by stainless steel.
EU Green Deal supply chain disclosure mandates require documented carbon intensity from raw material extraction through retail distribution. Leather goods and jewelry brands must now map tannery energy sources and mining provenance, with non-compliant inventory facing market access restrictions. Italian luxury clusters invest in photovoltaic-powered facilities to maintain EU qualification.
Direct-to-consumer resale platforms fragment traditional wholesale relationships for pre-owned accessories. Authentication technology providers capture margin pools previously held by auction houses, while original manufacturers launch certified secondhand programs to retain customer lifetime value. This channel rotation is most visible in China, where domestic platforms dominate circular luxury transactions ahead of Western market development.
Personal Accessories Market Segmentation
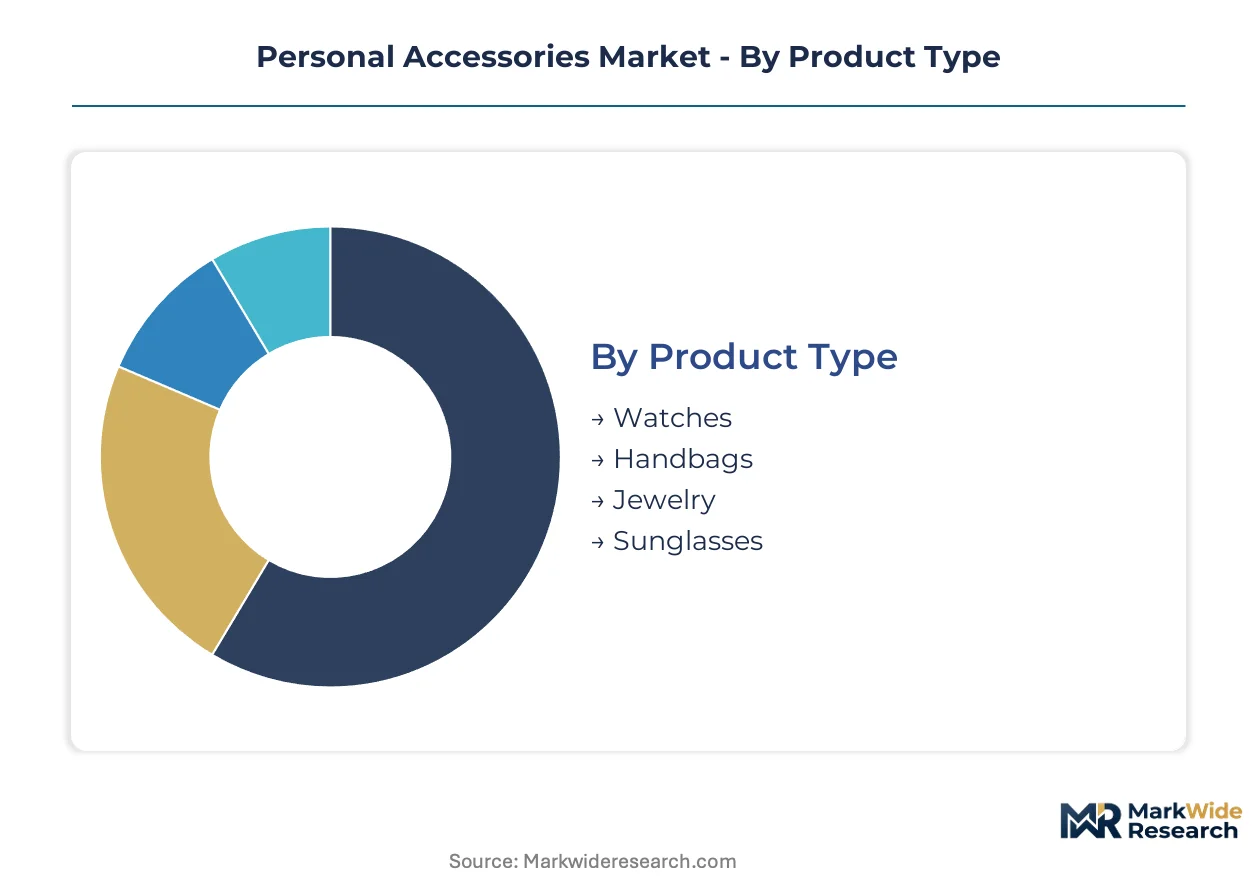
Personal accessories segmentation reveals divergent capital requirements across manufacturing modalities. Hand-stitching leather goods demands artisan labor pools, while precision machining for smartwatches requires cleanroom facilities and sensor integration capabilities.
Product Type:
Capital intensity varies sharply: mechanical watchmaking requires Swiss-grade CNC machining centers, while sunglasses molding scales with commodity injection equipment.
- Watches:Swiss and Japanese manufacturers dominate mechanical movements, with ceramic matrix composites displacing stainless steel in entry-luxury tiers. Demand concentrates in China as domestic luxury consumption strengthens under dual carbon policy incentives.
- Handbags:Tuscan and Veneto tanneries supply premium leather, with mini-format and gender-neutral designs expanding addressable demand. REACH chromium restrictions are compressing supplier margins and accelerating inventory localization for EU-bound brands.
- Jewelry:Lab-grown gemstones threaten natural scarcity premiums in entry-luxury segments.
- Sunglasses:Italian and Chinese optical clusters concentrate manufacturing scale.
Most installed capacity flows through Sunglasses. Expansion is steepest in Handbags.
Material:
Raw material sourcing geography determines compliance exposure and margin stability across supplier networks.
- Leather:Chromium tanning processes face ECHA reformulation mandates under REACH, forcing tanneries toward vegetable-based alternatives. Italian clusters invest in photovoltaic-powered facilities to maintain EU Green Deal qualification.
- Metal:Nickel release restrictions affect jewelry electroplating protocols, with certified supply chains creating competitive moats for early-adopter brands.
- Fabric:India's PLI scheme for textiles attracts contract manufacturing investment from European luxury houses.
- Plastic:Biodegradable polymer alternatives emerge under carbon-neutral manufacturing incentives.
Leather commands the deepest heritage premiums. Fabric is climbing the fastest on supply diversification trends.
End User:
Gender-targeted design traditions are fragmenting as unisex positioning captures cross-demographic demand.
- Women:Traditional core for handbags and fine jewelry, with mini-format accessories expanding occasion-based purchase frequency.
- Men:Fastest-growing segment for wrist-worn accessories as health sensor miniaturization pulls demand from traditional horology.
- Children:Safety-certified materials and durable construction specifications dominate procurement criteria.
- Unisex:Gender-neutral designs now anchor brand identity for emerging designer labels in China.
Women retain the largest revenue base. Unisex is gaining share fastest on Gen Z purchasing patterns.
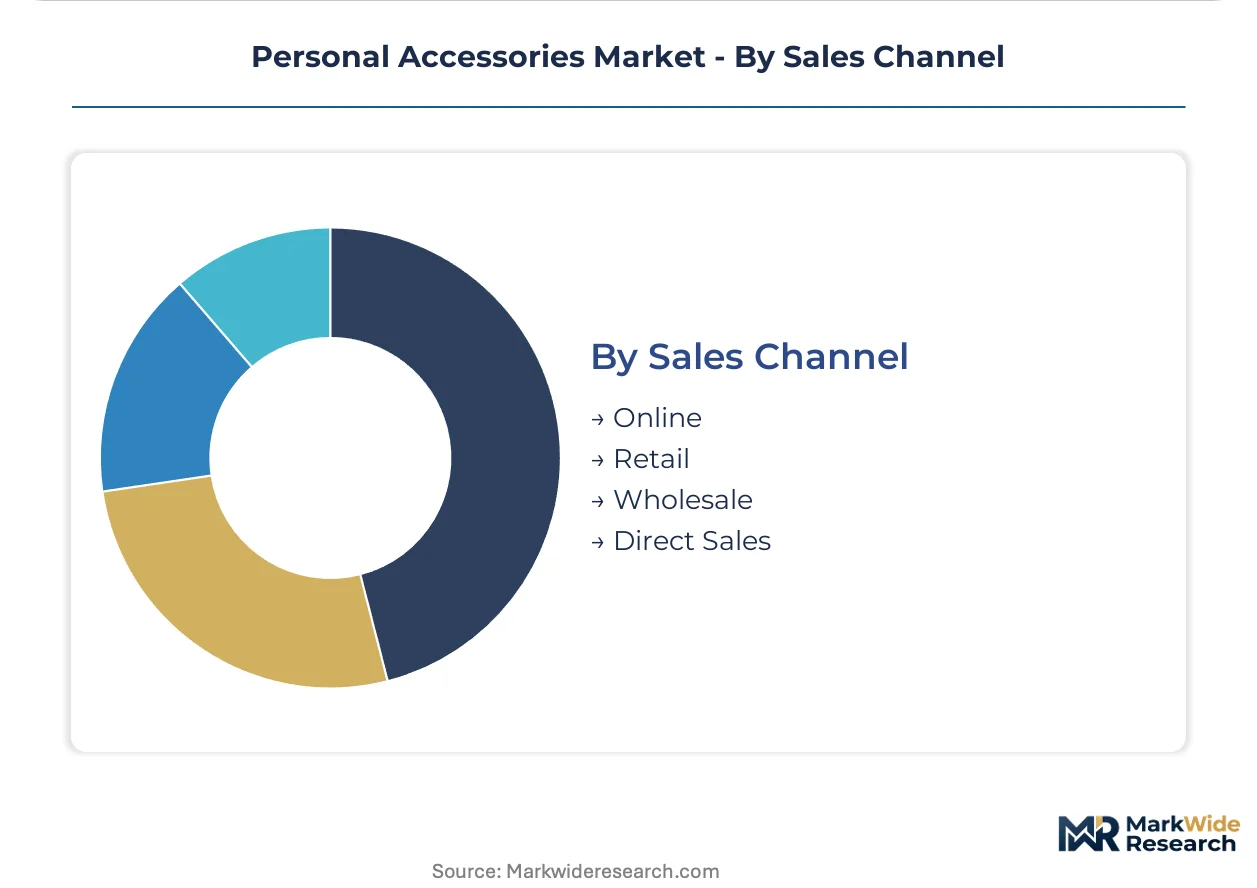
Sales Channel:
Channel economics diverge on authentication technology requirements and customer lifetime value capture mechanisms.
- Online:Direct-to-consumer resale platforms fragment wholesale relationships, with authentication providers capturing margins previously held by auction houses.
- Retail:Boutiques sustain margin control for vertically integrated luxury houses from tannery to point-of-sale.
- Wholesale:Department store relationships face compression as brands prioritize direct channels.
- Direct Sales:Certified secondhand programs launched by original manufacturers retain customer lifetime value in circular transactions.
Retail maintains the highest average transaction values. Online is expanding most quickly on platform authentication technology maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Artisan leatherworkers in Tuscany and Veneto anchor European supply chains for premium handbags, while precision metalworkers in Solingen and Pforzheim sustain German jewelry manufacturing traditions.
China
Domestic luxury consumption among millennial and Gen Z buyers drives demand for wrist-worn accessories and designer handbags. SAMR quality certification and anti-counterfeiting enforcement tighten market access requirements for imported brands. Shanghai and Beijing host flagship boutiques where local designer labels capture loyalty through carbon-neutral manufacturing incentives under dual carbon goals.
United States
Health sensor miniaturization pulls demand toward tech-integrated wrist-worn formats challenging traditional watchmakers. FTC monitoring of greenwashing claims and precious metal purity disclosures shapes brand communication strategies. New York and Los Angeles concentrate direct-to-consumer resale platform activity, with authentication technology providers fragmenting wholesale relationships.
France
Heritage-positioned leather goods and fine jewelry sustain deep margin pools through material scarcity and brand equity. REACH substance restrictions from ECHA enforce nickel release protocols affecting electroplating facilities. Paris anchors vertically integrated luxury houses controlling operations from tannery to boutique, while Lyon supports precision metalworking for high-end timepieces.
Italy
Concentrated tannery operations in Tuscany supply premium leather for handbags facing REACH chromium reformulation mandates. Photovoltaic-powered facilities in Veneto maintain EU Green Deal qualification for export-bound production. Milan and Florence host design studios where artisan skill scarcity among aging craftspeople constrains capacity expansion for heritage brands.
India
Production-linked incentives for textiles and leather goods attract contract manufacturing investment from European luxury houses seeking supply diversification. BIS standards and DGFT export protocols shape operational compliance for accessories manufacturers. Kanpur and Kolkata clusters expand tanning and finishing capacity as brands accelerate inventory localization decisions.
Personal Accessories Market Vendor Landscape
Top-tier vendors anchor heritage luxury positioning, while technology-integrated specialists and accessible jewelry players occupy distinct competitive tiers. The vendor base stratifies across three strategic archetypes: vertically integrated European fashion houses controlling supply chains from raw material to retail, Asian electronics manufacturers embedding connectivity into wrist-worn formats, and mid-market accessible brands scaling through efficient production networks. Dominant competitive moves include backward integration into tannery operations and strategic partnerships with authentication technology providers.
Within the heritage luxury tier, LVMH Moët Hennessy Louis Vuitton and Kering Group exemplify vertically integrated European fashion houses. Among Swiss-based horology specialists, Rolex SA and Compagnie Financière Richemont SA occupy positions defined by mechanical movement expertise and heritage brand equity. Tapestry, Inc. represents the accessible-luxury archetype scaling through efficient production networks and multi-brand portfolio management.
| Leading Market Players |
|---|
| Kering Group |
| Chanel S.A. |
| LVMH Moet Hennessy Louis Vuitton |
| Tapestry, Inc. |
| Rolex SA |
| Compagnie Financiere Richemont SA |
| The Swatch Group Ltd |
| Pandora A/S |
| Apple Inc. |
| Others |
Supply Flow & Price Mechanics
Artisan leatherworkers concentrated in Tuscany and Veneto anchor labor-cost differentials that widen pricing-tier spreads between heritage-positioned handbags and mass-market alternatives. REACH compliance investments in chromium-free tanning and nickel-release certification compress margins at entry-luxury tiers while reinforcing premium positioning for vertically integrated houses.
Pricing Analysis
Bundled after-sales authentication and certified resale programs now separate heritage brand pricing from unbundled commodity accessories lacking provenance documentation. Three-tier pricing structure across artisan-crafted, precision-manufactured, and mass-produced levels reflects certification grade and vertical integration depth. Cost compression in entry-luxury jewelry intensifies because lab-grown gemstone substitution erodes natural scarcity premiums. Price-sensitive Gen Z buyers concentrate in online resale channels, while least-sensitive collectors sustain auction premiums for vintage mechanical timepieces.
Supply Chain Analysis
Reverse-logistics flows for wearable electronics refurbishment and battery recovery now parallel traditional leather goods repair networks, complicating inventory localization decisions. Manufacturing gravity draws from Italian tannery clusters, Chinese optical molding facilities, and Swiss CNC machining centers. Raw material dependencies rest on chromium-tanned hides, ceramic matrix composite substrates, and rare-earth sensor components. Single-source vulnerability concentrates in Tuscan vegetable-tanning capacity constrained by REACH reformulation timelines. Distribution runs through flagship boutiques for heritage houses and direct-to-consumer platforms for tech-integrated specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in carbon-neutral manufacturing premiums and sensor-integrated wrist-worn formats that command pricing power over traditional horology. REACH certification investments and dual carbon compliance in China create defendable cost-down positions for early adopters.
For Market Incumbents: Hedge against artisan skill scarcity in France and Italy by captive training programs and precision automation partnerships that preserve hand-finishing cues. Lock in photovoltaic-powered tannery capacity ahead of EU Green Deal disclosure mandates. Battery disposal rule fragmentation across EU member states threatens smart accessory margins; localize refurbishment logistics now. For New Entrants and Emerging Players: Biometric payment authentication embedded in wrist-worn formats offers technology-first wedge into fintech-accessory convergence. Target India's PLI-backed leather and textile clusters for contract manufacturing relationships with European houses seeking supply diversification. Direct-to-consumer authentication technology partnerships bypass wholesale margin capture by legacy auction channels. For Investors and Strategic Acquirers: European luxury houses with tannery-to-boutique control are the most active acquirer in this space, consolidating heritage positioning through backward integration. Five-to-ten year viability favors brands with blockchain-traceable supply chains aligned to digital product passport mandates. Monitor ECHA substance restriction expansion timelines as inflection indicator for compliance-cost winners versus locked-out exporters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tannery Operations | LVMH and Kering secure margin control from raw hide through finished goods against REACH volatility. |
| Digital Product Passport Implementation | Blockchain-integrated traceability satisfies EU Green Deal mandates ahead of non-compliant competitors. |
| Health Sensor Miniaturization R&D | Apple pulls wrist-worn demand from Swiss mechanical watchmakers through biometric integration. |
| Certified Secondhand Program Launch | Original manufacturers recapture customer lifetime value from fragmented resale platform margins. |
| India PLI Scheme Manufacturing Footprint | European houses diversify beyond Italian leather cluster concentration through Kolkata and Kanpur capacity. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with luxury brand supply chain directors, tannery operations managers, wearable device platform engineers, and resale platform authentication specialists. Secondary validation drew from ECHA substance restriction databases, EU Green Deal implementation guidelines, SAMR quality certification protocols, SEC filings from publicly traded fashion houses, and customs trade data for leather goods and optical product categories. Bottom-up SKU-level demand modeling and top-down macroeconomic anchoring triangulated volume and value estimates.
Comparable-period anchoring tied projection assumptions to historical reference intervals spanning pre-pandemic baseline, demand disruption, and recovery normalization phases. Segmentation dimensions modeled across the projection horizon included product type, material substrate, end-user demographic, and sales channel format. CAGRs derived from fitted growth curves applied to country-level consumption patterns, with specific inputs for REACH compliance cost pass-through rates and dual carbon policy incentive effects in China.
The model holds under stable regulatory enforcement timelines; deviation in ECHA substance restriction acceleration or battery disposal rule harmonization failure would shift competitive positioning and margin forecasts. Practitioners should monitor digital product passport mandate rollout schedules and artisan labor pool demographics in Italian clusters for early signals of supply constraint or qualification advantage.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fashion & Accessories
Middle East and Africa Leather Goods Market
Fashion & Accessories
Custom Dog Tags Market
Fashion & Accessories
Fashion Accessories Market
Fashion & Accessories
Global Handbags Market
Fashion & Accessories
Selfie Accessories Market
Fashion & Accessories
Hair Accessories Market
Fashion & Accessories
Hair Scrunchies Market
Fashion & Accessories
North America Lingerie Market
Fashion & Accessories
Europe Fashion Accessories Market
Fashion & Accessories
Asia Pacific Fashion Accessories Market
Fashion & Accessories
North America Fashion Accessories Market
Fashion & Accessories
Couture Millinery Market
Fashion & Accessories
North America Handbag Market
Fashion & Accessories
South America Handbags Market
Fashion & Accessories
Cufflink Market
Fashion & Accessories
Sustainable Fashion Market